Tag Archives: contactless payments

time is money 8964120

What You Should Know About Real-Time Payments

The democratization of something is often used too loosely and in many industries and business practices. The democratization of shopping, renting, buying, traveling, and particularly finance. The over usage of this term does not apply to payments transfer over the past decade. With the advent of smartphones, better internet, and peer-to-peer payments are virtually real-time within the U.S. and many developed countries worldwide.

The Past, Present, and Future

Western Union first started to issue employee salaries via non-cash payment with a metal plate card in 1914. Throughout the ’50s and ’60s, payments networks such as American Express, Mastercard, and Visa emerged as payment networks that began facilitating trade. This paved the way for the magnetic-stripe POS system in the ’70s and ’80s, which went wireless in the ’90s.

Today, non-cash transactions make up more than 80% of in-store sales. Non-cash is the preferred method of payment for a growing number of transactions. Payment networks continuously look for ways to capture a larger piece of the payment’s universe, particularly the tail-end of the payment ecosystem, such as small ticket items such as candy bars and large ticket items like cars.

Advances in payments processing have made the world both smaller and safer and have allowed trade to grow in the form of e-commerce and mobile payments and digital wallets.

However, there still are key barriers to overcome. Payment settlements are not quick. In many cases, nor is it cheap. Even with automated clearing house (ACH) transactions, which has reduced the cost of payments and processing time down to a matter of one day, instead of the average three days, merchants would still prefer to have the funds for the goods sold right now, as is the case with cash.

Enter Real-Time Payments (RTP)?

That is what Real-Time Payments (RTP) accomplishes. Although RTP is not a new technology, it has been adopted only recently in the U.S. In the ’70s, Japan introduced the first RTP, and today it is estimated that over 50 countries have an active RTP system implemented.

RTP allows payments and data to flow extremely fast, settling payments instantaneously. The Clearing House (THC) unveiled the U.S. iteration of the RTP in 2017 and now processes payroll, B2B, P2P, and RFP transactions, among others, in real-time.

How does RTP work?
Real Time Payments

The closest to RTP so far has been Next Day Payment and ACH Same Day Payment. They are usually traditional payments processed very fast. They have a specific cutoff time for transactions to be assigned to particular dates and then processed.

ACH Same-day funding and Next day funding utilize batch submission that happens faster via the ACH network and, depending on the cutoff times of the day, has the payments transferred to sellers in a matter of hours or overnight. 

Real-time payments are different. RTP is the collection of financial information and verification of user identity between the seller and the buyer that is settled, and funds transferred at that very moment, effectively in real-time, like cash. The following steps are involved in this exchange:

  1. The seller submits a Request for Payment (RFP).
  2. The buyer submits payment details.
  3. The payment is settled once the seller receives payment details and confirms authenticity.
  4. The buyer confirms the finality of the transaction.

These steps happen in a matter of seconds, if not microseconds.

Even with the fastest existing payment rails, merchants must wait overnight to access their funds if the processing is done by a specific cutoff time. The system is available 24 hours a day, 365 days a year, even on weekends and holidays with RTP.

Benefit

There are numerous benefits for all types of users using RTP. First, Merchants can get their funds immediately. If there are issues in processing a certain payment, the merchant will know of it in real-time.

Another benefit is that the RFP is available 24/7/365, including holidays. So anyone can transact at any time, and the payment is cleared, and funds settled immediately.

This system can translate into actual dollars for firms. Any business processing payroll will not need appropriate funds and processing fund transfers out of their bank accounts a day or two before the paycheck date. Businesses can process payroll and have the funds withdrawn at that date.

Risks

As with any innovation, there still are cracks in the system. The biggest hurdle will be adoption. As the system gains traction, many financial institutions will be late adopters, which will not be able to accept RTP payments. Until there is mass adoption as banks and financial intermediaries ramp up their technology infrastructure and security, it will not be easy to gauge the impact of a new payment system.

Furthermore, although there will be a heightened level of security surrounding the new payment rails, any fraudulent transactions that slip through the system will also be processed just as quickly as any other real-time transaction. This will create more hurdles in monitoring and tracing transactions involved in theft or other criminal activity.

Federal Reserve’s FedNow 

The U.S. Federal Reserve Board is also expected to enter the fray. The central bank announced in late-2019 that it was developing an RTP rail called FedNow and will launch in 2023. As of early-2021, over 200 financial institutions were participating in the FedNow pilot program, supporting the rail’s development, testing, and implementation. These financial institutions also included several payment processors that are part of developing the technological integration requirements to sync with FedNow to adopt the RTP.

The payments industry has experienced many changes, with a history ripe with ingenious innovation. More and more firms enter the market to take advantage of the latest technology to facilitate trade and transactions at breakneck speeds. Now, thanks to real-time payments, merchants and consumers alike can benefit from a payment system that is both cheaper and settled instantaneously.
word writing text myths and facts business concept for usually traditional story of ostensibly historical events 162013834

Myths About the Safety of Contactless Payments

Even though card payment is still a popular method of payment, more and more people are now switching to contactless payments especially after the COVID outbreak. It’s obvious that people want to prioritize their safety by limiting physical contacts, and one way to reduce the physical contacts at the retail stores is by paying through e-wallets. 

With more than 90% of the transactions being processed through contactless payment methods, Australia has become a leader in accepting this mobile payment trend. Not only in the US and Australia, but mobile payments are gaining attention worldwide, and for good reasons. 

Despite their popularity, contactless payments are associated with a few myths that make people wonder if they should embrace this new technology or stick to cash and card payments. We have listed a few myths surrounding contactless payments that every user should know before they start using mobile apps for transactions. Here’s a look:

  1. Electronic Pickpocketing is Possible

Let’s start with the most common myth. Some people believe that it’s possible to pickpocket your contactless payment data. All it takes for a person to steal your private information is the NFC card. If they are standing close to you with an NFC card, they can record your card’s details. The NFC card can read your account number and the expiry date, but that’s it! Even that is possible if the person manages to steal the POS terminal, which is practically not possible for any non-tech savvy person. 

Overall, there is a higher chance of your physical credit/debit cards getting stolen in a public place than your contactless card information getting leaked. So, you can rest easy knowing that it is just a myth and there’s no way anyone can pickpocket your contactless cards electronically.

  1. You Might End up Paying for Someone Else

First things first, the POS system can catch your card’s data only when the card is placed 1-2 inches from the terminal. So, if you are worried that the point of sale terminal will use your card’s information for somebody else’s purchases, know that it’s highly unlikely. Besides, you should maintain distance from the person and the terminal until it is your turn to pay.

  1. It is not a Convenient Option for Merchants

Embracing a new technology may seem daunting at first, but once you get used to contactless payments, there is no payment method that seems more comfortable and safer than these payments. Contactless payments are convenient for both customers and merchants. It’s a lot easier for customers to make the payment in one click. Imagine not having to carry cash every time you go shopping. All you need is a mobile app to transfer money to the merchant’s account. 

For merchants, there is no need to count cash and store the money in the drawer. At the end of the day, you have to count the total cash and match it with your records. Besides, you need to transport this money to your bank every day. Not only is the process pretty inconvenient, but it is risky. What if an intruder gets access to the cash? Stealing money is not uncommon at brick-and-mortar stores. So, to avoid such issues, you should use contactless payments. The money goes directly to your bank account.

  1. The Thief can Duplicate the Contactless Cards

If a thief gets access to your contactless card information, there is a risk they can duplicate your card. It is another common myth that stops people from accepting and making payments through mobile apps. When you initiate the transaction, the card sends a unique code to the card reader to process the transaction. 

It is only a one-time number that can neither be stolen nor be copied. Even if the thief gets access to your contactless card details, they cannot duplicate the card due to the one-time code technology. There is absolutely nothing to worry about your card getting duplicated. Even a professional hacker or a tech-savvy person cannot duplicate a contactless card.

  1. Stolen Contactless Cards can Cause Losses

We have already mentioned that it’s not possible to steal contactless card information. Let’s say someone gets access to this data somehow. Now, the common myth is that the thief can make multiple transactions using the stolen card information and the money will be deducted from the cardholder’s account. For some reason, people also believe that the thief will be able to use the stolen contactless card to make payments without having to enter the security PIN.

Even if your contactless card gets stolen and you suspect any fraudulent activities on your cards, you have to report them to the bank just like how you would report the fraudulent transactions with your physical card. Besides, you don’t have to worry about incurring major losses, as contactless payments have the same policies as any physical card. You will get total reimbursement for all the transactions made by the thief. Another important thing to note here is that a PIN is mandatory for all types of contactless card transactions. Even if you are buying groceries, you need to enter a PIN to process the transaction. 

  1. The Contactless Cards can Get Stolen if Someone Gets Access to My Device

Another major concern of contactless card users is “can someone get access to my card details if they steal the device connected to these cards”. Let’s face the reality – if a thief were to get access to your device, it wouldn’t be hard for them to find your contactless card information. However, contactless commerce is a lot safer than you can imagine. The card number is not visible. The hidden number has to be deciphered by the issuer to process any transaction. 

Conclusion

Not only are the e-wallets convenient and fast, but they allow people to make the payment in one click without having to swipe the card. These contactless payments make an ideal choice for customers and merchants looking for easy and safe ways to make payments.

veterinary customer paying with the smartphone 144486397

6 Contactless Payment Methods For Your Vet Clinic Checkout [2023 Update]

People are using contactless payment methods more than ever. While the move towards contactless payments had started before the global pandemic, the issue has hastened this shift. People are more willing to complete these payments because they know they are safer to follow. But there’s also the benefit of how easy it is to complete payments through such means.

Veterinary clinics can benefit from many of these contactless payment methods. You can use six different methods to help your vet clinic bring in revenue from your customers. These are convenient solutions to use at your clinic’s checkout station, plus they can support various features.

These payment solutions are vital when you consider the worries your clients might hold. Pet owners often have various concerns surrounding their pets’ health. Asking for payment may be insensitive or harsh at times. A contactless payment solution will be ideal for ensuring the client stays comfortable and that there will still be a way for that person to pay for a pet’s needs.

Customer-Facing Devices

The first contactless payment method to explore entails using a customer-facing device. You can place a terminal on the client’s side of the counter. The terminal will link with a virtual terminal that you control.

Using a customer-facing device will be easier to follow than if someone had to give you a card. The customer will also feel comfortable, as that person will always control one’s card. The card will stay intact, plus the person doesn’t have to give out more details than what one might be comfortable with sending at a time.

You will need to initiate the transfer through a virtual terminal browser. The client will then follow the prompts on the customer-facing device to complete the payment.

Everything will stay in a secure cloud system. The cloud computing system will ensure you can access the data you collect from anywhere. But you’ll need to ensure your setup is fully secure and encrypted while meeting all PCI standards for operation.

NFC

nfc

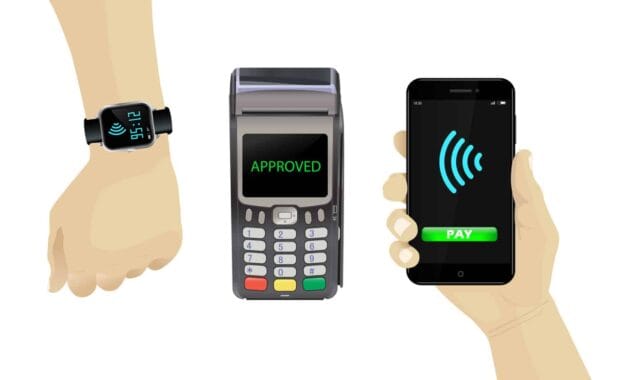
Near-field communication or NFC payments are very popular today. An NFC payment allows a customer to wave a card or another device over a terminal. The device can include a phone, band, or another item that features the customer’s payment data.

The NFC transaction process is contactless and provides a faster way to complete the payment. It also uses heavy-duty encryption that ensures the card’s data will not be lost when transferred.

Some NFC-based solutions like Google Pay and Apple Pay come with two-part verification features. A customer could add a fingerprint or a small code to a transaction to confirm one’s identity. Considering how much money someone might spend at a vet clinic on a pet’s needs, using a payment method that is safe and secure will be essential to review. An NFC transaction allows the customer to complete the payment without risking anything being lost in the general process.

EMV

The EMV chip-based card platform has been used by vet clinics for a while now. But it is becoming increasingly contactless, as card brands that support the EMV platform no longer require signatures for transactions on EMV-based devices.

Your vet clinic doesn’t have to retain payment receipts anymore if you use EMV payments. The process does not require much physical contact. You won’t have to pass a pen or pad to anyone anymore. It is easier to manage the payment, plus your business becomes greener by saving on paper.

You can use your virtual terminal to load up your receipts without having to print anything of value. You can text or email digital receipts to your customers as they request them.

Website Collection

Another choice is to collect customers’ data through your website. People might be more comfortable paying for services online instead of in person.

A customer can review the outstanding balance someone has for services at your clinic. You can provide a login account or other data for the customer to access. The customer can then pay for the services as necessary.

The website can also include complete invoices for people to review. You can upload all billing data online to help people see what they are paying for, reducing the risk of billing errors. The process is ideal for some of the more expensive things you might provide to people.

Phone Collection

Another solution to see involves secure phone payments. You can establish a phone payment system through a cloud-based virtual terminal. The terminal will be accessible by phone app and can connect the payment info people provide to your records.

The customer will provide one’s payment data through a phone app or a mobile version of your website. The customer can also provide a fingerprint or other secondary verification signal for one’s security.

The virtual terminal can collect the customer’s data to ensure you know who makes legitimate payments for a pet’s needs. You can contact the customer if you notice any discrepancies surrounding the transaction you’re planning.

Upfront Collection

The last of the contact-free payment options for your vet clinic involves collecting a client’s card and other data before providing services for their pets. You can ensure the customer’s data is on hand by collecting it once. The customer can submit new payment data as necessary or if the person wants to use a different payment method for the transaction.

By collecting the data, you can charge people based on the services they utilize. You can then send digital copies of their receipts. The effort reduces the stress associated with paying for things. The point is especially critical for more emotional needs, including surgeries and end-of-life practices surrounding one’s pets.

These six solutions for your vet clinic are worthwhile solutions worth trying. Be sure when planning your efforts that you know what you’re getting out of a system. You will have an easier time managing your clinic when you see what works for your general needs.

self ordering kiosks at mcdonalds 157443259

How Self-Service Retail Has Advanced and Helped Consumers Amid the Pandemic

Self-service kiosks and other devices have become a commonplace at many retail sites over the years. From kiosks at fast food restaurants that accept orders to self-checkout aisles at grocery stores, self-service retail has never been more visible than now.

The self-service or unattended retail industry has especially become more essential during the global pandemic. Self-serve kiosks and other unattended items help reduce human interactions and have been preferred by many during the pandemic. But the industry is still evolving, and there’s a potential for new developments further down the road. Some of these changes include efforts in making kiosks safer and making people feel comfortable with them.

Significant Growth

The self-service retail market has been growing in value in the past few years. PYMNTS.com reports that the self-serve market will likely grow to about $46 billion in value by 2027. The growth includes a compound annual growth rate of about 7 percent from 2020 to 2027.

Meanwhile, people are continuing to use more contactless payment solutions. PYMNTS.com also states in the same report that the contactless payment market is currently valued at $40 billion and will likely grow to $100 billion by 2026. Self-service kiosks and other stations can support contactless payment methods, making the industry likely to keep on growing in prominence.

What Makes Self-Serve Retail Useful?

People are finding self-serve retail stations to be safe during the pandemic, but there are many other positives worth noting. These include benefits that support the retailers:

  • Self-service stations help businesses save on labor costs.
  • It is easier for businesses to serve more customers when they have kiosks and contactless stations on hand. Customers can access these features at any time while a business is open, including during off-peak hours.
  • Customers will have more control over their purchases. They will see everything available at a site, or they can select different payment methods for whatever works.
  • The risk of errors is minimal through self-serve spots. People can confirm their orders before paying for them, plus there’s no risk of someone mishearing or misinterpreting someone’s request.

More Consumer Spending

Self-service stations can also potentially increase sales numbers at businesses that offer them. Research and Markets writes that self-service kiosks can increase customer spending by about 30 percent on average. The rise is from people being more willing to spend money on purchases because they have more control over their orders.

Self-service kiosks could help reduce the income hit that stores have experienced as of late. Customers have been using physical stores less often in the past few years. The trend had been around before the pandemic, but the pandemic has accelerated that concern.

Meanwhile, people are more willing to buy products on kiosks, voice-activated devices, mobile devices like smartphones or tablets, and call centers. They want control over their orders, and they especially want more options when buying products. Self-service stations will be critical to how well businesses can thrive as the economy evolves and shifts.

When Will Businesses Adopt Self-Service Stations?

While self-service kiosks have become critical for sales during the pandemic, businesses that have explored these have held off on introducing them. Many enterprises have delayed their 2020 plans for introducing kiosks, as they saw limited revenues that year. They hope to bring in new stations in 2021 and 2022. The increased demand for these stations will especially make it where businesses will want to fast-track the development of new kiosks.

A General Concern of Cleanliness

There is one worry surrounding self-service retail spaces and how effective they can be. People aren’t interacting with others when checking out, but they are interacting with tables, trays, and touchscreens that others utilize each day. Some customers may also be using carts and baskets that others keep touching. They use them to store their purchases before bringing them to these kiosks to finish their orders.

The point proves that not all self-service retail items will be completely clean. But the perceived risk that customers have about these self-service features is lighter than if someone were to checkout with another person in a spot. Still, people might be more comfortable with using these kiosks if they know everything in those spots are clean and safe to use.

New technologies are still in development to make these self-serve spots cleaner. UV-powered antibacterial coatings or sensors may be utilized around these stations to keep them clean, for example. But business employees may still need to clean off these stations on occasion to ensure everyone stays comfortable.

NFC Technology Could Reduce the Risk

Another solution that could make self-service kiosks cleaner and more appealing entails NFC support. Kiosks could use NFC payment systems that allow people to purchase items through a completely contactless method. The customer can specify one’s order and wave a product over a sensor as necessary. The person will then waive a phone or other device linked to a payment account to pay for the purchase.

Amazon has been utilizing such a system at its Amazon Go stores. The “Just Walk Out” system lets people shop while being monitored by weight sensors, security cameras, and identification tags on items in these stores. Amazon’s system also uses deep machine learning to identify what items were purchased and what needs to be restocked the soonest.

While most businesses likely won’t have technology as advanced or complex as what Amazon uses, it is possible they could start working with more unique systems that reduce contact points. The general goal of the self-service industry will be to eliminate all contact points, providing an environment that everyone will feel comfortable with.

The growth of the self-serve industry will be worth exploring. People appreciate having more control over their orders. Businesses are also finding their own benefits through these systems. Expect the field to keep growing and to expand with new technologies that will make self-service stations more convenient and sanitary. Trends show that these kiosks are growing in popularity, so taking advantage of that trend will be critical to success.

a close up of an african man x27 s hand paying at a grocery supermarket checkout with a contactless payment using a mobile 220100705

Google Pay Adds Grocery and Transit Service Deals

Google Pay is already a popular mobile payment system, as it supports wireless payments on various Android-enabled devices. It is flexible enough to work on any Android-powered tablet, phone, or watch. It uses a secure approach to paying that can link to a credit card or another payment source.

Google Pay isn’t done evolving, as it is partnering with various grocery store chains to offer more benefits for customers who shop with this digital wallet app. Google Pay is partnering with the Target department store and the Safeway grocery chain to offer grocery deals. It is also working with various transit companies in the United States to offer more affordable and convenient ways for users to purchase tickets.

The new development is the latest move from Google Pay to become more convenient and useful for work needs. Google Pay has been expanding its options for how it works while staying competitive with Apple Pay and other competing solutions.

Grocery Support

The first part of Google Pay’s update is to help customers find the best deals on purchases at Target and Safeway grocery stores. The update will work for all Target locations around the United States. It will also run at many Safeway locations across the country. These include Albertsons, Randalls, Tom Thumb, Vons, Pavilions, and Jewel-Osco locations in different areas.

The new Google Pay update allows app users to browse Safeway and Target’s weekly circulars. These features will highlight the latest deals these stores offer.

Google Pay can also recommend different deals from each circular. It can identify prior purchases and one’s preferences to find the best deals.

Google Pay will also notify users of weekly deals when they are near participating stores. The feature works when the device reads the customer’s location. It automatically sends details on the deals available in that location, giving the customer the details one needs before shopping.

What makes this development noteworthy is that in-store shopping hasn’t been as popular as of late. The global pandemic has prompted people to look at online shopping, including digital shopping where people can get their grocery items delivered to their homes. The location-based system Google Pay will likely face a challenge as people might not be willing to return to in-person shopping as soon. But the risk of in-person shopping has been dropping as vaccination rates rise, making it possible that the new move from Google Pay could be more successful than people expect.

Transit Support

Another part of the Google Pay update involves helping people buy transit tickets in moments. Google Pay will help customers buy transit tickets in more than eighty cities around the United States.

People can use Google Pay to search for transit tickets and to buy them with their Google Pay accounts. People can then load their tickets on their apps and use them to board whatever buses, trains, or other transit services they wish to use.

Google Pay transit feature will now work in Chicago and the San Francisco area. The move comes not long after Apple Pay announced its support for the Clipper transit card for Bay Area Rapid Transit services in the San Francisco area.

The Google Pay customer will hold one’s device up to a reader to board the bus or train service. A visual ticket may be necessary if there are no readers available.

Google Pay also uses Token Transit integration to help people pay for public transit services in smaller towns around the United States and Canada. Token Transit lets people search for bus agencies around the country. People can choose whatever passes they need and specify how much time they will require. The system supports various bus transit services in many smaller communities.

Part of an Ongoing Expansion

The new features on Google Pay are part of the app’s ongoing expansion to provide more services and solutions for payment needs. Google Pay facilitates contactless payments, plus it can track a person’s finances. The app even introduced the Plex system as a partnership with major banks to help people keep track of their bank accounts and funds while on the go.

Google Pay is still changing to offer more things. It is working to produce more detailed insights and analysis reports on how people spend their money and how they research things of value. These reports can come from whatever purchases someone makes through Google Pay, including details on what one spends and what specific stores one visits. The insights will help customers find deals on whatever they are more likely to find at stores.

Competition Is Critical

The hope for Google Pay is that it will continue to expand to offer more things of value. But there are some contenders who are trying to capture some of Google Pay’s momentum. These include entities that go well beyond Apple Pay, including a few that have become highly prominent in their own right.

PayPal is hoping to update its app to make it more thorough and comprehensive. PayPal’s app has been updated to support QR code payments that are easy to follow. PayPal can also support buy-now-pay-later transactions, plus it can support some cryptocurrencies.

Facebook also has plans to produce a competitor to Google Pay. Novi, a program formerly known as Calibra, will support full integration of all Facebook programs. These include the WhatsApp, Instagram, Messenger, and Kustomer platforms. The setup allows people to pay for more items and to access various things of value. The app will also potentially link to the Diem cryptocurrency that Facebook is planning, although it is unclear when Diem would be made available.

The competition will likely prompt Google Pay to advance and evolve further. Google Pay has already become a popular choice for payments, and its new efforts in facilitating transit payments and in helping people find shopping deals are proof that the app is still changing.

pos terminal smartphone smartwatch contactless payments set 103888539

MasterCard Introduces Next-Generation Contactless Payments

On 26th January 2021, MasterCard made the announcement that it is going to apply for the revolutionary range of quantum-resistant technologies for the development of next-gen contactless payments. The Ecos or Enhanced Contactless specifications will be the first-ever such technology in the industry. It helps in ensuring that as the dynamic digital landscape continues to evolve, and newer technologies including quantum computing are getting introduced, the technology of contactless payments will be future-proofed. At the same time, it also helps in ensuring that consumers would continue enjoying the same higher levels of security as well as convenience they have in the modern era, for several years to come.

The overall demand for safer, more convenient, and faster ways of payment has ignited the transition to the technology of contactless payments. At the same time, it is expected that the given trend will only grow in the coming years. As a matter of fact, during the 3rd quarter of 2020, contactless payments accounted for around 41 percent of transactions related to in-person purchases across the globe –witnessing an overall increase of 30 percent in comparison to the previous year.

MasterCard Introducing the Revolutionary Contactless Payment Technology

MasterCard has been accelerating the overall shift to the concept of contactless payment for several years. At the same time, the leading payment giant has been developing high-end specifications in the form of Ecos for supporting efforts related to industry standardization. At the same time, it can also help in ensuring that the overall ecosystem tends to benefit from increasing security levels.

Ajay Bhalla –President of Cyber & Intelligence at MasterCard, says that contactless technology serves to be the present as well as the future of in-person payments. The year 2020 had been responsible for bringing with it a significant rise of digitization while reinforcing the overall significance of digital solutions. One major instance of the given solution is contactless technology for helping in meeting the everyday needs. As the given ecosystem continues evolving, an increasing number of connected devices as well as the IoT (Internet of Things) are going to yield improved user demands. At the same time, it can also help in creating a greater need for continuous innovation for building next-gen capability while ensuring that technology would never outgrow trust.

Benefits of Ecos

With the help of Ecos or Enhanced Contactless specifications, some potential benefits to look out for are:

  • Improved Convenience: Over the passage of time, it is estimated that the respective in-store shopping experience will become contactless only. The latest specifications will help in delivering the assurance that any device is truly capable of serving as a payment device while getting rid of the overall need for the backup swiping or dipping of the card.
  • Improved Privacy: The all-new specifications will be helpful in delivering advanced protection when the existing account information will be getting shared between the digital wallet or card and the final checkout terminal. Ecos helps in building on the improved requirements for supporting a myriad of privacy regulations.
  • Improved Trust: Ecos is known to make use of the all-new quantum-resistant technology for delivering advanced algorithms as well as cryptography major strengths. At the same time, it also helps in maintaining the contactless interaction under the value of half a second.

As the all-new specifications get activated in the period of coming years, merchants as well as consumers can expect hassle-free transactions. Mobile payments, digital wallets, point-of-sale terminals, and contactless cards are going to continue working as they are doing in the modern era. Moreover, the overall compatibility with Ecos, along with the ongoing contactless specifications is going to be simple & straightforward.

Ecos is known to work behind the existing scenes while being delivered through some software upgrade. As such, no terminals or hardware specifications are required. The given investment tends to complement similar investments in the form of Click-to-pay, 3-D secure, and token technologies for delivering an improved merchant as well as consumer experience.

The Ever-increasing Demand for Contactless Payments

The overall demand for contactless payments is going strong and is increasing with each passing day. It is estimated that around 15 percent of the respective in-store purchases across the globe make use of the given technology. Realizing the immense opportunity to speed up the process of adoption, MasterCard has come up with a proper roadmap for setting out the specific requirements:

  • After the period of October 2018, acceptance terminals that are relatively newer in countries like Africa, the Middle East, Asia Pacific, Latin America, and Europe will be featuring the EMV chip while being contactless enabled.
  • After the period of April 2019, the cards that are issued new in the countries like Africa, the Middle East, Asia Pacific, and Latin America will be featuring EMV chip as well as the revolutionary contactless technology
  • By the time of April 2023, all the respective merchant terminals in countries like the Middle East, Europe, Africa, and Latin America will be featuring the EMV chip while being contactless-enabled

Markets across the countries of Africa and the Middle East have already embraced and implemented the high-end technology of contactless payments. The given momentum is expected to receive more momentum with the acceleration of the acceptance landscape in the given region.

Foundation for Improved Security and Enhanced Growth

In the modern digital world, transactions are going to get smarter. At the core of the given fact is dynamic authentication in which every transaction would be incorporating unique information. It would also make it virtually impossible to replicate. This helps in reducing the overall risk of ensuring fraudulent transactions.

As the issuers would be evolving the respective offerings with the merchants upgrading the existing terminals, the modern payment system will be becoming more secure. This is because the given form of dynamic data gets introduced into the payment transaction. As such, the roadmap by MasterCard aims at strongly encouraging the overall adoption of the most secure available technologies.

What Are NFC

What Are NFC, Apple Pay, and Google Pay?

Today, consumers either don’t use cash or they try to avoid it as much as possible. Many even avoid using their credit card, and thanks to NFC, or ‘Near Field Communication,’ it’s possible.

What is NFC?

NFC allows two devices near one another to ‘talk’ to exchange payment information. Apple Pay and Google Pay are two of the most common NFC type payments used today, although there are others. How do they work and what should users pay with them?

Apple Pay – How it Works

As you probably guessed, Apple Pay is a payment option for Apple users. Customers may also use their Apple Watch to make payments. When a user is near an NFC terminal where they want to make a payment, they do the following:

  • Unlock the phone or watch using face ID or entering the passcode
  • Hold the phone near the NFC reader
  • They’ll hear a beep or feel a tap when the transaction is complete
  • The screen will show a check mark to show it’s done

Using these steps will pay with the default card set up in Apple Pay. If you want to use a different card, you must switch cards in the app before paying.

Google Pay – How it Works

Google Pay is the equivalent of Apple Pay but for Android phones. Users store a credit card in the Google Pay app and use the default card for contactless payments.

Users use these steps to pay with Google Pay:

  • Unlock the phone or watch
  • Hold the phone or watch near the NFC reader
  • Their device will show a blue checkmark when it’s complete
  • The user’s device will buzz when the payment is complete

Are NFC Payments Safe?

Consumers and merchants have reason to worry about NFC payments’ safety. It seems like it would be riskier, but there is less risk using NFC payments than a credit card.

Since you don’t have to share any personal information or even show a picture ID, there’s a lower risk of the consumer’s information being stolen. Users also have to unlock their phone for the payment to take place, so unless a thief has the passcode, they couldn’t use the Apple or Google Pay function.

Also, both Apple and Google Pay have the option to switch the function off from any device. If a user’s phone is stolen, they can shut off the payment app via any internet-enabled device.

Why is NFC the Wave of the Future?

NFC payments were popular before, but the pandemic further popularized NFC. People were almost forced to adopt the technology, which made it more widely spread. Now that people know how it works and that it’s safe, they are more likely to use NFC payments moving forward.

As a merchant, it works to your benefit to adopt the technology in your store. Consumers will patronize businesses they know keep them safe, and adding NFC payments to your checkout process is a sign of safety.

COVID-19 Payment Trends

COVID-19 Payment Trends Are Here to Stay, Says Visa

As we near the one-year anniversary of the pandemic, it’s apparent that the latest payment trends that took place at swift speeds are here to stay.

The most common changes businesses are implementing include contactless payments, ‘buy now, pay later’ options, and increased security protection. In short, small and micro businesses need to cater to customers in the areas they need it most – they want to stay safe, yet still conduct business as usual.

According to the Visa ‘Back to Business Study,’ more than 80 percent of small and micro businesses changed the way they accepted payments and/or did business. The study also found that business owners are still looking for ways to implement new strategies to protect consumers from fraudulent transactions, accept contactless payments, and offer additional payment opportunities.

What Most Businesses are Doing Today

  • Contactless payments – The largest surge of payment changes are how merchants collect payments. In-person swipe or chip cards aren’t nearly as common as contactless payment options. In the summer of 2020, only 20 percent of small businesses offered contactless payments. Today, that number is at 40 percent of businesses and climbing.
  • Increased digital payment options – Many small businesses also reported meeting customers where they are – online. Most customers want to do business digitally to avoid unnecessary contact that could put them at risk. Whether that means curbside pickup or home delivery options, many small businesses are adapting to what consumers need.
  • Protecting against fraud – Protecting against fraudulent transactions is the key to successful business transactions. Many businesses still have a long way to go in this department, but many businesses are going in the right direction.

Why Contactless Payments are so Important

COVID

Many businesses focused first on mask use in-store, which is a large concern. But consumers have more concerns than the airborne risk not wearing a mask poses. They want to know they’re protected from all shared devices which include pens, credit card machines, and handling cash.

Offering contactless payment options for credit card processing keeps your customers safe and gives them a reason to come back. If they don’t feel supported or validated in their concerns, they’ll take their business elsewhere.

What Else are Businesses Doing?

Besides the precautions taking place in the store with credit card processing and avoiding shared devices, customers want an online shopping option too.

Businesses that didn’t sell anything online are now online. According to the Visa study, in the summer of 2020, only 27 percent of small businesses jumped online, while by winter of 2020 43 percent of businesses are online and the number keeps growing.

Small businesses that want to see their business through to the end of this pandemic must meet the customer where they are. The trends that the pandemic started aren’t going to go away when the pandemic dies down. Instead, it will be the ‘new normal’ for most consumers, so the sooner you jump on the bandwagon, the more your business will grow.

2

More Consumers Want to Use Venmo at Retail Stores [2023 Update]

Venmo started as a fun way for peers to pay one another, but it’s quickly becoming the payment method of choice at retailers too.

Venmo has become a household brand – it’s the brand consumers trust when paying friends and family, and now they want retailers to use it too. While contactless payment options are more available than ever before, consumers don’t trust all of them, but Venmo is an exception.

Venmo Has an Incredible Following

Over 65 million people use Venmo to send and receive funds. Much of the audience is the younger generations, but it also includes affluent and educated older generations who’ve embraced contactless payments today.

Venmo users love the versatility Venmo offers including splitting the bill with family and friends. It’s a natural transition to use it to pay retailers, especially in restaurants when out with a group, and splitting the bill always causes that award silence everyone hates.

Consumers Want to Change Their Habits

At the start of the pandemic, consumers shopped mostly online as many retailers were closed while the entire country was shut down. The trend continued for a while, but slowly, retail trends indicate that consumers are shopping in-store again.

When they do, they want options to stay safe and that includes contactless payment options, of which Venmo is a top choice.

Since consumers are already comfortable with it, they don’t have to learn a new platform or discover if it’s safe or not. They know Venmo is safe. With consumers able to add funds to their Venmo account and/or pay their balance over time, Venmo is quickly the most popular choice.

What Troubles Would Retailers Face?

While consumers are on board with paying for retail purchases via Venmo, the platform itself isn’t quite ready.

While some retailers use Venmo, they are few and far between. It’s primarily a peer-to-peer app that doesn’t need to consider taxes or fees. With the onslaught of changes accepting retail payments would offer, Venmo’s platform would have to change considerably to handle the pressure of accepting retail payments.

Why is Contactless Payments so Popular?

Is Venmo Safe for Sellers

Image source

As the pandemic continues, consumers want contactless payment options. It creates the best of both worlds for consumers – they can shop safely, in person, and not have to worry about touching shared devices or even exchanging payment with the cashier.

The more hands-off the shopping experience can be, the better off we’ll be in the end. Not using cash and using phones to pay is the epitome of cashless spending. You can check out with ease, shop in person, but not have to worry about the risk the virus poses with shared devices.

Will Venmo Jump on Board?

The jury is still out if Venmo will become the way of the future. But one thing is for certain, all consumers want contactless credit card processing systems. Whatever you can do to make that happen in your store will help increase your sales.

MasterCard Takes Contactless Payments to the Cloud

MasterCard Takes Contactless Payments to the Cloud

The past few months, especially since the pandemic outbreak, saw rapid development in contactless payments. The rising need to accept or adopt cashless or contactless payment modes was mainly in response to preventing the spread of coronavirus.

Nowadays, more advanced and smarter technologies are being deployed across several mobile devices, mostly due to factors like convenience, flexibility, and speed. And this is the reason why contactless payments are gradually being moved to the cloud.

contactless payments

With that, the card brand, MasterCard announced on January 11, 2021, that it has partnered with payments gateway NMI, financial tech company Global Payments, and IT services provider CEG (Computer Engineering Group) to launch its first pilot for the new cloud-based point of sale (POS) technology, called Cloud Tap on Phone.

Their aim is to broaden the acceptance of contactless payments for merchants since today’s consumers prefer paying for their purchases using mobile payments on their smartphones. In addition to enhancing and expanding its point-of-sale solutions, MasterCard is also working on improving its cloud POS systems.

mastercard contactless payments

The card network’s goal is to make its Cloud Tap on Phone openly available across various cloud-based environments. It will empower different solution providers and ecosystem partners to build their own cloud POS offerings by integrating newer features, tools, and functionalities. The process, therefore, is also expanding the acceptance of this new cloud-based payment and POS technology.

Nili Klenoff, Senior Vice President, Global Acceptance Solutions at MasterCard, revealed that the pilot for their new cloud POS system is based on three major dynamics in the marketplace:

  1. The digital shift, which she believes won’t change soon, even if the pandemic recedes.
  2. The acceleration in the need for adopting a contactless infrastructure within the retail industry.
  3. The advantage of switching to cloud solutions, which Klenoff believes is democratizing access to digital payments solutions and apps.

MasterCard has further said that in Q3 2020, contactless payments accounted for 41% of global in-person transactions. This was a significant increase from the previous year’s 30%. It indicates that amid the pandemic situation, this new offering received much popularity and acceptance.

mastercard contactless payments - Cloud Tap On Phone

As a result of this launch, other payment players have innovated their digital POS solutions to make them more widely accessible.

For example, towards the end of 2020, Visa came up with its Tap-to-Phone solution across several global markets. Just like MasterCard’s Tap on Phone solution, Visa provides businesses with a mobile POS solution that one can deploy without requiring any additional hardware.

Klenoff reportedly said that the company’s new cloud solution is designed to help users develop and expand the entire payment ecosystem. This is mainly targeted at enabling businesses to enhance their customer engagement and improve their shopping experiences.

This new system from the card company can be especially beneficial for SMBs (small- and medium-sized businesses), who are affected by the pandemic outbreak. Hence, the cloud-based POS solution might also accelerate the global expansion and evolution of digital transactions.

MasterCard Contactless Payments – Key Points

  • Cloud Tap on Phone is one of the card network’s next-gen innovative acceptance products. Furthermore, the software is hosted on the powerful Azure Cloud platform from Microsoft.
  • Microbusinesses and SMBs can gain access to a more cost-efficient contactless POS system without investing in any external hardware. MasterCard’s Cloud Tap on Phone can help businesses with fewer resources for purchasing additional POS hardware.
  • During the COVID-19 crisis, 34% of SMBs have adopted contactless payment solutions to optimize their checkout processes. This was a result of a study conducted by Paysafe that analyzed several SMB checkout processes used in various countries like the US, UK, Italy, Canada, Austria, Bulgaria, and Germany.
  • The Tap on Phone solution from MasterCard is also designed to expand the acceptance of contactless payments across global markets.
  • By introducing this cloud-based POS system, SMBs can also keep pace with larger enterprises that provide a number of different payment modes. It further enables MasterCard to increase their volume of payments.
  • Since the company’s new offering is spreading across numerous countries, businesses operating in markets where digital transaction infrastructures are developing, such as parts of Asia and Africa, are expected to gain access to this cloud POS system. It will further push contactless payment acceptance forward, thus accelerating MasterCard’s payment volume potential.
  • For instance, micromerchants running in India who have seen significant growth in cashless payments are more likely to take up the card network’s offering. Therefore, it will expand the overall acceptance of contactless payments in the near future.
  • Using the Tap on Phone solution, businesses, irrespective of their size, can deliver the best-in-class contactless payment expenses to their consumers via their own smartphones.
  • MasterCard’s new cloud system democratizes POS technology by converting an Android device into an acceptance device. It enables businesses to implement more contactless payment systems at checkout, while cutting down costs on external hardware terminals and other tools or features.
  • The system will help merchants to provide better curbside pay on delivery or pickup facilities for faster checkouts at the store, thus eliminating long queues. It’s a convenient, touch-free, cash alternative for consumers.
  • MasterCard’s cloud POS has become a new channel for businesses to provide more meaningful and value-added services to their consumers.
  • At present, MasterCard’s Tap on Phone software has been rolled out across 16 markets, including Asia Pacific, Europe, Latin America, North America, Africa, and the Middle East. Additionally, pilots are occurring with respective partners in Hong Kong, Costa Rica, Poland, Romania, Kazakhstan, Russia, Canada, the UK, Belarus, Turkey, and several other markets.
  • The card network’s new product development wing, MasterCard Labs, spearheaded the development of the cloud POS technology and its new cloud-based Tap on Phone product. The pilot working with CEG is following product testing sessions on the New York campus of MasterCard’s Purchase.
  • The product, Cloud POS, is a result of the company’s multi-cloud strength, meeting several businesses, financial institutions, partners, and consumers in the Cloud using innovative solutions and applications.

MasterCard has been planning this transition to contactless digital transactions for years. The rising demand for faster, safer, more convenient, and flexible methods to make payments has been a driving force behind this transition.

Today, consumers are willing to use this touch-free transaction experience permanently, even after the pandemic ends.