Tag Archives: merchant services

payment processing

Payment Processing News Roundup [2023 Update]

Payment Processing News

Today The Official Merchant Services Blog is going to give you a roundup of the latest news that is affecting merchants and payment processing. Our goal is to keep you informed and up to date on all the important news developments in the industry. Armed with that information you can make the decisions and the moves to keep your business ahead of the curve. The news roundup today focuses mainly on The Durbin Amendment and its continued impact on consumers, merchants and processors. The Durbin Amendment will continue to have a major impact on processing throughout 2012, and we’ll continue to keep you abreast of the topic.

Durbin Reactions

The first story we bring you is from the Los Angeles Times and it’s about the fallout from the Durbin Amendment. The article, found here, states that by the end of last year 610,000 U.S. bank customers switched to a switched to a smaller institution to protest plans by major banks to impose monthly charges for using debit cards. The article says the data was reported by Javelin Strategy & Research in a report and that the 610,000 figure represented 11% of the overall 5.6 million people who switched banks in that time period. The article also noted that: “In addition to the 11% who joined the Bank Transfer Day movement in October, November and December, an additional 26% told Javelin that they switched not as part of the protest movement per se but because the banks charged too many fees.”

Host Merchant Services Predictions Confirmed

The next news item we’re reporting is from The Denver Post. In this article the Post reports pretty much exactly what Host Merchant Services predicted would happen in its Durbin Amendment Analysis article.

The Denver Post writes: “Instead of one new fee, prepare to be sold more products, offered new services, lose rewards and face more fees in general.”

In the HMS Article from 2011, we wrote: “Merchants will end up having to shoulder the burden of the extreme cuts in revenue that this cap brings. Those who predict that merchants will end up worse off by the amendment suggest that the banks, not wanting to take a $9 to $10 billion dollar loss in revenues for the year, will simply add fees to other payment options or get rid of premiums and extras that they had been offering merchants prior to the cap being put in place.”

So essentially the Denver Post reports that the banking industry is reacting as expected to the Durbin Amendment. We even did an entire blog making the statement that the banking industry was going to go in stealth mode like a ninja.

The Denver Post article also gives a recounting of the tale of the Durbin Amendment as it took center stage in the media spotlight. This entire tale was chronicled as it happened by The Official Merchant Services Blog both in its Countdown to Durbin Series, as well as its ongoing Durbin Coverage after the October 1, 2011 date that saw the bill’s provisions begin. The Denver Post recap is succinct and states: “Several other banks already had either imposed debit card fees or were testing them, and analysts had predicted the trend would spread to the entire industry. But BofA’s plan, which leaked out at the end of September, produced an enormous surge of criticism. Protesters from the Occupy movement, consumer advocates and even President Obama questioned the move, and an online movement called Bank Transfer Day emerged to encourage people to switch to small  banks and credit unions. Bank of America ultimately called off its plans without imposing the $5 charge, and the rest of the industry followed suit in allowing fee-free use of debit cards.“

Durbin Going Bye Bye?

The final piece of Durbin-related news comes to us from payment processing review site cardpaymentoptions.com. In this article, they give an extensive roundup of their predictions for 2012 — and one piece is sub-titled “Durbin May Get the Boot.” The article states the Durbin Amendment was originally designed to help merchants deal with high swipe debit card transaction fees, but now that it’s been in effect merchants are feeling the legislation has harmed them. The article specifically cites merchants getting hit with much higher for small ticket transactions — a noted loophole in the law that many media sources criticized while the amendment was still being discussed by Congress.

The article then makes this bold prediction: “Several retail organizations have brought suit against the Federal Reserve in order to repeal/modify the amendment and even the main author, Dick Durbin, has admitted the new law is flawed. With such disastrous results, merchants should expect to see the Durbin Amendment either repealed or greatly modified this year.”

The Official Merchant Services Blog has reported on a few of these suits as they’ve come up. And the backlash against Durbin has been significant. But with the election about to be in full swing it seems, to us at least, that the Durbin Amendment may continue to kick around for 2012. In fact, we’ve also reported that there is growing interest in a similar cap on credit card processing fees, swinging things even further in a direction that will burden consumers and incur ire with the banking industry. It just seems like it will be a lot more difficult to get rid of Durbin after it’s started and that the path of least resistance for Congress on this issue will be to continue to add to the law with more tweaks and changes, making it even murkier and over-legislated. That’s more the federal government’s style.

What do you think? Will 2012 see the end of the Durbin Amendment and the great experiment that was finance reform for payment processing fees? Or will the federal government just try to keep working with the law they have in place trying to smooth it out?

Visa Kicks Open the Door for Chip Cards

Today The Official Merchant Services Blog discusses a fascinating new development by Visa in the realm of credit card processing, security, and hopefully Mobile Payment Technology.

Smart cards have been slow in gaining traction, especially in the United States. But now Visa is making moves to drag the U.S. into the chip card realm, kicking and screaming if it has to. A recent article on Credit.com reveals as of December 31, 2011, Visa — the largest processor of both debit and credit card payments — had issued more than 1 million credit cards that use “chip” technology to sore consumer payment information. The article notes that this data is being announced rather quickly in relation to Visa’s August 2011 announcement that it planned to start issuing more EMV — Europay, Mastercard, Visa — smart cards to push the industry toward better security and an easier transition to mobile payments.

What is Smart Card Technology?

A smart card, or chip card, is any pocket-sized card with embedded integrated circuits. These cards contain volatile memory and microprocessor components, are made of plastic,and provide strong security authentication capabilities. Because of these characteristics, the technology is being utilized for credit cards by major card companies like Europay, MasterCard and Visa — garnering the nickname EMV. Visa has begun a major push of this technology because of the benefits the technology provides.

Host Merchant Services image of smart card chip technology

What are Those Benefits?

These kinds of smart cards can provide identification, authentication, data storage and application processing. A single contact/contactless smart card can be programmed with multiple banking credentials, medical entitlement, driver’s license/public transport entitlement, loyalty programs and club memberships to name just a few. Multi-factor and proximity authentication can and has been embedded into smart cards to increase the security of all services on the card. In one fell swoop, this technology can bridge the gap between card-swipe style processing and the mobile payment processing that the industry is striving to move toward. The technology lets virtual wallets and contactless payment happen, increasing convenience for consumers. And then it also boosts security, which is the largest concern consumers have with mobile payments.

The Credit.com article quotes Stephanie Ericksen, head of authentication product integration at Visa Inc. as saying “Migrating the U.S. market to chip will help build an infrastructure for accepting NFC mobile payments, enhance international acceptance and reduce fraud.”

TransFirst Sets Guidelines

TransFirst, Host Merchant Services’ acquirer and one of the premier providers of transaction processing services and payment processing technologies in the U.S., has issued a mandate in response to the EMV push. TransFirst says that Visa will require U.S. acquirer processors and sub-processor service providers to be able to support merchant acceptance of chip transactions no later than April 1, 2013. Visa also intends to institute a U.S. liability shift for domestic and cross-border counterfeit card-present point-of-sale transactions effective October 1, 2015, and for fuel-selling merchants by October 1, 2017.

Many of these dates are long-term projections and would seem to be a little far out there in comparison to the fast-paced results Visa is achieving already with their shift to chip cards.

Host Merchant Services image of a contactless terminal for EMV cards

The Carrot on the Stick

TransFirst explains that Liability Shift is often used as the incentive to encourage acquirers or issuers to move to chip transactions. For magnetic stripe swipe transactions, POS counterfeit fraud is mostly absorbed by the card issuers. But in the EMV shift Visa is pushing, the party that is not chip-capable will be liable for frauds that would have been prevented if the transaction were processed with a chip-on-chip connection.

It would seem that Visa is happy with the fast embracing of their chip transition but are still giving the acquirers and the merchant service providers and the merchants years to implement this fully before holding them liable.

In preparation for Visa’s Accelerated Chip Migration plan, TransFirst will migrate new terminal deployments on the following POS Terminals to chip capable versions of the same devices. Once implemented, non-chip capable versions of these terminals will no longer be available for purchase through TransFirst:

  • Verifone’s Vx570
  • Hypercom’s T4205
  • Hypercom’s T4220
  • Hypercom’s M4230

How Chip Cards Work

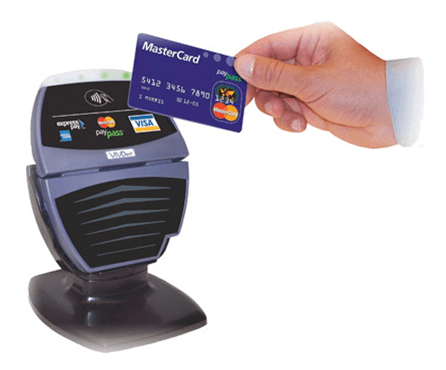
These new cards work in a similar fashion to the cards they are replacing. Users present them when making a purchase and from there the transaction follows the steps detailed in the Host Merchant Services Infographic found here. But the cards are different from swipe cards in some very important ways. Consumers do not swipe these cards. Instead they wave them over a sensor. This is the exact same style of payment that mobile phone based “virtual wallets” look to employ. You wave your smart card across a sensor, or you wave your smart phone across a sensor. Payment made. Visa also plans to allow chip cards to work with PIN codes, bringing debit under the umbrella.

Host Merchant Services image breaking down how chip cards work

The Mobile Payment Connection

Visa is heavily invested in the future of Mobile Payments. Which is not surprising as you can see from Host Merchant Services‘ coverage of the topic in its article archive. Past blogs have noted that the biggest obstacle Mobile Payments face with U.S. consumers is concern about the safety of the transactions. Visa’s hoping that the added security that the chip technology provides will overcome that obstacle and finally tap them into the billions of dollars of revenue that Mobile Payments are predicted to have in the coming years. As Ericksen says in the Credit.com article, “Since announcing our roadmap last year, we have seen strong interest among U.S. issuers large and small to invest in chip technology, as today’s milestone shows.”

Tips to Improve Your Business’ Website

Today The Official Merchant Services Blog is going to address an e-commerce issue that perhaps gets overlooked by a lot of merchants — effective design of your online shopping experience. Previously we offered a 2-part series on free, open source online shopping carts that are available. But just having the basic elements there for functionality is only part of the process. Your site should integrate e-commerce into its experience seamlessly so that visitors effortlessly make the transition from stopping by to actually purchasing.

Design plays a huge role in making this happen.

What is E-Commerce?

E-Commerce refers to the buying and selling of products or services over electronic systems such as the Internet and other computer networks. The term may also refer to the entire online process of developing, marketing, selling, delivering, servicing and paying for products and services. You can review a detailed explanation of E-Commerce in the Host Merchant Services Article Archive at this link here.

Why is E-Commerce Important?

E-Commerce is important because of how commonplace it has become in the daily lives of consumers. Shopping online has blossomed and grown in the past decade, and sales figures show that it is a standard. Merchants need to offer online shopping alternatives and can make quite a lot of profit by offering good online shopping solutions.

E-Commerce Tips

To assist merchants in making their e-commerce venture robust, well designed and profitable, we’re going to offer up a series of tips focused on improving e-commerce through strong design elements. Here’s our list of tips:

Navigation

Navigation is probably one of the most basic, and yet most often mangled aspect of strong e-commerce design. All online shopping sites have to allow their customers to navigate through the products to find the stuff the customer wants to buy. But so many sites out there have difficult or clunky navigation. Make sure your site offers a smooth, easy to navigate experience and you’ll get your customers clicking “purchase” much more frequently.

Host Merchant Services image for online shopping

A Detailed Product Catalog

Tied right into navigation, is the single most important element merchants need to consider — the product catalog. This is what you are selling and it needs to be seamlessly incorporated into your website. Your product catalog needs to have detailed information about the products you are selling.

Database Search Capability

This is an extension of the previous element. If you have a large product catalog, then you need to offer your customers the ability to search through that catalog. Essentially you need to give your customers a database searching tool that will help them drilldown through your catalog to quickly find what products they are interested in.

Product Images

Your catalog needs to contain clean, easily readable images of the products. You should consider offering images from multiple angles — this is of course product dependent — so that your customers can feel safe that they are getting the most information possible about what they buy. One of the long-standing concerns about buying online is that customers feel like they’re being conned because they can’t view the product right there in front of them. Offering multiple angles can assuage some of those fears. Also you must balance the issue of image file size versus resolution and quality of image. You want to keep images small enough that they don’t distract from your catalog, but detailed enough that they give the customer a good look at what they’re buying. One solution that a lot of sites use these days is a Content Delivery Network (CDN).

Contact Information

Your E-Commerce solution needs to contain an easy to use, and easy to find, contact information area. Many sites make finding contact information a bit of a treasure hunt — sometimes requiring using the site map just like a treasure map. Keeping contact information visible and easy to use helps you with long-term customer service goals. And your contact information can also assist you in making sales. If a customer has special needs or requests involving a product they want to buy, they may need to contact your business directly. Making them hunt around for the ability to contact your business could cost you a sale.

email


Checkout Process

Integrating your online shopping cart into your site is extremely important. It was the primary reason we ran through our two-part series on open source shopping carts. Those 10 carts were advertised because of their cost efficiency (free) and because of their online support. Having a strong support community from an open source shopping cart gives you a safety net for things like your checkout process. Your checkout process needs to be smooth. It needs to be just a series of clicks and a small form (usually credit card information). Your customers want to click to purchase, click to confirm and get the shopping done. That’s the biggest draw of an online shopping cart — the internet makes it easy and convenient. So your checkout process needs to play on that, and get your customers through the checkout fields as easily as possible.

Payment Options

Building off of the checkout process, a good online shopping cart needs to present the various payment options to its customers in a clear, concise and easy to read manner. You want to offer your customers a variety of payment options. This includes all forms of credit and debit transactions, including gift card — even EBT where applicable. You want to make sure coupon codes and gift certificates are also shown clearly and have easy to use forms for completion. Merchant Services Providers, like Host Merchant Services, make it easy for merchants to offer any and all forms of payment for their online shopping cart. So it’s really just a matter of contacting your merchant services provider to make sure your e-commerce is customized to offer the maximum amount of payment options.

Related Products

This is an E-Commerce enhancement that helps improve your shopping experience. You an see this in a variety of forms. It can be something as simple as a list of products that fall under the same “category” your customer was searching, or as over the top as what Amazon does with its Customers Also Bought These Items lists that you get when shopping there. No matter what your approach, though, you should consider offering some type of related products feature in your online shopping cart. This helps establish return business in a very meaningful way as it gives customers targeted advertising to products they may also be interested in purchasing.

Image for Host Merchant Services article on credit card processing

Shipping Rates Calculator

This should be standard on any and all e-commerce sites. Letting the customer control and maximize their shipping options directly will lead to more sales. Shipping costs have always been one of the biggest obstacles E-Commerce has faced, so making it transparent and giving customers the ability to reduce their costs manually helps keep them hooked on the potential sale of your product.

Store Policies

And last, but not least, try to make any and all relevant store policies displayed prominently on the site during the perusal and during the purchase portion of the experience. This includes things like return policies and refund policies. Be as up front about what it is you can and unfortunately can not do for your customers and your E-Commerce site will avoid some serious customer service headaches.

That’s just the basics of what The Official Merchant Services Blog suggests merchants do to make their E-Commerce and online shopping experience powerful and persuasive for their customers.

stop online piracy act

SOPA: The RIAA isn’t doing so bad [2023 Update]

Today The Official Merchant Services Blog dives right back into the fire with the Stop Online Piracy Act (SOPA). We were kind of surprised to find out what this PC World Article had to say. Apparently the  music industry is doing pretty good despite the issue of online piracy upon which SOPA hinges.

SOPA was shelved by Congress more than ten days ago, as we reported in our January 20 blog, but the lobby that fueled the bill is still pushing for federal government involvement in online piracy. In fact, much of the content of SOPA that caused the controversy has popped back up on a wishlist from the International Federation of the Phonographic Industry (IFPI) regarding what they think needs to be done to fight online piracy. The IFPI is a global group similar to the U.S.-based Record Industry Association of America (RIAA).

SOPA and PIPA Review

To recap what SOPA was about you can review our initial post about it from our November 20, 2011 blog. The Official Merchant Services Blog was out in front of this story and eventually the rest of the medial caught up with the impact that this House of Representatives bill and its twin in the Senate — the Protect Intellectual Property Act (PIPA) — were going to have on a variety of tech industry sectors, including Payment Network Providers. Host Merchant Services provides an in-depth analysis of SOPA here.

Host Merchant Services image about the Stop Online Piracy Act and the players involved.

The Kids are All Right

According to the RIAA the music industry is outperforming other entertainment sectors in terms of digital sales. Jonathan Lamy, senior VP of Communications for the RIAA, tweeted that paid subscription services rose 65 percent to 13.4 million in 2011. This tweet was in response to figures released by the IFPI which Lamy was excited to read. Lamy also tweeted that paid digital music services are active in 58 countries, generating $5.2 billion in revenues.

Jumping into the tweets was another RIAA executive, Cara Duckworth. The VP of Communications for the RIAA also cited the IFPI figures and then said: “W/more than half of all music sales coming from digital services, we know how Internet works. “Music=Innovation. Declare THAT. #CES #SOPA.”

Throwing down the gauntlet, the RIAA is now essentially claiming that they have a viable working digital sales model that can exist on the internet. And yet still they pursue a lobby to crack down on piracy, and collateral damage that includes the internet and e-commerce.

Here’s a graphic detailing the top sales from 2011 according to the IFPI:

Host Merchant Services chart on record sales in 2011, related to SOPA

The Wishlist

The IFPI put out this PDF which details a very hardline stance on how to deal with Online Piracy. Perhaps the most entertaining aspect of this wishlist is that it essentially repeats the details of SOPA. According to the PCWorld article IFPI chief executive Frances Moore said record companies are building a business in digital music “in spite of the environment in which they operate, not because of it.”

Moore went on to say record companies are working with ISPs, search engines, governments, and law-enforcement agencies to reduce the number of illegal downloads and ensure that an ever-higher percentage of the music that is downloaded is bought legally. “Our digital revenues, at one-third of industry income (and now more than 50 per cent in the US), substantially surpass those of other creative industries, such as films, books and newspapers.”

So the IFPI establishes with facts and figures that the music industry is doing well on the internet. Digital Music services are getting traction, profits are rising and piracy is being challenged. The RIAA finds all of this so amazing and awesome that they go and re-tweet it to the world.

With all of this good stuff being said about digital music sales, why does the IFPI have a wishlist of demands to fight piracy that seem pretty much like the exact same thing SOPA wrote?

The Seven Demands

This arstechnica.com article goes into detail about the demands the IFPI has. The demands can be broken down to seven key elements:

  1. Graduated response laws in which rightsholders can pass along notices about file-sharing to the accused party and possibly disconnect them from the internet.
  2. Site blocking. The industry wants the ability to wall off infringing sites, however defined (yes, you read that right, they don’t currently define the criteria for being able to wall off the site), at country borders.
  3. Search Engines need to help the industry. Search Engines need to remove links to infringing content that the industry identifies as well as prioritize links according to industry standards, not the engine’s own standards. Search Engines need to rank search results factoring legality or illegality into the ranking.
  4. Payment Processors. Just like SOPA and PIPA, the wishlist also includes payment processors. Which is why The Official Merchant Services Blog is continuing its ongoing coverage of this topic. Payment Network Providers, Payment Processors, merchant services providers, whatever the entertainment industry wants to call us, are being targeted to police copyright infringement. It’s very strange. The IFPI wishlist demands processors cut off pirates voluntarily, much like SOPA tried to do. As the ars technica article states: “This was a theme of the recent Stop Online Piracy Act in the US, which originally featured a section encouraging companies like MasterCard to take unilateral actions against websites, and provided legal immunity for doing so. IFPI touts a deal with the City of London Police and credit card companies in which IFPI supplies the City of London Police with evidence that illegal downloads are being made available from an infringing site. The police review the evidence, verify its integrity and notify payment providers that their services should not be provided to such sites.”
  5. Ad networks are being called on to cut off funds to suspected pirates as well. Even though some online advertising sites are themselves going through litigation for spams, scams and clickjacking.
  6. Mobile operators need to get involved according to the IFPI wishlist. Because hey, why not? The IFPI’s paranoia suggests that outside the comfy confines of the U.S. where illegal downloaders just lazily go about swiping songs from their PCs, “piratical behavior increasingly takes place through phones and other mobile devices.”
  7. And finally, the IFPI calls for increased litigation. Keep suing the big sites. The PDF report cites how much piracy dropped after Limewire was shutdown as the impetus to keep going after the big dogs in the world of online piracy. Compared to some of the other demands on this list, the final wish seems to be far more reasonable, logical and effective. Going after ad networks, especially those already mired in a legal quagmire of clicks and spam issues, might not do a whole lot in the war on piracy. Going after the big, popular piracy sites, though, might have an impact.

Where to go From Here?

Host Merchant Services image of a pirate button keyboardIt just seems tiresome that after all that went down with SOPA, PIPA, the internet blackout, and the controversy, the music industry just reloads and reuses the same exact talking points that got the laws killed in the first place. SOPA died because the things being asked for weren’t going to work. Banking on payment processors to police the internet was a bad idea. It still is a bad idea. This whole wishlist smacks of some old sitcom gag where a child asks one parent for a cookie, is told no, then goes and asks the other parent. The answer’s still no.

Payment Network Providers do not support online piracy. But the demands being given to them have loopholes where the Processor is being asked to shut down customers that are legitimate and not pirates, just on the whim of the entertainment industry.

And the real kick in the pants with all of this? At the exact same time the music industry makes this zealous push to continue to ask for wide open and ineffective legislation, they spend time gloating about how well they’re doing on the internet with legal, and apparently very profitable, digital transactions. All of course run through e-commerce sites supported by the same payment processors they are asking to shut down other customers at their fancy.

The bottom line is if Lady Gaga and Pitbull online sales are robust and  legit, it’s probably time to back off the Online Piracy rhetoric.

Facebook Attacks Clickjackers

Today The Official Merchant Services Blog takes a look at one of the latest and most twisted developments in online marketing: Clickjacking. This topic comes up because of a new lawsuit that is making the news. Facebook has filed a lawsuit against the company Adscend Media. The suit claims Adscend developed targeted spam campaigns and encouraged others to spread spam using a variety of tactics — including clickjacking.

According to Wikipedia, Clickjacking — also called User Interface redress attack, UI redress attack, or UI redressing — is a malicious technique of tricking Web users into revealing confidential information or taking control of their computer while clicking on seemingly innocuous web pages. A vulnerability across a variety of browsers and platforms, a clickjack takes the form of embedded code or a script that can execute without the user’s knowledge, such as clicking on a button that appears to perform another function.

Joining Facebook in filing against Adscend Media was the Washington State Attorney General Rob McKenna. A statement released by McKenna says: “We don’t ‘like’ schemes that illegally trick Facebook users into giving up personal information or paying for unwanted subscription services through spam. We applaud Facebook for devoting significant technical and legal resources to finding and stopping scams as soon as possible – and often before they even start. We’re proud to join forces in order to protect Washington consumers.”

In addition to Adscend, Jeremy Bash and Fehzan Ali, co-owners of the company, are named in the suit.

Jacking for Likes

Here’s how clickjacking scams, such as the ones described in this lawsuit, work:

Host Merchant Services image for Clickjacking scams

Scammers design Facebook Pages to look like they will offer visitors an opportunity to view provocative content. They then require the user to complete a series of steps before they can view the content. These steps are designed to lure Facebook users into visiting websites that deceive them and get them to reveal their personal information. In terms of what this particular lawsuit is focusing on, Facebook users are encouraged to click the “Like” button on the scammers’ Facebook Pages. These like-clicks then alert the user’s friends to the existence of the scammers’ page. Then they are told that they cannot access the content unless they complete an online survey or advertising offer.

In one example noted in the complaint, the scammers overlay the Facebook “Like” button with a link that promises to reveal the results of: “This man took a picture of his face every day for 8 years!!” Of course, the promised content often does not exist and the tricked user is then directed through a series of prompts taking them off of Facebook and through a host of unrelated advertising and subscription service offers, where the scammers receive money for each misdirected user.

In another example, a Facebook user would see a link to a video on a friend’s wall. If the user clicked on the link, a pop up would appear asking the user to verify their age. Clicking on the verification box, the user would unknowingly share the video on their own Facebook wall.

In some cases, Facebook users don’t even need to click the “like” button to spread the spam on their Facebook pages. In the process called “clickjacking,” a hidden code in enticing-looking links activates Facebook’s “like” function and puts it on the users’ friends’ news feeds.

Host Merchant Services Image detailing how Clickjacking Scams work

How this Affects SEO

We bring up this lawsuit to draw attention to this black hat and negative advertising practice. It can have a big impact on SEO and online marketing for businesses. Spam is never good and so on the most basic level if you get your own Facebook page wrapped up even indirectly with this type of scam, Facebook could take action against your business page. Beyond just that, there’s the negative PR that comes from being linked to a spam scam. If people think you are spamming them, you’ll lose more “fans” and “likes” than you would ever gain by the scam campaign.

Facebook is a powerful marketing tool, but as a merchant you should be aware of the pitfalls and obstacles you can encounter while using it. Stay on top of issues like this, and you can avoid any potential long-term harm to your SEO and consequently your business.

What to do if You Get Scammed

If you do make the mistake of clicking on a link spread via a clickjacking scam, follow these easy tips to lessen the damage:

  • Check your Facebook news feed and remove any offending links that you might have spammed out to your friends.
  • Hover your mouse over the top right hand corner of the post and you should see a small “x” which will allow you to remove it.
  • If you entered your mobile phone number, you should keep a close eye on your cellphone bill and notify your carrier to prevent bogus charges from stinging you in the wallet.
  • Remember to be wary of any suspicious links. If you really want to watch a video chances are that it’s available for free — without you having to complete any surveys — on legitimate video sites like YouTube.

Facebook logo

Going forward, it’s essential that you stay informed about the latest scams spreading fast across Facebook and other internet attacks. Keep following The Official Merchant Services Blog, or the Host Merchant Services Facebook Page, as we routinely update both with the latest news and information on any tech industry issues that affect businesses and merchants.

Adscend Denies Clickjacking

According to this Computerworld article, Adscend Media has denied the allegations filed against them. The company said in its own statement responding to the filing of the two lawsuits, “At no time did we engage in the activity alleged in the complaints.”

The article also states that Adscend is pointing the finger at its own affiliates, claiming their customers shoulder the culpability: “Adscend is hired by advertisers that pay the company each time someone clicks on their page or advertisement. Adscend in turn often hires affiliates to drive traffic to the sites. It’s those affiliates that Adscend is now pointing a finger at. ‘We are undertaking an investigation to determine whether any of Adscend Media’s affiliates engaged in the activity alleged by the Attorney General’s office and Facebook. If they did, we are fully certain that the activity was conducted without the company’s knowledge,’ the company said in its statement.”

Adscend Media LLC Logo

The Washington Attorney General’s office doesn’t buy that claim and replied in the suit that: “Defendants create and provide their affiliates with technology that is designed to deceive Facebook users into visiting websites that pay defendants for the referral traffic. Defendants encourage and pay their affiliates to create Facebook pages that are titled and designed to ‘bait’ users into visiting other websites.”

Top Free Online Shopping Carts

Today The Official Merchant Services Blog shifts its focus to the E-Commerce industry — specifically some tips we’ve found online to help small businesses with their e-commerce solution.

An article written by Nova Scotian Vangie Beal details the ins and outs of ten open source online shopping carts that are available to merchants or really anyone who wants to sell things on the internet. Beal’s been covering small business, e-commerce and internet technology for more than a decade with her writing. You can find the original article here.

E-Commerce has become an integral part of the economy throughout the world. Shoppers have embraced online shopping as part of their normal shopping routine. So businesses have responded by jumping into e-commerce and providing those consumers with competitive options that focus on the convenience that can be had with the click of a few buttons — the classic clicks vs. bricks debate is showing that clicks beat bricks.

So what do Merchants need to know about E-Commerce to get started?

Step One: Get A Payment Processor

The first step is something Host Merchant Services can handle — payment processing. Merchants need to accept payment in the form of credit cards and debit cards to stay healthy and viable as a business. So merchants need to incorporate payment processing solutions both in their brick and mortar stores as well as on their website with their online shopping solution. Host Merchant Services provides merchants with these options — along with free equipment and a guaranteed low rate that will save them money.

So step one in setting up your e-commerce business is to get a merchant account, with the services Host Merchant Services provides.

Image for Host Merchant Services article on credit card processing

Step Two: Your Online Shopping Cart

Now that you’ve got a merchant account set up and are reedy to process payments online, step two is to get an online shopping cart for your website. As Vangie Beal says in her article, “When shopping for your own e-commerce shopping cart software the most important aspect toconsider is how well the cart software meets your business objectives.”

The shopping cart has to be customizable so that you can alter it to fit your business needs. It also needs to be able to fit your branding so that the shopping cart melds seamlessly with the rest of your website. It needs to be flexible so that as your business grows, your online shopping card and ability to process payments online can also grow. It needs to be secure and it needs to support industry security standards such as PCI compliance.

You can read about PCI Compliance Standards in the Host Merchant Services Article Archive.

We provide a PCI FAQ here. 

We provide a step by step guide on PCI Compliance here.

PCI Compliance

Open Source Shopping Cart

Vangie Beal’s article discusses the top 10 free or Open Source shopping carts. Beal says “Open source shopping carts are an attractive option. Storeowners might look to open source e-commerce software because it will typically deliver the features and tools to manage a product catalog on a website without the hefty licensing fees that come with proprietary or off-the-shelf packages.”

Continue Reading – Top Free Online Shopping Carts, Part 2

the durbin amendment

Durbin Amendment Back In the News [2023 Update]

The Official Merchant Services Blog returns to a topic that it covered thoroughly throughout 2011: The Durbin Amendment. With the Stop Online Piracy Act getting most of the headlines lately, Durbin Amendment’s continued impact on the payment processing industry has gone into stealth mode. Until today that is. Stick with us as we offer a whirlwind roundup of all things Durbin related.

Bank of America Took a Beating

We’ll start off our tour Durbin tidbits with this article by ABC News. Apparently Bank of America took a substantial hit from their plan to charge $5 per month to use debit cards. According to the article: “Bank of America’s failed plan to impose a $5 monthly debit card fee led to a 20 percent increase in closed accounts in the last three months of 2011 and a public relations headache.”

The article quotes Bank of America CEO Brian Moynihan as saying, “yes, we had some impact from the $5 debit fee. That’s why we made a decision to reverse it.”

It wasn’t all bad news for Bank of America though, as the bank reported earnings of $2 billion in the last three months of 2011, up from a net loss of $1.2 billion in the same period a year ago, boosted in part from a one-time gain on the sale of China Construction Bank.

Small Lenders Strike it Big

The next little bit of Durbin aftermath comes from this article by NACS online. As was seen in the Host Merchant Services in-depth analysis of the legislation, The Durbin Amendment only applies to lending institutions with assets over $10 billion. Smaller banks and credit unions are exempt from the Durbin Amendment. As a result of being exempt, a Wall Street Journal report cited by the NACS article states that these institutions have been “collecting fees that are often three times those imposed on cards by large banks.” 

For comparison, the article says: “The WSJ notes that a $100 sweater purchased with a debit card would incur a fee of 95 cents on a card issued by a smaller bank and only 26 cents for those issued by big banks. “

The article also suggests that banks face further uncertainty by April 1, 2012, when “all U.S. banks and credit unions must offer retailers more choices of companies used to process debit card transactions, a move that is expected to lower interchange fees further.”

New Target: Credit Card Swipe Fees

Time Magazine Online Feature Moneyland reports something that Host Merchant Services has already touched on before in The Official Merchant Services Blog — that Credit Card Swipe Fees may be the next target of legislators and financial reform. From the Time article: “There’s another interchange fee fight in the offing — this time over credit cards. According to CNBC, equity analysts who cover the financial sector have expressed worry that ongoing litigation involving several major banks could lead to a cap of 0.5% on credit interchange fees — one-fourth of what’s currently charged — potentially dragging down bank earnings. If that happens, consumers who are used to generous credit card rewards programs complete with double miles, accelerated earnings, and big sign-up bonuses might get a rude awakening.”

The Official Merchant Services Blog on December 13, 2011 covered the topic of a Credit Card Swipe Fee. In that blog we wrote: “the plan would end up working much like the Durbin Amendment has worked. Where the idea of reform would get overshadowed by how banks and credit card companies reacted to the law. There would be some shifting, so in that sense the reform would cause change. But that eventually the burden for paying for any losses that banks and credit card companies get forced into through reform would end up squarely on the shoulders of the consumers.”

The Time article notes something that Host Merchant Services already pointed out regarding a Credit Card version of the Durbin Amendment — Banks would take another huge hit because Durbin has language that freed up banks and merchants to market and promote options to the consumer directly. In short, Durbin’s language freed merchants up to promote credit over debit. And because of that, a lot of merchants did just that as Banks offered new programs to make credit the more attractive choice. Subsequent changes that would now penalize Banks for doing that would create a lot of negative momentum for Banks and added onus for consumers who get stuck with no good choices overall.

New Hampshire Law

This article from credit.com reveals that one state legislature is already making moves to see a Credit Card Swipe Fee Cap become reality. As the article states: “A piece of legislation introduced in the New Hampshire House of Representatives, House Bill 1319, has drawn some attention for the way in which it would drastically alter the credit card landscape between businesses and payment processors. The law will limit the amount banks chartered within the state are able to charge businesses for processing credit card transactions to just 1 percent of the total purchase value.”

The article goes on to state that many businesses pay costs that range from 0.67 percent of the transaction’s value to 4.76 percent and that a MasterCard spokesperson told the Nashua Telegraph that the average 1.75 percent.

Cash Still Rules Everything Around Me

Our last news brief on the topic of the Durbin Amendment and swipe fee caps is a little different. This article from the Huffington Post shows a study that reveals cash is still king. The gist of the article: “More than three-quarters, or 79 percent, of consumers said they made a cash purchase in the last seven days, according to a report released on Tuesday from Javelin Strategy & Research, a market research group for financial services. Compare that to about 65 percent of credit and debit cardholders who say they swiped their plastic in the last week.”

The article suggests that this is a consumer reaction to card swipe fees. The article states that consumers are choosing to pay for items with cash to avoid fees on small, everyday purchases. The convenience of plastic gets overrun by the savings consumers perceive they get from going back to cold, hard cash. The study indicates that cash is replacing debit for small purchases, and credit is replacing debit for big purchases and the Durbin Amendment’s lasting legacy may simply be that it pushes Debit out of the consumer’s arsenal of payment options.