Every time you accept a credit card payment, you lose money. Let’s say you take a $100 payment. The $100 doesn’t go to your bank. With the processing fees explained, we know that the banks, card networks, and your processor all take a cut. Knowing who takes how much is the first step to lowering the cost.
Credit card companies charge merchants varying fees. According to NerdWallet, in the United States, the all-in fee (the total cost to merchants) falls between 1.5% and 3.5% of the total sale. Your fee will depend on which card is used, the type of sale, your industry, and the prices you set. This article has each credit card processing fees explained with the latest numbers from 2026. Each number is referenced.
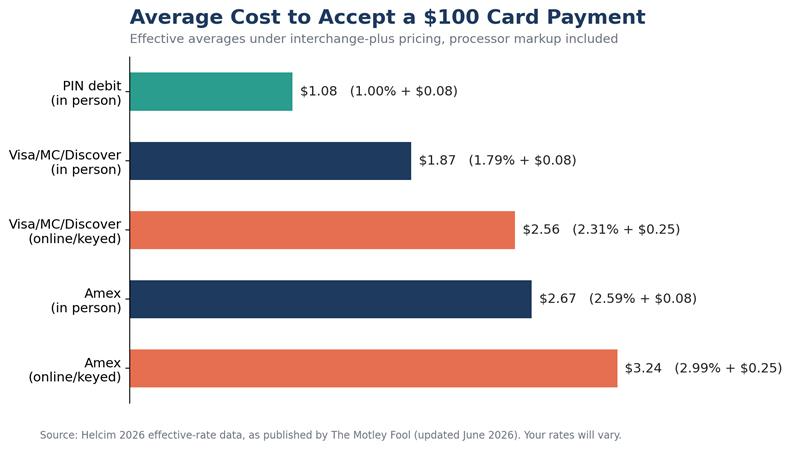
Data can be extremely useful in comparing rates, although they can vary widely. Helcim, a payment processor, lists average rates for in-person transactions for Visa, Mastercard, and Discover at 1.79% + 8 ¢. For keyed-in transactions (online and over the phone), rates are 2.31% + 25 ¢.
Amex is more expensive, according to Helcim’s data. In-person transactions are 2.59% + 8 ¢, and keyed-in transactions are 2.99% + 25 ¢. PIN debit, however, is lower, at 1.00% + 8 ¢. All rates listed should be treated as averages, not guarantees. Your mix of cards can change the rates, for better or for worse.
Flat-rate companies post set prices, which are easy to compare, but which can change at any time. The following table shows published U.S. rates as reported in 2026.
| Provider and plan | In person | Online | Source |
| Square (Free plan) | 2.6% + 15¢ | 3.3% + 30¢ | Square published rates, via NerdWallet |
| Square (Plus / Premium) | 2.5% / 2.4% + 15¢ | 2.9% + 30¢ | Square published rates, via NerdWallet |
| Stripe (standard) | 2.7% + 5¢ | 2.9% + 30¢ | Stripe pricing page, via NerdWallet |
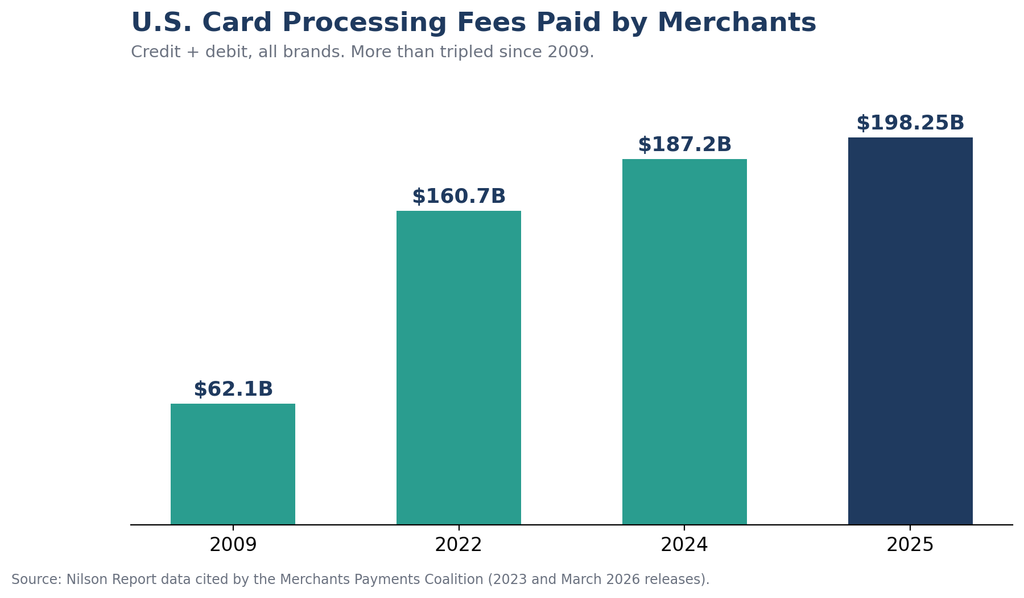
Merchants pay large card fees. In 2025, approximately $198 billion was paid by U.S. merchants in credit/debit card processing fees, as per the Nilson Report, the data cited by the MPC (Merchants Payments Coalition). According to the same MPC release, $118.8 billion of that 2025 total was made up by Mastercard and Visa credit cards. Debit card fees came to more than $40 billion. For many merchants, these fees are the highest operating cost after labor.
CMSPI estimated swipe fees at $236.4 billion for 2024. Nilson put 2024 swipe fees at $187.2 billion. CMSPI reports that their estimate includes interchange, network, and processing fees. The trend is undeniable.
The rapid growth in the use of rewards cards, and in particular premium cards, has significantly increased average interchange fees, and the direction is undeniably up. The average combined Mastercard and Visa credit card fee has increased from 2.02 percent in 2010 up to 2.36% in 2025, per the Merchants Payments Coalition.
Card fees are made up of 3 main parts. Interchange is paid to the bank that issued the customer’s card. Assessment fees are paid to the card network (Visa or Mastercard, for example). The last, called the markup, goes to the processor. The card industry sets the first two fees. Usually, the last, the markup, is open for negotiation.
Interchange is by far the largest piece. It’s estimated to be between 70% and 90% of processing costs. These rates are set by card networks. The issuing banks collect them. These rates differ based on the type of card, how the card is accepted, and the merchant category.
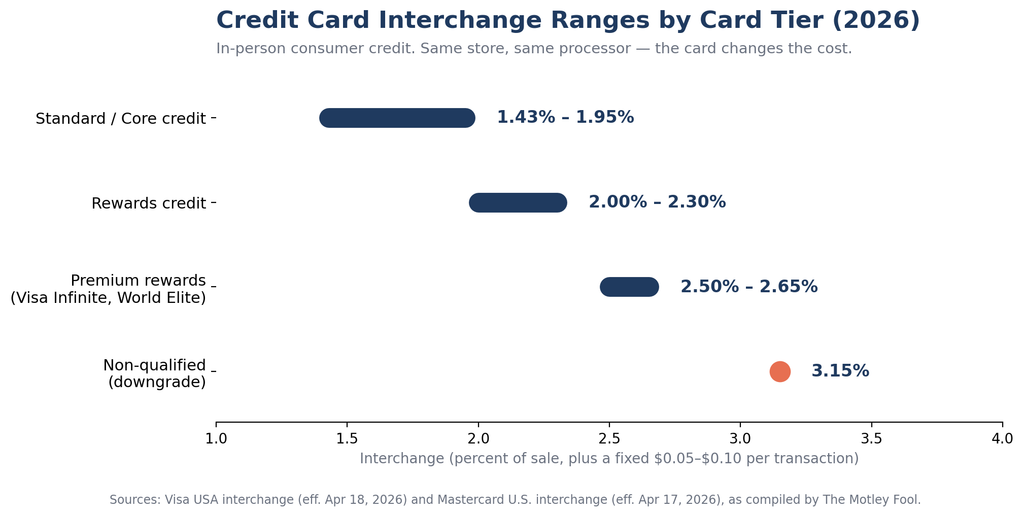
The difference in rates by 2026 is displayed in the schedules. An example from Mastercard’s Merit I rate from 04/17/2026 charges 1.95% + $0.10 for a Core consumer card. The same program for a World Elite card would be 2.60% + $0.10. Visa’s Retail Credit Performance Threshold I rate for the same time period would charge 1.43% + $0.10 for a Traditional Rewards card and 2.30% + $0.10 for Visa Infinite. These examples were compiled by The Motley Fool from published schedules of the card networks.
Sometimes sales are processed as ‘non-qualified’ transactions. This is the case when card-present transactions lack required data. Non-qualified rates set by Mastercard and Visa are 3.15% + $0.10. The card networks review rates in April and October.
Assessment fees go directly to the card brands. These are a small fraction of interchange fees. Industry data shows Mastercard and Visa assessments at about 0.13% to 0.165% of the sale, and small per-transaction assessments. Discover Card publishes a 0.13% card brand assessment and a $0.0195 data usage fee per transaction. Assessments are similar to interchange fees and are not negotiable.
Markup is how your processor recoups its costs for service. These costs consist of technology, support, risk management, and profit. It may appear as a percentage, a per-transaction fee, a monthly fee, or a combination of all three. This is where providers most distinctly differ.
Published markups provide reference points. As reported by Merchant Maverick, Helcim and Host Merchant Services card-present pricing are interchange plus 0.20% – 0.25% + $0.09 – $0.10. As reported by The Motley Fool, Helcim’s published examples of interchange plus markup for transactions done in-person are 0.40% + $0.08, and for transactions done online are 0.50% + $0.25. Your quote will depend on the level of risk your industry presents, and your transaction volume.
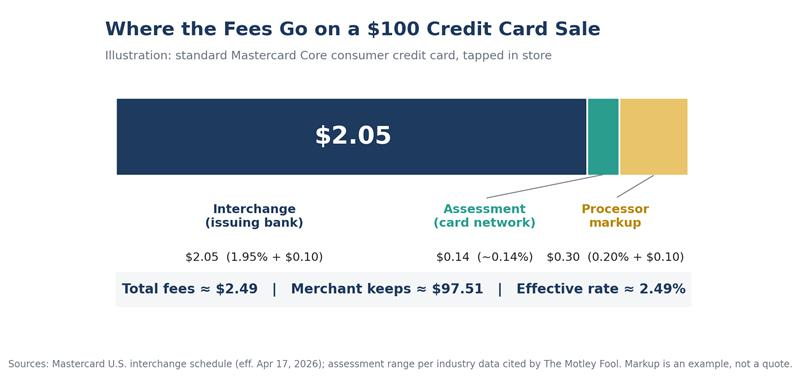
We will review a single sale to illustrate our example. Imagine a customer taps a standard Mastercard Core credit card for $100 at a retail store. Using Merit I, the interchange rate would be $2.05 (1.95% + $0.10). Network assessment would be approximately 0.14%, adding another $0.14. Lastly, a sample processor markup of 0.20% + $0.10 would add $0.30.
The total cost would be $2.49. You keep about $97.51. Again, this is an illustrative example and not a quote. A higher markup, rewards card, or online sale would increase the total cost.
Prices for the same product can vary depending on the situation, and two processors can charge different prices for the same item. The following are the most important factors that contribute to this.
Card Type
In general, debit cards cost less than credit cards. Basic credit cards cost less than reward cards. Visa Infinite and World Elite Mastercard cards, premium cards, are on the higher end of the cost scale. Business and Corporate cards have their own cost structures.
In-Person vs Online Sales
Card-Present transactions are less expensive than Card-Not-Present transactions (Phone, keyed, or Mail Orders.) Online sales increase the risk of fraud and chargebacks. Interchange is higher for Card-Not-Present transactions. The Motley Fool estimates that Card-Not-Present transactions increase cost by 0.40% to 0.50% compared to Card-Present transactions.
Industry and Merchant Category
Networks, such as Mastercard and Visa, price according to each Merchant’s Category Code. Fuel Merchants and other service industry Merchants have their own pricing tiers. Visa charges a rate of 1.15% + $0.25, capped at $1.10, per their April 2026 schedule, for fuel transactions. Other high-risk industries, such as pawnshops and payday lenders, have higher markups and reserve requirements.
Sales Volume and Ticket Size
Very large merchants can qualify for lower volume tiers. Supermarkets with $6 billion or more in annual volume can qualify for a lower Tier 1 rate of 1.15% + $0.05. A fixed fee of $0.30 represents 6% of a $5 sale or 0.3% of a $100 sale. Small-ticket merchants should monitor per-transaction fees.
Card Network
Each one has its own schedule. American Express is usually the most expensive one. In 2026, Helcim data showed that Amex in-person transactions cost an average of about 2.59% + $0.08. For Visa, Mastercard, and Discover, it was 1.79% + $0.08.
Different regulations apply to debit cards. Interchange fees were limited by the Durbin Amendment for debit cards issued by banks with over $10 billion in assets to 21¢ plus 0.05 percent of the amount transacted. These banks can charge an additional 1¢ to prevent fraud. Smaller banks and credit unions are exempt from this amendment.
There is a large disparity. The Federal Reserve gathered information for 2023 and it indicated that the covered issuers charged between $0.22 and $0.24 per transaction, and the exempt issuers charged between $0.50 and $0.52 per transaction. For a $100 purchase, using a debit card would cost just a fraction of what a credit card costs.
There is ongoing review of the rule. The North Dakota Federal Court’s decision to vacate the debit interchange rule in August 2025 is stayed pending appeal. A proposed amendment by the Fed in 2023 to lower the cap to 14.4¢ plus 0.04% is yet to be effected, and, for now, the cap remains at 21¢, according to recent reviews.
How you price your services impacts your description of those services. Interchange and assessments are the same across processors. How they bundle markup is what’s different. There are four major models.
Interchange-Plus Pricing Model
Here, you pay actual interchange and assessments and a fixed markup. The markup is a separate line item. Therefore, comparison shopping is simple. It is commonly used by steady volume businesses.
Flat-Rate Pricing Model
You pay a single rate on all or most cards. Example processors are Square and Stripe. A flat rate makes budgeting simple. However, if a customer pays with a low-cost debit card, you pay a higher markup than necessary.
Tiered Pricing Model
Selling prices are separated into qualified (lowest), mid-qualified and non-qualified (highest) tiered sales. Which tier a sale goes to is at the discretion of the processor. This makes your true costs hard to see. The Motley Fool calls it the least transparent model.
Subscription or Membership Pricing Model
You pay a fixed monthly fee, interchange, and a small per-transaction fee. Motley Fool also claims per-transaction fees range from $0.05 to $0.15. It works well for merchants that process $10,000 or more in a month.
| Model | How it works | Typical fit |
| Interchange-plus | Actual interchange and assessments plus a fixed markup | Most businesses that want clear statements |
| Flat rate | One bundled rate on most transactions | Low-volume or new businesses that value simplicity |
| Tiered | Sales grouped into qualified, mid-qualified, and non-qualified rates | Hard to audit; compare carefully |
| Subscription | Monthly fee plus interchange and a small per-sale fee | Higher-volume merchants |
Source: model descriptions based on The Motley Fool and Helcim (2026).
Merchant account providers charge per-sale fees, monthly fees, batch fees, statement fees, gateway fees, and annual fees. Some charge early termination fees. Host Merchant Services charges a $0.20 batch fee, but does not charge early termination fees. Read the entire fee schedule to fully understand what you will pay.
Chargebacks can be expensive, and each dispute brings a fee in addition to the loss of a sale. Clear and accurate billing descriptors, signed receipts, and good records help eliminate chargebacks.
The fee-to-sales ratio, aka the effective rate, shows how much you paid for each dollar of card sales, and can be calculated by dividing fees by card sales and multiplying by 100. Therefore, for a merchant who incurred $300 in fees for card sales of $10,000, the effective rate would be 3.00%.
Check this number every month. Sudden changes in this number indicate a change in rate or a new fee. Also, this helps you level the playing field when comparing quotes. Effective rate benchmarks can vary by industry. As a general benchmark, 1.5% – 2.0% is a reasonable effective rate for the average card-present retail business, but effective rates for online retailers can be significantly higher.
There could be changes to credit card fees in the next few years. In November 2025, Mastercard and Visa reached a revised settlement with a class of about 12 million U.S. merchants. A federal judge granted preliminary approval to the settlement in June 2026. There will be a final approval hearing in November 2026. Meanwhile, various merchant groups have objected to the settlement, and it is expected that there will be appeals. (Payments Dive)
According to Payments Dive and America’s Credit Unions, if the settlement receives final court approval, the following provisions would be implemented:
It should be noted that the average effective interchange rates would be lowered by 10 basis points. The savings would depend on the particular credit cards and the industries involved. Also, Congress continues to consider the Credit Card Competition Act. That would require large banks to allow credit card routing over a second, unaffiliated network.
Ask for an interchange-plus quote first, then compare markups side by side. Because interchange rates and assessment fees are the same across the board, savings happen by reducing markups. High processing volume and a clear history of processing pay also help reduce rates.
Next, reduce costly downgrades. The card-present terminals should be chip-and-tap capable. The merchant should send complete data for card-not-present transactions. B2B transactions may qualify for better rates by sending level 2 or 3 data with the transaction.
Merchants can also steer customers to less costly payment methods. Debit and ACH transactions can cost less than credit transactions. Surcharge and cash discount programs are two ways merchants can recoup or eliminate transaction fees. Laws vary by state, and rules also vary by card brand. Rules to protect merchants and help them make an informed decision vary by state and should be reviewed before beginning the program. Merchants also should review their processing statements to help them identify unauthorized fees.
How much do credit card companies charge merchants? Credit card companies charge between 1.5% and 3.5% per sale, according to NerdWallet. That cost is split into three parts: interchange, assessment, and markup.
Merchants cannot change interchange and assessment fees. However, merchants can control the markup fees charged by processors. You can lower the markup through negotiations. Also, you can ensure better pricing by opting for a better pricing model and ensuring a lower rate through tracking.
In short, improvements on small gains can really benefit businesses.
According to NerdWallet, most merchants pay between 1.5 and 3.5 percent per transaction. Average credit card processing fees were about 1.79 percent plus $0.08 in person and 2.31 percent plus $0.25 online for Visa, Mastercard and Discover in 2026, according to data from Helcim. Fees for Amex and rewards cards were typically higher.
Yes, either through surcharges or cash discount programs. However, there are state laws, card network rules and provisions of the recent Visa-Mastercard settlement that dictate and restrict how merchants can surcharge.
In-person payments have less risk for fraud, and thus, lower interchange fees. Online and keyed sales, where the card is not physically present, carry a higher risk of fraud. The Motley Fool estimates the difference between online and in-person payments to be between 0.40 and 0.50 percent.