Tag Archives: mobile payments

Android Phone Now Takes Payments

Host Merchant Services finally gets to make this announcement official: All mobile payment solutions the company offers now feature both iPhone and Android compatibility.

On February 28, 2012 Host Merchant Services teased through its Facebook Page that it would have big news regarding HMS and Mobile Payments in March. But technical difficulties with the full release of Payfox’s Android solution held the news back until today. In the Android Marketplace, Payfox is now listed and available for download. You can see the listing here.

The App has been on the Android Marketplace since March 21. But now the rest of the support is in place to get the app working. The final piece of the puzzle was the card reader — UniMag II, Two-Track Secure Mobile MagStripe Reader. The device is a two-track, encrypted magnetic stripe reader that works with a wide variety of mobile platforms, including Apple, HTC, LG, Motorola, and Samsung devices. Use your mobile device to read credit cards, signature debit cards, gift cards, loyalty cards, driver’s licenses, and ID badges. The UniMag reads up to 2 tracks of information with a single swipe in either direction, providing superior reading performance for your mobile device.  A merchant account is required to accept credit card transactions.

Host Merchant Services image of the Unimag II.

You can download the specs from the UniMag II data sheet right here. These are the Android devices supported by the reader:

  • HTC Aria
  • HTC Desire Z
  • HTC Eris
  • HTC EVO 4G
  • HTC EVO Shift 4G
  • HTC G2
  • HTC Hero
  • HTC Incredible
  • HTC MyTouch 4G
  • HTC EVO 3D
  • HTC Nexus One
  • HTC Incredible 2
  • HTC MyTouch 3G Slide
  • HTC MyTouch 4G Slide
  • HTC Thunderbolt
  • HTC Merge
  • LG Optimus T
  • LG Revolution
  • Motorola Droid 2
  • Motorola Droid X
  • Motorola Droid Pro
  • Motorola Milestone
  • Motorola FlipSide
  • Motorola Atrix
  • Motorola Droid 2
  • Motorola Droid 2 Global
  • Motorola Droid Bionic
  • Motorola Droid 3
  • Samsung Captivate
  • Samsung Droid Charge 4G
  • Samsung Epic
  • Samsung Epic 4G
  • Samsung Fascinate
  • Samsung Nexus S
  • Samsung Replenish
  • Samsung Infuse 4G
  • Samsung Continuum
  • Samsung Galaxy SII

Please Note

When you go to the Google Play Market and search for PayFox using your Android/Droid phone, the PayFox application will only display for those devices for which the application itself is compatible.

Host Merchant Services image for difference between Android phones and Star Wars Droids.

Red 5 Standing By

Our friends at Transfirst also wanted to offer some clarification about the use and licensing around the word Droid:

“Android and Droid are often used interchangeably when referring to ever-growing & increasingly popular line of smartphones that run on Google technology. The difference, for most purposes, is one of legal definitions and intellectual property. Android simply refers to the operating system and software that powers phones built by any of number manufacturers, including HTC or Motorola, and that run on any of the major carriers.

Droid, on the other hand, is a term coined and owned by LucasFilm Ltd., the licensing rights for which Verizon had to purchase in order to brand their specific line of Android Smartphones.”

In short, Androids are phones, and you can now use them to swipe payments. Droids are what Jawas scavenge. Though I’m sure the Jawas will happily accept mobile payments from all you moisture farmers out there. Ootini!

Payfox for Android Coming Soon

On February 28, 2012 Host Merchant Services teased through its Facebook Page that it would have big news regarding HMS and Mobile Payments in March. The Official Merchant Services Blog is here to give you that big news.

Sort of.

The news is that Payfox will be usable for Android phones as well as the iPhones it has been compatible with for the past couple of years. Unfortunately that news is coming piecemeal. The announcement was slated for late March. But the project isn’t quite ready for launch. According to an ISS Bulletin from Transfirst:

“Although PayFox Android is currently not yet available … We are expecting a formal release in the next couple of weeks. “

In anticipation of the pending release, there is a new “PayFox Droid card reader” option opened up in Transfirst’s ELAPP™ software. The option is there, but the functionality isn’t ready yet. So it’s just a teaser of what’s to come. ELAPP™ is an innovative virtual application system that walks users through the merchant boarding process with intelligent rules for data entry.

Host Merchant Services E-Commerce Mobile Payments image

That’s not the only teaser, however. In the Android Marketplace, Payfox is now listed and available for download. You can see the listing here.

User tests by the staff here at The Official Merchant Services Blog show that the download works. And the app will then show up on your Android phone. But there is no reader equipment available yet and the transactions can’t yet be processed. The App has been on the Android Marketplace since March 21.

So all we’re able to confidently report right now is that the pieces for Android appear to be in place, just not fully ready. We will keep you posted with any updates or breaks in this story. Once it is ready, Host Merchant Services will be rolling out a detailed press release discussing the addition of Android to their already robust iPhone capability and how it relates to their full e-commerce service package that it offers merchants.

Merchant Services 2012 Events

2012 is heating up and the payment processing industry is getting things moving. Today The Official Merchant Services Blog reports on a major event that just happened, and brings you all the details on a major event that is coming up in the credit card processing industry.

What You May Have Missed

The GSMA Mobile World Congress just took place in Barcelona, Spain. The event is the combination of the world’s largest exhibition for the mobile industry and a conference featuring prominent Chief Executives representing mobile operators, device manufacturers, technology providers, vendors and content owners from across the world. It ran from February 27 to March 1 and featured a lot of push from Android devices — including the latest and greatest gadgets and apps from the Samsung Galaxy brand. But VeriFone, the credit card transaction terminal making company that Host Merchant Services provides free equipment for its customers from, also dropped a major announcement at the event.

This press release, carrying a byline directly from their event booth at the Mobile World Congress, states VeriFone announced: “The PAYMEDIA Universal Acceptance Platform (UAP), a complete suite of services and software that enables Mobile Network Operators (MNOs) to manage mobile wallet acceptance at merchant systems.”

Host Merchant Services promotional banner for the Mobile World Congress

This is VeriFone’s mobile payment system. The UAP is designed for mobile-network operators to offer merchants to accept digitall walled applications. Customers with Near Field Communications (NFC)smartphones with digital wallets will pay for items by tapping their phone near an NFC-enabled terminal. VeriFone offers the MX800 and MX900 series terminals to their Tier 1 retailers (merchants with annual sales exceeding $1 billion). These terminals were already usable with the NFC App Manager VeriFone created for the Google Wallet Trial. So UAP is one step forward for VeriFone giving them the ability to run mobile payments through their own branded applications and their own customers.

This is an interesting devleopment in light of the NFC problems Google and Google Wallet were facing recently. This shows that the allure of Mobile Payments is still very strong for companies. The predictions still center around billions and billions of dollars worth of growth in the next few years. So companies are still making major moves to tap into mobile payment solutions such as NFC.

Host Merchant Services supports VeriFone terminalsThe testing of NFC, however, still continues to be limited. As VeriFone demonstrates, it’s still not ready for the majority of merchants. Tier 1 merchants give a good testbed based on the volume of transactions, but the technology still isn’t being tested heavily in the rest of the marketplace. So the standard knock against NFC still exists: The majority of consumers are still hesitant to accept the payment method due to security concerns. Analysts continue to predict Mobile Payments will explode and the sector will boom, but consumer acceptance still remains an obstacle.

VeriFone states in their press release that they have a plan to address consumer acceptance. “The missing element in MNO’s mobile wallet plans has been the lack of focus on how to provision, integrate and manage wallet and value-added acceptance apps at merchants’ systems,” said Paul Rasori, VeriFone senior vice president of marketing. “VeriFone’s PAYMEDIA UAP bridges that gap in the NFC ecosystem by managing the complexities of mobile commerce acceptance and ensuring a seamless buying experience no matter what wallet, app or program consumers bring to stores.”

  • For more information about VeriFone’s UAP, click here.
  • For more information about the rest of the Mobile World Congress, this blog gives a decent recap.

Host Merchant Services Promo image for the ETA Expo

What Is Coming Up

While you may have missed the Mobile World Congress in Barcelona, fear not — The ETA Annual Meeting and Expo is coming up. From April 17 to 19 the most diverse and comprehensive conference in the payments industry will rock Mandalay Bay Las Vegas. This year’s show brings together more than 3,500 payments professionals and suppliers to the industry for three days annually to provide peer-led education, networking, and one-of-a-kind partnership opportunities. Whether you want to learn more about the payments industry, showcase a new product, or are in the market for a new partner or channel opportunity, you will find everyone and everything at the 2012 ETA Annual Meeting & Expo, from merchant acquirers, financial institutions, payments processors, and alternative payment providers to value-added resellers, prepaid companies, and merchant sales teams. Some of the highlights for this year’s extravaganza include:

  • Opening General Session Keynote Speaker: Guy Kawasaki: Tech industry legend and the original Mac evangelist, Kawasaki will share his irreverent approaches to innovation. Learn how to create your own successful innovations, and. . . generate revenue.
  • 2012 Political Analysis: Charles E. Cook, Jr.: Cook, widely regarded as one of the nation’s leading authorities on US elections and political trends, will provide insight into the upcoming US elections. As an authority on policy-making and politics in Washington, Cook’s perspective on the 2012 political and legislative environment promises to be especially insightful as it relates to the unique challenges and concerns of our industry.
  • Educational SUPER Sessions: If you want to move from ordinary to extraordinary you need the latest and most complete information. Take a deep dive into these four fundamental industry topics at this year’s meeting: Sales, Technology / Products, Regulatory Issues and Social Commerce.

For more information about the expo visit this link.

step forward

1 Step Forward, 2 Steps Back [2023 Update]

step forward

We’ve been covering Mobile Payments here at The Official Merchant Services Blog since the very beginning. In fact, the Article Archive at Host Merchant Services has extensive coverage of the topic as well. It’s just too sexy a topic — everybody loves the allure of gadgets — and too fascinating a financial prediction — folks in the know are predicting Mobile Payments to boom in the billions between now and 2015-ish — to not continually cover Mobile Payments.

But I keep picturing a scene from the 1992 women’s sports movie A League of Their Own in my head every single time I look at the state of Mobile Payments in the U.S. The scene that resonates with me is the one where Marla Hooch — fearsome and uniquely striking power hitter for the team — is about to step into the batter’s box. But she’s getting confused. She steps into the box. Then back out of the box. The reason for her confusion? She’s getting contradictory signals from her Manager and her teammate. One wants her to swing away and unleash the fearsome potential of her staggering offense. The other wants her to play it safe and move the runner over for a better chance to score an efficient run. So there she goes, Marla Hooch, the powerhouse of the league. One foot in the box. Then out of the box. It’s the exact problem Mobile Payments currently faces. The power and potential of what it can do for commerce keeps getting highlighted in story after story, research after research. And then the biggest obstacle it faces keeps getting thrust in front of its face: Security.

Step Out of the Box

Google Wallet, one of the biggest lynchpins in the mobile payment industry’s bid to effectively take hold in the U.S. market was recently plagued by a security problem. This article from ExtremeTech notes the issues that happened to Google and its mobile payment system in a piece that discusses the pitfalls of its beta testing. A pair of bugs forced Google to shut down its pre-paid cards and Google Wallet took a huge hit on the nose in the press. This reinforced the public’s view that mobile payments are a bit scary because people think that their personal information — account numbers, social security information, credit card numbers — will get swiped from them out of thin air. The thought process being that if all they have to do to pay for an item is wave their phone in the air at a cash register, some sneaky net ninja can pluck the data right out of the very same air.

The article sums up the problem: “In the last week, there have been not one, but two exploits that could give a malicious individual access to your Google Wallet mobile payment app on Android. While the first is a root-only hack that Google couldn’t really be expected to plan for, the second affects all Android users and is simple to do.”

It goes on to suggest these bugs popped up due to a core problem with how google beta tests things.

Since that story broke, Google has gone on the offensive, and is now stating that the bugs are fixed. As this cnet article says: “Google has patched a hole in Google Wallet that could’ve allowed someone to access a user’s funds simply by resetting the PIN and using a prepaid card. The company said yesterday it has issued a fix that now prevents a prepaid card from being re-provisioned to another person. It has also restored the ability to issue new prepaid cards following a move on Monday to disable the use of such cards.”

These bugs were a major setback for more than just Google. The Mobile Payments landscape is bubbling with interest but it’s also saturated with variety. There are multiple avenues businesses are considering for their entry point into what research firms like Gartner predict will be big money very very soon. One of those avenues is Near Field Communication (NFC).  The underlying technology of NFC is described as: “Near field communication (NFC) is a set of standards for smartphones and similar devices to establish radio communication with each other by touching them together or bringing them into close proximity, usually no more than a few centimetres. Present and anticipated applications include contactless transactions, data exchange, and simplified setup of more complex communications such as Wi-Fi. Communication is also possible between an NFC device and an unpowered NFC chip, called a “tag”.” 

This is the technology that Google tagged to be their entry into Mobile Payments. And so these bugs are a major hit for Google and NFC as a whole, taking one of the most hyped aspects of Mobile Payments down a peg in the industry.

Step Into the Box

In the midst of NFC taking it on the chin, Visa and MasterCard unleashed its EMV initiative — as The Official Merchant Services Blog reported on February 7. This is, in my mind, the Mobile Payments Marla Hooch being told to step into the batter’s box and knock it out of the park. Visa is invested heavily into Mobile Payments, and is prepared to drag the industry kicking and screaming into the future of profits that are being predicted for Mobile Payments. The EMV initiative hinges on chip technology being attached to cards, and for Mobile Payment evolution also being attached to smart phones. What Visa’s investment in this avenue brings is added security. This is huge. The security advantage addresses the biggest fear people have for mobile payments. Visa, much like Tom Hanks, wants Marla Hooch to get in there and swing away.

Going Sci-Fi

This article from Asia One adds another wrinkle into payment processing, and possibly the future of mobile payments: Biometrics. The article cites The Monetary Association of Singapore (MAS) as researching ways to make Debit card transactions more secure. And one of the avenues of research has been biometrics. This could really lead to a breakthrough in the march towards a cashless society, including the use of smartphones for mobile payments. Having biometric security measures on your phone would work in tandem with the chip technology that Visa is pushing, making both the unit you use to store the information — your phone — attuned to your own physiology; and the transmission of your transactions — the swipe of said phone in the air — attuned to a secure chip. Identity thieves and card fraud masters would be stymied on multiple ends and have to work very hard to stay ahead of that security curve in their mission to steal your information and then your money.

The Bottom Line

So What’s Marla Hooch going to do? It looks like Google is sticking with its plan and dedication to NFC. They sort of have to due to how invested they are into the technology already. And it’s no secret that Visa is very much tied into the future of mobile payments, chip card technology, and payment processing security. Both entities are full steam ahead. And with that much tech and finance industry strength behind the initiatives, Mobile Payments will get its chance to swing for the fences. We look for the Google Bugs to blow over and not really hinder Mobile Payments growth much at all in 2012.

For more information on Mobile Payments you can read from Host Merchant Services:

The Official Merchant Services Blog will continue to keep you up to date on the latest advances in Mobile Payments technology.

Visa Kicks Open the Door for Chip Cards

Today The Official Merchant Services Blog discusses a fascinating new development by Visa in the realm of credit card processing, security, and hopefully Mobile Payment Technology.

Smart cards have been slow in gaining traction, especially in the United States. But now Visa is making moves to drag the U.S. into the chip card realm, kicking and screaming if it has to. A recent article on Credit.com reveals as of December 31, 2011, Visa — the largest processor of both debit and credit card payments — had issued more than 1 million credit cards that use “chip” technology to sore consumer payment information. The article notes that this data is being announced rather quickly in relation to Visa’s August 2011 announcement that it planned to start issuing more EMV — Europay, Mastercard, Visa — smart cards to push the industry toward better security and an easier transition to mobile payments.

What is Smart Card Technology?

A smart card, or chip card, is any pocket-sized card with embedded integrated circuits. These cards contain volatile memory and microprocessor components, are made of plastic,and provide strong security authentication capabilities. Because of these characteristics, the technology is being utilized for credit cards by major card companies like Europay, MasterCard and Visa — garnering the nickname EMV. Visa has begun a major push of this technology because of the benefits the technology provides.

Host Merchant Services image of smart card chip technology

What are Those Benefits?

These kinds of smart cards can provide identification, authentication, data storage and application processing. A single contact/contactless smart card can be programmed with multiple banking credentials, medical entitlement, driver’s license/public transport entitlement, loyalty programs and club memberships to name just a few. Multi-factor and proximity authentication can and has been embedded into smart cards to increase the security of all services on the card. In one fell swoop, this technology can bridge the gap between card-swipe style processing and the mobile payment processing that the industry is striving to move toward. The technology lets virtual wallets and contactless payment happen, increasing convenience for consumers. And then it also boosts security, which is the largest concern consumers have with mobile payments.

The Credit.com article quotes Stephanie Ericksen, head of authentication product integration at Visa Inc. as saying “Migrating the U.S. market to chip will help build an infrastructure for accepting NFC mobile payments, enhance international acceptance and reduce fraud.”

TransFirst Sets Guidelines

TransFirst, Host Merchant Services’ acquirer and one of the premier providers of transaction processing services and payment processing technologies in the U.S., has issued a mandate in response to the EMV push. TransFirst says that Visa will require U.S. acquirer processors and sub-processor service providers to be able to support merchant acceptance of chip transactions no later than April 1, 2013. Visa also intends to institute a U.S. liability shift for domestic and cross-border counterfeit card-present point-of-sale transactions effective October 1, 2015, and for fuel-selling merchants by October 1, 2017.

Many of these dates are long-term projections and would seem to be a little far out there in comparison to the fast-paced results Visa is achieving already with their shift to chip cards.

Host Merchant Services image of a contactless terminal for EMV cards

The Carrot on the Stick

TransFirst explains that Liability Shift is often used as the incentive to encourage acquirers or issuers to move to chip transactions. For magnetic stripe swipe transactions, POS counterfeit fraud is mostly absorbed by the card issuers. But in the EMV shift Visa is pushing, the party that is not chip-capable will be liable for frauds that would have been prevented if the transaction were processed with a chip-on-chip connection.

It would seem that Visa is happy with the fast embracing of their chip transition but are still giving the acquirers and the merchant service providers and the merchants years to implement this fully before holding them liable.

In preparation for Visa’s Accelerated Chip Migration plan, TransFirst will migrate new terminal deployments on the following POS Terminals to chip capable versions of the same devices. Once implemented, non-chip capable versions of these terminals will no longer be available for purchase through TransFirst:

  • Verifone’s Vx570
  • Hypercom’s T4205
  • Hypercom’s T4220
  • Hypercom’s M4230

How Chip Cards Work

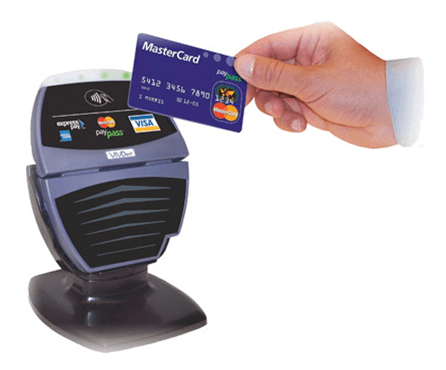
These new cards work in a similar fashion to the cards they are replacing. Users present them when making a purchase and from there the transaction follows the steps detailed in the Host Merchant Services Infographic found here. But the cards are different from swipe cards in some very important ways. Consumers do not swipe these cards. Instead they wave them over a sensor. This is the exact same style of payment that mobile phone based “virtual wallets” look to employ. You wave your smart card across a sensor, or you wave your smart phone across a sensor. Payment made. Visa also plans to allow chip cards to work with PIN codes, bringing debit under the umbrella.

Host Merchant Services image breaking down how chip cards work

The Mobile Payment Connection

Visa is heavily invested in the future of Mobile Payments. Which is not surprising as you can see from Host Merchant Services‘ coverage of the topic in its article archive. Past blogs have noted that the biggest obstacle Mobile Payments face with U.S. consumers is concern about the safety of the transactions. Visa’s hoping that the added security that the chip technology provides will overcome that obstacle and finally tap them into the billions of dollars of revenue that Mobile Payments are predicted to have in the coming years. As Ericksen says in the Credit.com article, “Since announcing our roadmap last year, we have seen strong interest among U.S. issuers large and small to invest in chip technology, as today’s milestone shows.”

mobile payments

Mobile Payments: 2023 and Beyond [2023 Update]

Today The Official Merchant Services Blog updates our outlook on Mobile Payment Technology and the rampant predictions for its success in the near future. We have previously covered the topic with this blog entry on Tuesday, October 18, 2011. The parameters of that blog are still pretty much the current state of Mobile Payments. But there have been some very interesting developments from the end of 2011 and moving into the first quarter of 2012.

Black Friday Boom

The Black Friday business blitz revealed some healthy news for Mobile Payments. According to this article from Seeking Alpha, mobile payments business increased 500% from 2010 on Black Friday. According to the article, PayPal mobile reported the huge increase, coming in at 511% to be exact. PayPal Mobile also noted that there was a 350% increase in mobile shopping on Thanksgiving 2011 when compared to 2010.

According to numbers from the aforementioned IBM research, 17.37% of all consumers used a mobile device on Black Friday to visit a retailer’s site. And 9.73% used a mobile device to make a purchase. The Seeking Alpha article quoted Amanda Pires from PayPal. Pires suggested that this year’s holiday is proving to be the largest mobile holiday shopping season PayPal and eBay has ever seen, and then quoted Pires directly as stating: “The retailers that are taking advantage of mobile shopping are going to win. We expect mobile shopping to continue to be strong throughout the holiday season.”

This is good news for Mobile Payments, as Host Merchant Services research has shown in the past that there have been some bold predictions for growth in Mobile Payments, but that the services were slow in taking hold this year in the U.S. Growth like the numbers cited from Black Friday 2011 should fuel more positive momentum for that consumer payment option.

Host Merchant Services E-Commerce Mobile Payments image

From 2012 Onward

All of this brisk business in the mobile payments sector is indicative of the forecasting that analysts and reporters have been making for the technology. But the obstacle that our Magic 8-Ball suggested hurts the industry still remains: Consumer confidence. There’s still trust issues with mobile payments. This article by Eric Savitz from Forbes really delves into the heart of what we at Host Merchant Services have been saying about Mobile Payments.

Savitz says: “There’s a common thread between these points: there has to be something fundamentally changed about the current point of sale model in order for mobile payments to take off. It’s about added value and convenience to the consumer, and the ability to drive more customers, loyalty, efficiency and lower risk for the merchant and banks and operators involved in the payments process. Think of contactless “tap and pay” credit cards – you may have one in your wallet right now, but you still swipe it anywhere you go. As a consumer, there’s nothing more convenient or inherently better about tapping your card vs. swiping your card if all that matters is making the payment. Would the time spent setting up and configuring a “mobile wallet” be worth it if the only difference at the cash register of Macy’s is that you wave a phone over a terminal rather than swipe a card through one? Doubtful.”

That’s what Host Merchant Services has been saying. It’s about convenience to the consumer. The worries about security are valid. E-Commerce has faced the same problems with security and the same worries. But people have adopted online shopping — as seen with the same Black Friday and holiday shopping season boom in 2011 — to the point where it’s now just a common part of the shopping experience. People can’t even remember back 10 years where online shopping was new, awkward and insecure. It’s just part of their lives now.

And for Mobile Payments to jump off the same type of conversion of consumers has to take place. Convenience will outweigh security concerns and people will just accept the behavior as part of the way they shop. That’s where the Mobile Payments Industry stands right now. On the edge, waiting for the breakthrough that will rocket it into everyday life for shoppers. It has to grow beyond gimmick. Because gimmick won’t carry it forward. It might be easy to do, but as Savitz points out, if there’s no reason to swipe your phone over just using your card in your wallet, people won’t bother.

Small Businesses Susceptible to its Charms

One inroad Mobile Payments are making with consumers is through small businesses. This article from Newsfactor.com delves into how small businesses are seeking mobile payment solutions that free them from reliance on traditional payment solutions. The article discusses how Square has been shaking things up with the changes its made to its business model in 2011, becoming an entire processing solution itself and making its card reader more readily available to merchants. The article then mentions how Gartner Research data shows that the Mobile Payments Industry surged to $86.1 billion in 2011.  The article notes that Square is just one of many viable options that are helping fuel the growth the sector is seeing.

HMSPay

Host Merchant Services recognizes the huge growth potential in this sector of the industry. Beyond their coverage of the latest developments and news that take place in Mobile Payments, Host Merchant Services offers its own mobile payment solution, HMSPay. The solution utilizes a card reader that is attached to a smartphone and an application on the phone which transforms it into a payment processing terminal, complete with signature field and e-mailed receipts.

Host Merchant Services Mobile Payment Solution HMSPay

So What’s Next?

Savitz’ article suggests that the potential breakthrough for Mobile Payments will take place in 2012. And that the catalyst for this breakthrough will be through value added applications of the process. He cites Google Wallet and Isis as showing the most promise in being a catalyst because they both go beyond just having the swipe gimmick and offer “services delivered on top of the payment itself.” He says these additional services will be what prompt consumers to shift into mobile payments. He offers these bullet points:

  • Deals and offers: Highly targeted, relevant offers based on prior buying patterns and current location. Imagine receiving a time-sensitive text message or in-app alert with a coupon to your favorite electronics store after your digital wallet “checks in” that you are within the store.
  • Digital receipts and account information updated in real time to give a comprehensive view of personal and linked accounts while also displaying loyalty rewards status.
  • Real-time, customizable alerts to certify that the purchases being made in an account are valid, based on your phone’s proximity to where the purchase is being made.

So it appears that one promising avenue for the evolution of mobile payments is to essentially make them a virtual wallet “plus.” Something that does more than just allow you to pay with a swipe of your phone. Something that collects the relevant data and helps you manage your shopping right there, at your fingertips. Something that tracks your own shopping trends and makes you aware of deals, then lets you conveniently take advantage of those deals.

It’s a compelling point. Host Merchant Services sees the value in such a transition. The technology works to make the consumer’s shopping experience convenient and comprehensive — something a shopper can’t even consider they could do without in previous years. That’s what happened with e-commerce, after all.

E-Commerce: Review and Preview

The Official Merchant Services Blog begins our second year of blogging with a look at one of our favorite topics: E-Commerce.

2011 saw huge gains for online shopping. As reported in The Official Merchant Services Blog on Cyber Monday, online shopping was strong on Black Friday. IBM research unit Coremetrics stated that 20% more consumers shopped online Black Friday 2011 than did in 2010. The data collected also states that 39% more online shopping happened on Thanksgiving Day 2011. The ease of online shopping is infiltrating the traditional brick-and-mortar retail event and Host Merchant Services‘ analysis of it held true –– sales numbers across the board rose from 2010, so overall Black Friday had a boost for retail, but clicks from e-commerce continue to grow and cut into the sales from bricks.

Also, mobile payments saw a huge increase during the holiday shopping season. According to this article from Seeking Alpha, mobile payments business increased 500% from 2010 on Black Friday. According to the article, PayPal mobile reported the huge increase, coming in at 511% to be exact. PayPal Mobile also noted that there was a 350% increase in mobile shopping on Thanksgiving 2011 when compared to 2010.

The Numbers Keep Coming In

This article by Internet Retailer demonstrates that Black Friday was just the beginning. There were more than 3,000 transactions totaling $141.6 billion in 2011 in the marketing, media, technology and service industries according to data collected by investment banking firm Petsky Prunier LLC. Of those transactions the E-Commerce and digital media segment was the most active, with 1,159 deals valued at more than $44 billion.

All of this activity demonstrates strength in the E-Commerce industry, and suggests that 2012 is a year primed for continued growth and success — which combines with the already rampant predictions of success for Mobile Payments within the E-Commerce industry.

Host Merchant Services Online Shopping E-Commerce Credit Card Payment Processing Image.

Is There A Bubble?

This article from moneycontrol.com asks the question, “Will the E-Commerce Bubble Burst?”

Comparing the recent success to the success of internet companies in 2000 and 2001, the article tries to figure out if the bubble will burst like it did back then for tech companies. The author’s opinion is that the similarities are only on the surface, and that the two situations are vastly different — suggesting that in the end, it’s not a bubble that is going to burst but rather an industry that is going to grow and evolve. The article looks specifically at the E-Commerce sector in India, but does spend time detailing the big picture globally.

Online Shopping is Now Commonplace

To really underscore the potential growth that E-Commerce has in 2012, this article from Daily Deal Media talks about how popular online shopping is becoming with moms. The article cites a BabyCenter survey which suggests that: “71% of moms regularly turn to websites such as shopping engines and review sites to compare prices. Another 56% admit to searching for coupons or digital discount opportunities on a regular basis.”

This is a compelling point in regards to the overall picture of E-Commerce. It has become more and more commonplace in everyday life for shoppers around the world. Mothers are turning to it for the convenience of being able to get shopping done quickly and efficiently, according to the article. And it is just become an ingrained part of our economy, fueling the potential for further growth.

Host Merchant Services E-Commerce Mobile Payments image

Mobile Payments Big Problem

The potential growth for Mobile Payments is huge. But the one thing holding it back in the U.S. is security. Just as online shopping has become more and more commonplace, people have gotten comfortable with making payments online. That brings risk, as phishing scams and credit card fraud has increased. But security standards like the PCI DSS have helped to make the mainstream comfortable with clicking the pay button and giving out their payment information.

Mobile Payments, however, are not quite there yet in terms of acceptance. This article from the Chicago Tribune discusses the looming security issues that the mobile payments market faces. As the article states: “While the first mobile virus dates back to June 2004, risks from hackers remained limited because of the relatively small size of the market. But this has changed with the surge in the smartphone segment, which this year outgrew the PC market, and the new dominance of Google’s Android software. The emergence of mobile payments, which allows shoppers to swipe their phones at a cash register, is whetting the interest of hackers and data thieves.”

The article states that fewer than 5% of smartphone users have security software installed on their device, according to Juniper Research — the same Juniper Research that predicts Mobile Payments will increase to a $670 billion industry by 2015. And a study by Deloitte cited in the article suggests that for companies in the technology, media and telecom sector expect data stored on staff mobile devices to be their biggest security headache in 2012.

Essentially that’s the biggest obstacle holding back the Mobile Payments industry. The sheer convenience the technology brings to the payment industry is extremely powerful and so despite security concerns it continues to be developed and pushed. 2012 will see growth in the industry, despite the security issues. And as consumers get more and more familiar and comfortable with the phone swipe style of payment, the industry will boom.

A List for 2011

And just for fun, here’s a list from Mashable.com detailing who they think were the biggest winners and losers from 2011 in E-Commerce.

  • Their winners include: Amazon, Apple, Wal-Mart and Gilt Groupe.
  • Their losers include: Barnes and Noble, HP, Netflix and Sony.

Click the link to read why each company made the list.

Customized E-Commerce

The Official Merchant Services Blog switches its focus today back to e-commerce. After the boom in mobile phone usage this past weekend from Black Friday on through Cyber Monday, it’s becoming increasingly clear that smartphones and mobile internet users are becoming very important parts of the  e-commerce industry. As such, businesses that utilize e-commerce need to consider including the mobile phone element in their online shopping capability.

This increase in the importance of mobile usage –– most notably mobile payments –– is leading many e-commerce businesses to develop mobile apps. These mobile apps let those businesses customize their service and stay in touch with their consumers who prefer to connect via mobile networks. The trend is moving e-commerce mobile solutions away from the traditional Wireless Application Protocol (WAP) sites. That’s a paradigm shift in the industry. E-commerce businesses are developing and designing their own applications –– or at the very least branding their own versions of mobile apps.

Applications Over Surfing

E-commerce leaders are finding out that users prefer using a mobile application instead of going to a business through their mobile phone’s web interface. This article from The Hindu Business Line quotes Amarjit Batra of OLX.in as saying: “We found users more comfortable in having a mobile application than opting for mobile web search or using WAP sites.”

This change in e-commerce puts an emphasis on having payment gateways accessible across different mobile platforms. To put it simply, a business with a mobile payment aspect to its e-commerce presence needs to have a mobile payment system compatible with Android, iPhone and Blackberry.

Host Merchant Services is staying ahead of this curve, offering a series of customizable e-commerce solutions to its merchants. Included in that package are mobile payment services apps that work on both iPhone and Android. HMS keeps its options flexible so that its merchants can tap into the rapid growth in mobile payments.

Mobile is Key to E-Commerce

This growth is looking like a trend for businesses in the burgeoning mobile payments market. Juniper Research is often cited as predicting the Mobile Payment Industry is going to blossom from a $240 billion industry to a $670 billion industry by 2015. This makes it very helpful for businesses to recognize consumer behavior in terms of their mobile device usage. Google Analytics provides a great free source of tracking for e-commerce merchants to monitor traffic from mobile devices. That’s a great first step for a business to determine what kind of mobile payment option or customization might be needed for the e-commerce a merchant is already doing. At least get an indication if there is a need for mobile payments or a customized and branded mobile app for your business.

The move towards individual businesses dabbling in their own branded app development also extends from the fluid nature of the industry as it grows and evolves. With so many different companies –– Google, PayPal, Visa to name some of the giants –– all coming up with their own variation on mobile payments, the flexibility to customize and brand their own version of mobile payment services is extremely important for all players involved in the process. This includes merchants themselves as well as merchant services providers.

Stitching it all Together

Besides just crossing platforms between the major mobile carriers, the applications being developed need to integrate web services and payment options into the solution. Essentially the goal is to make e-commerce seamless for mobile users as well as internet users. The whole range of potential business needs to be taken into account with a business’ e-commerce package. And that’s why the focus is on customization.

Sachin Singhal, e-commerce expert for Naaptol, underscores this in the Business Line article when he told them: “A mobile app is more user-friendly than having a WAP site. However, integrating the payment window with it makes the application complete.”

Host Merchant Services has been aware of this trend from its beginning. And that’s why the company offers powerful tools to its merchants that help them complete this integration –– giving them an across the board e-commerce solution that caters to mobile users and internet surfers alike. HMSPay and HMSExpress are both important elements that allow the company to capitalize on this trend and give online businesses the flexibility they need to cater to the huge growth happening in mobile payment sector.

mobile payments

Magic 8-Ball on Mobile Payments [2023 Update]

Magic 8-Ball on Mobile Payments: Outlook Hazy, Ask Again Later

Mobile Payments are getting a lot of press right now and are being heralded as the future of commerce. There are quite a few media sources playing the role of prognosticator, tagging Mobile Payments as a billion-dollar boom waiting to explode. But as we creep right up on the 2011 holiday shopping season, the actual impact of Mobile Payments is still short of its predicted potential. So today The Official Merchant Services Blog is going to take a brief look at Mobile Payments, shaking the topic up vigorously and seeing what the Magic 8-Ball (a potential holiday gift in itself) has to say about the whole thing.

Sunshine and Positivity

One of the most commonly quoted statistics about Mobile Payments can already be found in Host Merchant Services Article Archive in a story about Mobile Payments and how bright the future is: A Juniper Research study that predicts the value of all mobile money transactions will grow from $240 billion to $670 billion. That’s a hefty number and makes for sexy copy. Other stats cited often from the Juniper Research study are that digital goods will make up nearly 40% of the market that the $670 billion figure is drawn from. And that Asia, Western Europe and North America will make up nearly 75% of the entire market for those goods.

So that’s the good news. What’s the bad news?

Two Big Problems

The bad news is mobile payments haven’t taken off as quickly in the U.S. as the media reports suggest. The Juniper study sets things in four years in the future. So the boom is still very much capable of happening. But two things are holding Mobile Payments back in this country:

  1. The technology isn’t developed fully yet.
  2. Security issues scare consumers.

The technology is sort of all over the place right now. You have a variety of different ways to process a mobile payment. And the biggest competitors in the industry (Google, PayPal, Amazon.com, MasterCard, Amex, Visa) are all still racing to outdevelop each other. Google Wallet is still not fully there yet. Near Field Communication (NFC)  is still only being tested on a small scale in the United States. The phenomenon simply hasn’t taken root.

Security Concerns

Mobile Payment Security Concerns

The other major problem holding a Mobile Payment boom back in the U.S. is security. People are already worried about credit card hacks, phishing scams and the security of their transactions with plastic or with online transactions. PCI Compliance is a hot button issue, especially in light of Sony’s security breach earlier this year as well as the recent DigiNotar Hack. So technology like NFC where people just wave their cell phone at a scanner make people nervous about how secure the transaction really is. And of course it was already shown this year at a security conference that the Square device from Square Up could be hacked and used to steal credit card information.

All is Not Doom and Gloom

While there isn’t much anyone can do but wait when it comes to the technology being developed, Host Merchant Services provides a nice set of tips for addressing the security concerns.

And the Mobey Forum provides a whitepaper extensively reviewing the ability for NFC mobile payments to take hold, and detailing ways to make that happen.

Blogger Keith Cowing also wrote this interesting read on mobile payments, addressing the issue of security and the worries consumers have over eReceipts. In his blog he asks: “The world of retail is changing faster than it ever has before. Nobody had heard of flash sales, group buying, or NFC three years ago. One of the most exciting changes will be the adoption of mobile payments and eReceipts, which will combine to provide a paperless way to checkout and manage your expenses. But when mobile payments and eReceipts become widespread, who will own your purchase data and how will they use it?”

A very compelling question. He goes on to touch on many of the same talking points The Official Merchant Services Blog brings up about mobile payments. I’ll leave you with Mr. Cowing’s final point: “When a customer visits your website, walks into your store, makes a purchase, gets an eReceipt, or talks about your brand on Facebook, these are all touch points in an ongoing customer experience. Your brand is represented by every step along the way and doing the right thing for your customer is doing the right thing for your business. When it comes to mobile payments and eReceipts, providing a convenient and simple solution is part of the customer experience. “

That’s exactly what it’s going to take for Mobile Payments to reach those lofty Juniper Research predictions. The customer has to experience mobile payment as a convenient and simple solution to their transactions. That’s when the mass of consumers will just seamlessly shift their gears (and their dollars) into mobile payments.

Steve Jobs passes away 2011

Steve Jobs 1955-2011

Steve Jobs, Apple co-founder and former CEO of the company, passed away Wednesday October 5, 2011. Apple’s website posted this as a remembrance:

“Apple has lost a visionary and creative genius, and the world has lost an amazing human being. Those of us who have been fortunate enough to know and work with Steve have lost a dear friend and an inspiring mentor. Steve leaves behind a company that only he could have built, and his spirit will forever be the foundation of Apple.”

The impact Jobs had on the payment processing industry is still being defined even now after his passing. Mobile Payments are a booming sector in payment processing, and technology is still being developed and tweaked and polished to harness the revenue potential that some predict will blossom by billions of dollars in the next four to five years.

And the iPhone that Jobs helped Apple launch is a key element in mobile payments. Host Merchant Services‘ own mobile payment solution, HMSPay uses an iPhone application to function. The iPhone, the iPad, the iPod are three of Jobs’ greatest legacies and innovations. These items that Jobs brought forth into the world are still only at the beginning of their use in terms of payment processing and its evolution.

You can find out more about Steve Jobs and his life from these links: