Author Archives: hostmerchantservices

man using smart watch to pay in restaurant nfc contactless convenient payment service 215885687

Smart Payments Association Says 2021 Is a Pivotal Year For Wearable Payments Tech

People have been using wearable items for many purposes in the last few years. They have gone beyond fitness bands and include items that can store schedules, send messages, and read online reports.

People can also pay for products and services with wearable tech items. Wearables like wristbands and watches can link to someone’s credit card or banking information. A person can send one’s data on a wearable to a payment kiosk to pay for something in moments.

It’s also easy for people to program their wearables. People can charge them and link them to online networks where they can provide their payment data. They can link credit cards, bank accounts, online wallets, and other setups to their wearables. They can use these to pay for items without having to bring out any other traditional materials. It provides a secure and quick effort for managing payments.

The rise of wearable payments has prompted the Smart Payments Association to produce a new white paper surrounding the subject. The SPA said in 2017 that wearables are intriguing payment opportunities to explore. But the SPA is now saying that the industry is growing. Wearables have become more flexible, plus customers have never been more willing to use contactless payments than now. The extensive value of the market makes it to where businesses will likely want to get in on it and find new ways to support these payments.

Sales Are High

The Smart Payments Association reports that about 20 percent of proximity payments in 2020 were made with wearables. Global wearable payment totals have risen to about $500 billion in 2020. The number is more than 3.5 times higher than what people had spent in 2017.

The SPA’s report is confirmed by a similar study from Grand View Research. GVR writes that the United States wearable market will rise to about $80 billion in 2028.

The Asia-Pacific market is also expected to be the fastest-growing field in the next few years. HTC, Huawei, and various other Asian businesses have been actively developing new wearable items. Their goal is to mass-produce more items that can work in various spaces while also being affordable for everyone.

The sales totals suggest that the wearable industry won’t be going anywhere any time soon. The field will likely grow in prominence where people can easily find and program these wearables to their liking.

Adoption and Development Are Spreading

The SPA also says that more groups are adopting the use of smart payments through wearables. The production of smartwatches, bands, and rings has risen in the past few years. More companies are entering the field or have plans for doing so very soon.

Apple has thrown its hat in the race by patenting a new smart ring. Apple’s new patent shows it will use a sensor-based gesture setup that allows the customer to waive one’s ring in front of items to complete transactions. The sensor would also notice its position versus other devices, including various Apple items like the iPhone or iPad. The Apple ring would be comparable with the McLear Payment Ring being used in some parts of Europe.

Other companies have also made moves suggesting they may produce new devices that support wearable payments. Google recently acquired Fitbit, although it took a while for the acquisition to be approved by industry regulators.

Peloton also acquired three separate firms that create wearable items. These include companies that produce AI-based solutions to identify how someone might function while exercising.

What New Technologies Will We Find Soon?

The SPA’s report shows that wearable payments will become more prominent as time progresses. More items will be under development soon, and businesses will need to start finding ways to support these items.

There are many aspects of the wearable industry worth watching:

  • Near Field Communication or NFC technology will become essential for businesses to accept soon. NFC systems allow wearables to communicate with payment systems.
  • The variety of wearables available for sale will expand. This point comes as the sensors necessary for wireless transactions are becoming smaller than ever. The rise of the smart ring market proves this point, although sensors could be incorporated in key chains or other compact items.
  • Contactless POS terminals will also become popular. Businesses may find these worthwhile, as they are easy to install and use. They can work anywhere, plus they cost less than most businesses might expect.
  • Wearables may also become more efficient to where users won’t have to charge a battery. These include passive solutions that use electromagnetic induction to stay functional and transfer data to a card reader or another setup.
  • People can also link their wearables with any smartphones or other devices they have. They can check their financial accounts on their phones to confirm their transactions if they wish. The support gives customers more control over their money, as they will know what they are doing when spending on things they want to buy.

Customers and businesses will be more likely to adopt these payments as the technology advances and progresses. The increasingly affordable nature of wearables will also be a positive for the field to watch.

An Exciting Future

People are always looking for convenient ways to handle payments. Wearable technology brings the best of both worlds, as it brings together functional items with high fashion. The industry is growing, and more wearable products are available than ever before. The industry will especially become more noticeable as people continue to wear these products and make them all the more viable. 

It will be intriguing to watch how wearable payments evolve. The SPA writes that 2021 will be an essential year for the industry, as the potential for more products to be made available will be significant. People can expect to find new products soon, plus retailers will be more willing to offer support for wearables. Expect more businesses to get on board and start producing exciting new items that can support wearable payments.

Improving the Bottom Line With Fraud Mitigation

Improving the Bottom Line With Fraud Mitigation

Ecommerce fraud has become a significant concern in today’s economy. People are flocking online more than ever before to make purchases. Some retailers are also focusing more on their digital commerce efforts than their in-store work.

People are using digital commerce services more than ever, but there are worries about the fraud mitigation efforts these companies use. Some businesses are unaware of what they can do to stay safe while online. Others might not be willing to evolve their websites to make them more secure and functional.

But more people are engaging in ecommerce fraud than ever before, as businesses lost about $17.5 billion in online fraud this past year. That total is expected to rise to $20 billion in 2021, especially as people become more reliant on digital sales and less on going to traditional outlets for things.

Fraud Mitigation

Many of these losses come from synthetic ID fraud. The practice entails a user using another person’s identifiable data to acquire something online. The person who makes a transaction is not the person that the website assumes is making the deal.

New efforts to mitigate the risks of online fraud are critical for the industry’s survival. The threat of synthetic ID fraud is too significant for people to ignore, as are various other worries. But artificial intelligence can be critical to preventing possible threats from becoming worse.

Fraud Mitigation – Synthetic ID Fraud Concerns

The most significant worry about synthetic ID fraud is that it isn’t easy for traditional fraud mitigation measures to identify. Sometimes synthetic fraud entails using one piece of identifiable data to move forward. A person’s Social Security Number could work, but the person’s address or name may not be there. A website could assume the customer is the one that links to the SSN in this example.

Fraud Mitigation - Synthetic ID Fraud

Sometimes the synthetic fraud will entail behaviors that are similar to what someone might utilize online. These issues are impossible for some old online platforms to recognize. It becomes easier for people to get away with fraud this way, forcing businesses to write off their losses.

Other Fraudulent Activities

Online fraud can occur on any shopping website through many other methods:

  • A person might steal credit card data and test it on a website. The person can test the card to see the possible credit limit on that card. Once someone knows that a card works, that person will want to continue making expensive transactions on that card.
  • People could steal passwords and other bits of verification data when getting online. A person might use the data one finds to impersonate an actual person’s account.
  • Interception fraud can occur when someone uses the same billing and shipping info on a stolen card, but the person will intercept the goods in transit. The customer might contact a customer service department to change the shipping address right before moving out of a warehouse.

Many other fraud instances could occur, and they can all be dramatic. The worries that people have surrounding fraud can be dangerous and risky, but they don’t have to be worrisome if the best measures work. Artificial intelligence is a suitable solution to use, as the next section shows.

AI Is Necessary

Artificial intelligence-based solutions will be critical for helping businesses stay safe and to avoid fraud. AI can review customer actions and compare them with general signs of fraud. For example, an AI system can flag situations where someone tries to commit interception fraud by changing the shipping address after placing the order.

Fraud Mitigation - AI Is Necessary

An AI system can use a database that highlights general examples of fraud and common warning signs. The AI review will compare multiple activities in a transaction with the known fraud instances and then flag transactions that may be a concern.

Depending on the setup a business uses, the company can either alert a customer or block the transaction altogether. The held transaction could also be secured if the customer provides enough data to confirm one’s identity. The work can be extensive at times, but it is about ensuring everything happening online stays safe and secure without risking possible losses on either end of the deal.

There are many ways how an AI system can work:

  • Customer behaviors can be gauged versus what people normally do on a website. A website can review when someone gets online, when that person is purchasing things, and where someone accesses a website.
  • A system can also review the payment methods that people use. An entity that uses multiple payment methods might be trying to use many accounts for the same item.
  • Some parties may be using foreign sources for funds. They might use credit cards issued by banks in different countries. Others might be using funds through accounts that support cryptocurrencies that some retailers might not accept for payment purposes.

A business can use multiple third-party programs to identify connection sources and to verify addresses and other details. The business can include these programs surrounding whatever one feels is right for use.

The goal of the analysis is to reduce the risk of chargebacks by identifying fraudulent cases as soon as possible. All activities can be reviewed versus whatever norms the website experiences. 

Responding Is Critical

All online retailers must be ready to respond to potential fraud cases. The process requires twenty-four-hour support that can identify anything new.

But the response should include a personal touch. A company must review the norms that customers express and find cases where something is outside the ordinary. It becomes easier for businesses to reduce their fraud risks when they recognize what is working and what they should be doing when keeping their efforts afloat.

Fraud is a significant worry that can impact any business, but it will be easier to rebound and reduce risks if the right measures work. Businesses can stop various concerns if they know what they are doing while recognizing possible changes that might occur after a while.

Blockchain Technology

How Blockchain Technology Is Fixing Payments Today and What Comes Next [2026 Update]

The challenges that come with payment for items are plentiful. It takes a while for some payments to go through, plus it is tough to trace some deals. Cross-border payments are also burdensome, as people have to go through many legal obstacles to move funds. The potentially expensive fees can also be a burden, plus it might take longer to manage some transactions.

But there is hope, as blockchain technology is helping to simplify payments. Blockchain systems make it easier for people to move their payments. Whether it entails general payments or cross-border transactions, the blockchain system will make it easier for people to facilitate whatever they want to manage.

Payment efforts are challenging, as various banks and other financial groups have various terms for work. The overly centralized nature of money makes it so that people can manage payments through specific platforms. The varying rules, rates, currencies, and other terms make many deals harder to manage than necessary.

How Does The Blockchain Technology Works

Blockchain technology is already prominent today, and it will continue to be worth watching in the future. The potential for the industry is strong, but it will require technical support to ensure it can stay active.

How Does The Blockchain Technology Work

A blockchain-based system provides a convenient approach to handling payments. A blockchain works by allowing parties to interact with one another over a decentralized network.

The two entities that are managing the funds will send their private and public keys out in a transaction. The keys confirm the identities of the people handling the money.

The blockchain transfer is then confirmed by the two parties. Their transaction will be recorded on the blockchain, which is run by a countless number of nodes that will manage data. The content is easy to track, plus it cannot be removed from the ledger after it works.

A Stable Transfer of Data

A Stable Transfer of Data

The blockchain deal works with a consistent currency or another asset. The transfer is easy to follow, as the process doesn’t have to utilize any exchanges, fees, or other obstacles. Since the blockchain is decentralized, it is easy for the system to work in more markets. There’s no need to rely on the specific rules set by one party.

An Open Network

An open network will work on the blockchain. An open network allows people to use whatever forms of technology they wish to utilize. The blockchain is interoperable with many other systems and markets, providing a convenient design for work.

A Modern Approach to Paying

The G20 has been looking for a way to modernize cross-border payments for years. Blockchain technology will help make this possible. By providing a new way to manage money, underserved markets will have more accessibility to handling funds. It becomes easier for people to interact and manage payments with one another when a blockchain system works.

The digital assets that move will also be backed by fiat currency. The value of the assets will vary surrounding the fiat currency. But the total can be worthwhile if managed well enough. The transfer process lets people facilitate payments without having to exchange currencies for their payment needs.

Reduced Risk

The greatest part of the blockchain system is that it works without much of a risk. The problem with traditional payment methods is that they can feature limits for how they operate. Not all people will have access to the technology necessary for some payments.

The centralized nature of traditional payment solutions can also be a concern. One party might handle all the payment data in a centralized environment. However, the data could be vulnerable to hacking and other threats.

A blockchain system is sensible, as it reduces risk and makes payment transfers open to everyone. The setup does not require any additional materials for work. The two sides can use one of many software programs to access the system as well. They can find many online, although there’s always the option to download something new if necessary.

A Duty of Care

The security of the blockchain also makes it easier for transactions to stay secure. The blockchain operates on various nodes, ensuring the network always stays active.

There’s also a duty of care for the blockchain. All nodes will ensure the blockchain stays intact. All transactions must flow through as accurately and safely as possible without risking possible losses on the market. The effort ensures all transactions work well and that everyone has a plan for whatever might work at any time.

What’s Next For the Blockchain?

What’s Next For the Blockchain?

Blockchain systems will be critical for success when handling funds. But the future of the blockchain will be even more exciting to watch. There are many noteworthy points that could work soon:

  • Renewable energy can help facilitate blockchain transactions without spending lots of time managing the work. The increased power needed for keeping the blockchain active can be challenging to manage, plus it may be expensive after a while.
  • The open nature of the blockchain makes it where most software programs that manage blockchain activities are open-source solutions. More parties can use these to facilitate payments without spending more money on infrastructure.
  • Banks and other legacy financial service providers may start working with blockchain systems. They could settle transactions in minutes instead of in days. Such transfers would be for intra-country efforts, but it will still be worthwhile.
  • A blockchain sandbox may work where people can produce new blockchain apps and platforms as they wish. They can create new platforms for handling money that might fit unique needs. But the effort requires technical knowledge, and testing may also be necessary for the work.

Blockchain technology will be worth exploring as the payment industry evolves and moves forward. Blockchain support will help people handle funds in moments while removing obstacles. It will provide a distinct approach to handling money that can work in moments and provide a sensible solution for an operation that everyone will appreciate managing in any situation.

generation z business concept 109099249

Gen Z Millennials’ Changing Preferences Drive Financial Technology

Technology and trends change with each generation, a point that is true about millennials. The millennial generation has some unique preferences surrounding how they handle their finances that are different from what other people have used in the past. These points are especially true for credit cards. Millennials have unique ideas for what they want out of their cards.

The Most Intriguing Developments

There are many notable developments surrounding what millennials prefer for their finances:

  1. Close to half of all millennials prefer to use credit cards to complete their transactions.
  2. Traditional cash payments aren’t as prominent as they used to be. About 12 percent of millennials use cash as their preferred method for paying for items.
  3. About 40 percent of millennials use debit cards for their payment needs. The total is a drop from nearly 60 percent a few years back.
  4. Millennials are more likely than others to use mobile apps for their financial needs. They often use mobile apps to make deposits.
  5. Millennials are interested in doing business with traditional financial institutions. But they especially appreciate the ones that will invest in technology systems and setups.
  6. People have been completing balance transfers on their cards a little more often than they used to. Some of these transfers may come from debt-related issues.

Can They Cover Their Balance Statements?

There’s a good concern over whether millennials can cover their balance statements when paying off their credit cards. But the Motley Fool-associated Ascent website found in a recent survey that most people do cover their balance statements every month. About 60 percent of consumers say that they pay off their balances on their cards each month.

But slightly less than 20 percent of the respondents in that survey said that they pay the minimum balances on their card bills. The point is a concern, as people who cannot pay off their expenses will be subject to high interest charges. It would also take longer for people to pay off their entire balances if they don’t cover them soon enough.

What Do Millennials Want In Their Credit Cards?

The credit card industry is especially evolving, as it is looking to adapt to the unique needs that customers have when making purchases. Millennials are showing unique thoughts surrounding their credit cards. They want various things in their cards, including these points:

  • Most millennials are looking for cash back offers on their cards.
  • Millennials also want cards that don’t have annual fees.
  • About a quarter of millennials want credit cards with low interest rates. While the number of those who pay their minimum balances is relatively small, those who do this are probably more likely to look for cards with these lower rates.
  • Credit-related perks are prominent among millennials. These include points like credit monitoring and fraud protection support.
  • Purchase protection is also critical among many card users. Return protection and extended warranty support are among the most popular points people can utilize.

What Types of Cards Do Millennials Want?

An average millennial will have about two credit cards in one’s name. The number is on par with other older generations, although baby boomers are more likely to have three cards.

Millennials have unique attitudes surrounding the cards they want:

  • Store-specific cards aren’t as popular among millennials as they are with baby boomers. But they are still convenient for those who want something to pay for purchases at one site, especially since some come with special shopping benefits.
  • Airline and travel cards are still popular with millennials. These cards allow people to earn rewards for travel purchases.
  • Millennials do not think about whether card issuers are as widely accepted as others. They may be more willing to accept cards from any particular network out there.

Smartphones Will Especially Be Critical

Millennials use smartphones more than other generations. Financial technology will likely evolve and update to meet the needs that millennials hold. This work can include linking credit cards, bank accounts, and other investment items to apps people can access on their devices.

Millennials will prompt businesses to start making their financial services available anywhere. The effort will include providing quick access to accounts and other details while also offering consistent alerts. The fraud and purchase protection alerts that credit card companies offer today are examples of how they communicate with their customers more often.

Will Banks Compete?

While millennials are influencing changes in the financial technology and credit card industries, there are worries about whether banks can adapt to the needs people hold. Companies like PayPal and Stripe have been growing in prominence thanks to how easy it is for millennials to access these services. But traditional banks have been worried about whether their systems are going to be interesting to millennials.

The general worries that banks have is that they might be seen by millennials as being inflexible and incapable of managing their needs. Millennials might also consider these banks as being too regulated and strict.

Banks and other traditional financial service providers will need to adapt to the unique needs that millennials hold. They will need to do a few things to make their efforts more viable:

  • They will need to offer more protection and coverage for clients. This work can include monitoring transactions and activities and providing alerts as necessary.
  • Mobile access will be critical for traditional companies to consider. Mobile access can include providing apps that link people to their accounts from anywhere.
  • The ability to integrate with multiple platforms will be essential. Banks and other groups that can integrate with social media systems and various tech items will be easier for millennials to trust and support.
  • Decentralization may also be a necessity. Blockchain technology has made decentralized transactions more appealing. Banks could start working with cryptocurrencies and other blockchain-related assets, although they must also watch for the risks associated with these before they start.

Millennials are changing the credit card and financial technology industries. The ways these fields will continue to change will be interesting for people to watch as time progresses.

holding mobile phone with stock market charts of gamestop 213526229

GameStop Now Has An Additional $551 Million To Fund Its eCommerce Transformation

The video game retailer GameStop was in the news for a while earlier this year, as the company saw its stock price rise thanks to a Reddit-based purchase frenzy. But GameStop is in the news once again, as the company has raised $551 million to manage its ongoing transition to the digital sector.

GameStop raised the funds by selling 3.5 million new shares of stock. The company says it will use its funds to help it move towards online sales. The funds will also manage the company’s balance sheet and help it maintain its ongoing stability.

The work comes as physical retail sites haven’t been as popular. The increasing digitalization of video games and their technology is also making it harder for physical GameStop stores to survive. GameStop’s efforts to move online will help the company become more viable to possible investors interested in finding a stock to support.

Dramatic Stock Shift

GameStop’s move comes as the retailer has seen significant changes in its stock price this year. GameStop, which trades on the New York Stock Exchange under the GME symbol, was trading at about $17 at the start of the calendar year. A heated and passionate frenzy on social media to fight against hedge funds that were shorting the stock prompted GameStop’s value to rise. The stock went over the $300 mark in late January. It dropped back down to around $50 in February, but it has since been a popular “meme stock” among many amateur investors.

The stock value has been fluctuating since that early rise and fall, although its value has been a little steadier in the last few weeks. As of May 19, GameStop stock is trading at $165.

GameStop’s shares rose by about 7 percent in value after the announcement that the company raised more than half a billion dollars. The 3.5 million new shares were sold at slightly under $160 each. The value is more than eight times what it had been trading for at the start of the year. There are no signs that GameStop’s stock value will drop, but whether it will start to rise once more remains an uncertainty, especially given the frustration some investors have towards hedge funds that short stocks.

The Future of GameStop

GameStop may be considering moving towards online work while putting its physical stores on the backburner. GameStop’s physical locations have been dwindling due to shopping malls and other physical commerce locations becoming less popular. Video game companies have also been focusing less on physical media formats and more on making their games available through online-only formats. The effort makes it where the physical console or computer and the necessary controllers for a game are the only things people will require for playing.

GameStop is aiming to make its online presence more prominent. It will not only offer online game sales, but it could also potentially offer online trade-ins. A digital version of the trade-in system would allow GameStop to profit, as people can trade in old games they buy for credits towards new ones. The trade-in system has been a prominent profit producer for GameStop, although it has been notorious for how it often short-changes sellers.

GameStop saw its online revenues for the fourth quarter increase by nearly twice as much as what it had in that same quarter the year before.

Changes At GameStop

The move also comes as GameStop will see some changes at the top. The Dallas-area business will have a new CEO, as George Sherman will leave his position on July 31 at the latest. He may leave the company earlier if the company can find a successor soon. Sherman will get a severance package of about $169 million when he leaves his position.

The business also has a new COO in Jenna Owens. Owens is a former executive with Google and Amazon.

Investor Ryan Cohen has also become more powerful, as he is GameStop’s majority shareholder. Cohen is the co-founder of the online pet goods retailer Chewy.com. The website had become more successful than Amazon in the pet goods industry to where PetSmart acquired nearly two-thirds of the business for more than $3 billion in 2017.

Cohen owns enough shares to have a 13-percent stake in the company. He has been aiming to make GameStop a more prominent entity in the video game industry. He hopes to do to GameStop what he did with Chewy.com and make it into a website people will choose for video game sales instead of Amazon.

Constant Updates

GameStop has been keeping people in the know about how the company is changing. Since February, the company has released more than ten press releases surrounding how it is raising capital and bringing in new executives and other personnel.

GameStop hasn’t talked much about how it is moving towards digital activities. The company hasn’t been overly open on how it raises funds either.

GameStop has a value of about $13 billion. While GameStop appears to be a company on the rise, there also exists some skeptics who are uncertain about what will happen next. The hope for investors is to see that GameStop remains active in building itself up and producing a more digital business plan. But what is happening behind closed doors remains a mystery, although it is possible GameStop will become more valuable.

Whatever happens next, the news from GameStop will be intriguing for gamers and investors to watch. GameStop could see some significant changes very soon, especially as the gaming industry continues to grow in prominence. The release of various new gaming consoles and games have helped GameStop become a company that more people want to invest in above others. The desire to go digital could help GameStop become even more profitable to where it won’t need any memes or social media influence to keep its stock rising in value.

BNPL Schemes

BNPL Schemes Make It Easy To Spend, But Harder To Understand the Risks [2026 Update]

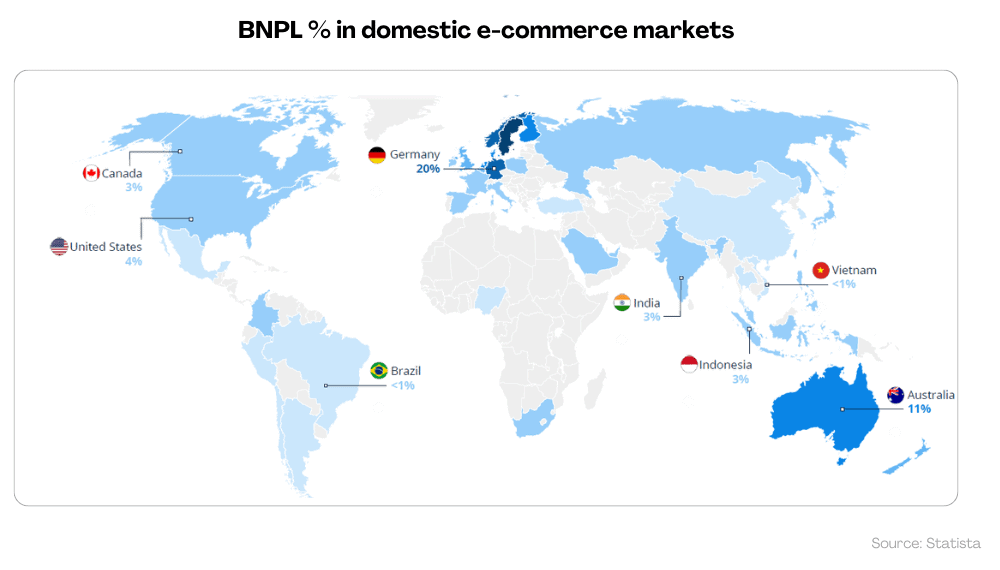
The concept of buy-now-pay-later transactions sounds convenient for many people. The idea allows a person to purchase a product on credit and then pay for it after an interest-free period. The customer can also pay for the item in installments. Online retailers have been using BNPL schemes for a while. They have also become available at some physical sites as of late.

While BNPL systems are appealing, there are many risks to consider. Sometimes a person might have less power over one’s purchase than what someone might expect. It is also tough for many people to fully understand some of the things they’ll get out of their schemes.

domestic market of bnpl

Sour: Statista

A BNPL provider could also help reduce the risks associated with these schemes by being more transparent and easy to understand. A BNPL team can work with security systems to protect everyone’s data, plus it could provide clear terms and conditions that people will want to read and understand. It will still be up to the customer to watch for the risks that come with whatever one wishes to manage.

BNPL Schemes – Different Limits

A BNPL scheme will often subject customers to lower transaction limits than what their credit cards might support. A BNPL website or service will require a customer to provide personal data before completing a transaction. A customer might need to allow access to websites or services that can review someone’s credit risk.

Alternative credit scoring may also work in some cases. The effort entails non-traditional methods for reviewing someone’s credit risk. Instead of focusing on what credit bureaus say, an alternative credit scoring process can entail looking at things like these:

  • Bill payments for various entities
  • What someone does on social media
  • Employment history
  • Property records
  • Any transactions someone makes with a government
BNPL Schemes - Different Limits

These points are radically different from whatever traditional credit bureaus can review. The review efforts make it that someone might have less purchasing power than if someone used a traditional credit card. The review process may also be invasive to where more of one’s data is being used in ways that someone might not prefer or expect.

Extensive Fees

Most people who use BNPL services don’t think about the fees they would pay if they don’t handle their work well. The costs can be significant at times:

  • Some BNPL fees can be several percentage points of the value of a purchase. These fees will keep the BNPL system operational while ensuring it can maintain a profit. The charge is also reflective of the convenience the system provides to its customers.
  • Late fees can be more than 50 percent of the value of one’s outstanding balance in some cases.
  • Some services may not have caps on how high the late fees can get.
  • A service could suspend an account if someone doesn’t complete a payment on time.

But a BNPL service won’t charge interest on outstanding payment amounts like what a credit card company would do. BPNL will gain its revenue from merchant fees instead of through annual fees or interest debt.

Payment Data Storage Is Necessary

bnpl icon

A BNPL system will require a customer to store one’s payment data in a network. The customer’s security risk will be higher due to one’s data being open in a new platform. There’s no guarantee that a BNPL setup will always be secure for regular use either, producing a significant worry surrounding what someone can get out of the work.

Customers will put their data at risk of being lost when they deal with these transactions. But this doesn’t have to be as much of a concern if a BNPL provider manages things right. A BNPL solution should utilize the proper security features to ensure its safe operation. A BNPL system can work with many things, including:

  • Password protection, including two-way verification processes
  • Firewalls, including hardware and software-based ones that the BNPL service operates
  • Encryption support, especially for credit card data
  • Tokenization of transactions to replace personally identifiable information on a network

BNPL solutions will increase how many transactions a business can offer, as BNPL efforts can make a business more accessible and useful. But a BNPL service will not be as effective if one isn’t aware of everything that can work.

Complex Terms and Conditions

The terms and conditions surrounding BNPL schemes can be too convoluted for people to figure out. People who don’t understand these terms might fall victim to some of the risks associated with a BNPL deal. The BNPL app Klarna has an extensive terms and conditions listing that takes close to an hour for a person to read, for example.

The greatest worry is that most people don’t think to read the terms and conditions. The computer game retail site Gamestation had an April Fools’ Day gag this year where it said in its terms and conditions that anyone who didn’t click on a specific link that day when making a purchase would forfeit their souls to the website.

The prank showcased how people never read these terms before making purchases. It shows that people are often willing to skip these details when trying to complete a transaction. They want to pay for items right now and aren’t willing to wade through complex terms.

BNPL services are traditionally transparent when discussing their fees. They want to prevent their customers from collecting more rollover debt than what they can afford. But the terms and conditions sections can be complex and thorough to where it might be tough for people to afford certain things that they think they could purchase right away.

Caution Is Critical

BNPL schemes can be useful when ensuring people can get more access to different items they want to purchase. But a BNPL solution needs the right planning. Every customer must be capable of recognizing the risks associated with such a transaction. Failing to understand the concerns of a BNPL deal can be dangerous, especially considering how one’s financial data is being made open to everyone in the process.

woman hand holding apple iphone 11 pay pass online terminal 162910035

Why Are Apple Pay, the Starbucks App, and Samsung Pay More Successful Than Other Mobile Wallets?

The odds are you’ve heard about many online wallet solutions. These systems let customers link their credit or debit cards to a wallet setup. The customer can then complete a transaction through one’s phone or another NFC-enabled device. It offers a convenient way to handle payments. It ensures people can complete transactions with physical cash or with a credit or debit card.

There are two mobile wallets that are more successful than the others. Apple Pay has become a staple in the mobile payment industry, while Samsung Pay has also been growing in prominence.

There’s also one unique app that is rising in prominence. The Starbucks coffee chain has a dedicated app people can use when purchasing items from various Starbucks locations.

eMarketer writes that there are about 25 million Apple Pay users and 12 million Samsung Pay users in the United States. These totals are based on how many people have completed at least one transaction with these wallets in the last six months. The Starbucks app has an even greater user base of about 28 million.

But what makes these three payment solutions more popular than other mobile wallets? Let’s take a look at what makes these so prominent.

Apple Pay

First, let’s look at Apple Pay, the most prominent of the online wallet programs around. Apple Pay was one of the first such wallets out of the gate, as it was introduced in 2014.

Apple Pay uses NFC technology to transfer payment data. A user can waive an Apple Pay account over an NFC reader to transmit funds. The system can work on many Apple devices, including the iPhone and Apple Watch.

Apple Pay offers many positives:

  • Customers don’t need online connections to use Apple Pay. All payment data stays in the cloud, ensuring the content can move forward as necessary.
  • Apple Pay uses a biometrics-based system where the user can touch a specific part of one’s phone or watch or another device that uses the setup. The two-part ID system ensures only the right person will initiate the transaction.
  • Most payment networks and banks support Apple Pay. The system ensures people can use the wallet in more places.

The immense popularity of the iPhone and other Apple devices will also ensure that Apple Pay will become more accessible in the future. As more people use the latest Apple devices, more retailers will accept Apple Pay payments.

Like with many other Apple features, this only works on Apple devices. But Apple’s products are still popular enough to make Apple Pay a highly sought-after solution for managing payments.

Samsung Pay

Samsung Pay has also been around for a while, as the system started in 2015. It is slightly different from Apple Pay in that while it stores payment data in a cloud, the tokens it produces will go from the cloud to the device when the purchase is made. An online connection will be necessary in this case.

What makes Samsung Pay useful is that it is easier to use it in more locations. Samsung Pay uses a Magnetic Secure Transmission or MST system to transfer data. It can work in more POS readers, including non-NFC magstripe readers. MST technology is easier to find on devices than NFC technology.

An MST system uses a few steps to work:

  1. The device will produce a magnetic signal like what you’d produce on a traditional magstripe card when you swipe it.
  2. The card reader will identify the signal. It will find the card number and other pieces of security data.
  3. The POS terminal will read the card data and process the transaction from there. You’ll get a note on your phone through a cloud network after the transaction is complete.

Samsung Pay doesn’t have as much of a reach as Apple Pay, although it is still a prominent choice of note. The Samsung S6 and S6 Edge phones will make the system more popular.

The Starbucks App

The idea of a single company’s app being highly popular among mobile wallets sounds surprising. But there aren’t many companies that are as widespread as Starbucks.

The Starbucks app lets people load money from a separate credit or debit card to the app. The customer can then use the app at any Starbucks location to pay for the coffee or whatever else someone orders at the location.

The app features a useful setup and is ideal for people who frequently visit Starbucks. But there are many other reasons why the Starbucks app is so popular. These points may help show other retailers why starting their apps might be a good idea:

  • The Starbucks app provides rewards to regular customers. People can earn points they can use for various free purchases, giving them an incentive to return for future purchases.
  • There’s more loyalty attached to the Starbucks app. Since it isn’t preloaded on the phone like the other wallets for specific devices, people can choose to download the app if they tend to do business at Starbucks more often.
  • The app gives Starbucks regular customer insights and data. The company can use this data to provide rewards and other features to its customers. Starbucks also keeps the data to itself, ensuring its security.
  • The app also supports various debit and credit cards. This feature may be thanks to Starbucks’ immense reach and power, but it does help the company take in more money and handle payments well.
  • Since the transactions come through physical devices, it is easier for Starbucks to manage these deals without risking chargebacks and other common concerns.

All three of these mobile wallets are very popular for different reasons, but they all have one thing in common. They make it easier for people to complete their transactions. It is no surprise that they are all prominent in today’s online world and continue to be useful to many people.

hacker trying to hack in to computer network with warning screenshot 122102799

Merchants Called To the Offensive In Battle Against Cyber Fraud

Cyber Fraud has been a concern that merchants have been dealing with for a while. But the increasing use of online payments during the global pandemic has forced merchants to take it a little more seriously. The risk of fraud has never been greater than it is now.

People are engaging in fraudulent activities while online more than ever. Friendly fraud is a concern, as people are requesting chargebacks on many transactions after they collect their items. While customers are running off with various things, online retailers are losing money from chargebacks. 

Traditional forms of cyber fraud are still prominent. These include the use of malware, remote access Trojans, and other things that can target a merchant’s system. It becomes easy for thieves to steal data and compromise a website with these tools. A business will lose money on chargebacks if this happens. These chargebacks can be worth significant amounts of money, as data thieves often make expensive purchases through the identities they steal.

Online merchants are more susceptible to fraud than ever, but it doesn’t have to be this way. These retailers are working harder than ever to control cyber fraud. They are using many efforts to reduce the risk of fraud and to keep their investments under control. All of these moves are about going on the offensive and working harder towards identifying fraud.

Confirming the Customer’s Identity

Many cases of cyber fraud can occur when a person tries passing oneself off as another person. Online identity theft is a concern, as anyone could log into an account and claim to be that person. The customer will quickly engage in fraud after stealing that identity.

Merchants are fighting this form of fraud by using further measures to confirm each customer’s identity. The business can confirm details like one’s billing and mailing address, credit card data, and other factors.

The customer’s IP address will also be a factor. The IP address of the connection one uses when purchasing something would have to link up to the billing or mailing address one uses, for example.

Customers can also monitor other things surrounding a person’s identity, like one’s phone number or email address. A phone number might be listed in an area outside one’s area or have a billing address outside where one lives. The email address might also look fake or be registered in a different spot.

Other sudden changes like a higher frequency of orders or a significant increase in one’s order amount versus prior purchases could also be points of review. Merchants can check these things to flag possible fraudulent activities that might result in chargebacks.

Managing Internal Data

Internal data can also help identify cases of fraud. The business can monitor all the activities the customer enters. The team can monitor when that person logs into an account, what products someone purchases, unique promo codes one uses, and other activities. A merchant can compare internal data with everything else a customer is doing to confirm a transaction or to directly question whatever someone is doing while online.

The work is about finding unique changes in one’s behaviors. Anything that is out of the ordinary will be flagged. The goal is to prevent the customer from completing the transaction before anything can go forward.

Finding Fraud Through Behavioral Analysis

Artificial intelligence will play a critical role in preventing cyber fraud in the future. Behavioral biometrics technology is one part of the work. This system is a solution where a customer’s behavior is monitored in real-time. The customer’s interactions with online apps and devices are measured to identify how they act and if they show signs of possible fraud. The AI system will review these details and determine if the user is real or if that person is trying to commit fraud.

The behavioral biometrics system can also identify when a user is a remote access Trojan, a malware program, or a non-human entity. The effort can catch parties that might commit fraud. The work does not entail going through specific private details, but rather about confirming the person is accessing a site from a place where one might appear.

Positive Profiling Also Works

Another solution for preventing cyber fraud entails positive profiling. The practice involves using Big Data to review a person’s behavior through various retailers and websites. The customer’s behavior is compared with actions from other confirmed fraud suspects. The customer is screened instead of the transaction, providing a more accurate response to the issue.

Positive profiling is not about trying to uncover private data on a customer. It is about monitoring the customer’s shopping activities. It confirms that the customer is acting like any other shopper and that nothing is out of the ordinary.

A Chronological Analysis

The last point merchants are using to stop cyber fraud entails using a chronological review of everything happening in a chargeback. This part of stopping cyber fraud entails what happens after the transaction, but it can potentially prevent friendly fraud cases.

A time-based review can analyze the customer’s identity, prior purchase or shopping behaviors, and other details surrounding a transaction. The retailer can review how the deal is different or similar to others. The work is about showing that a person might have made a proper transaction and is trying to cheat one’s way out of paying for it. But it could also confirm that a legitimate chargeback is necessary. Whatever the case, it can still reduce the general risk of excess chargebacks in the process.

Will Everything Work?

People are going to keep on attempting cyber fraud no matter what happens. Some people will want a free ride on things, while others might be desperate and willing to do what it takes to avoid spending money on items. Whatever the case, online retailers are more proactive in reviewing possible cyber fraud cases. Their work is about preventing fraud and protecting their investments. With fraud being on the rise, these businesses will need to be more adamant when fighting fraud.

Frequently Asked Questions

  1. Why are merchants being called to the offensive in the battle against cyber fraud?

    Merchants are being called to the offensive in the battle against cyber fraud due to the increasing prevalence and sophistication of fraudulent activities targeting businesses. Cybercriminals constantly evolve their tactics, posing significant threats to merchant operations, customer data, and financial security. By taking an offensive stance, merchants can proactively implement robust security measures, such as multi-factor authentication, encryption, and fraud detection systems, to protect their businesses and customers. Being proactive allows merchants to stay ahead of cyber threats, minimize potential losses, maintain customer trust, and preserve their reputation.

  2. What are the consequences of cyber fraud for merchants?

    Cyber fraud can have severe consequences for merchants. Firstly, financial losses can be substantial, as fraudsters can exploit vulnerabilities in payment systems, leading to unauthorized transactions, chargebacks, and financial damages. Additionally, the reputational damage resulting from cyber fraud incidents can erode customer trust, leading to loss of business and negative brand perception. Merchants may also face legal and regulatory repercussions if they fail to adequately protect customer data and comply with industry standards. Moreover, the time and resources required to investigate and mitigate cyber fraud incidents can be significant, impacting operational efficiency and diverting focus from core business activities.

  3. What proactive measures can merchants take to combat cyber fraud?

    Merchants can take several proactive measures to combat cyber fraud. Firstly, implementing strong authentication protocols, such as multi-factor authentication, helps verify the identity of customers and reduces the risk of unauthorized access. Secondly, encrypting sensitive data, both in transit and at rest, ensures that it remains secure and inaccessible to unauthorized individuals. Thirdly, deploying robust fraud detection and prevention systems, leveraging advanced algorithms and machine learning can help identify suspicious patterns and behaviors, allowing merchants to take action promptly. Additionally, regularly updating security software, training employees on cybersecurity best practices, and conducting vulnerability assessments are crucial steps in maintaining a secure environment.

  4. How can merchants collaborate to combat cyber fraud?

    Merchants can collaborate to combat cyber fraud by sharing information, best practices, and threat intelligence within their industry or business networks. Collaborative efforts can include participating in industry-specific working groups, sharing anonymized fraud data, and collaborating with payment processors and financial institutions to identify and respond to emerging threats. By pooling resources and knowledge, merchants can collectively strengthen their defenses, raise awareness about cyber fraud risks, and work towards developing industry-wide standards and guidelines. Collaborative initiatives also enable merchants to leverage shared experiences and insights, staying ahead of evolving fraud techniques and enhancing the overall security posture of the merchant community.

  5. What role do payment processors play in combating cyber fraud?

    Payment processors play a crucial role in combating cyber fraud. They act as intermediaries between merchants and financial institutions, facilitating secure and reliable payment transactions. Payment processors employ advanced fraud detection and prevention technologies to monitor transactions for suspicious activities, enabling them to flag and block potentially fraudulent transactions. They also invest in robust security infrastructure, such as encryption and tokenization, to protect sensitive payment data. Additionally, payment processors often collaborate with merchants to share fraud data, provide education and training on fraud prevention, and offer support in investigating and resolving fraudulent incidents, collectively strengthening the defense against cyber fraud.

qr codes in ring scan for product information 21043960

Exploring the Varying QR Code Adoption Rates Around the World

The Quick Response or QR code has become a necessity for various scanning purposes. The QR code is convenient for touchless payments and other transactions.

QR codes are becoming increasingly essential for secure payments. People are starting to see what makes QR codes so valuable and are picking up on their use. But the adoption rates for QR codes vary by country, with some places being more supportive of them than others. The global pandemic may still force people to use them more often.

Early Adoption In Europe

QR codes are more common in Europe. Part of this comes from Europe’s early adoption of these codes. Abode Systems found in a 2014 report that slightly less than 30 percent of people in Germany and France had used a QR code. The total went down to around 25 percent in the United States and the United Kingdom.

People in these parts of the world were more familiar with QR codes at the start. It would be easier for these codes to work in Europe and other places where people often use them.

Prominent In China

China is one country that has been accepting QR codes more than others. CNN Tech reported that at least a trillion dollars’ worth of transactions were handled through QR codes in China in 2016.

Much of China’s use of QR codes come from WeChat, a popular online social media platform available in the county. The app lets people communicate with each other and make mobile payments. The system uses QR codes to transfer funds, authenticate people, and get information on various things.

It appears that these codes would be more prominent in China and other countries around Asia. The system was established in Japan in 1994 as a system to track vehicles in construction. While it was intended to track the construction of new passenger vehicles, it has since found many other applications. It has become a replacement for traditional barcodes in many situations, including in retail and communication sectors.

Major Surge In India

India is another country that has adopted QR codes well. The Indian government started an effort in 2016 to cut down on fraud and corruption surrounding physical currency. Businesses around India have begun using mobile payment platforms that use QR codes to collect and exchange funds. They can do this without requiring paper currency.

The online payment platform Paytm supports millions of these businesses. Such transactions do not require physical currency, thus preventing fraud. It has been part of India’s ongoing effort to create a fair economy and to reduce risks.

American Acceptance

Americans started using QR codes more often as the 2010s progressed. Statista reports that about less than ten million American households had scanned a QR code in 2018. The number rose to about eleven million households in 2020.

QR codes are becoming more prominent in the United States. They are in use through various businesses and private individuals for many purposes:

  • Recording loyalty programs at different retail sites
  • Tracing products and shipments to ensure they reach their desired locations
  • Creating links people can scan to learn more about physical items; these can appear on billboards and other public messages
  • Accepting donations for various events or charitable activities
  • To help people communicate with others through social media platforms; this includes linking QR messages to social media accounts

How the Pandemic Changes Things

The most significant factor influencing the rise of QR codes has been the ongoing pandemic. QR codes are becoming more common for touchless payments. QR codes can send payment data to different parties without requiring any contact, thus providing a safer approach to trading funds. People can also use QR codes to scan and read documents online instead of using physical ones.

Statista found in late 2020 that nearly half of all Americans and those in the United Kingdom had used QR codes more often. Code adoption has also been on the rise in Canada, Australia, France, Thailand, Hong Kong, and other major markets.

Some governments are even requiring businesses to use QR codes. The Australian state of New South Wales requires stores to use QR codes for transactions to support contact tracing. The effort ensures people can be tracked and monitored if there is an outbreak in certain places. People who visited areas where outbreaks occur can be informed of the situation.

Further Work Is Necessary

Additional efforts will be necessary to make QR codes more viable. Governments could potentially start using QR codes to facilitate various monetary transactions. An example of this appears in Singapore, where the government is establishing national payment standards that utilize QR codes. The effort would make it easier for people in the city-state to receive payments from the government.

Pandemic-related changes that have caused businesses to become more reliant on QR codes could also make an impact. These codes are critical as people start looking for contact-free payment and document solutions.

Could the Positives of QR Codes Make an Impact?

It might be easier for people to start using QR codes if they understand the positives that come with them. Businesses and the general public may start using QR codes more often if they notice some of the benefits of the work:

  • A QR code can store more data than a traditional bar code. It features a two-dimensional approach to storing data. The layout includes content in its horizontal and vertical spaces.
  • QR codes are encrypted and hard to hack, making them useful and safe for financial transactions.
  • It is easier for people to read QR codes than barcodes. A QR code can even be read if it is damaged or partially obscured.
  • These codes can also be produced in massive sizes, including ones that could cover an entire billboard.

QR codes are already becoming more prominent worldwide due to the pandemic. But the benefits of QR codes and the familiarity that people have with these codes will make them prominent very soon.

cozy restaurant 39875776

Friendly Fraud Becomes Sworn Enemy For Restaurants

Restaurants have already been hit hard during the pandemic, as they are subject to various restrictions. Many places cannot open for anything other than delivery. Reduced dining room capacity keeps these businesses from bringing in as much income as usual. There’s also the worry about further restrictions coming later.

One other concern that is harming restaurants entails friendly fraud. This issue has become more prominent during the pandemic. People are buying more products and services online than ever. It has become easier than ever for people to get refunds on purchases they already consumed or utilized. People can get chargebacks instead of restaurant-issued refunds on their purchases.

The problem is simple, but it can be resolved or reduced if a restaurant uses the right measures. These include efforts for reviewing disputes and for accepting alternate forms of payment.

What Is Friendly Fraud?

Friendly fraud is where a customer will get a chargeback on a transaction the customer completes while online. The effort entails a few steps:

  1. A customer will complete a purchase with a credit card while online.
  2. The person receives the products or services.
  3. The customer will then request a chargeback from the issuing bank. The person must file an explanation surrounding the removal.
  4. The bank will review the request.
  5. The bank then decides to accept or decline the chargeback.
  6. If accepted, the bank will cancel the transaction.
  7. The consumer receives a refund of whatever one spent on that purchase.

The effort makes it easier for people to get things they want for free. Restaurants are hurt by this as people purchase foods for delivery or takeout online. Those people can then ask for chargebacks after they acquire whatever foods they ordered. The move provides free meals at the restaurant’s expense.

Who Is Liable?

A restaurant or other business will be held liable when a chargeback occurs. The merchant is accountable despite any efforts to verify the deal. Sometimes the customer requesting the chargeback might say the transaction was unauthorized. The move makes it easier for that person to get the full refund.

This concern has become prominent during the pandemic. Fewer people are dining at restaurants and are ordering home delivery. They do this for safety reasons, but some are starting to abuse the system.

It is easier for friendly fraud to occur when someone completes an online to-go order. The card doesn’t have to be present for an online transaction.

Other Payment Platforms Hurt

Another concern restaurants are dealing with entails how other payment platforms work. Many digital platforms people use for ordering foods from restaurants will move transaction data through an outside party. There exists another layer between the customer and restaurant due to these external programs.

It could become easier for people to request chargebacks if they purchase foods through these other platforms. The customer could claim that the food one ordered was ruined while in transit, or the delivery never came. But these points might not be valid, and it might be tough for a third party to dispute this point.

Why Do Card Issuers Usually Side With the Customers?

While the customers often lie about their chargebacks, it is easy for them to take advantage of this point. There are many reasons why card issuers will stick with the customers in these disputes surrounding friendly fraud:

  • Card issuers have zero-liability policies, meaning the customer isn’t liable for any unauthorized purchases.
  • Online transactions are card-not-present deals, meaning anyone could use a card so long as one has it in one’s possession.
  • Consumer protection regulations focus on protecting customers from abusing card companies or businesses. They may be more willing to support the customers to keep their positive images intact.

Why Are People Engaging In Friendly Fraud?

The main reason people participate in friendly fraud towards restaurants entails their own financial struggles. Many people have lost their ability to bring in income during the past year. People might be willing to do anything they can to reduce their expenses.

The faulty mechanisms surrounding fraud protection for online food purchases are another factor. Since these transactions are card-not-present deals, it becomes easier for people to produce claims. They could say someone else had the card in hand, for example.

How Can Restaurants Fix This?

Friendly fraud is a legitimate concern that will likely become worse. More people will start to learn about it and take advantage of this point. But restaurants can fix this problem before it can become more widespread. They can use a few points for help:

  1. Digital wallets can add protection.

Digital wallets like Google Pay or Apple Pay allow people to complete transactions through a P2P network. The system doesn’t require any outside banks or delivery parties. It is also easier for people to confirm their identities through these digital wallet programs.

  1. Cash-on-delivery may also work.

Cash-on-delivery transactions may become necessary for some restaurant purchases. COD deals allow people to pay for their foods when they are delivered or when they pick them up. The customer can use a credit card, although cash could also work if the customer prefers this option.

  1. Artificial intelligence support is necessary.

Restaurants can use artificial intelligence or AI technology to review and resolve disputes. AI can review customer disputes and identify the best resolution methods. The work reduces the risk of chargebacks and ensures businesses can issue refunds when they are legitimate.

  1. Regular interaction is critical.

A restaurant can also communicate with the customer whenever there’s a problem. The restaurant can talk with the customer about the issue at hand. The two parties can find a reasonable way to resolve the issue before a chargeback is necessary. Having a more transparent system may also discourage people from committing friendly fraud.

Friendly fraud will be a significant concern for restaurants to watch for now and into the future. But the taking the right efforts for preventing the issue will help.

Friendly fraud: one piece of running payments in a restaurant. The rest of our restaurant payment guides are in Restaurant Payment Resources.