Author Archives: hostmerchantservices

zelle scam

How To Defend Your Business Against Email Scams

Business email scams, also known as business email compromise (BEC) scams, are a type of cybercrime that involves criminals sending fraudulent emails to businesses or individuals to trick them into releasing sensitive information or transferring money.

These scams can be devastating for businesses, as they can result in financial losses, damage to reputation, and legal issues. This article will discuss what business email scams are, how to defend your business against them, and what to do if you have been targeted by one. We will also look at the future of business email scams and what we can expect in the coming years.

What is a Business Email Scam?

Business email scams, also known as business email compromise (BEC) scams, are a widespread and frequently occurring form of cybercrime. Criminals behind these scams send fraudulent emails to businesses or individuals, intending to trick them into revealing sensitive information or transferring funds.

BEC scams are notoriously sophisticated, often involving the use of fake websites and email addresses that are designed to look genuine. These scams can have severe consequences for businesses, potentially leading to financial losses, damage to reputation, and legal issues. It is crucial for companies to be aware of these scams and to take steps to protect themselves against them.

Some common types of business email scams include:

Phishing scams

These scams involve criminals sending fake emails that appear to be from legitimate sources, such as banks or government agencies, to trick the recipient into giving out sensitive information, such as passwords or log in credentials.

Invoice scams

One common type of business email scam involves criminals sending fake invoices to businesses, often requesting payment for goods or services that were never received. These scams can be extremely convincing, with the criminals going to great lengths to make the invoices appear legitimate.

They may use logos and branding similar to the business they are targeting and may even forge the signature of an honest employee.

Executive impersonation scams

These scams involve criminals pretending to be high-level executives within a company and sending emails to lower-level employees requesting sensitive information or money transfers.

Lottery scams

In this type of scam, criminals send emails claiming that the recipient has won a large sum of money in a lottery and requesting personal information or a fee to receive the winnings.

How to Defend Your Business Against Email Scams

There are several steps that businesses can take to protect themselves against business email scams:

  • Train employees on recognizing and avoiding scams: Employees must know the various types of business email scams and how to identify them. This can be done through training programs and regular reminders to be cautious when receiving emails from unknown sources
  • Use spam filters: Many email programs have built-in filters to help identify and block fraudulent emails. It is essential to regularly update these filters to ensure they effectively block new types of scams
  • Verify the authenticity of emails: If you receive an email from a colleague or business partner that seems out of character or unusual, it is vital to verify the email’s authenticity before taking action. You can do this by contacting the sender directly or checking with other colleagues to see if they have received the same email
  • Use strong passwords: It is crucial to use strong passwords for all accounts, including email accounts, to prevent criminals from accessing your accounts and using them to send fraudulent emails
  • Enable two-factor authentication: Enabling two-factor authentication (2FA) on your accounts can add an extra layer of security by requiring an additional piece of information, such as a code sent to your phone, before allowing access to an account

What Should I do if a Business Email Compromise Scam has Targeted me?

If you believe that a business email scam has targeted you, there are several steps you should take:

  • Do not respond to the email: Don’t respond to it or click on any links within it, as this can potentially give the scammer access to your account or personal information
  • Contact the relevant authorities: If you have received a fraudulent email claiming to be from a government agency or financial institution, don’t contact that organization directly to verify the authenticity of the email. You should also report the scam to the relevant authorities, such as the Federal Bureau of Investigation (FBI) or the Internet Crime Complaint Center (IC3)
  • Change your passwords: If you believe that your accounts have been compromised, you need to change them as soon as possible to prevent further access by the scammer
  • Monitor your accounts: Keep a close eye on your accounts and report any suspicious activity to the relevant authorities and your financial institution
  • Protect your personal information: Be cautious about giving out personal information, such as your social security number or bank account information, to anyone, even if they claim to be from a legitimate organization

What is the Future of Business Email Scams?
beware of scams 209135546

Business email scams will likely continue to evolve and become more sophisticated. Cybercriminals are always looking for new ways to trick people into giving out sensitive information or transferring money. They are likely to continue to find new ways to do so.

To protect against these scams, it is essential for businesses to stay up to date on the latest threats and to implement strong security measures, such as training employees on how to recognize and avoid scams, using spam filters and two-factor authentication, and regularly updating passwords.

Conclusion

Business email scams can devastate businesses, resulting in financial losses, damage to reputation, and legal issues. To protect against these scams, it is crucial to train employees to recognize and avoid them, use spam filters and two-factor authentication, and verify the authenticity of emails before taking action.

If a business email scam has targeted you, it is crucial to report the fraud to the relevant authorities and take steps to protect your accounts and personal information. Business email scams will likely continue to evolve, so businesses must stay updated on the latest threats and implement strong security measures to protect against them.
Recession-Proof Your Business

How to Recession-Proof Your Business

A business cannot thrive on its own. If the market trends are good and growing most businesses benefit from that growth. But, during a recession or slow down every business gets impacted, regardless of their size and industry. People get jobless during the recession. They have less money to spend and thus they buy fewer things. As a business owner, what can you do to avoid the damages due to recession?

Fortunately, there are many ways to recession-proof your business so that it won’t fail just because of a general economic downturn. Read on to learn how to keep your business thriving despite the economic recession.

As a business owner or manager, it is important to keep a watch on the market trends. A recession doesn’t ever hit all of a sudden, there is typically a gradual process and there are ample signs that can indicate that the recession is imminent. When it hits, you can follow any or all of these six practical solutions that have helped defend countless businesses in various industries throughout previous recessions. You need to first analyze the benefits of these solutions and then implement then into your business.

How do Recessions Impact Small Businesses?

When a recession hits, all types of companies get affected. But, small businesses suffer the most. The biggest reason for this is that the owners of small businesses often do not have multiple sources of income. Larger companies have many options to survive the recession. They have large reserves that they can use to sustain or they have multiple income streams that keep them afloat during bad times. They have big teams of talented people who can help them create policies and strategies to survive the recession.

Small businesses need to take care of themselves and these six important tactics can help them to recession-proof their business.

6 Ways to Recession-Proof Your Business

Talk to suppliers and partners

For small businesses, their core strength is their suppliers and partners. As soon as you see the signs you need to implement the first strategy. And that is to talk to your partners and suppliers so that your business gets the required material and money to sustain the recession.

Remember, when a recession hits your competitors might lower their prices to stay ahead or capture the market. Are you prepared for that? Will you be able to stay in profit after lowering your product or service cost? To lower your selling price you need to first lower your production cost. So suppliers of raw materials to your business are crucial.

Sometimes, you might need to upgrade your technology to lower your production cost. Your partners needs to be on board to invest in those upgrades. In short, your partners and suppliers need to be on the same page based on the decisions that you want to make.

Create an emergency fund

2023 trends for global payments

A financial cushion is a sensible business investment, particularly for smaller businesses that can’t quickly tap debt markets in the same way that a large enterprise might be able to do. Having financial backup during a recession is even more important.

Establish a cash reserve that can pay up to six months’ worth of basic needs, such as payroll, inventory, and utility payments, in the event of a financial emergency. You can gain a head start by aggressively collecting the receivables owed to you. You can also try to find out investors who can help in improving the technology so that you can stay ahead in the market. This will help in two ways – you will get extra funds and at the same time, you will be technologically prepared to beat the competition during the recession.

Reduce cost

customer payment

Since overhead costs are expenditures that are always incurred, regardless of the amount of revenue, they provide a particular challenge during a period of economic contraction.

The overhead costs can be cut drastically. When a company is on a growth trajectory company tends to increase its overhead costs. During difficult times overhead costs should be reduced as a priority.

Renegotiating with vendors that offer you various types of services is one way to reduce costs. Renegotiating contracts with suppliers, switching to a different vendor for services such as office cleaning or communications, or decreasing or eliminating bonuses for staff members are a few examples of renegotiation. Eliminating travel and leisure expenses and outsourcing various works can also help in reducing costs.

Outsourcing can save many infrastructural costs and help you stay in the competition. Finding ways to minimize overhead costs before an economic downturn can not only help your business survive but also improve overall efficiency with less staff and resources.

Uncertain Situation Due To Lack of A Strategy

Disrupt the Payments Industry

Small firms face heightened levels of uncertainty during recessions. This usually happens if the businesses have not prepared themselves beforehand for the recession. Recessions are not always bad for business and can often present many companies with valuable opportunities. But the only condition is to have a concrete strategy before the recession hits.

Build strong relationships with people and brands you know

customer relationship

Any business – big or small – faces less damage during a recession if they have a strong bonding with the customers. If your customers are loyal and have faith in your products and services they will stay with you during bad times too.

If you haven’t thought about it until now then start connecting with your customers on a personal level today. You can come up with multiple strategies to do so. But, the end goal is to keep your customers happy and content.

Your customers also face many difficulties during a recession. Having a good relationship with them will help you understand their challenges and prepare a strategy to cope with the same. For example, reducing price, or offering a subscription package that offers free services for some period of time can help your customer stay in a comfortable zone.

Recession-Proof Industries

There are many industries that are called recession-proof industries. For example health or education industries. If you are in this segment of the business then you won’t face the brunt of the recession like other industries. If you can switch to any such types of segments then you should do it now.

If switching is not possible then diversify the products/services you offer to connect with these industries. Thus during recession, your products or services from these segments will keep you afloat.

Conclusion

A recession can have a significant impact on any industry, regardless of the financial health of your company. While it is impossible to escape a recession, some steps may be taken to safeguard your company from the effects of the consequences.

You can do many different things to shield your company from the effects of a recession, such as increasing the effort you put in, diversifying the products and services you offer, or investing in more environmentally friendly technology.

Top DeFi Trends

Top DeFi Trends and What Comes Next

DeFi stands for decentralized finance. In the past year, we’ve seen an explosion of new DeFi projects and initiatives launched worldwide. These DeFi trends aren’t something that will go away anytime soon. We are now entering peak DeFi – a decentralized financial ecosystem is now widely recognized as inevitable and imminent.

The global financial crisis has made it clear that no single institution can be trusted to safeguard money or manage risk responsibly in any given economy. As a result, we are seeing more and more people moving their assets from banks into digital currencies like Etherium and Bitcoin.

These emerging trends show how DeFi has become more than just a niche community of enthusiasts; it has become mainstream – at least among savvy coders who understand the need for decentralized systems over centralized ones.

What is Decentralised Finance (DeFi)?

Decentralized finance (DeFi) is financial services built on decentralized technologies like blockchain. DeFi allows users to create financial products and services that are not controlled by any single entity.

For example, a decentralized lending platform would allow borrowers and lenders to enter into a contract without needing a financial institution to facilitate the transaction. On a broader level, decentralized finance refers to the idea that financial services are best offered outside traditional financial institutions such as banks and venture capital firms.

The Importance of Decentralized Financial Infrastructure

Decentralized financial infrastructure is crucial to empowering people and businesses in a way they have never been empowered before. In the past, the centralized system was necessary because it was the only way to scale and distribute services to a wide range of people. But now, with the advent of blockchain technology and smart contracts, there is no reason for financial services to be concentrated in a few hands

Especially when managing finances like lending. Decentralized financial infrastructure will pave the way for fairer, more transparent, and more accessible systems managed by all stakeholders, not just a select few.

Top DeFi Trends

Uniswap

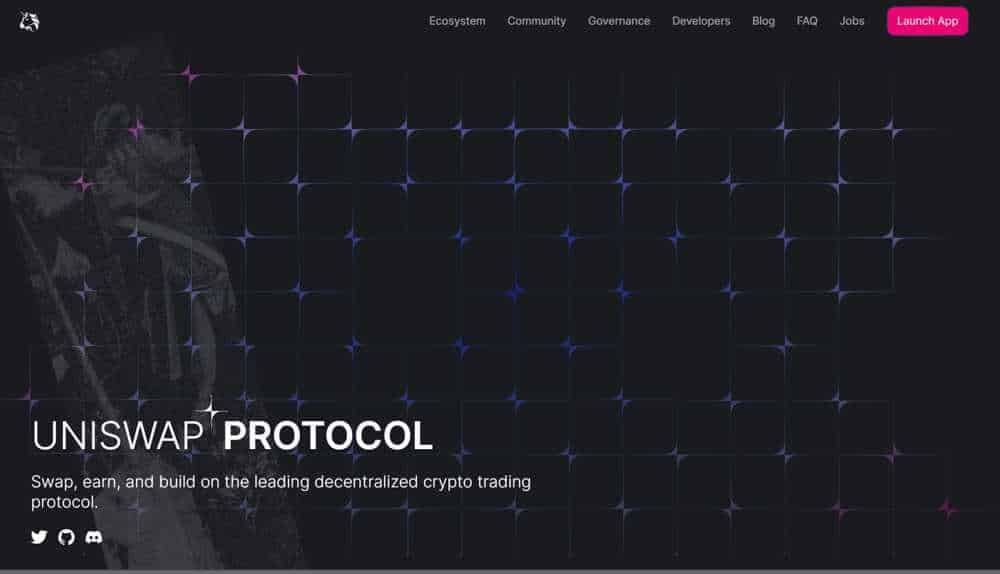
Uniswap is one of the industry’s biggest and most well-known DEXs, and it is a must-have tool with most DeFi investors. Uniswap, first and foremost, allows traders to swap cryptocurrency tokens securely and conveniently, with lower fees than centralized exchanges. Users can also generate passive revenue by putting their tokens in liquidity pools.

uniswap
image source

To set the price and execute deals, Uniswap employs an AMM approach that depends on smart contracts. As a result, the platform is completely decentralized, with no intermediaries involved.

Uniswap, like Aave, can ease crypto trading through liquid pools, which are puddles of user-contributed funds locked in smart contracts. These funds facilitate consumer purchases and sales of various cryptocurrency pairs.

A minor fee is collected with each activity on Uniswap and dispersed among the pool’s liquidity providers. This approach is mutually beneficial because traders can exchange tokens with fewer fees, and those who supply liquidity may receive points for doing so.

Aave

aave
image source

There is no more famous and identifiable brand in the DeFi industry than Aave and with good cause. Aave has evolved into among the most reputable sites for Defi, providing a secure environment for consumers to borrow and lend cryptocurrency and hard assets without any middlemen or brokers.

The concept behind Aave’s platform is straightforward: users who extend credit to one another are rewarded with interest, while users who do not are penalized. Ethereum was used as the base for and accepted all any ERC-20 coins, but additional blockchains, such as Fantom, Avalache, and Harmony, have been added. Its community runs through an autonomous body where AAVE-registered users vote on important issues.

Aave provides DeFi clients with a variety of alternatives, with over 30 pooled for Ethereum-based commodities and different markets on other platforms.  There are other lending pools available for physical assets like freight bills and real properties.

Aave gives these pools due to the announced partnership with Centrifuge, using DeFi solution that helps companies to tokenize specific data assets. These tokens then are openly sold, operating in a manner akin to treasuries and receiving a steady income.

Orbs

orbs
image source

The infrastructure layer on which the DeFi protocols function is just as crucial as the protocols themselves, which is why Orbs Network is working to function better. Orbs pays itself as an accessible, distributed blockchain infrastructure layer to speed up DeFi applications across many chains.

Orbs will be regarded as a distributed backbone that enables additional DeFi capabilities by collaborating with established Layer-1 blockchains, including Ethereum and Layer-2 networks like Polygon.

It builds a tiered infrastructural stack for DeFi, allowing decentralized apps to benefit from Orbs’ increased execution services. As a result, developers can create more advanced DeFi apps.

Orb’s Open DeFi Notification system, which offers up-to-the-second notifications on the most significant on-chain events, is an excellent example. Orbs have released a new, distributed Time-Weighted protocol, which can accommodate new order kinds for DEXs as well as Automated Makers.

TWAP is frequently employed in automated trading in the conventional financial industry. Traders utilize a time-weighted average cost to reduce the market impact of large orders. Orders are broken into smaller trades, each executed at defined time frames over a specified time.

Alliance Block

alliance block
images source

AllianceBlock is the designer of a complete DeFi technology that caters not only to those who wish to borrow, lend, and stake crypto but also to programmers of other DeFi initiatives. It provides permissionless KYC/AML and proof of identity, compliant peer-to-peer and NFT services, cross-border compliance, an on-chain or off-investment data API, and more, in addition to its decentralized investment solutions.

Rachid Ajaja and Matthijs de Vries created AllianceBlock in August 2018, when interest in ICOs, or first coin offerings, was growing. The founders were motivated to devise a method to make cryptocurrency investments more transparent, equal, and fair. Since then, AllianceBlock has broadened its scope and strives to bridge the gap between DeFi and traditional financial instruments provided by banks, including loans, bonds, savings, and capital accumulation.

Avalanche

Avalanche is again a promising option for DeFi’s future due to its cryptographic protocol application and revolutionary blockchain approach. AVAX’s blockchain is based on a fundamentally different approach to scaling. Around the blockchain’s magical triangle. Avalanche depends on a blockchain of three threads, with one strand representing each scalability, decentralization, and security.

Compared to Ethereum, this makes payments faster, cheaper, and more ecologically friendly. Avalanche uses the consensus technique. Avalanche is a smart contract framework that enables decentralized applications. An all-purpose coin that aspires to dethrone Ethereum. Avalanche might benefit from its swift and efficient chain, particularly in the DeFi industry.

Conclusion

The next 10 years are likely to bring many more decentralized financial services. This has already started to happen, but it will likely become even more widespread as the technology becomes more accessible and people understand its benefits. The tech behind DeFi is rapidly improving, which means we are likely to see more and more impressive financial services being offered in a decentralized way.

small business saturday

When Is Small Business Saturday 2023: Strategies to Prepare Your Small Business

Small Business Saturday is an annual shopping event that is typically on the first Saturday of November. It’s a day dedicated to supporting small businesses and local shops. Small Business Saturday has grown into an international movement, with more than 700 independent communities coming together to support local businesses in their area.

Small Business Saturday isn’t just another marketing gimmick or sales gimmick. It’s an opportunity. It’s a perfect time and opportunity to introduce your business to potential customers, especially if you have been operating as a local business.

Small Business Saturday gives you a great chance to show your potential customers who you are, what you do, and why they should support you by shopping at your store. Read on for five ways to help you prepare for Small Business Saturday, so your business can welcome customers from all over with open arms!

When is Small Business Saturday 2023?

First, let’s chat about when Small Business Saturday falls. This year, the event will fall on November 25th, but remember that the date can vary from year to year. So you’ll want to make sure you mark your calendars for this year! There are many reasons that you should get ready for this event now.

When it comes to smaller enterprises, even a little bit of exposure may go a long way. Small Business Saturday is the best opportunity you’ll have all year to showcase your own small business as well as the others in your town.

In the United States, the Saturday following Thanksgiving is designated as “Small Business Saturday,” which is an event that takes place annually. After the worldwide recession of 2010, American Express was one of the first companies to pioneer this practice, which is now widely used throughout the United States and the rest of the world.

This way, you’ll have time to prepare and promote your strategy. Otherwise, you might not have enough time to get everything together before the big day. And because Small Business Saturday is just around the corner, you will want to ensure that you’re prepared. You don’t want to wait until the last minute to start promoting your event.

Strategies to Prepare Your Small Business

Make sure your social media presence is on point

good quality content for social media

First and foremost, you’ll want to ensure that your social media presence is on point. This includes your posts, images, and overall social media presence. You want to make sure that your posts are consistent with your business and that they are also appropriate for your audience. Now, you don’t have to post on social media every day.

Limit your posts to once a week or every two weeks. This way, your posts will be consistent but not overwhelming to your audience or followers. You can also use images to your advantage. Not only do images help engage your audience and customers, but they’re also essential for posting on social media.

Host an exclusive sale for Small Business Saturday

sales selling commerce cost marketing retail sell concept
Sales Selling Commerce Cost Marketing Retail Sell Concept

If you’re hosting an exclusive sale for Small Business Saturday, you will want to ensure that you advertise this sale on your social media pages and other marketing outlets. Ensure you also include start and end dates to avoid customer confusion.

If you have a brick-and-mortar store, consider putting up signs inside your store to promote your exclusive sale. Make sure that your signs are clear and concise. You can also create a page on your website to host your exclusive sale. This way, potential customers can learn more about the sale and even sign up for an email list to get additional information about the sale.

Create a printable shopping list

master card match list

You can create a printable shopping list to entice your customers to shop at your store. This shopping list will include products or items you sell at your store. You can post this list on your social media pages or your website.

The great thing about a printable shopping list is that it can apply to any business, regardless of industry. It can be used for small businesses, major brands, and everything. You can even make the shopping list interactive.

You can ask customers to check off which items they’d like to purchase. Or you can ask them to comment on what they’d like to purchase. This will help you gauge what your customers are interested in purchasing at your store.

Offer free delivery or handling for Small Business Saturday

You can offer free delivery or handle on Small Business Saturday if you want to entice customers to shop at your store. This is an excellent way to show customers that you care about their purchases and overall shopping experience.

You can also consider offering free delivery to customers who spend a certain amount of money or who purchase certain items. Or you can offer free delivery on certain items at your store.

Free delivery or handling is a great way to entice customers to shop at your store. They’ll know that you care about their shopping experience and want to make it as easy as possible.

Get creative with your marketing and advertising

Now, when it comes to getting creative with your marketing and advertising, you can do various things. You can write blog posts about why you Shop Small or support Small Business Saturday. You can also consider sharing stories from your customers. You can also write and publish customer reviews.

Don’t just write reviews from customers who love your products and services; also, get customer feedback from less than satisfied people. By getting creative with your marketing, you’ll be able to engage your audience in a new way and show that you care about your customers.

Create a Small Business Saturday sale

Last but not least, you can create a Small Business Saturday sale. You can decide how long your sale will last. It may last through the entire month of November. This way, customers know you’re hosting an ongoing sale throughout the month. You can also consider offering free shipping on all orders for a duration of time.

This is another great way to entice customers to shop at your store and to support small businesses. You can also consider offering a percentage off certain items at your store. You can even consider hosting a contest where customers can win discounts or free items.

Conclusion

Now that you have an idea of what Small Business Saturday is, you can prepare for when it rolls around again, and give yourself ample time to implement your marketing strategy. Later this year will be an an excellent opportunity to attract new customers and get your brand name out there.

You can do this by providing amazing deals and discounts, hosting events in-store, or even offering free delivery on purchases. It is never a bad time to prepare for Small Business Saturday. If you follow these tips, your business will be thoroughly prepared for the upcoming shopping event.

JPMorgan

Mastercard and JPMorgan Launch Pay By Bank-Streamlining ACH Payment

In the world of payments, the need for efficiency is greater than ever. Transactions, where someone hands a cashier a bill and receives change, are not only slow, but they’re also expensive. That’s why more businesses are adopting digital payments as an alternative to cash, cards, and coins.

Between mobile wallets like Apple Pay, Google Pay, and Samsung Pay, contactless payment methods like EMV-enabled stickers and NFC-enabled POS terminals, and peer-to-peer payment apps like Venmo and Zelle, consumers now have plenty of options when it comes to making fast, frictionless payments. Unfortunately, the same cannot be said about the numerous third-party processors that must get involved for many of these services to work seamlessly together.

To address this gap in the market for streamlined payments between financial institutions and merchants, known as “last mile logistics,” JPMorgan Chase launched a new Pay by Bank program.

What is Pay By Bank?

Pay By Bank is an initiative from JPMorgan Chase that allows merchants to accept credit card payments through the bank’s payment gateway. Instead of using merchant services provided by a third-party processor, businesses with a Chase account can use this new feature to accept payments from Chase cardholders without ever having to touch a credit card.

Pay By Bank allows Chase cardholders to pay with their bank account rather than a credit card, making for a seamless and frictionless payment experience. While the feature is currently only available for Chase cardholders, Pay By Bank also has the potential to streamline payments for people who don’t bank with Chase.

How Does Pay By Bank Work?

When Chase customer uses Pay By Bank to make a payment, their funds are instantly transferred from their bank account to the merchant. Card data is never stored on the merchant’s POS system, and no transaction details are ever transmitted to Chase.

Using tokenization, Pay By Bank generates a unique payment code for each transaction. This tokenized payment method means merchants never receive customer account information, providing added security and privacy. Payment codes are generated when a customer initiates a transaction, so they can’t be used again.

Because Pay By Bank processes funds directly between a customer’s bank account and the merchant, it doesn’t require card readers or NFC terminals. Merchants can accept payments from all customers, regardless of whether they have a credit or debit card.

Benefits of Pay By Bank

Pay By Bank
  • Instant, real-time payments – Unlike credit cards, funds move directly from a customer’s bank account to a merchant’s bank account in real-time. This means businesses don’t have to wait weeks to receive payment, and there’s no risk they’ll be charged a fraudulent charge
  • No risk of chargebacks – Unlike credit cards, bank-to-bank transfers don’t require a customer to dispute a charge. This means there’s no risk of chargebacks, which can greatly reduce the profit a business makes from each sale
  • No need for card readers or NFC terminals – If a customer doesn’t have a credit or debit card, they can still use Pay By Bank to make a payment. This eliminates the need for card readers or NFC terminals, which may be incompatible with certain devices, such as Apple devices

Drawbacks Of Pay By Bank

  • No rewards or cash back – Unlike credit cards, Pay By Bank offers no rewards, cash back, or frequent flyer miles. This means businesses that offer products and services that are often purchased by frequent travelers, such as airlines and hotels, will have to find other ways to incentivize customers
  • Limitations on certain services – While credit cards can be used to purchase just about anything, Pay By Bank is limited to online and phone purchases. This will make it difficult for businesses that rely on in-person sales to accept payments
  • Requires a Chase account – While Pay By Bank is a convenient way for Chase customers to make payments, it’s not an option for people who don’t use this bank

Is Pay By Bank A Good Solution For Your Business?

Suppose most of your customer’s bank with Chase, Pay By Bank is likely a good solution for your business. However, if most of your customers bank elsewhere, Pay By Bank may not be a good choice. Instead, consider a partner processor that offers many payment options, including bank-to-bank transfers.

Partner processors work with a variety of financial institutions to seamlessly accept payments from a wide range of customers. Partner processors also commonly offer a variety of value-added services, such as automated fraud detection and chargeback mitigation, that help merchants keep costs low and profit margins high.

When it comes to regular payments like rent, utilities, transactions to the government, education, insurance, and universal healthcare, where ACH is counted as the principal payment channel, Pay-by-Bank has a significant amount of untapped potential that billers may leverage to make life easier for their customers.

Billers whose customers already paid with ACH can integrate the Pay-by-Bank solution offered by J.P. Morgan on their current payment page. Customers can choose to “Pay-by-Bank” when they are checking out. At this point, they could be urged to discover the bank, verify themself using the authentication process that is familiar to them from their bank (such as a biometric scanner), and share their account details with JPMC so that the payment can be processed on the biller.

This year, J.P. Morgan, as well as Mastercard, are managing their Pay-By-Bank service with a limited number of merchants and billers in the United States. They anticipate expanding the service in 2023.

Conclusion

Pay By Bank is a new and convenient way for Chase cardholders to make payments. While this feature will likely appeal to many customers, it’s not an option for those who don’t bank with Chase. If most of your customers bank with Chase, Pay By Bank will likely be a good solution for your business.

Open banking allows businesses and individuals to share their information safely. These experiences range from new payment methods to protection and zero-friction giving, bringing the pledge of digitalization to more individuals. Pay-by-Bank is another innovation that open banking has made possible.

With the purchase of Vocalink in 2017, Mastercard was able to bring its years of experience and knowledge in the payments industry into account-based transactions. However, if most of your customers bank elsewhere, Pay By Bank may not be a good choice. Instead, consider a partner processor that offers many payment options, including bank-to-bank transfers.

Shift4 Launches New Payments Platform

Shift4 Launches New Payments Platform for eCommerce Businesses

As the market for eCommerce continues to grow, there are more opportunities than ever to set up an online store and sell your products directly to customers. However, with so many different platforms available, finding one that is right for you and your business can be tricky.

If you’re considering setting up an eCommerce store, you will need a platform that makes listing your products and handling payments easy. There are plenty of different eCommerce software options out there, but not all of them will meet all your needs as a small business owner. Now, Shift4 launched its new payments platform for eCommerce businesses which can be a game changer.

In this blog post, we’ll look at why shifting from the traditional eCommerce model is so important for businesses today and why the Shift4 Platform is great solution if you want to move fast, grow big, and stay lean.

Importance of eCommerce

To better understand why eCommerce is so important today, it’s worth taking a brief look at online shopping history. Shopping online has become increasingly popular over the past few decades, but it wasn’t until the 1990s that online retail started to take off.

Early online merchants like Amazon and eBay set the standard for eCommerce, with customers able to browse products online and pay for them conveniently and easily. With the rise of mobile internet access, online shopping has become increasingly convenient, with consumers able to shop from anywhere at any time.

Moreover, a report by The Boston Consulting Group found that online consumers will increase by 50% over the next five years, which is great news for online merchants. All of these factors make online shopping an incredibly important part of the retail sector, with eCommerce growing at a rate of about 18% each year.

Right Platform for Your Business

As you’re looking for the best eCommerce platform for your business, there are a few key things that you should look out for. Firstly, you must ensure that your chosen platform has a great user experience that enables you to build your store quickly and easily.

This will enable you to get your store up and running as quickly as possible, especially if you plan to sell products during the holiday season. You will also want to ensure that your chosen platform is designed for scalability. This is important for two reasons.

Firstly, you should ensure that the eCommerce platform you choose is reliable and robust so that your sales don’t suffer from any issues with the platform you’re using. Secondly, the more customers you attract to your platform, the more sales you can make. An eCommerce platform that is designed for scalability will be able to handle the increased traffic that will come as your store grows and expands.

The newly released online payments platform from Shift4 enables businesses to quickly and easily develop a checkout page that can be personalized according to their needs and integrated on any site page by using only a few lines of code. The user interface of this form is straightforward and optimized for use on mobile devices. It also supports many card kinds and more than 160 different currencies.

In addition, it is compatible with a diverse selection of payment models, such as one-time payment, part dependent and subscription, hybrid billing models that include both one-time fees and monthly rates, and variable pricing for pay-per-use pay-per-user marketing strategies. The platform also has sophisticated anti-fraud technologies that can protect companies from chargebacks and stop fraudulent transactions.

3 Tips to Grow Your eCommerce Business with Shift4

If you’re thinking of setting up a new eCommerce business, there are a few things that you can do to ensure that your store is a success. Firstly, it’s important to ensure that your store is easy to navigate and that users can quickly and easily find what they’re looking for quickly and easily.

You will need to spend some time on your product descriptions, making them as detailed and attractive as possible so that potential customers will be drawn to your products. Secondly, you will need to work hard to build your brand.

This will help set you apart from your competitors and give your store an identity that will attract new customers. Finally, you will need to keep growing your sales as your store expands. This means you must keep investing in your marketing efforts to attract more customers and keep your existing customers happy.

Shift4 Platform benefits

The Shift4 eCommerce platform offers several benefits for businesses of all sizes and industries. One of the most important advantages of using the Shift4 platform is that it’s easy to start. This means that you can set up your store quickly to start selling your products as soon as possible.

The Shift4 platform is also fully customizable, so you can change your design and add new features as your business grows. Another advantage of the Shift4 platform is that it is easy to scale up.

As your business grows and you start attracting more customers, you can easily increase your capacity to handle larger orders and more traffic. The Shift4 platform is secure, so your customers can shop confidently, knowing their data is protected.

Shift4: Great Choice for Small Businesses

Shift4 eCommerce payment platform launched
image source

Overall, the Shift4 eCommerce platform is a great choice for small businesses. It’s easy to start, so you don’t have to worry about long-term contracts or tricky setup procedures. It also offers several great features that will help you to sell more products, from marketing tools to payment options.

Finally, the Shift4 platform is scalable, so as your business grows, it will be ready to handle more traffic and larger volumes of orders without any problems. Overall, the Shift4 platform is a great choice for small businesses that want to get started selling their products online quickly and easily.

Conclusion

If you’re a small business owner looking to set up an online store, it’s important to make sure that you choose the right eCommerce platform. It’s best to find a platform that is easy to use and customize, offers great functionality, and is scalable so that it can grow with your business. The Shift4 eCommerce platform is a great choice for small businesses, offering several benefits, such as a user-friendly interface and easy setup.

The importance of maximizing profits cannot be overstated, particularly in light of the current uncertain economic climate. People look at their bottom lines when things are tight, as Itzkowitz put it. By doing so, they aim for new levels of efficiency and place emphasis on the use of automation to achieve this goal.

According to the three executives who spoke with PYMNTS, platforms are necessary for optimizing integrations and embedding services into software that manages customer relationships. This enables businesses to concentrate on their primary operations.

Credit Card Security Risks for Small Businesses

Credit Card Security Risks That Small Businesses Should Be Aware Of

As a small business owner, it is crucial to accept credit card payments to stay competitive and meet consumer preferences. However, doing so also exposes you to potential credit card security risks for small businesses. You can reduce these risks to avoid costly mistakes such as lost revenue, stolen customer information, and fines.

One way to do this is to stay informed and know the rules regarding accepting credit cards. Additionally, you should pay attention to any simple security risks in getting credit cards for small businesses that could have severe consequences. To protect your business and customers, it is essential to be proactive and understand the risks involved in accepting credit card payments in person.

Credit Card Security Risks for Small Businesses that Should be Aware of

credit card

Counterfeit Credit Cards

As a business owner, it is essential to spot counterfeit credit cards, especially when dealing with a big line of consumers. Fake credit cards may include extensive scratches or damage to the barcode. Another red flag is if the numerals are crooked or do not line up as they should, indicating that perhaps the card is a forgery.

Educating yourself and the staff about the appearance and feel of a credit card is critical. This will assist you in identifying a fake when you come across one. Additionally, look out if the user says their card’s chip isn’t working and ask for ID before you manually run it.

Also, pay attention to the card’s magnetic strip. If it’s scratched or damaged, it could be a sign that the card is fake. In case of any doubt, call the bank on the card’s back to confirm the authenticity of the credit card.

Staff Error

It’s crucial to ensure that you and your staff are appropriately trained in handling credit card transactions to avoid potential fraudulent transactions and legal action. Not being adequately trained can leave your business vulnerable to these incidents.

When taking credit card payments, it is critical to understand how to manage credit card data fully and to comprehend what is and is not permissible. You have a duty as a business owner to do all possible to protect your client’s data, not just for the good of your company but also due to the law.

Effective employee training programs can help to show employees how to handle credit card data and recognize fraudulent transactions. They should also be aware that not all security risks in accepting credit cards for small businesses come from outside the company’s walls.

According to a study by the Ponemon Institute, 54% of data breaches are caused by employee negligence. This highlights the importance of investing in a secure network, regular password updates, and implementing a separate Wi-Fi network for guests and a top-of-the-line firewall.

Cash Refunding

Correctly processing credit card returns is crucial for your business to avoid financial loss. One critical thing to remember is that if a customer purchases a credit card, they should get a refund back to the card and not in cash. This is because many businesses tend to allow customers to buy a credit card and get back the product for money instead of refunding it to the card.

This can lead to issues, such as the original purchase using a stolen card, that fraudsters return the products to get cash. It’s a common tactic used by fraudsters to take advantage of businesses unaware of this scenario.

It’s essential to be vigilant and have a process to check for suspicious returns or refund requests. This may include asking for identification, comparing the rescue with the original purchase, monitoring for patterns of suspicious behavior, and educating your staff on how to recognize and handle potential fraudulent returns is crucial. Doing so can protect your business against financial loss and possible legal action.

Missing Signatures

When processing credit cards in person, missing signatures can pose a security risk. Many card networks no longer require signature verification for firms that use an EMV-compliant reader for credit cards.

Customers may still be required to sign a ticket when adding a gratuity in some circumstances, such as restaurants. Businesses that don’t have an EMV card machine may also run cards manually.

When accepting credit cards, it’s usually a good idea to ask for identification to safeguard the security of your company and your clients. In these situations, or when there is suspicion, it is critical to look for a signature on the card’s reverse side and request identification.

This is particularly important for smaller businesses, as larger companies may sometimes have strict protocols.

Point-of-Sale Skimming

Skimming is a form of credit card fraud where an employee or a fraudster uses a device to copy the card information. One of the ways it can happen is through POS tampering, where a skimmer is installed on an existing terminal; it’s quick and easy to do.

The most dangerous form of skimming is when criminals pose as representatives of your bank or processing company, replacing your equipment with a clone that transmits the card information directly to them or stores it until they return for the device. Monitoring your POS device for indications of manipulation and keeping it visible to consumers is essential if you want to prevent this kind of skimming.

One solution is to use a mobile card reader that allows servers to collect payment at the table or to ensure the card never leaves the customer’s sight. Additionally, never leave your processing device unattended during business hours, and regularly inspect it for any changes. Be wary of anyone claiming to be a representative of your bank or processor, and always call to verify their identity.

Conclusion

Accepting credit card payments may seem daunting, but it can be manageable by being aware of credit card security risks for small businesses and using good judgment. The benefits of accepting credit cards far outweigh the risks, but it’s essential to keep in mind that the threats may evolve as technology and consumer behavior change.

It’s crucial to adhere to industry security standards, keep staff members educated and trained, and invest in a reputable credit card processing business that will safeguard your data if you want to stay safe. By preparing your industry and remaining vigilant, you can enjoy the rewards of accepting credit cards while minimizing the risks.

gps tracking

Best GPS Fleet Tracking Software for 2023

Nowadays, you can’t operate a business fleet with optimum efficiency and productivity unless you have a GPS fleet tracking software. Not only will you be able to watch your vehicles in real-time with this fleet management software, but the top GPS fleet tracking systems right now can monitor drivers’ behavior, examine fuel efficiency, generate automatic reports on what’s happening across the fleet, and more. You’ll be able to reduce fuel expenses, enhance customer service, and use analytics to help your company expand.

Stick with us, as we’ve made this research to make it easy for you to choose the right GPS fleet tracking software that’s out right now. This article is for smaller business owners, fleet managers, and larger organizations who want to monitor and manage their cars and trucks using a GPS fleet monitoring system.

What is GPS Fleet Tracking Software, and Why do You Need it?

GPS fleet tracking is a management system organizations in transport-related industries commonly use to track corporate assets such as cars, equipment, and drivers. GPS fleet monitoring systems, often known as telematics, allows businesses to track where their equipment and products are in near real-time while also delivering vital data about driver and fleets performance. Knowing what a telematics system is allows you to understand how it can assist your company saves money (such as on fuel), controlling vehicle maintenance, supervising your mobile workforce, and ensuring driver safety and compliance.

How to choose the right GPS Fleet Tracking Software for you

GPS Fleet Tracking Software for 2022

Even though most of the GPS fleet tracking systems appear almost the same, they frequently contain unique characteristics that can make or break your fleet. Therefore carefully consider your options to find the ideal telematics solution for your company.

Specify what needs to be tracked

The first thing you need to do before selecting a GPS fleet tracking software is to determine the sorts of assets and vehicles you need to monitor and the number of each. Since different forms of tracking gear will be required based on what you are tracking, determining the sorts of vehicles and assets will help you limit your potential possibilities. Some companies, for example, provide relatively limited tracking accessory options, and many GPS brands need a minimum number of cars. These are minor numbers (three with Samsara), but we prefer brands with no minimum fleet size restriction (GPS Trackit).

Choose the features you need from the GPS tracking fleet software

Once you’ve finished the first step, you must decide why to track them. GPS fleet tracking systems differ in feature sets, so determine which essential and negotiable functions.

For example, suppose driver’s safety is your priority. In that case, you need to look for a solution that includes driver’s scorecards, vehicle safety and maintenance warnings, dashcams, geofencing, and driver training and coaching. Less comprehensive choices may be preferable if you only need to track the position of nonpowered assets and equipment.

Set a budget

GPS fleet tracking solutions are frequently expensive to purchase. You must first buy the hardware and then pay a monthly subscription price for the software. Although, some monitoring systems provide tiered subscriptions with varying feature sets, which can help you save money if your tracking requirements are low.

After determining the required features, create a budget and search for telematics solutions that fit your budget. Budget concerns include contract terms, vehicle minimums, free trials, and software and hardware expenses.

Best GPS Fleet Tracking Software for 2023: Review

Verizon Connect

Verizon Connect is our top pick for the best GPS tracking software. Firms with a narrow focus will appreciate the great amount of customization it provides. For example, you can change the word “vehicle” to “crane” to match industry-specific terms.

It is possible to overlay GIS data, such as power lines and sewage pipelines, on the company’s customized maps (rather than the standard Google Maps utilized by many rivals). Although it takes some time to perfect, this degree of granular control outperforms most rivals.

Pros

  • Its driver performance scoring identifies who is performing well and who requires guidance
  • Allows for simple integration with third-party navigation devices
  • There is no installation charge
  • A fantastic alternative for bigger fleets and vehicles

Cons

  • Signs you up for lengthier contracts than other vendors (typically three years)
  • Only the more costly subscriptions provide fleet maintenance data

Samsara

Samsara is among the most sophisticated GPS monitoring solutions available on the market, with industry-specific plans tailored to your specific requirements. It also provides one of the most extensive collections of tracking accessories and hardware, allowing you to pick the devices you require to track your fleet. Samsara is among the few organizations that provide real-time tracking and reporting, which is critical for many small enterprises.

Pros

  • Every 30 to 60 seconds, the tracking data is refreshed
  • Its dispatch feature immediately picks the optimal vehicle for a job, enhancing real-time efficiency
  • It’s the best bang-for-your-buck solution

Cons

  • It’s not the cheapest option out there
  • Its average contract periods range from three to five years

Azuga

Azuga is among the most user-friendly GPS fleet tracking solutions, with bundled and customizable plans available. It’s based on OBD-II plug-and-play monitoring hardware, one of the simplest-to-install device types. We found the Azuga mobile app and dashboard to be intuitive and simple, and some plans also offer chat options to let management and drivers communicate inside a single platform.

Regarding tracking, Azuga is tied for second with Samsara, with the sole drawback being that its warnings aren’t as comprehensive as those on other platforms. One of its most distinctive features is the option to tailor refresh time from 30 seconds to 59 minutes, allowing the drivers to operate with as much or as little supervision as they want.

Pros

  • Its FuelSaver add-on advises vehicles to the nearest gas station with the most affordable fuel
  • ELD compliance is possible (though at an additional cost)
  • Its travel logs provide full data of all journeys taken in the previous 90 days
  • WEX, PAPCO, and EFS all provide fuel card integration

Cons

  • It does not offer accident reporting
  • Only firms with more than 30 cars are eligible for a free trial
  • A maintenance schedule function is paid for separately, although other systems provide it for free
  • It doesn’t measure the cargo temperature

GPS Trackit

GPS Trackit is a fleet management system with outstanding reporting capabilities. It enables managers to trace their fleets via breadcrumb tracking, updated every 30 to 60 seconds. With insights into maintenance records, engine diagnostics, service history, and expenses, you can receive information on diverse fleet data and optimize vehicles. These reports can be automated to make the reporting process easier. Real-time interactive maps, current weather, live traffic, and street-level views are available. Also, heat-sensitive cargo items can be remotely monitored.

Pros

  • Data is refreshed every 30 to 60 seconds
  • Fuel card integration is possible
  • ELD compliance is offered for an additional cost

Cons

  • More costly than other alternatives
  • Does not track weather updates to aid in route planning
  • Does not monitor fuel consumption in the absence of integrated fuel cards
  • Driver dispatching options are only accessible with a fee

Teletrack Navman

Teletrac Navman is a very good GPS fleet management system for vehicle maintenance. It provides solutions by industry and role, with a selection of hard-wired and plug-and-play devices, allowing you to select the tracking option that best meets your vehicle or asset tracking needs.

Pros

  • You can record distance while concealing your location, allowing you to keep trips private
  • Sends stolen car notifications to assist you in responding immediately to theft
  • Daily driver vehicle inspection records are captured (DVIRs)
  • Integration with ProMiles ensures that you comply with IFTA and DoT requirements

Cons

  • It does not offer accident reporting
  • Contracts automatically renew, making cancellation more difficult
  • The most affordable plans are severely constrained, with fewer features and slower data refresh (every five minutes)
  • It does not monitor the temperature of the engine or the load

What to look for when choosing the right GPS Fleet Tracking Software

  • Price – GPS fleet tracking software prices generally comprise a one-time fee for each hardware device and a monthly subscription fee for tracking features. Pricing for a single hardware device starts at about $100, with monthly subscriptions ranging from $15 to $35
  • Tracking – How reliable and efficient is the tracking feature on the platform? For example, how fast does the tracking map refresh, and does the map consider the traffic jam, etc
  • Vehicle management – Examining the condition of your vehicles. Are they in need of repair? Are they adequately secured against theft?
  • Driver’s management – Tracking and recording each of your drivers’ actions. Is Driver #3 idling his car for an excessive amount of time? Is Driver #4 prone to speeding?
  • Product Features – What more is the product capable of? Can it communicate with third-party navigation systems? Is there a mobile app?
  • Customer support – Which company has the best customer support to help you whenever you need them?

Conclusion

While there are several aspects to consider when researching vehicle monitoring solutions, we hope that by reading this article, you’ve learned what GPS Fleet Tracking Software is, why you need it and how to choose the right one for you.

Although numerous alternative providers are available, Verizon Connect is the most popular in terms of overall features, vehicle management, excellent tracking, and driver management functions.

Payment Stack

How To Simplify Your Payment Stack

The world of payments is changing. New digital-first competitors like Apple, Google, and Samsung have been quick to become major players, while others like PayPal, Venmo, and Square are growing in popularity with millennials.

Even if you’re just starting your payments journey, the sooner you simplify your payment stack, the better off you’ll be later on. Here are some ways to make your payment stack simpler and fast.

Consumers expect frictionless experiences and are more conscious than ever about their personal data privacy, which means you have to get smarter about building your payment infrastructure. Let’s face it: Your existing payment stack is probably complicated. It might involve many point-of-sale (POS) terminals, stored value vendors such as Google Wallet or LevelUp, a financial institution for issuing virtual accounts, a payment gateway for online transactions, and more.

What is a Payment Stack?

A payment stack is the entire process of taking card payments for your business, from the initial customer interaction to the final settlement of funds. It involves all the companies and technologies that enable you to process payments, whether online or offline, with plastic cards or other forms of payment, such as app-based virtual accounts.

A stack refers to the relationship between the players that make up the overall payments ecosystem. When you buy a new house, you must choose a mortgage company, an insurance company, a real estate agent and a contractor, and then coordinate your tasks with theirs. It’s a process that can also apply to building out payments infrastructure.

How To Simplify Your Payment Stack?

Simplify Your Payment Stack

Consolidate your POS devices

If you’re running a brick-and-mortar business, your POS devices most likely run on software from companies like Square or Intuit. While these devices are cost-effective, they may not provide the best experience for your customers. Why not use a more robust solution that provides a better overall experience for you and your customers?

One option is to partner with a cloud-based POS provider to host your payment system. This allows you to ditch your physical terminals and provides a high-quality digital customer experience on your website or mobile app.

Separate payment responsibilities

If your business grows quickly, you might rely on a third party for fraud detection and chargeback management. While many third-party services can help with this, it’s important to remember that they have your sensitive data, like customer card data and sales reports. That means you must build an extra level of trust with your vendor of choice and thoroughly vet them before entering into a long-term contract.

Reconciliation and settlement

The number of your company’s purchases will become overwhelming as it grows. The process of reconciling payments ensures that all fees paid are recognized and processed appropriately.

Payment reconciliation is essential for businesses since it safeguards against the loss of data and the omission or loss of entries or even receipts. It is highly recommended to use accounting software to maintain a record of each transaction that takes place not only within the organization but also outside of it.

Checking the records kept by the banks that were used in the transactions is how this is accomplished. If an error is made, all that is required to locate its origin is to cross reference your firm’s records with its bank statements.

Fraud prevention

fraud prevention

Fraudulent schemes keep advancing alongside the development of new technologies. It shouldn’t be a surprise that retail establishments and other types of enterprises are witnessing an all-time high number of data breaches.

Card fraud cases reached a staggering $28.65 billion in just a year, 2019. Due to the rise in fraudulent behavior, being able to monitor and identify fraudulent transactions has become an integral part of any payment stack.

Use a cloud-based payments platform

If your business processes many online transactions, you might use a payment gateway to facilitate those payments. Payment gateways are great, but they might slow you down as you scale and want to add new payment options like virtual accounts. Gateways are designed for large organizations and can be difficult to customize.

They also can lock you into using one specific set of payment routes and may not provide a robust set of analytical tools. On the other hand, a cloud-based payments platform can be scaled up quickly and easily to accommodate new payment types and partners. It also allows you to add new customer features, like a digital “Know Your Customer” section.

Diversify your portfolio of vendors

Every business is different, so that it might make sense to partner with more than one company for certain payments-related services. For example, if you have a physical store and accept payments via card swipes, you need a payment gateway that is EMV-compliant.

If you operate online, you might use a virtual account provider. If you sell products internationally, you might use a cross-border solution. As your business grows, you may be tempted to integrate all of these services into your stack fully.

During this process it’s better to be selective and choose single-purpose vendors that have already proven themselves in the market and have a proven track record of success.

Go digital with EMV chip technology

As the world’s payment systems evolve from magnetic stripe card readers to more secure EMV chip card readers, you may consider upgrading your hardware. But hardware vendors can be tricky to work with, especially if you’re looking for a quick and easy solution.

For example, you may want to issue virtual accounts to your customers. But the only option you have right now is to install a chip reader and a virtual account issuance device. This would require significant investment and a longer implementation timeline.

With a new payments platform, you can avoid many of these headaches by partnering with a vendor that offers a one-stop-shop solution. They can help you bring your payment infrastructure up to date with EMV chip technology without having to buy new hardware.

Conclusion

When it comes to payments, it’s critical to keep things simple. Simplifying your payment stack will allow you to focus on growing your business and delighting your customers, not managing the challenge of integrating and managing various vendors. At the same time, it’s important to remember that the payments landscape will continue to evolve.

New technologies and trends like digital identity, blockchain and artificial intelligence will play an important role in shaping the future of payments. For your business to stay competitive and relevant, it’s important to stay agile and keep an eye on what’s coming next.

what is customer to customer

What is C2C and How is it Relevant in 2023

The C2C business plan is now commonly connected with e-commerce and selling online platforms such as Craigslist and Etsy. Some C2C platforms, such as OfferUp, prioritize mobile shopping through applications. C2C, on the other hand, can apply to any firm that establishes a market amongst customers. In this article we’ll breakdown what C2C is and how it is relevant in 2023 and the years to come.

C2C enterprises include the classified ads section of a newspaper and an in-person auction house. C2C enterprises facilitate consumer relationships by locating and connecting consumers and vendors. They are especially beneficial in niche markets.

What is C2C or C-2-C?

Consumer-to-consumer (or, in some cases, customer-to-customer) is a business concept in which customers trade with one another, generally online. Auctions and classified advertising are two examples of C2C market implementations. With internet development and websites such as Etsy, eBay and Craigslist, the C2C business has grown in popularity.

Traditional marketplaces demand business-to-customer connections, in which a client visits the firm to buy a product or service. On the other hand, customer-to-customer marketplaces offer an innovative approach for customers to communicate and exchange assets.

C2C refers to a market setting in which one client acquires products from another customer via a third-party firm or platform. C2C businesses are a form of a business model that arose as a result of e-commerce technologies and the sharing economy.

How Does C-2-C Work?

What is C2C

Customers benefit from product competition and frequently find tough goods to buy elsewhere. Furthermore, sellers’ margins might be bigger than typical pricing techniques because there are no merchants or wholesalers. C2C websites are convenient since they eliminate the need to visit a physical store. Buyers come to sellers when they advertise their stuff online.

Fees charged to sellers for displaying products for sale, providing promotional features, and enabling credit card transactions are how C2C websites and similar platforms generate money. These C2C transactions often include selling secondhand goods via a classified or auction system.

Pros

  • Low cost – C2C has low operating costs. Because C2C platforms do not have to deliver goods, costs are kept to a minimum. This keeps supplier margins higher and buyer prices lower.
  • Time-saving – Customers can save time by searching for what they require online, from the comfort of their homes, rather than driving all over town.
  • Convenient for sellers – Sellers like the advantages that C2C marketplaces offer. If someone intends to sell a set of ancient books, they don’t have to find possible purchasers. Instead, they can enter a C2Cmarketplace and gain access to many potential customers.

Cons

  • Quality control – Quality control may be lacking in C2C transactions. Because the sellers are customers, there is sometimes minimal redress for defective or misleading items. Furthermore, because the purchasers are also customers, payment guarantees might be difficult to implement.
  • Credit card payments – Credit card purchases on some C2C sites might be tricky. Some sites may not accept or process credit cards. However, services like PayPal and Venmo are easing these difficulties.
  • Spams vulnerability – C2C sites can be riddled with fraud as opportunists seek to exploit others. Buyers should be aware of sellers who cannot answer specific queries concerning the things for sale. They should also avoid any salesperson who puts them under pressure to buy immediately. Many sites have extensive selling policies that, if broken, result in user bans.

C2C Companies Examples

Consumer-to-consumer

Craigslist

One of the oldest and most popular websites in the US that got mass approval is Craigslist. It is a job, housing, for sale, goods sought, services, community service, gigs, résumés, and discussion forum website in the United States.

It was founded in 1995 as an email distribution list for friends by Craig Newmark. San Francisco Bay Area was the main area of focus where it promoted local events. In 1996, it launched a web-based service and moved into other categorized categories. It began growing to additional cities in the United States and Canada in 2000 and serves more than 70 nations today.

With approximately 49.4 million monthly visitors in the U. S. alone, the site delivers more than 20 billion views every month, ranking it 72nd overall among websites globally and 11th overall among websites in the United States. Craigslist is the leading classifieds site in any medium, with over 80 million new classified adverts posted each month.

eBay

eBay is a global American e-commerce firm headquartered in San Jose, California, that enables consumer-to-consumer and business-to-consumer purchases via its website. eBay was launched in 1995 by Pierre Omidyar, and since then, it has become a prominent success story of the dot-com boom.

In 2019 it became a multibillion-dollar corporation in about 32 countries. The corporation administers the eBay webpage, an online auction and shopping platform where people and businesses worldwide purchase and provide a diverse variety of goods. Customers can use the site for free; however, after a limited number of free postings, sellers are charged fees for listing products after a certain amount of free listings and a separate or additional cost when those items are sold.

Buying by Universal Product, ISBN, or another type of SKU number, in addition to the quick “Buy It Now” purchase, many other services have indeed been introduced to eBay throughout the core auction-style sales.

Previously, eBay’s services included online transfers of money (through PayPal, an entirely subsidiary between 2002 to 2015), free advertising listings (through Kijiji or eBay Listings Company), and online event ticket trading (via StubHub).

Etsy

Etsy is a worldwide marketplace for one-of-a-kind and creative items. It houses a variety of unique, amazing goods, ranging from handmade creations to vintage treasures.

Their objective is to retain human interaction at the core of trade in an age of rising automation. They’ve created a space where creativity can thrive since people fuel it. They assist their seller community in turning their ideas into enterprises.

Etsy’s network links them with millions of shoppers searching for an alternative, something exceptional with a personal touch, for occasions that call for a little more creativity.

Why is C2C Relevant in 2023?

The C2C business model is still relevant in 2023 because it took a swing in the beginning and during the pandemic and didn’t seem to stop.

Companies can now develop C2C markets on an unprecedented scale thanks to the internet. According to McKinsey, the pandemic boosted the C2C trend in Europe since so many individuals took the opportunity to get rid of useless items. Furthermore, because buyers prefer sustainable products, sustainability concerns may fuel additional C-2-C growth.

Because of its low cost, the C2C business is expected to develop and grow more. The cost of utilizing third parties is decreasing, while the quantity of items available for sale by customers is continually increasing.

Because of the prominence of social media and other internet platforms, retailers consider it a crucial business strategy. These channels highlight specific items that customers already own, increasing demand and driving increased web traffic to C2C platforms.

Conclusion

Companies can now develop C2C markets on an unimaginable level thanks to the internet. Due to the fact that so many individuals took the opportunity to sell undesirable belongings, the pandemic intensified the C2C trend in the US and Europe.

Furthermore, because customers prefer green solutions, sustainability concerns may fuel additional C2C growth. One thing to remember is that constructing a C2C platform is frequently unfeasible for SMBs because the business strategy frequently needs having or building a large audience.