
Posted: November 10, 2026 | Updated: November 12, 2026 at 4:03 PM
US businesses have to complete two year-end reports, Form 1099-NEC and Form W-2. While the W-2 reports employee wages, the 1099-NEC reports payments made to independent contractors. Both forms W-2 and 1099-NEC deadlines are due by the last day of January.
January 31, 2027, falls on a Sunday, so both forms must reach the government by Monday, Feb. 1, 2027. Also, for tax year 2026, Congress lifted the 1099-NEC reporting floor to $2,000, up from $600. In addition, the IRS will not accept 1099-NEC forms through FIRE starting with the 2027 tax year. As a result, the IRS will only accept 1099 forms through the IRIS system.
The January date encompasses four transmissions. Employers hand each worker a W-2, then file Copy A with Social Security. Businesses give contractors their Forms 1099-NEC and send the IRS copies. Employers filing on paper mail Copy A together with a W-3 transmittal. Paper Form 1099 filers give the IRS Form 1096 and Forms 1099.
If January 31 lands on a Saturday or Sunday, the IRS pushes the deadline forward to the first weekday that follows. In 2026, the IRS gave employers until February 2 to submit W-2 copies. In 2027, the IRS moved the date to February 1. Payroll employees typically submit the fourth quarter Form 941, the fourth quarter Employer’s Report of Tax Liability and the transmittal forms, and employee W-2 copies on the same day.
Employees receive a W-2 each year after taxes are withheld from their pay. For wages paid in 2026, a business must also issue one to any employee whose pay reached at least $2,000, even if taxes were not withheld. That cutoff was $600 before Public Law 119-21 raised it in July 2025. Fees paid to contractors are not reported on a W-2.
The SSA, short for Social Security Administration, receives Copy A. That wage data is then shared with the IRS. Employees receive copies B, C, and 2. These copies may also be provided electronically if the employee agrees to receive the form via this method.
Extensions are available but are rarely given. The IRS no longer automatically grants a 30-day extension for the filing of W-2 forms. The IRS states that extensions may only be granted in cases of disaster and/or the death or illness of the person responsible for filing. A 30-day extension for the SSA copy may also be granted if Form 8809 is completed. Additional time for the employee copies requires a request be made directly to the IRS.
The 1099-NEC captures what a business pays to people outside its payroll. Non-employees include independent contractors and consultants. Before 2020, these contractor fees went on Form 1099-MISC. Starting with 2020 taxes, the IRS moved them to their own form, the 1099-NEC.
Beginning in 2026, there will be a change in the reporting threshold. According to the Settings-Adjustment Act of 2025, which was signed on July 4, 2025, the reporting threshold will increase to $2,000 from the previous amount of $600. Starting in 2027, the threshold will be adjusted for inflation. For 2026 payments, a threshold of $2,000 means that payment to a contractor must be reported to the IRS, with a copy going to the contractor. A contractor paid $1,500, or any sum under $2,000, needs no form. Payment to corporations is exempt from the $2,000 threshold; however, payment to lawyers is always reported to the IRS.
Contractors get their 1099-NEC on the same schedule that employees get their W-2. For 2026 payments, contractors must receive their copies by Feb. 1, 2027, which is also when the IRS copy is due. Extension requests for the form can be made to the IRS using Form 8809. The requests are reviewed on a case-by-case basis.
Under T.D. 9972, issued in February 2023, the cutoff for mandatory e-filing of these forms dropped to 10 from 250. This decision will impact returns due in 2024. According to IRS Topic 801, the combined total of information returns, W-2s included, is what counts. With 6 employees and 4 contractors, a business would have to file 10 information returns and report them all electronically.
There are a few exceptions to the combined total. First, the count is per filer for each information return type. Second, penalties can be assessed for filing above the threshold. According to the Intuit ProConnect Tax Center, section 6721 penalties can be assessed against businesses for paper W-2 filing above the threshold. Form 8508 can be used to request relief from the e-file mandate. Form 8508 requests must be filed at least 45 days before the return due date.
Social Security Administration Business Services Online (BSO)
BSO provides an electronic filing service for W-2s. Employers can create an account to upload a wage file or key W-2s into an online screen. The service is free.
IRIS: The IRS Online Portal for 1099s
IRIS is the IRS website for filing 1099 series forms. Smaller batch filings are done for free via the web and larger batch filings are done for a fee via system-to-system service. The IRS has stated that after 2026, it will stop taking filings through the FIRE system, and all 1099 series returns will be filed via IRIS.
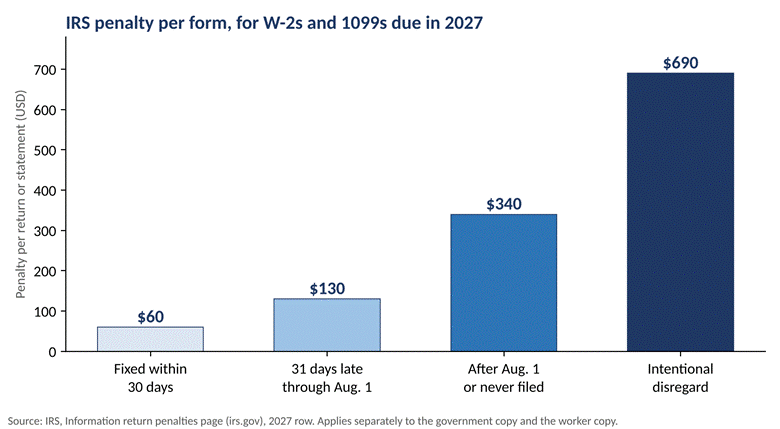
Per-form penalties can be found in sections 6721 and 6722 of the tax code. The penalty for the government’s copy is codified in 6721, and the penalty for the employee’s copy is in 6722. As stated in the IRS’s penalty website, they charge both penalties separately, so a single late W-2 can be hit twice.
Each W-2 filed up to 30 days past the due date costs $60. Penalties increase to $130 if the forms are submitted between 31 days and August 1. If the forms are submitted August 2 or later, or if the forms are not submitted at all, the penalty increases to $340. If it is determined that a person willfully neglected to file the forms, the charge rises to $690. This penalty can be applied to each form that person neglected to file.
The penalties listed in this document for forms filed in 2027 replace the penalties for forms filed in 2026. The penalties for forms filed in 2026 were $680 for willfully neglecting to file.
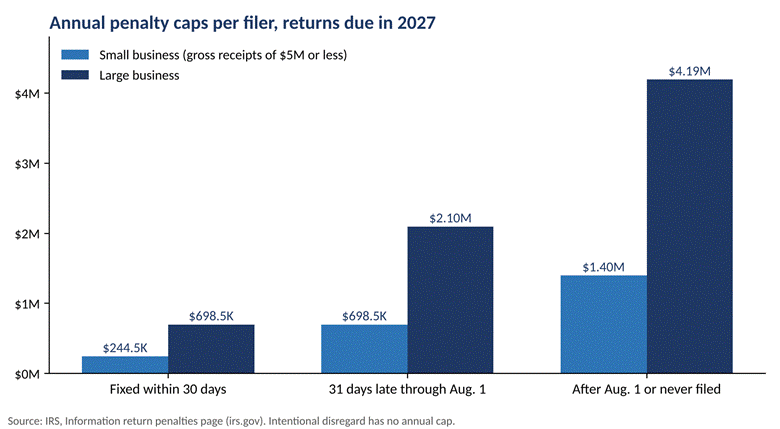
Annual limits usually apply to caps. Under section 6721(d), the IRS defines a small business as an entity that, on average, has annual gross receipts no higher than $5 million in the last three years. Lower limits apply to small businesses. The IRS has the discretion to waive penalties for reasonably stated circumstances beyond the entity’s control.
Although there is no set deadline to correct W-2 forms, the IRS expects that, upon discovery of an error, an employer will prepare and file Form W-2c to fix the mistake and prepare and hand the affected employee their copy. While there is no set deadline to correct W-2 forms, the IRA states that the penalty amount climbs once the corrected form arrives past the 30-day mark following the original due date. The penalty amount will remain $60 if the corrected form is filed within 30 days of the original due date.
1099-NEC forms are corrected similarly. The payer prepares a corrected form and sends the payee their copy.
The IRS recently finalized rules regarding corrected forms. A penalty will not be assessed for incorrect reporting if the difference reported is less than $100. The employee has the right to opt out of this reporting and request that a corrected form be sent. The employer must provide the corrected form within 30 days of the request. The safe harbor covers honest slips, not deliberate misreporting.
Legal dates don’t change. Preparation before those dates is voluntary. The dates below show when the IRS requests preparation to be completed for tax year 2026.
December is the month to review the names, Social Security numbers, and addresses of employees. At this time, businesses should collect a Form W-9 from contractors expecting to pay them at least $2,000 over the year. Businesses should also check whether their combined count of W-2s and 1099s reaches 10, which makes e-filing mandatory. On the last day of January, businesses should review their accounts in the Bureau of Securities and the Interstate Regulatory System to ensure they are active. Businesses should also determine whether the totals reported on W-2s match the totals reported on the four quarterly Forms 941.
Recipients should have their 1099 and W-2 copies by Feb. 1, 2027.
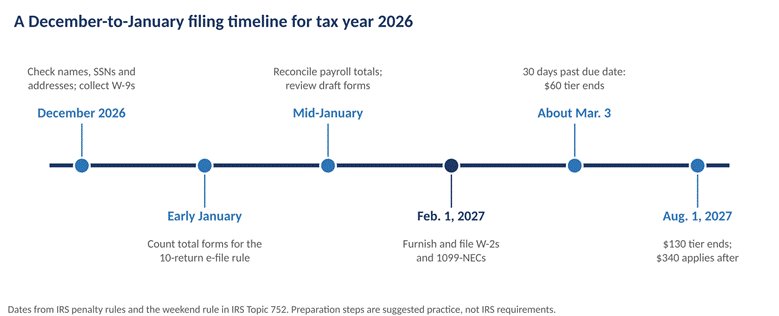
Two other deadlines pertain to the main deadline. The cut-off for the $60 penalty tier for either submitting the correct forms or submitting forms late is 30 days after February 1. The cut-off for the $130 penalty tier is August 1, 2027.
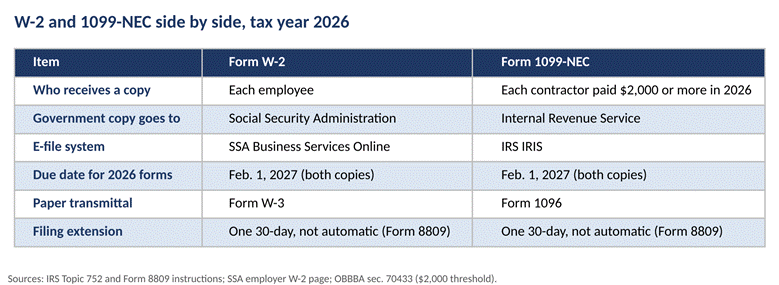
For tax year 2026, both copies of W-2s and 1099-NECs for recipients and the forms for the government all have a filing date of Feb. 1, 2027. Neither the W-2 copies bound for the SSA nor the 1099-NEC copies bound for the IRS are automatically extended. If a business files at least 10 information returns, those returns must be filed electronically.
Beginning in 2026, the trade or business payments reported on 1099-NEC must be greater than $2,000 to be reportable. This change will result in fewer 1099-NECs being issued. Penalties for returns filed in 2027 increase to $60 per return and $340 per return if filed after August 1.
This information pertains to requirements established by the federal government only. To determine requirements and due dates set by individual states, a tax professional should be contacted.
Every year by Jan. 31. When that date is a Saturday or Sunday, the deadline becomes the following Monday. For 2026 wages, employee copies and the copy for the SSA are due Feb. 1, 2027.
Yes. The IRS and recipient copies of 1099-NEC for 2026 will be due Feb. 1, 2027.
Yes, if you send at least 10 information returns in one calendar year to the IRS or the SSA. Returns below this limit may be filed using paper.
The IRS will charge a penalty of between $60 and $340 for each late W-2 during 2027. Willful neglect will raise the charge to $690 for each form. Separate charges apply to the SSA copy and to the employee’s copy.
