Clover POS – How It Can Help Your Business

Clover® POS is transforming the delivery of merchant services today.  Not only does Clover POS simplify acceptance of card payments, it provides software that may also help you monitor inventories, evaluate transactions, manage staff, and enhance client relationships, among many other benefits. Clover payment processing solutions are available in several forms, such as Clover Go, Clover Station and Mobile, and Clover Mini. If you have been struggling with the traditional registers, Clover will simplify your merchant services with the following benefits:

Improve Customer Relationships

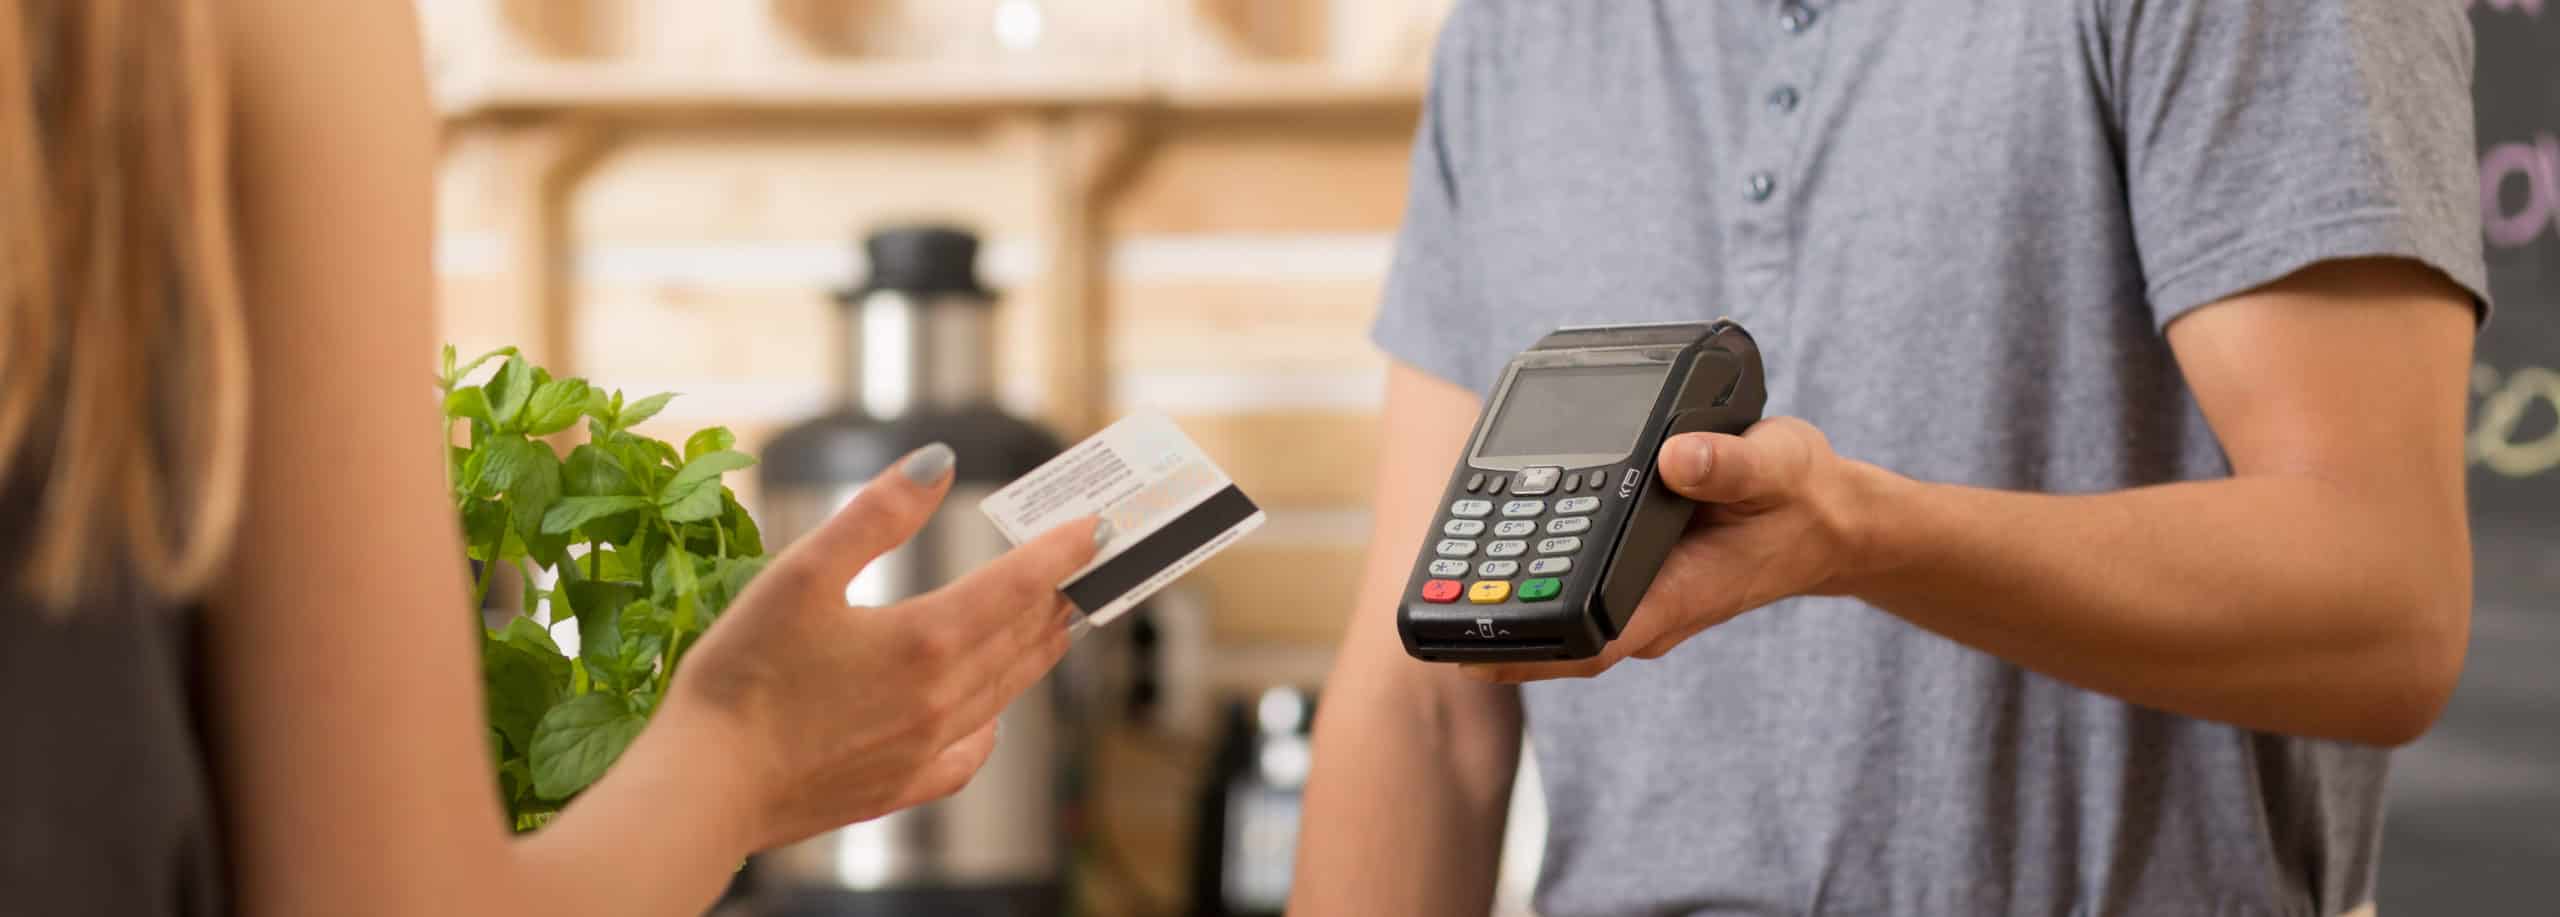
Besides offering quality services or products, your ability to build strong relationships with your clients is important. In your business operations, you will meet clients that prefer to make payments in different ways. If your business can’t process multiple payments, you may risk losing them to your competitors. With Clover, your clients will comfortably make payments using cash, credit or debit cards, and contactless NFC options such as Apple Pay, Google Pay, and more.  Clover apps offer many excellent customer loyalty programs, marketing, and retention tools too.
Retail shop manager doing inventory on tabletSimplify Inventory Management

Clover is more than just a point of sale system. All inventory information is readily accessible via any device using cloud-based software from anywhere and at any time. For instance, while analyzing inventory data, you will be able to see products with the highest sales and determine what to stock. This will help you save on time and increase your savings.  Inventory management can be streamlined and integrated with your payment system.

Guaranteed Data Security

Clover Point of Sale Systems are designed using cutting-edge technologies that provide data security to your business and clients. Its data encryption and tokenization prevent breach of personal information by hackers. Build confidence with customers by using Clover point of sale as a secure way to accept payments and protect customer data, in full compliance with Payment Card Industry Data Security Standards, also called PCI DSS.

Reliable Payment Processing Software

One of the best advantages of Clover POS is the simplicity right from setting it up to using it. Since it’s an all-in-one payment processing solution, you won’t be stressed over incompatible software and hardware. Even though the system uses Wi-Fi or Ethernet to function, its offline mode makes it easy to operate even during an Internet outage. This feature ensures that your business continues to operate smoothly at all times.

Transaction Reports Made Easy

Clover point of sale systems can do a lot more than just allowing multiple payments. Through various Clover apps and add-on software, the system helps you access emails, texts, and print receipts and track sales reports. Such information is essential in understanding your clients’ buying behaviors and finding ways to increase sales and efficiency.

Used By Many Merchants and Merchant Types

Clover POS systems offer versatile options that work for most businesses irrespective of size. Whether you run a food truck, restaurant, brewery, retail shop, ice cream shop, supermarket, among others, Clover is one of the best business software systems to use. This robust platform can handle all merchant services for small-scale to large-scale businesses.

Clover POS solutions are designed to revolutionize merchant operations. If you hope to enhance payments, strengthen client relationships, and increase productivity, the Clover system is a fantastic option to consider.

The Clover® name and logo are trademarks owned by Clover Network, Inc., an affiliate of First Data Merchant Services LLC, and registered or used in the U.S. and many foreign countries.
How to Accept EBT Payments

EBT or electronic benefits transfer payments are benefits that are given to families in low-income households. The government transfers money onto an EBT card, and it is similar to a direct deposit. People can use their EBT card to purchase food and other necessities for their home.

For retailers and merchants to accept EBT payments, they need to sell food that can be prepared and consumed at home. Merchants should sell at least three different qualifying food from each staple food groups, and half of all retail sales should be from the sale of staple foods that are eligible under the program.

Retailers with approval can accept EBT card payments from customers just as they would any other debit card or credit card payments. Retailers or merchants are paid for the total amount of the purchase, and as with any other form of electronic payment, they are transferred automatically to the merchant services bank.

Your business can accept EBT card payments if you are registered and authorized through SNAP or the supplemental nutrition assistance program. If your business is not yet registered, you can sign up to become a SNAP merchant.

Mom and son getting groceries with EBTOnce your registration is complete, SNAP will give you a seven-digit identification number that is also referred to as an FNS number. Your SNAP identification number, your business is well on its way to accepting EBT cards for payment.
People who depend on EBT receive a card that can be swiped at approved retailers. They are processed just like other card-based transactions. Your business will need a point of sale software to handle these card transactions.

It is important that your business uses a credit card machine that can handle federal aid payments. Once you have been approved and have the right payment processing system in place to accept these payments, you will want to follow the government’s rules to maintain your authorization.

These guidelines include:

  • Make sure your customers are purchasing eligible foods with their EBT cards.
  • Never pay cash refunds for customers who pay with their SNAP benefits.
  • Do not charge additional sales tax on foods paid for with electronic benefits transfer cards.
  • Customers need their card and pin to make purchases.
  • Payments should be processed on location and not on credit. Delayed or credit payments are not eligible for SNAP benefits.

If your retail business is food, the chances are that you will qualify to accept electronic benefits transfer and SNAP benefits from customers in the program. There are millions of potential customers with families that use the benefit program every month, so it could also boost revenue for your business. It’s also important to be an inclusive business offering the very best in healthy foods to all of your customers.

5 Great Benefits of Using Clover POS for Your Business

If you run any kind of brick and mortar store, you’ll need an efficient method for checking out customers and receiving payment. To accomplish that, you need a point of sale system, also known as POS for short. Without one, merchant services can quickly turn into a logistical nightmare.

Of the different POS systems on the market, perhaps the best is the one available from Clover® named Station. In many ways, it’s a technological breakthrough compared to traditional POS systems. Below are a few ways a Clover POS system could benefit your business.

It’s Intuitive and Easy to Use

Smartphones, tablets and other smart devices have transformed the world. 3.5 billion people across the globe use smart phones. Clover, recognizing the trend, has integrated some of that same technology into its products. The screen of a Clover POS is very much like that of a smart phone or tablet home screen and integrates the same kind of touch-screen technology. Nearly anyone should be able to intuitively know how to operate it.

woman using clover pos systemClover Harnesses the Power of Apps

Another great feature that is being transferred from smart phones to POS systems by Clover is the use of apps. Investing in a Clover POS system gives you access to something Clover refers to as its App Market. This App Market gives your business access to 100 different business related apps. This now means your system can do a lot more than just payment processing. It can also manage employees, schedule shifts, check inventory, take notes and much more.

It Works with Other Clover Devices

Another benefit of the Clover Station is that it’s designed to be integrated with other products available from the company with no compatibility issues that you may experience with products from other vendors. This includes the Clover Mini, a small sized credit card machine that can scan payment from credit or debit cards. It also works with other products like Clover Go, an even smaller card reader, and Clover Flex, a handheld device that can read cards, take inventory and more.

Clover Gives You Added Security

Today, business owners have to worry about a lot more than just shoplifting. They also have to contend with hackers and cyber criminals. One way thieves steal from businesses and customers is by stealing credit card numbers after they are used to make a payment. Clover POS, however, prevents this due to using card readers that have built-in encryption in compliance to new standards. Without the proper security key, it will be nearly impossible to access customers’ credit card numbers.

Clover Makes Your Business Smarter and More Data-Driven

Using a Clover POS system means having access to the data reporting tools offered by the company. These can record and analyze the numbers so you gain immediate insight into different trends regarding sales, products, customers and more. You’ll be more informed about how your business is actually performing and be able to make appropriate adjustments more quickly.

Overall, there are many great benefits to investing in a Clover POS system. It will utilize the newest technology and be very easy for employees to learn to operate. It can increase your efficiency, security and knowledge of your business. It’s a really great tool to have.

The Clover® name and logo are trademarks owned by Clover Network, Inc., an affiliate of First Data Merchant Services LLC, and registered or used in the U.S. and many foreign countries.

Top Benefits of Clover Mini Point of Sale [2020]

A compact POS system, the Clover® Mini Point of Sale does more than accept payments. If you need more space to do your actual work, the Clover Mini Point of Sale is the solution for you. Ideal for small to medium-sized businesses, the Clover Mini finds its way to businesses like fast service restaurants, salons, and other customer-facing businesses. Flexibility and ease of use make the Mini POS a popular choice for busy retailers. Here are the top benefits of the Clover Mini Point of Sale:

Payment Types

The Clover Mini Point of Sale accepts most payment types, including contactless payment and chip cards. Whether your business accepts gift cards, cash, checks, or debit, the Clover Mini has you covered. With built-in encryption-abled card readers, Clover provides an additional level of security beyond PCI and EMV standards. This advanced security technology keeps your customers and your business safe.

Ease of Use

The user-friendly Clover POS is great for the employees of small to medium-sized businesses. Intuitive and flexible, the all-in-one hardware, including the card reader, makes Clover set up and use of their POS solution easy and fast for business owners. Your customers won’t have to wait in long, slow lines while your system processes payments.

Small business Grocery store helping customerAdded Functionality

As your business evolves, grows, and adjusts to the market, you can add functionality to your Clover Mini Point of Sale via the Clover app market. You can add tools that help you manage inventory and employees. Combining POS and data analysis, you can run reports that are easy to interpret. With an easy search function allowing managers to search by day and by time, the Mini Clover liberates business owners from the hassle of paperwork and filing.

Hardware Flexibility

With the option to connect to Clover Station and many other terminals, the Clover Mini enables businesses to leverage a variety of POS systems to fit the needs of their circumstances. The Clover Mini also integrates with barcode scanners and weight scales, as well as other accessories As business needs change, Clover allows managers to shift course without starting over, saving money, time, and hassles.

LTE/4G

The LTE/4G cellular network option provides a safety net for businesses operating without a reliable ethernet connection. With AT&T’s 4G network, you don’t need an ethernet or WiFi connection. Clover handles the connection taking the worry of a wireless plan or SIM card off of business owners’ shoulders.

Host Merchant Services and Clover

Host Merchant Services can customize your Mini Clover Point of Sale System to fit your business needs. The Mini POS is only one of a number of Clover products in HMS’s offerings, including a robust station with a tablet interface and printer with the option to add functionality, a mobile app turning your phone into your POS, and the handheld POS perfect for a farmers market stand or an intimate restaurant.

Offering complimentary express service, Host Merchant Services provides free quotes. Our payment specialists can provide Clover POS pricing that fits your business.

The Clover® name and logo are trademarks owned by Clover Network, Inc., an affiliate of First Data Merchant Services LLC, and registered or used in the U.S. and many foreign countries.

The Best Clover Point of Sale Apps for Restaurants

Clover Point of Sale for RestaurantsThe Clover® point of sale system is made for restaurants with the Clover Dining feature built into the system. A robust POS, the Clover restaurant point of sale empowers restaurateurs to manage all aspects of the business from one system. Plus, there’s an abundance of clover apps that liberate restaurant management to pick and choose the capabilities they need from a POS.
Whether your restaurant runs a happy hour, provides takeout service, needs notification of low stock, and everything in between, there’s a Clover app covering your every need. Here are the best Clover point of sale apps for restaurants:

Thrive

Keeping track of your restaurant’s up-to-the-minute social media posts and online reviews, the Thrive app can help you manage – and even drive –  your online presence. Even if you’re notified of a negative comment, the Thrive app empowers your restaurant to address the challenge in a timely fashion. As a bonus, the Thrive app also provides current sales data, as well as sales trends and refund and discount data. The Thrive app is developed and offered for free by Thrive.

Shifts

Providing a timeclock, tip declaration, sales reports, and beyond, the Clover-developed app Shifts enables restaurant management and staff alike to multi-task the record-keeping aspects of running a business. The app is free of charge provided by Clover.

Menufy

Allowing restaurants to offer a takeout menu without the 30% charge often associated with outside delivery services, the Menufy app creates a website exclusively for online orders. And if you already have a website, Menufy will generate a module that can integrate with your site. Charging $1.50 per order for high-volume takeout operations, Menufy is less costly than most takeout services. Offered free from Menufy, the app has high reviews from Clover users.

Woman prints receipt on clover pos systemHappy Hour

By placing menu items or categories of items in a time range, the Happy Hour app streamlines the Happy Hour pricing process and eliminates user error at the point of sale. Free of charge, the Happy Hour app developed by Clover helps restaurants run a smooth Happy Hour.

Ping Me If

The manager’s little helper, the Ping Me If app gives managers a heads up when a specific event occurs, be it a refund, the cash drawer exceeding a specified amount, a discount exceeding a specified amount, and more events that require a manager’s approval or notice. With the Stock app, Ping Me If also alerts managers when an item in stock is running low. Developed by Seven Spaces, the Ping Me If app is $4.99 per month or $.99 per month with the Stock App.

Host Merchant Services and Clover

Host Merchant Services can customize your Clover Point of Sale System to fit your restaurant’s needs. Whether your business requires a robust station including a tablet interface and printer with the option to add functionality or your business only needs a mobile app, turning your phone into your POS, Host Merchant Services offers these and everything in between, including the Mini POS and the handheld POS perfect for a farmers market stand or an intimate restaurant. Along with a variety of Clover apps, Clover provides the flexibility required in the restaurant business.

Offering complimentary express service, Host Merchant Services provides free quotes. Our payment specialists can provide Clover POS pricing that fits your business.

The Clover® name and logo are trademarks owned by Clover Network, Inc., an affiliate of First Data Merchant Services LLC, and registered or used in the U.S. and many foreign countries.

With Clover apps for restaurants on your list, the restaurant resources hub has the related guides.

small-medium-business

Rapid Settlements Save SMBs [2023 Update]

We all know that time is money, and in the world of small and medium enterprises, time is intrinsically tied to cash flow. When business owners have sufficient cash on hand, things have a great chance of going smoothly. Once the cash flow is drastically reduced or even depleted, operations suffer even if the promise of a cash injection is somewhere between one to seven days away. We have all heard about American families living from one paycheck to the next; a similar situation is endured by many small business owners, but the time frames tend to be tighter.

Settlement Speed is of the Essence for Small Business Owners

Small business customer paying with debit card

A recent survey conducted by MasterCard illustrates the importance of quick settlements, and providers of merchant services should be paying close attention to what American business owners are going through. More than 60% of small companies start feeling the deleterious effects of waiting around for money to arrive. Imagine a convenience store owner who is left with less than $20 in the register; he may be waiting for a nice $900 transfer from his payment processing provider, but this could take another day or two. The same thing goes for an architect who is stuck waiting for an ACH transaction to switch from pending to available in her bank account.

Happy business owner croppedThe reality of access to capital these days is that more than half of all small business owners, particularly retailers, are more than willing to switch to a merchant services provider who offers who offers quick payouts. The bigger names in the payment processing sector are offering faster delivery of funds, and they are hardly alone in this regard. We have already seen credit card processing firms such as Square speed up their payments considerably, and their clients have been signing up for instant payments, which generally cost them more, at a healthy pace. Big financial institutions such as JPMorgan Chase are taking advantage of their status as established financial institutions to speed up payment processing to completion almost in real-time.

Analysts who cover the merchant services and credit card processing sector have been warning about the rise of digital currencies and their potential for instant settlements. In emerging markets, small business owners skip payment processors and deal directly with shoppers who wish to settle purchases from one digital wallet to another. What merchants do in this case is tap the cryptocurrency exchanges to convert their funds into fiat, but this is sometimes faster than waiting on credit card payments to be deposited. In the United States, automated clearing houses are in danger of becoming a relic because even the most nimble providers can take up to 24 hours to complete transactions.

Last Minute Holiday Shoppers Used Store Pickup

in-store pick up illustration

There’s been a new trend among shoppers when it comes to online shopping this holiday season: make the last-minute purchase online and pick it up in-store. It has, in fact, become so popular that both consumers and retailers alike have come up with a trendy new anacronym: BOPIS (buy online pick up in-store), and according to Adobe, BOPIS orders were to see a surge of 39 percent over the 2018 holiday season.

According to Target CEO Brian Cornell, this also leads to more shoppers leaving their shopping to later in December, which led to stronger retail sales overall due to the increase in physical brick and mortar shopping as opposed to shopping that was otherwise done exclusively online. In total, Target saw an increase of more than 5 times in the number of items bought for in-store pick up during the 2019 holiday season than they did in 2018.

According to data put together by Salesforce, when a store’s online site offers in-store pickup as an option, shoppers will start to become more active. In total, retailers who are offering in-store pickup can expect to attract an increase in customers of as much as 48 percent against those that don’t in the final 5 days running up to Christmas.

order online, pick up in storeOverall, a company such as Walmart, for example, will be losing out on money for each digital order. If they are able to convince a customer to make their own way to an actual physical store to collect the item themselves, however, it can start to save Walmart some money. And it all soon adds up.
One of the first companies to adopt the concept of in-store pickups was Nordstrom. Nordstrom’s co-president Erik Nordstrom found that by allowing customers to pay online with their credit or debit card and collect in-store, they could greater engage with their customer base. Recently, Nordstrom has increased its openings of local smaller stores which, while not actually selling any products, allow customers to collect their digital orders.

Major big-box retailers like Target, Walmart and Best Buy are all now offering customers the option to pay online with their credit or debit card and pick up in-store at their convenience. Ultimately, for large name retailers such as these, offering their customers the option to make their purchases online and pick their items up in-store opens up the ability to leverage already existing store infrastructure, teams and tech against any losses made through their digital sales.

In total, holiday sales this year saw a rise of 14.6 percent over the 2018 holiday season, which, according to the NRO (National Retail Federation), way above what was expected and predicted.

Frequently Asked Questions

  1. What is store pickup and how does it work for last-minute holiday shoppers?

    Store pickup is a convenient option that allows last-minute holiday shoppers to reserve items online and collect them at a nearby store. Simply select the items you want, choose the store pickup option during checkout, and wait for an email or notification confirming that your order is ready for pickup. Head to the designated pickup area in the store, present your identification and order details and collect your items hassle-free.

  2. Can I use store pickup for all items available online?

    Store pickup availability varies depending on the retailer and the item you wish to purchase. While most retailers offer store pickup for a wide range of products, certain items may be excluded due to size, weight, or other restrictions. It’s best to check the product page or contact the retailer’s customer service to confirm if store pickup is available for your desired items.

  3. What is the estimated time for my order to be prepared for pickup?

    The duration required for your order to be prepared for pickup can fluctuate, contingent upon the retailer and their operational efficiency. Typically, retailers aim to have orders ready within a few hours or by the following business day. However, during busy holiday periods, the timeframe may be slightly extended. Once your order is prepared, you will receive a confirmation email or notification containing the estimated time for pickup.

  4. Are there any additional fees associated with store pickup?

    In most cases, store pickup is a complimentary service offered by retailers. However, it’s important to note that some retailers may charge a small fee for certain items or if expedited pickup options are available. These details are typically provided during the checkout process, so you can review any potential fees before finalizing your purchase. Keep in mind that any applicable sales taxes or other standard fees may still apply to your order.

  5. What do I need to bring when picking up my order?

    When picking up your order, it’s essential to bring a valid form of identification, such as a driver’s license or government-issued ID, that matches the name on the order. Additionally, it’s a good idea to have a copy of your confirmation email or order details readily accessible, either printed or on your mobile device. This helps ensure a smooth and efficient pickup process, allowing store staff to quickly locate and verify your order.

  6. Can someone else pick up my order on my behalf?

    Yes, many retailers allow someone else to pick up your order as long as they have the necessary information and identification. If you wish to authorize someone else to collect your items, provide them with a copy of your confirmation email or order details, along with a signed letter or note stating your permission. The authorized person should bring their identification as well as a valid form of identification for you, matching the name on the order.

holiday-sales

Sluggish Holiday Sales for Kohls Despite Help From Amazon [2023 Update]

Historically popular mid-price department stores in the United States have experienced a steady decrease in brick-and-mortar foot traffic over the past several years. The main cause has been a massive shift by consumers from shopping primarily offline to utilizing digital online options and home delivery. Online storefronts have helped department stores make up some lost revenues, but the reduction in on-site/offline shopping has hurt the retail industry. Last year, Kohl’s partnered with Amazon to bring more people into physical stores. The idea was simple: Kohl’s would freely accept, pack and ship returns brought in by Amazon customers and, in return, the traffic would result in impulse purchases and create new, loyal Kohl’s customers, especially over the Q4 holiday season.
retail clothing store that accepts credit and debit cards

Where Did It All Go Wrong?

Earlier in 2019, Kohl’s and industry analysts estimated that Kohl’s would see a certain amount of revenues for Q4. They based the estimate on previous shopping trends and evidence from previous quarters, starting in Q2 with the national returns rollout, that the partnership worked as planned. Yet, Kohl’s relies heavily on seasonal and member discounts and female shoppers. Offering steep discounts during the holidays brought additional people into stores, but fewer women bought apparel. Unsurprisingly, Kohl’s saw plenty of foot traffic, but not the level of expected impulse and other purchases from that traffic. Kohl’s experienced a 0.2 percent drop across November/December as compared to previous years even though it experienced a strong growth trend in Q3 with nearly double the traffic and triple the sales.

Although the full Q4 earnings won’t be released until March 2020, Kohl’s CEO Michelle Gass advised investors on January 9 to expect lower-than-estimated earnings. Some analysts believe that the actual losses are worse than 2008. Kohl’s is pleased by the increase of traffic that has resulted from the Amazon returns. Digital purchases also continue to rise because of the Kohl’s app, but the company must now re-evaluate how to bring female consumers back into stores to buy apparel or find another revenue generator.

Retail clothing merchant account

Why Is This News Important?

A well-known name, massive discounts and even an Amazon partnership isn’t a guarantee of steady on-site, brick-and-mortar traffic and revenues in today’s volatile retail market. Kohl’s ignored warnings about shopping trends and relied too heavily on female apparel purchases. It’s been known for some time now that women are shopping more online through programs that allow them to conveniently try on clothing and shoes at home and then return items they don’t want or need. Kohl’s also didn’t offer more perks to appeal to younger shoppers. Its heavy discounts usually appeal to older consumers who are less like to impulse shop. Mid-price department stores across America are dying not only because of these factors, but also because of competitors, such as T.J. Maxx, Marshalls and Ross, who offer high-end goods at discounted prices far below their own. These buying trends have forced retailers like Kohl’s to offer steep discounts and adapt in various ways to survive. Without adapting, such as by accepting Amazon returns, Kohl’s would have lost far more. J.C. Penny, for example, experienced a 7.5 percent drop in sales over the holidays. According to Mastercard, department stores industry-wide experienced a drop of 1.8 percent.

At Host Merchant Services we hope that this type of news can help our retail merchants understand how they need to adapt their own traffic and sales strategies to survive. We also want these mistakes to help you to learn how to adapt so that you can always reach your estimated revenue goals. For more information, contact us today.

Speed Optimization at the Point of Sale

Point of Sale

While the 2015 fraud liability shift has increased chip card adoption in the United States, consumers and merchants alike still express frustration with a major drawback of EMV technology: slow transaction times at the point of sale.

Unlike magnetic stripe cards, chip cards need to be inserted for a long period of time until the transaction goes through. Transaction times can vary by chip card issuer, POS system, and merchant but may take up to 15 seconds or longer, increasing wait times and slowing down the checkout process.

Chip adoption has been slow; in 2019, just 68% of U.S. merchants who accept cards have adopted chip technology and just 67% of total Visa cards issued are EMV-enabled. Consumer dissatisfaction is just one of the reasons for this slow transition in addition to the cost to merchants to upgrade POS systems. Merchants that are EMV-ready are experiencing significant slowdowns in transaction time.

Chip technology is designed to increase card processing security, not speed; by improving card-terminal authentication and reducing the risk of fraud, chip technology adds to point of sale transaction time.

several point of sale systemsQuick Chip and M/Chip Fast: The Card Issuer Response to Slow Chip Transactions

Credit card issuers have responded to slow transaction times with “faster EMV.” Discover, Visa, and American Express offer Quick Chip while Mastercard offers M/Chip Fast. This update mimics traditional magnetic stripe swipes by allowing for pre-dip and faster card removal before the total transaction amount is known while maintaining most of the security benefits of chip technology.

The Quick Chip software update is one of the simplest ways for merchants to optimize transaction times. With the update, the point of sale system retains the chip data while requesting an authorization or ARQC. When the authorization is returned by the card’s chip, the terminal will prompt the customer to remove the card. The authorization may be for a provisional transaction amount of what has been scanned if the process occurs in the middle of the terminal.

The Quick Chip update is only available for merchants in the U.S. and it requires an update of the point of sale software through the processor. It will only work when the system is online as well.

Contactless Payments: A Faster Alternative

Contactless payments are faster than both chip and mag swipe transactions. Contactless chip cards, which offer the same security of chip transactions, offer customers a much faster checkout experience. Most point of sale systems that support chip payments also support contactless EMV payments as well. By offering contactless payments as an option, merchants can give consumers a faster option to pay and reduce checkout times.

CFPB Files Lawsuits Against Student Loan Debt Relief Firms

Student Loan Merchant ServicesThis week, the Consumer Financial Protection Bureau (CFPB), a consumer protection agency created by the Dodd-Frank Act of 2010, has filed lawsuits against a number of people and companies involved in student loan debt relief services.

According to the CFPB, these companies illegally obtained consumer reports, charged illegal advance fees for services, and engaged in many forms of deceptive behavior.

In the complaint, the CFPB alleges that Monster Loans, a mortgage lender named in the suit, violated the Fair Credit Reporting Act (FCRA) by obtaining the consumer report data for millions of consumers with student loans from a credit bureau under the pretense of using the information to offer mortgages. Instead, between 2015 and 2017, Monster Loans sold the reports to student loan debt relief companies to market services. The lawsuit also alleges that Lend Tech Loans violated the FCRA between 2017 and 2019 by obtaining credit bureau reports for consumers to market student debt relief services.

Student working to pay off loanIn addition to violations of the FCRA, the CFPB alleges that several defendants violated the Consumer Financial Protection Act of 2010 and the Telemarketing Sales Rule (TSR) while marketing and providing student debt relief services through deceptive representation about services. Defendants allegedly misrepresented to consumers that their interest rates would be reduced, their credit scores would improve, and the Department of Education would become their loan servicer. Several defendants also illegally charged over $15 million in fees in advance of consumers receiving adjustments to their loans or making payments toward the adjusted student loans.

The CFPB has filed suits against:

  • Mortgage lender Chou Team Realty, LLC doing business as Monster Loans
  • Lend Tech Loans, Inc., an allegedly sham brokerage firm
  • Student loan debt relief companies Docu Prep Center, Inc. (doing business as DocuPrep Center and Certified Document Center); Assure Direct Services, Inc.; Certified Doc Prep Services, LP; Secure Preparation Services, Inc.; Direct Document Solutions, Inc.; and Docs Done Right, Inc.
  • Individuals Thomas “Tom” Chou, Bilal Abdelfattah (also known as Bill Abdel and Belal Abdelfattah), Robert Hoose, Sean Cowell, Jawad Nesheiwat, Eduardo Martinez, Frank Anthony Sebreros, and David Sklar.

The CFPB is seeking an injunction against the defendants in addition to damages, disgorgement of ill-gotten gains, redress for harmed consumers, and civil financial penalties.

The CFPB maintains supervision authority for institutions with over $10 billion in assets with examination and enforcement authority for financial institutions that provide financial products to consumers. The Consumer Financial Protection Act gives the Bureau the authority to protect consumers from abusive, deceptive, and unfair practices while overseeing mortgage lending and servicing. Consumers can also submit complaints about unfair financial practices, products, and security in the financial sector through the Bureau’s database.