DOGE, or the Department of Government Efficiency, is in full action, taking significant steps to streamline operations by restricting or fully deactivating Federal credit cards designated for travel and procurement purposes across multiple agencies.
As of last week, DOGE reported (via X) that 298,903 credit cards had either been reduced to a $1 limit or entirely disabled. These include 35,493 procurement-related cards and 263,410 travel-related cards.
The restrictions have impacted numerous independent agencies, such as the Office of Personnel Management, General Services Administration, Environmental Protection Agency, Small Business Administration, NASA, and Social Security Administration. Several Cabinet-level departments have been affected, including Homeland Security, Labor, Agriculture, Interior, Education, Treasury, Commerce, State, Health and Human Services, and Housing and Urban Development.
To date, DOGE has completed audits on 55,587 purchase cards and 501,798 travel cards, with the current restrictions affecting more than half of the audited cards. However, this is only the initial phase of DOGE’s ongoing initiative, as the department ultimately plans to audit approximately 4.6 million federal credit cards spanning various agencies and departments.
Key Takeaways
DOGE has disabled or severely restricted approximately 300,000 federal credit cards (263,410 travel and 35,493 purchase cards) to curb unnecessary government spending.
Affected agencies include NASA, the Environmental Protection Agency, and various Cabinet-level departments such as Agriculture, Interior, Health and Human Services, and Homeland Security, prompting them to reassess internal spending practices.
DOGE has audited over 550,000 credit cards to date, with the current limitations impacting over half of these audited cards. The department plans further audits across nearly 4.6 million government-issued credit cards.
Supporters see this initiative as crucial for fiscal accountability, while critics express concerns over potential disruptions to agency operations and essential public services. The exact savings for taxpayers are not yet known.
DOGE Deactivates 300,000 Government Credit Cards in Federal Spending Crackdown
In a decisive move to curb federal expenditures, the Elon Musk-backed DOGE has deactivated approximately 300,000 government-issued credit cards. This action aligns with the administration’s broader strategy to enforce stringent spending limits across federal agencies.
DOGE’s recent initiative targeted purchase and travel cards across multiple federal agencies. Specifically, over 263,000 travel cards and more than 35,000 purchase cards were either canceled or had their spending limits reduced to $1. This measure is part of a pilot program involving 16 agencies to audit and eliminate unused or unnecessary credit cards.
The primary objective of this mass deactivation is to identify and eliminate wasteful spending within the federal government. By scrutinizing and reducing the number of active government credit cards, DOGE aims to enhance fiscal responsibility and ensure that taxpayer dollars are utilized effectively. Elon Musk emphasized that such audits are just the beginning of a comprehensive effort to streamline government operations and reduce unnecessary expenditures.
As mentioned, deactivating these credit cards has significant implications for various federal agencies. For instance, the Department of the Interior saw 18,636 purchase cards affected, while the Department of Agriculture had 47,003 travel cards canceled or limited. Similarly, the Departments of Health and Human Services and the Department of the Interior experienced limitations on 42,959 and 39,213 travel cards, respectively.
These changes have prompted agencies to reassess their spending practices and implement more stringent expenditure controls. While the immediate effect may be increased administrative adjustments, the long-term goal is encouraging accountability and efficiency within federal operations.
The initiative has garnered mixed reactions from various stakeholders. Supporters argue that it is a necessary step toward reducing government waste and promoting fiscal discipline. They believe that such measures will lead to more transparent and responsible use of public funds.
Conversely, critics contend that the abrupt deactivation of a large number of credit cards could hinder the daily operations of federal agencies. They express concerns about potential disruptions in procurement processes and delays in essential services. Additionally, some view this move as part of a broader pattern of aggressive cost-cutting measures that may overlook the nuanced needs of various government departments.
The exact savings to taxpayers resulting from these cancellations remain uncertain. According to DOGE, approximately 4.6 million government-issued credit cards were involved in 90 million individual transactions, amounting to roughly $40 billion in expenditures during fiscal year 2024.
This action by DOGE is part of a series of measures to overhaul government spending practices. The administration has previously implemented spending freezes and imposed stringent limits on government-issued credit cards. Furthermore, the administration has sought to centralize payment systems and increase transparency in government expenditures. An executive order mandated federal agencies to establish centralized systems to record and justify all payments, aiming to enhance accountability and reduce opportunities for waste and fraud.
Last month, Elon Musk spoke at former President Donald Trump’s inaugural Cabinet meeting, highlighting DOGE’s goal to identify $1 trillion in savings to reduce America’s nearly $36.5 trillion national debt significantly.
Musk specifically criticized the approximately $2 trillion annual deficit, warning that the United States “simply cannot sustain” such massive borrowing levels.
Musk cautioned, “If this trend continues, the country risks becoming effectively bankrupt.” He emphasized that DOGE was not merely an optional measure but a crucial element for meaningful economic reform.
Over the weekend, DOGE revealed a concerning discovery involving millions in questionable loans. The agency found that nearly 5,600 loans, totaling about $312 million, were issued by the Small Business Administration (SBA) to recipients whose sole listed owner was 11 years old or younger at the time. These loans, distributed during 2020 and 2021 amidst the COVID-19 pandemic, raise serious questions regarding their legitimacy and intended purpose.
About DOGE
The Department of Government Efficiency (DOGE) is a federal initiative established by President Donald Trump through Executive Order 14158 on January 20, 2025. This department was created to implement the President’s agenda of modernizing federal technology and software to maximize governmental efficiency and productivity. Elon Musk, appointed to lead DOGE, has been instrumental in driving its mission to streamline government operations and reduce unnecessary expenditures.
DOGE’s approach involves embedding specialized teams within federal agencies to audit and optimize operations. These teams, known as “DOGE Teams,” consist of professionals such as engineers, human resources specialists, and attorneys. They are tasked with reviewing existing contracts, grants, and internal processes to identify areas where spending can be reduced or reallocated to promote efficiency. This initiative reflects a commitment to enhancing transparency and accountability in government spending, ensuring that taxpayer dollars are utilized effectively.
Conclusion
The DOGE’s large-scale deactivation of nearly 300,000 federal credit cards marks a significant step in its effort to curb unnecessary government spending. DOGE aims to promote fiscal responsibility and enhance transparency in federal operations by limiting or disabling travel and procurement cards across multiple agencies.
While the initiative has already impacted many agencies, it is only the beginning of a broader campaign to audit and streamline the government’s financial practices. With plans to review millions of federal credit cards, DOGE is positioned to reshape spending protocols further and enforce stricter financial controls.
Though the long-term savings and operational impacts remain, this move signals a firm commitment to reducing waste and ensuring more accountable use of taxpayer dollars.
As we enter 2025, point-of-sale (POS) systems—the tools businesses use to complete sales transactions—are evolving quickly. Modern POS platforms are no longer cash registers; they are smart, connected hubs that blend hardware and software innovations. From a bustling retail boutique to a popular restaurant (and even hospitals and hotels), POS technology is shaping customer experiences and streamlining operations.
In this blog, we’ll explore the top POS tech trends to watch in 2025, focusing on the retail and restaurant sectors and how other industries like healthcare, hospitality, and service businesses are embracing them. Each trend is backed by insights from recent reports and expert articles, highlighting how these technologies boost customer convenience, business efficiency, and revenue.
Top 8 POS Tech Trends to Watch in 2026
Cloud-Based POS Systems Go Mainstream
In 2025, cloud-based POS systems have moved from cutting-edge to the new normal. Unlike traditional on-site POS that locks data in a back-office server, cloud POS solutions securely online store sales and inventory information – accessible from anywhere. This means a store manager can check real-time sales across multiple locations, or a restaurant owner can update the menu on all terminals from home.
It’s no wonder analysts predicted cloud POS would dominate the market by 2025. The global cloud POS software market was valued at $2.24 billion in 2020 and is on track to reach $13+ billion by 2028, reflecting how rapidly businesses embrace this flexibility.
But why are cloud POS systems so popular? Key advantages include:
Remote management and real-time updates: Owners can monitor sales, inventory, and even employee performance across all stores in real time from any device with internet access. For example, Shake Shack uses a cloud POS to manage orders and inventory consistently across its global outlets.
Lower upfront costs and easy setup: Cloud POS often works on off-the-shelf hardware (like tablets or PCs) with software as a service. Businesses can install an app or use a web browserto avoid expensive dedicated terminals. Instead of hefty upfront fees, many cloud POS charge a subscription, allowing even small retailers to access advanced tools without breaking the bank.
Automatic updates and scalability: Because everything runs through the cloud, software updates roll out automatically, and adding a new store or terminal is plug-and-play. The system grows with your business, whether you’re a single boutique or a fast-growing franchise.
All of this translates to efficiency. Retailers and restaurants using cloud POS spend less time on IT maintenance and more time serving customers. And it’s not just retail and dining—hospitality venues and even healthcare providers appreciate cloud POS for multi-location coordination. A hotel group can oversee all its property gift shops centrally, and a healthcare clinic network can ensure consistent billing processes across offices. With cloud systems projected to make up over half of the POS market by mid-decade, it’s clear this trend is here to stay.
Mobile POS Puts Sales in the Palm of Your Hand
Mobility is another huge theme in 2025’s POS trends. Mobile POS refers to using tablets or smartphones as checkout devices, freeing staff from the fixed cashier counter. This has been a game-changer in retail and food service. Imagine a clothing store associate who can check you out on a tablet right in the aisle or a restaurant server using a handheld device to take orders and payments tableside – no more running back and forth. This convenience is boosting both customer satisfaction and sales. According to one industry survey, 43% of businesses not already using mobile POS planned to deploy POS software on mobile devices, highlighting strong interest in going cordless.
Tablets and handheld printers turn anywhere in a store or restaurant into a checkout counter, as seen with this tablet POS showing real-time sales insights. Mobile POS devices like these give staff flexibility and instant access to data, improving service speed. Retail giants and small shops alike are adopting mobile POS.
Apple Stores famously armed employees with iPhones to ring up customers anywhere in the store years ago. Everyone from big-box retailers to local boutiques is doing the same to eliminate checkout lines. In restaurants, mobile POS (like Toast’s popular handhelds for waitstaff) let servers swipe cards or tap phones right at the table, so diners never have to flag someone down for the bill. This speeds up table turn times and often increases sales. Restaurants that use mobile ordering and payment systems have seen a 9% boost in average check size – likely because it’s so easy for customers to add that extra item or dessert on a device.
Faster service and small upsells mean higher revenue and tips, a win-win for businesses and staff. Other industries are taking note. Hospitality venues use mobile POS for pop-up bars at events or poolside service at resorts. Healthcare providers are beginning to use tablets for bedside bill payment and check-out, bringing the payment process to the patient for comfort and speed. And many service businesses – from salon stylists to food trucks – rely on a phone or tablet with a card reader (think Square or Clover mobile readers) to take payments on the go.
The mobile POS terminals market was valued at around $36 billion in 2024 and is projected to triple by 2030, reflecting how ubiquitous this tech is becoming. In short, cutting the cord from the cash register lets businesses bring the checkout to the customer, wherever they are, and that convenience is driving higher satisfaction and sales.
Contactless Payments Become the Norm
Contactless payments, such as tap-to-pay cards and mobile wallets like Apple Pay and Google Pay, have become the norm. Once a novelty, they are now expected at most POS terminals. Shoppers appreciate the speed and convenience, while businesses benefit from faster checkouts. For example, Starbucks uses NFC-enabled POS readers, allowing customers to pay by tapping their phone or smartwatch, reducing wait times during busy hours.
This trend extends beyond retail and dining. In 2024, 92% of US consumers used some form of digital payment, a record high. Hospitals and clinics have adopted the technology, letting patients check-in or pay bills by tapping their phones or scanning a QR code, reducing paperwork and wait times. In hospitality, flexible payment options are now a deciding factor—55% of travelers won’t book a hotel if their preferred payment method isn’t available.
Both customer demand and improved accessibility drive the widespread use of contactless payments. Most new POS terminals include NFC readers, and providers like Square, Clover, and Shopify POS offer built-in contactless capabilities, making it easy for small businesses to accept digital payments. Security is also strong, with encrypted tokenization protecting customer data.
With contactless payments handling a growing share of transactions, businesses that don’t offer them risk falling behind. Accepting digital wallets and tap cards is now essential for meeting customer expectations and staying competitive.
AI-Powered Analytics Deliver Smarter Insights
Artificial intelligence is making POS systems brainier. AI-powered analytics in POS software means the system doesn’t just record sales – it can learn from them. Retailers and restaurants increasingly use AI and machine learning to analyze the troves of data coming through their POS. This trend is transforming everything from inventory management to personalized marketing.
A survey revealed that 71% of restaurant owners utilize data from their Point of Sale systems to enhance menus, simplify payment processes, and increase digital interaction with customers. In other words, businesses are hungry for data-driven decision-making, and POS systems are serving it up. What can AI do at the point of sale? A lot, it turns out. Here are some powerful examples of how AI analytics are being applied:
Demand forecasting & inventory optimization: By analyzing past sales patterns, seasonal trends, and even factors like weather, AI-enabled POS can forecast demand so businesses stock the right products in the right quantities. This is huge for restaurants and retailers looking to reduce waste and avoid running out of popular items. With AI insights, a cafe might notice iced coffee sales spike during unexpected warm weeks and adjust inventory accordingly. A clothing store can predict which styles will be hot sellers next month and pre-stock sizes.
Personalized promotions & customer insights: Modern POS systems often link with loyalty programs, allowing AI to crunch an individual’s purchase history and preferences. The system can then recommend tailored promotions – for instance, offering a discount on a customer’s most-purchased brand or printing a coupon for dog treats on a pet shop receipt if you frequently buy pet food. Sephora has experimented with AI-driven POS that analyzes buying patterns and suggests custom offers, which drives sales and boosts customer satisfaction through personalization.
Operational efficiency & staffing: AI analytics help managers see patterns humans might miss. For example, a fast-food chain’s POS data might reveal that certain hours consistently have spikes in drive-thru orders. The AI can suggest optimal staffing schedules or dynamic menu adjustments (promoting quicker-to-make items during peak times). It can also flag anomalies, like an unusual string of voided transactions that could indicate a training issue or fraud.
Crucially, AI is not just for retail giants. Thanks to cloud POS and user-friendly software, even independent businesses can tap into advanced analytics without a data science team. Companies like Square and Lightspeed build analytics dashboards into their POS offerings, showing key metrics and trends with a click. Many small businesses already rely on these: about 50% of small businesses say the analytics and reporting in their POS system is integral to their operations.
And industries beyond retail are leveraging AI insights too. Hotels use POS-linked AI to analyze guest spending and refine their services. Healthcare providers might use AI analytics to spot billing patterns or clinic patient flow inefficiencies. The common thread is that AI-driven POS systems turn raw transaction data into actionable intelligence. In 2025, adopting AI in POS is less about sci-fi and more about staying competitive, as those who leverage these “smart” insights can optimize their offerings, cut costs, and better delight their customers.
Smart POS Hardware and the IoT Revolution
POS hardware is evolving in 2025, moving away from bulky cash registers and multiple devices to streamlined, all-in-one systems and IoT-connected gadgets. Modern setups include sleek touchscreen terminals, handheld card readers, self-service kiosks, and smartwatches or voice assistants handling orders. This shift reduces counter clutter and adds new functionality at the point of sale.
A key trend is hardware consolidation. Companies like Square, Clover, and Lightspeed offer all-in-one systems that combine ordering, payments, receipts, and loyalty programs into a single device. For example, Square Register and Clover Station feature a large customer-facing display, built-in card reader, receipt printer, and cash drawer in one unit. This reduces the need for multiple devices, making maintenance simpler. Smaller merchants can use a single iPad with a portable receipt printer or go paperless by emailing receipts. This is especially useful for restaurants and hotels where counter space is limited.
Self-service kiosks and customer-facing screens are also becoming more common. Fast-food chains like McDonald’s use touchscreen kiosks that let customers independently place and pay for orders, reducing wait times and improving accuracy. Retailers are adding screens at checkout that display real-time pricing and allow customers to enter loyalty information or request email receipts, making transactions more transparent.
Beyond the counter, IoT integration is expanding POS capabilities. Smart scales and RFID scanners automatically add items when weighed or scanned to the sale, which is ideal for grocery and retail. In restaurants, kitchen display systems (KDS) sync with the POS to instantly show orders on a screen, eliminating the need for paper tickets. Some stores test sensors that track product movement and update inventory in real-time. Unattended POS systems, like Amazon’s Just Walk Out stores, use cameras and sensors to detect items taken by customers, automatically processing the transaction.
New POS hardware is also more user-friendly and durable. Touch interfaces replace complex keypads, and mobile device management (MDM) tools allow businesses to monitor and update devices remotely. The result is faster checkouts, fewer technical issues, and more flexible service options, like self-service or mobile checkout. For customers, it means quicker, smoother transactions without the frustration of outdated hardware.
Biometric Authentication Enhances Security and Speed
As cybersecurity concerns grow, POS systems increasingly adopt biometric authentication—using fingerprints, facial recognition, palm scans, or other biological traits—to secure transactions and improve efficiency. What once seemed futuristic, like paying with a fingerprint or unlocking a register with facial recognition, is quickly becoming standard. By 2025, security experts predict biometrics, encryption, and tokenization will be essential for protecting customer data.
Biometrics adds a layer of verification that is difficult to fake, making transactions safer and faster. Amazon’s palm-scanning payment system, Amazon One, is a prominent example. By the end of 2023, all 500+ Whole Foods Market stores in the U.S. offered palm payment, allowing customers to pay by hovering their hand over a scanner. The system links the palm signature to a credit card and loyalty account, automatically applying Prime discounts. Amazon encrypts the palm data for security, and the widespread adoption of this technology highlights the growing role of biometrics in everyday commerce.
Fingerprint and facial recognition payments are also gaining traction. Many payment apps and POS systems let customers authenticate purchases using their phone’s biometric security instead of a PIN. On the merchant side, biometrics can control access to prevent fraud. For example, restaurants can require a manager’s fingerprint to approve voided transactions or open the cash drawer, replacing easily shared or guessed PIN codes. Biometric authentication also speeds up the process, reducing the time spent on password entry.
Beyond retail, industries like hospitality and healthcare are exploring biometrics for identity verification and payments. Some hotels use facial recognition for faster check-ins and room access, with payment cards linked to guest profiles. Gyms and spas may use fingerprint or vein scanners for membership check-in and service payments. In healthcare, biometrics help confirm patient identities, which could eventually extend to bill payments or pharmacy pickups.
Biometric POS solutions offer both security and convenience. They reduce the risks of stolen PINs, lost cards, or unauthorized employee activity. When properly implemented, they also make transactions faster and more seamless—effectively turning a customer’s physical traits into the payment method. However, privacy concerns remain, and businesses must handle biometric data carefully and transparently. Still, as the technology matures, biometric payments are expected to become more common, particularly in settings where speed and security are critical.
Blockchain and Crypto Find a Niche in POS
Blockchain technology is starting to influence POS systems, offering secure, tamper-proof transaction records and new payment options. While still emerging, its presence is expected to grow in 2025, particularly in crypto payments, loyalty programs, and data security.
One area where blockchain adoption is seen is cryptocurrency payments. Payment providers like BitPay and NOWPayments offer crypto POS solutions that let brick-and-mortar stores accept Bitcoin or Ethereum. Customers can pay using their crypto wallets, while merchants receive the equivalent in local currency, avoiding the risk of crypto volatility. Though not yet mainstream, some tech-savvy retailers, restaurants, and hotels are adding crypto payment options to attract digital currency users and position themselves as innovators. As regulations around crypto evolve, more businesses may follow suit.
Beyond payments, blockchain is improving loyalty programs. Traditionally, reward points are tracked in centralized databases, but blockchain enables points to be securely managed and even transferred between partners. For example, in the future, customers could convert coffee shop points into airline miles if both programs run on interoperable blockchain tokens. Blockchain’s transparency also makes auditing and preventing fraud in complex systems, such as multi-location franchises or vendor marketplaces, easier.
In healthcare, blockchain is being tested for payments and insurance claims. A shared blockchain ledger could let patients, providers, and insurers track claims and costs in real-time, with smart contracts automatically releasing payments when conditions are met. This could reduce errors and streamline the often slow, complex billing process. In retail, similar systems could be used for supply chain payments or vendor commissions, ensuring accuracy and reducing disputes.
For most businesses, blockchain’s impact in 2025 will be subtle. Customers may not even realize it’s being used behind the scenes. However, companies are already testing blockchain-based gift cards, cross-border payments, and fraud prevention measures. Because blockchain records are encrypted and distributed, they are harder to tamper with, offering added security. For example, logging each POS transaction on a blockchain could help detect and deter unauthorized changes.
While blockchain won’t replace traditional POS systems anytime soon, it is quietly making transactions more secure, transparent, and flexible—especially in crypto payments and loyalty management areas.
Omnichannel Integration for a Unified Experience
In 2025, omnichannel integration is becoming essential for businesses, linking online and offline experiences into a unified shopping journey. Modern POS systems play a key role by syncing with e-commerce platforms, mobile apps, and third-party services, ensuring customers can move seamlessly between channels.
For example, retail stores with omnichannel POS can support services like “buy online, pick up in-store” (BOPIS). When a customer reserves an item online, the system automatically updates the inventory and prepares the product for pickup. In-store, the POS retrieves the order with a quick scan or reference number, processes the payment, and ties it to the customer’s profile. Target uses this approach, allowing customers to pick up online orders in-store or return online purchases at physical locations. The POS handles refunds and updates stock levels across both channels in real-time.
Restaurants also embrace omnichannel POS to manage dine-in, takeout, and delivery orders from one system. By integrating with delivery apps, the POS ensures accurate order tracking, prevents double bookings, and correctly applies loyalty points regardless of how the order was placed. Many restaurants also link table reservations to their POS, so when guests check in, their table is pre-assigned, and any orders are automatically connected to their reservation. According to industry surveys, nearly half of restaurateurs aim to upgrade their POS for better omnichannel functionality.
Other industries benefit from this integration as well. In hospitality, hotel POS systems sync with property management software, allowing guests to charge restaurant meals, spa services, or gift shop purchases directly to their rooms. Salons and service businesses connect their POS with online booking systems, ensuring that when customers pay in-store, their profile is updated with the service history, and receipts are sent digitally. Even in healthcare, clinics use omnichannel POS setups to let patients pay bills online or at a kiosk, with all records updated instantly across systems.
The impact on customer experience is significant. Omnichannel POS systems prevent frustrating disconnects, such as being told, “Our online system is separate—we can’t look up your order here.” Instead, customers enjoy flexibility, whether they want to shop online, in-store, or mix the two. For businesses, this integration improves efficiency, prevents lost sales by locating out-of-stock items across locations, and enables better marketing. For example, if a customer abandons their cart online, the POS can trigger a reminder at checkout during their next store visit.
Conclusion
As we move through 2025, point-of-sale technology is becoming more innovative, faster, and adaptable. From cloud-based systems enabling real-time management to mobile POS devices putting sales in employees’ hands, the focus is on convenience and efficiency. Contactless payments have become the standard, while AI-powered analytics are helping businesses make smarter, data-driven decisions. Meanwhile, innovations like biometric authentication and blockchain enhance security and expand payment options.
For businesses, keeping up with these POS trends is no longer optional—it’s essential for staying competitive. Whether a minor retailer upgrades to a mobile-friendly POS or a large restaurant chain uses AI to optimize operations, leveraging these technologies helps improve customer experiences, streamline processes, and boost revenue. As POS systems evolve, businesses that embrace these innovations will be better positioned to meet the demands of a rapidly changing marketplace.
Healthcare payments evolve rapidly as technology advances, policies change, and patient expectations grow. In 2025, providers, payers, and patients are all navigating new ways to handle medical bills and reimbursements.
Below, we explore the top payment trends in healthcare – from digital wallets and blockchain to shifting insurance models, new regulations, changing patient behaviors, and innovations in billing through automation and AI. The goal is to demystify these trends in a conversational, easy-to-understand way.
Top Payment Trends in Healthcare
Digital Payment Solutions Are Becoming Mainstream
Digital payment methods – from contactless card readers to smartphone apps – are becoming increasingly common at clinics and hospitals. The COVID-19 pandemic accelerated contactless payments in healthcare, and that momentum continues into 2025. Whether tapping a phone or card at the front desk or paying a bill through a mobile app, patients now expect the same convenient payment options in healthcare that they use in retail.
92% of U.S. consumers reported using some form of digital payment in 2024, an all-time high. Healthcare providers are catching up to this consumer trend by offering tap-to-pay, mobile wallets, and online bill-pay options. One significant development is the rise of digital wallets and mobile payments for medical bills. Many patients prefer to pay electronically instead of mailing checks or filling out paper forms. Nearly three-quarters of consumers (73%) say they prefer to pay medical bills online, and digital wallets (like Apple Pay, Google Pay, PayPal, or Venmo) are surging. Globally, digital wallet transactions are projected to grow 73% between 2024 and 2029.
In the U.S., almost half of consumers (48%) have used a digital wallet in the past 90 days, a jump of 12 percentage points from the previous year. We can expect more hospitals and clinics to let patients pay by scanning their phone or clicking a link, eliminating the need to handle cash or physical cards. These methods offer speed and convenience, and they come with multi-layered security (like tokenization, which replaces card numbers with encrypted tokens) to protect patient financial data.
Another cutting-edge trend is the exploration of blockchain technology for healthcare payments. Blockchain – a secure, decentralized ledger – has the potential to make transactions more transparent and tamper-proof. In the insurance industry, the blockchain market is expected to grow about 60% in 2025, reaching $3.11 billion, and healthcare is starting to follow suit. Blockchain can streamline claims processing by providing a shared, real-time view of the claim status for all parties. This means providers, insurers, and patients could track payments and approvals instantly, reducing back-and-forth phone calls and errors.
Smart contracts (self-executing agreements on a blockchain) are also being tested to automate payments – for example, automatically releasing funds to a provider once a claim meets specific criteria. By locking each transaction into an immutable ledger, blockchain helps prevent fraud and duplicate billing. While still emerging, these technologies promise a more secure and efficient payment process in the future.
Shifts in Insurance Reimbursement Models
Paying for healthcare isn’t just about patients handing over a credit card – a huge part of the system is how insurance companies reimburse providers. In 2025, we see a continued movement from the traditional fee-for-service model (where providers are paid for each test or visit) toward value-based care models that reward better outcomes and cost-efficiency. The U.S. government and private insurers alike have been pushing this transition. The Centers for Medicare & Medicaid Services (CMS) aims to have all Medicare beneficiaries in value-based care arrangements by 2030.
Progress is being made: as of 2024, 54% of Medicare beneficiaries were enrolled in Medicare Advantage plans (managed care), up from previous years. Medicare Advantage and similar programs often use capitated payments or bonuses for quality, incentivizing providers to focus on preventive care and avoid unnecessary procedures.
Beyond Medicare, many private payers and health systems are experimenting with hybrid payment models. For example, accountable care organizations (ACOs) and bundled payment programs pay providers a set amount for managing a patient’s care for a specific condition or period. These models will continue to expand in 2025, covering areas from primary care to specialty procedures. CMS is rolling out new initiatives like the GUIDE model for dementia care, introducing payments for care planning and caregiver education that weren’t reimbursed.
The idea is to pay for the overall management of a condition, not just discrete visits, thereby improving patient outcomes and potentially lowering costs in the long run. Another notable shift is the normalization of telehealth and remote care reimbursement. After the telehealth boom during the pandemic, insurers have been adjusting their payment policies. Medicare and other payers temporarily allowed broad telehealth coverage; many flexibilities have been extended through 2024 and into 2025.
For instance, Medicare beneficiaries can continue to have telehealth visits from home (not just in rural areas) at least through March 2025. In addition, CMS has proposed new billing codes for digital health services. In the 2025 Physician Fee Schedule proposal, CMS introduced new codes to reimburse digital therapeutics – software applications that treat health conditions – especially for mental health treatment.
This is a big step, as it signals that virtual care tools and apps could be covered just like medications or medical devices. Overall, insurance payment models are evolving to cover a broader array of services (like care coordination, remote monitoring, and virtual care) and tie payments more closely to quality and outcomes rather than the volume of services.
Regulatory Updates Affecting Healthcare Payments
Changing government regulations in the U.S. will significantly impact healthcare payments in 2025. One of the most impactful is the ongoing drive for price transparency. There’s strong public and bipartisan support for policies that make healthcare costs clear before a patient gets a bill—95% of Americans support more excellent price transparency rules to ensure prices are available to patients. In response, the federal government has implemented rules requiring hospitals to post their prices online and insurers to provide cost estimate tools.
However, compliance has been mixed. Reports indicate that roughly only 36% to 66% of hospitals have been fully compliant with the Hospital Price Transparency rule so far, meaning many patients still struggle to find out what a service will cost. Enforcement is ramping up, and regulators are increasing penalties for non-compliance. The expectation is that by 2025, patients will have better access to upfront pricing, whether through hospital websites or their insurance company’s online tools.
This helps patients shop for non-emergency services and avoid nasty surprises. Speaking of surprises, the No Surprises Act is another key regulatory development. Enacted in 2022, this law protects patients from surprise medical bills – those extra bills from an out-of-network doctor or facility you didn’t know was involved in your care (standard, for example, after an ER visit or surgery).
By 2025, the No Surprises Act’s processes will be in full effect: patients are generally only responsible for in-network cost-sharing amounts in emergency situations or when they don’t have a choice of provider. Any out-of-network payment disputes now go to arbitration between insurers and providers, keeping the patient out of the fight. This law was a response to the fact that 76% of consumers reported receiving an unexpected medical bill at some point.
Early data suggests the law reduces those surprises, giving patients more predictability in what they owe. Regulators are also adapting rules to changing technology. Telehealth policy is a good example, as mentioned above – Congress and CMS have extended Medicare telehealth coverage and are debating making some expansions permanent.
Additionally, there’s a focus on data security and privacy in payments. Healthcare organizations must follow HIPAA regulations to safeguard patient information, and with more digital payments, ensuring PCI compliance (payment card industry standards) and cybersecurity is critical. In 2024, healthcare faced a sharp rise in cyberattacks (over 2,400 attacks per week on average, up 81% from the previous year). Regulators and industry groups in 2025 are emphasizing secure payment systems to protect patient data and maintain trust.
Finally, government policy can indirectly affect payments through insurance coverage expansions or cuts. A looming issue is the scheduled expiration of enhanced Affordable Care Act subsidies at the end of 2025, which could increase uninsured rates if not renewed. More uninsured patients would mean more hospital uncompensated care and potential shifts in how providers approach patient billing (possibly leading to more need for charity care or payment plans). In summary, the regulatory landscape in 2025 is pushing for greater transparency, fairness, and adaptation to new care delivery models, all influencing how payments flow in healthcare.
Patient Payment Behaviors and Expectations
Perhaps the biggest driver of change is patient expectations. Healthcare consumers today approach medical bills with a mindset shaped by their experiences in other industries – they want transparency, convenience, and flexibility. One clear trend is that patients expect digital payment options. Most people already pay their utility or credit card bills online and now demand that same ease for medical bills. Surveys show that 91% of consumers prefer to pay healthcare bills electronically (credit/debit cards, online portals, etc.). Yet, historically, many healthcare providers have been behind the curve. As recently as a couple of years ago, 35% of consumers said they had no option but to pay their medical bills online.
In 2025, providers are rapidly adding online payment portals, mobile payment links via text/email, and office kiosks to meet this demand. Mobile-friendly billing is essential since over half of patients prefer to engage via mobile devices for healthcare tasks. Many hospitals now offer smartphone apps or mobile web portals where patients can view statements, set up payment plans, and pay bills with a few taps.
Another major factor is affordability concerns. Medical costs have been rising; even insured patients often have high deductibles and copays. About 50% of Americans (including those with insurance) worry about affording out-of-pocket healthcare costs and other expenses. Medical debt remains a widespread issue – more than 100 million people in America (41% of adults) have some form of healthcare debt. Because of this, patients are increasingly cost-conscious and proactive about managing bills. Many now ask for cost estimates upfront. (86% of consumers say it’s important to know costs before a provider visits, but only 21% always get that information, which ties back to the push for price transparency.)
Patients are also more willing to shop around for non-urgent procedures or use telehealth if it’s cheaper than an in-person visit. Payment plans and financing options have grown in popularity to help manage bills. Rather than one large medical bill that strains a household budget, patients appreciate being able to pay over time. Nearly 46% of consumers have used a no-interest payment plan to pay a medical bill, indicating almost half have taken advantage of installment arrangements.
Providers in 2025 often partner with financing companies or offer in-house payment plans that break a bill into monthly payments, sometimes without fees or interest. This helps patients get needed care without delay, and providers find it can improve collection rates by making bills more affordable. Hospitals are also increasingly storing credit card information on file (securely via tokenization) to automate payments for those plans or recurring charges. Patients’ customer service expectations have risen as well.
They want medical billing to be understandable and user-friendly. However, there’s a lot of room for improvement: about 71% of consumers find their medical bills confusing. They often struggle to decipher insurance jargon or see what they’re being charged for. This confusion can lead to frustration and delays in payment. In response, many providers are redesigning bills to be more explicit – using plain language, showing itemized charges in a patient-friendly way, and integrating insurance information and adjustments on the same statement.
Better communication is key. Some healthcare systems now provide 24/7 billing support through chat or phone and send reminders via text or email, acknowledging that patients appreciate the kind of follow-up they’d get from any service business. With so many options available, patient satisfaction with the billing experience matters – in one survey, 79% of consumers said they would consider switching providers for a better healthcare payment experience. In 2025, that message has hit home, and healthcare organizations prioritize the patient’s financial experience as part of overall care quality.
Innovations in Billing Processes, Automation, and AI Integration
Behind the scenes, healthcare finance departments are undergoing a tech revolution. Automation and AI (artificial intelligence) are deployed to make billing more efficient, accurate, and patient-friendly. This is crucial because the current process has plenty of inefficiencies – nearly 80% of medical bills in the U.S. contain errors, from simple typos to coding mistakes. These errors cause claim denials and billing headaches for both providers and patients. In 2025, hospitals and billing companies are investing in advanced software to streamline every step of the revenue cycle, from charge capture to collections. Some key innovations include:
Error Reduction and Coding Assistance:
Given the high error rate in manual billing, AI tools are now helping to catch mistakes and code claims properly. AI with natural language processing can scan clinical documentation and automatically assign the correct billing codes for procedures and diagnoses.
This speeds up the coding process and ensures accuracy so providers don’t accidentally under or overbill. By reviewing records in real time, AI can flag inconsistencies (for example, if a drug that was administered didn’t get added to the bill) and suggest fixes before the claim is submitted. These technologies help maximize legitimate reimbursement while maintaining compliance.
Predictive Analytics for Revenue Cycle Management:
Advanced analytics are being used to predict and improve financial outcomes. Machine learning algorithms analyze past billing data to forecast trends in reimbursements and denials. For instance, analytics might reveal that specific insurance claims often get denied for technical reasons – allowing a billing team to address those in advance.
Predictive models can also identify which patients might have difficulty paying so staff can proactively offer financial counseling or payment plans. By spotting patterns (like seasonal cash flow dips or rising patient balances), healthcare finance teams can strategize better and intervene early to keep revenue flowing.
Real-Time Insurance Verification and Claims Processing:
Automation is speeding up interactions with insurers. Rather than staff manually checking a patient’s insurance eligibility or calling an insurance company about a claim, automated systems can do these tasks in seconds.
Real-time payment systems are also emerging – about 83% of healthcare organizations have sent or received instant payments in the last year as the industry explores faster real-time payment (RTP) networks. Faster claims approval means providers get paid sooner, and patients get their bills faster. In some cases, insurers are beginning to use AI to auto-adjudicate claims (approve or deny) within minutes if all info checks out instead of taking weeks. These innovations reduce the traditional lag between a service and when payment is received.
AI-Powered Patient Engagement:
Automation isn’t just for back-office efficiency; it’s also improving how providers interact with patients about bills. AI chatbots and virtual assistants are increasingly used to answer common billing questions and help patients navigate their payments.
For example, a patient might ask a chatbot, “Why does my bill say I owe $100?” and the chatbot can access their account, see that it’s a copay not covered by insurance, and explain that in simple terms – or direct them to a human rep if needed. These tools provide 24/7 support and can handle routine inquiries (“Did you receive my last payment?”, “What financing options do I have?”), freeing up staff to handle more complex cases. Early use of AI in customer service has shown promise in increasing patient satisfaction by giving quick answers. Providers are also using automated texting systems to send reminders about balances due or offer payment plan sign-ups, meeting patients on their preferred communication channels.
Looking at the bigger picture, integrating AI and automation is expected to cut administrative costs and speed up payment cycles significantly. Some estimates claim that AI-driven automation could reduce healthcare billing administrative costs by 40% and speed up claim processing by 80%.
While those figures may vary across organizations, there’s no doubt that the financial side of healthcare is becoming more high-tech. In 2025, about 45% of medical groups plan to deploy new AI solutions in their revenue cycle (up from just 21% a couple of years prior). This includes everything from robotic process automation (RPA) bots that automatically post payments and adjust accounts to AI tools that help detect fraud. For example, AI can flag suspicious billing patterns that might indicate upcoding or insurance fraud before making payments.
These innovations aim to reduce manual work, accelerate reimbursements, and ensure that billing is accurate, secure, and as seamless as possible for everyone involved.
Conclusion
Healthcare payment systems in 2025 are undergoing transformative change. Digital payment solutions are making it easier for patients to pay and for providers to get paid quickly, whether through a tap on a phone or a blockchain-verified transaction. Insurance reimbursement models are gradually shifting to reward value and incorporating new forms of care while regulatory changes push for transparency and fairness in billing.
Meanwhile, patients are more empowered and vocal about wanting convenient, straightforward, and affordable payment options, leading providers to elevate the financial experience as a core part of healthcare service. On the operations side, billing departments are embracing automation and AI to eliminate errors and inefficiencies that have long plagued the system. These trends intertwine toward a common goal: creating a more consumer-friendly, efficient, and transparent healthcare payment ecosystem. Medical bills and insurance payments may never be anyone’s favorite topic, but by 2025 and beyond, they should be a lot less of a pain point than in the past. Hospitals and clinics will continue to innovate – from offering a one-click payment on your patient portal to sending you a cost estimate before a procedure – making the financial side of healthcare more straightforward to navigate.
For patients, this means less confusion and more control. It means modernizing processes to reduce costs and improve cash flow for providers and payers. While challenges like rising healthcare costs and cyber threats remain, the payment trends of 2025 indicate an industry actively working to meet the needs of the digital age. By staying on top of these trends, all stakeholders can better prepare for a future where paying for healthcare is as seamless as the care itself.
Last year, the Consumer Financial Protection Bureau (CFPB) sued EWS (which operates Zelle payments) along with the major bank owners – Bank of America, JPMorgan Chase, and Wells Fargo. According to a statement published by the CFPB at the time, the operators failed to protect consumers from Zelle fraud perpetrated on their payment platform.
CFPB, which is a government agency with the main goal of protecting consumer interests by offering financial protection, said in a statement published on its website that customers using banking services from the said operators have lost over $870 million to fraud. This data shows records since the inception of Zelle, seven years ago. In the lawsuit filed by the CFPB, the agency alleged that Zelle and its banking partners failed to implement any solid measures to safeguard consumers from fraud.
But in the recent turn of events, CFPB has dropped its lawsuit. The agency submitted a brief, one-page document formally dismissing the complaint with prejudice, permanently preventing it from being refiled. In the second half of February alone, the CFPB has withdrawn at least seven lawsuits initiated under the Biden administration, including cases involving Rocket Homes, Capital One, and TransUnion.
Key Takeaways
The Consumer Financial Protection Bureau has officially dismissed its lawsuit, with prejudice, against Early Warning Services (which operates Zelle), JPMorgan Chase, Bank of America, and Wells Fargo. This means the claims cannot be refiled.
Since acting Director Russell Vought took over the CFPB, the agency has dropped at least seven lawsuits initiated under the Biden administration. These actions are part of broader changes to the agency’s direction and structure under the current leadership.
The CFPB lawsuit alleged negligence in protecting consumers from fraud on the Zelle payment platform. The lawsuit highlighted nearly $870 million in consumer losses since Zelle’s launch in 2017, citing failures in fraud prevention, identity verification, and customer support.
The lawsuit accused the defendants of violating the Electronic Fund Transfer Act and Regulation E by failing to adequately safeguard consumers. Banks, however, argued against the claims, describing the regulatory action as politically motivated and exceeding CFPB’s authority, with Zelle asserting that it employs leading fraud prevention measures.
During that period, consumer protection groups supported CFPB’s focus on addressing systemic fraud issues, while the Consumer Bankers Association (CBA) defended the banks, highlighting Zelle’s comparatively lower fraud rates and criticizing the CFPB for what it deems an overly broad regulatory approach.
The dismissals have sparked backlash from former officials and consumer advocates, who warn that the move may undermine efforts to hold financial institutions accountable and recover funds for defrauded customers. A CFPB employee union is now suing to block what it sees as the agency’s dismantling.
Consumer Watchdog Withdraws Zelle Fraud Case, Closing Door on Key Recovery Option
On March 4, 2025, the Consumer Financial Protection Bureau (CFPB) filed a notice in federal court signaling it was dropping the high-profile lawsuit it brought in December against JPMorgan Chase, Bank of America, and Wells Fargo over fraud on the Zelle peer-to-peer payments network. That December complaint, initiated by then-Director Rohit Chopra in the waning days of the Biden administration, accused the three banks—and Zelle’s operator, Early Warning Services – of failing to protect consumers from hundreds of millions of dollars in scam losses. The abrupt withdrawal marks one of at least seven Biden-era enforcement actions the agency has now abandoned under the Trump administration’s new leadership.
Zelle, launched in 2017 by Early Warning Services—a consortium controlled by seven major banks, including the defendants in this suit—quickly became one of the foremost U.S. person-to-person payment platforms. In 2024 alone, consumers and small businesses moved roughly $1 trillion over Zelle, a 27 percent jump from the prior year, and completed some 3.6 billion transactions across 151 million enrolled accounts. Despite its popularity, the CFPB alleged that Zelle’s rapid roll-out lacked the necessary safety features to stop fraudsters from exploiting the network.
In its original filing, the CFPB charged that, in a rush to compete with apps such as PayPal’s Venmo and Block’s Cash App, EWS and its bank owners “rushed to put out Zelle” without implementing proper consumer safeguards. Over seven years, customers of the named banks reportedly lost $870 million to scams on the platform, and hundreds of thousands of fraud complaints were either inadequately investigated or outright denied. Some victims were allegedly told to contact the scammers directly to seek reimbursement—a stark contravention of norms under the Electronic Fund Transfer Act.
The CFPB’s March 4 filing was notably terse—just one page—and dismissed the complaint “with prejudice,” meaning it cannot be revived in the future. This move follows a broader pullback: in recent weeks, the bureau has dropped suits against Capital One, Rocket Homes, TransUnion, and Vanderbilt Mortgage & Finance, among others. Many other pending cases initiated under Chopra have been paused, leaving a swath of consumer-protection actions in limbo.
These developments unfolded amid a sweeping reorganization of the CFPB under the Trump administration. President Trump ordered the bureau to halt nearly all its work, shutter its headquarters, and seek mass firings of career staff—measures that agency officials contend would violate federal law. In addition, Office of Management and Budget Director Russ Vought, serving as Acting CFPB Director, publicly decried prior litigation as a “weaponization of ‘consumer protection’” and has overseen the cancellation of multiple enforcement actions. Employee unions and consumer-advocate groups have already filed suit to block what they view as an unlawful gutting of the agency.
Banks and industry groups greeted the suit’s dismissal with relief. Early Warning Services called the case “without merit, and legally and factually flawed,” and said it looks forward to continuing service to its 151 million account holders. JPMorgan stressed that combating fraud “requires a collective effort across the public and private sectors.” Bank of America declined to comment, while the Consumer Bankers Association noted that its members have “consistently followed the law” and urged policymakers to focus on underlying causes rather than assign blame.
For consumers who lost money to fraud on Zelle, the dismissal eliminates one avenue for relief. Because the dismissal is with prejudice, those defrauded cannot return to this particular suit to recover funds. Instead, they must rely on voluntary bank reimbursement policies or future regulatory rule-making, though with the CFPB’s enforcement arm in retreat, even those prospects appear uncertain. The retreat is not limited to the CFPB: the Securities and Exchange Commission has also paused or closed several high-profile cryptocurrency cases, signaling a broader pullback in federal financial oversight.
This episode is emblematic of a larger shift in U.S. financial regulation. Under former Director Chopra, the CFPB pursued a robust agenda of consumer-protection litigation, targeting an array of financial and fintech firms. Now, nearly all of those suits have been halted or dismissed, dramatically lowering the regulatory risk for large banks while raising questions about the future of consumer safeguards in the payments space. Should fraud losses continue to mount, state attorneys general or Congress itself may feel compelled to step in.
The CFPB’s decision to drop the Zelle lawsuit against JPMorgan Chase, Bank of America, and Wells Fargo underscores how swiftly enforcement priorities can be upended by a change in administration. As peer-to-peer networks proliferate and digital payment volumes climb, the adequacy of voluntary industry safeguards—and the willingness of regulators to enforce them—will remain under scrutiny. For now, Zelle’s users will have to trust that platforms and banks will shoulder more responsibility for stopping fraud, even as the federal watchdog steps back from its most aggressive tools.
CFPB Accused Major Banks and Zelle Operator of Negligence in Addressing Fraud Risks: A Brief Look
On 20 December 2024, the CFPB took legal action, where the centre of the allegations in the lawsuit was that these banks and EWS failed to implement adequate measures to protect and prevent widespread fraud in the payments network. As mentioned, the figures reported (which almost touch a billion dollars) in the lawsuit showcase the drastic ignorance by the “leading” and “trusted” banks in the US. The CFPB at the time took a dig at the banks for not acting and even addressing the ongoing widespread fraud on the network, despite having the means and obligations to do so under the Electronic Fund Transfer Act and Regulation E, which require financial institutions to investigate and resolve errors in electronic fund transfers.
Rohit Chopra at the time stated that this situation involved financial institutions meeting their fundamental responsibilities to safeguard customer funds and assist fraud victims in recouping their losses. He, at the time, criticized the banks for violating the law by operating a payment system that facilitated fraud and subsequently failing to support the affected customers.
Chopra criticized the banks for favoring quick service at the expense of security. He explained that the country’s major banks, feeling the pressure from rival payment applications, quickly launched Zelle. However, their lack of adequate security measures turned Zelle into an attractive target for fraudsters.
According to the lawsuit, the said parties failed to offer standard fraud detection and protection measures, which were the direct outcome of thousands of consumers losing millions of dollars since the launch of Zelle in 2017. The lawsuit highlighted these key lapses:
Failure to Track and Restrict Fraudsters: The lawsuit criticized Early Warning Services and the defendant banks for not acting swiftly to restrict and track criminals exploiting the system. It was noted that banks did not share information about known fraudulent transactions, allowing repeat offenders to exploit multiple institutions.
Inadequate Identity Verification: The CFPB claimed that Zelle’s limited identity verification methods allowed fraudsters to easily create accounts and target users, linking victims’ tokens to fraudulent accounts and redirecting intended payments.
Neglecting Red Flags: Despite numerous fraud complaints, the banks reportedly failed to use this information effectively to prevent further fraudulent activities and did not consistently report fraud incidents as required by the Zelle Network’s rules.
Inadequate Consumer Support: The banks were also accused of failing to properly investigate and resolve customer complaints about fraud, which is required under the Electronic Fund Transfer Act and Regulation E.
The CFPB’s legal action aimed to stop these unlawful practices, secure redress for affected consumers, and impose penalties against the institutions involved. The agency had been investigating payment networks like Zelle since 2021 to address these systemic issues.
Zelle, in response to the lawsuit back then, had defended its practices, stating that the lawsuit’s claims were baseless and asserted that the platform has industry-leading fraud prevention measures in place. The company argued that the legal action is politically motivated and not based on factual evidence of the network’s operations.
Zelle had expressed its readiness to robustly challenge what it describes as an unfounded lawsuit. In its defense, Zelle claimed that the allegations made by the CFPB are both legally and factually incorrect, suggesting that the lawsuit’s timing might be influenced by political motivations that do not pertain to the company’s operations.
Whereas, EWS also at the time criticized the CFPB’s actions, claiming they could unintentionally support criminal activities, increase consumer fees, hinder small businesses, and challenge the competitive ability of many community banks and credit unions.
In its statement to counter the lawsuit, Bank of America reported that over 99.95% of Zelle transactions are completed without any problems, criticizing the CFPB’s attempts to introduce substantial new costs for the more than 2,200 banks and credit unions that provide Zelle services to their customers at no extra charge.
Additionally, JPMorgan Chase had at the time accused the CFPB of exceeding its regulatory authority by holding banks responsible for the actions of criminals, including those involved in romance scams. The bank described this move as a clear case of “regulation by enforcement,” arguing that it bypasses the standard rulemaking process, which typically guides such regulatory actions.
Consumer Banking Association Defending Banks
The Consumer Bankers Association (CBA) at the time had openly expressed its concerns regarding the Consumer Financial Protection Bureau’s (CFPB) regulations on digital payments. The association back then had specifically pointed out the CFPB’s oversight as overly broad, surpassing what they considered to be the legislative boundaries set by Congress. They particularly highlight the CFPB’s scrutiny of Zelle, a payment platform operated by banks, noting that it recorded fewer fraud cases than other platforms.
The CBA acknowledged the importance of consumer protection but suggested that the CFPB’s regulatory path might be unnecessarily stringent and not aligned with legislative intentions.
In a statement released at that time, CBA President Lindsey Johnson emphasized the banking industry’s commitment to safeguarding customers against fraud, pointing out that combating such threats requires a collective effort beyond just the banking sector. Johnson also criticized the CFPB for its focus on a bank-owned platform, which, he noted, reports significantly fewer fraud incidents than other platforms, suggesting that the CFPB’s approach may be unfairly targeted.
Additionally, the CBA had underscored its proactive steps towards securing customer transactions, which include implementing multi-factor authentication, chip-enabled cards, and AI-driven technology to identify and mitigate fraud risks. They stress the need for a multi-sector effort to effectively combat fraud, extending beyond just the financial industry to include cooperation from government bodies and other sectors.
Communications from the CBA at the time advocated for a regulatory approach that avoids placing undue burdens on bank-owned payment systems and promotes cooperative regulatory development that includes significant input from the financial sector. They sought a more equitable regulatory framework that does not hinder bank-operated services while still maintaining robust consumer protections.
Bank of America, N.A. is a subsidiary of Bank of America Corporation, with its main office in Charlotte, North Carolina. This significant financial institution provides a broad array of banking, investment, asset management, and risk management products and services. It manages around 3,700 retail financial centers and 15,000 ATMs across the U.S., and it supports 58 million digital users.
On an international scale, it serves corporations, governments, and individual clients, and it plays a key role in wealth management, corporate, and investment banking. As of mid-2024, Bank of America reported more than $2.5 trillion in total assets and is listed on the New York Stock Exchange under the ticker symbol NYSE: BAC. The bank serves approximately 69 million U.S. consumer and small business customers, underlining its strong influence in the financial markets both in the U.S. and globally.
JPMorgan Chase Bank, N.A., a subsidiary of JPMorgan Chase & Co., is based in Columbus, Ohio, and is the largest bank in the United States. As of mid-2024, it holds more than $3.5 trillion in total assets. The bank’s operations are divided into several segments: Consumer & Community Banking, Commercial & Investment Banking, and Asset & Wealth Management. It provides a wide range of financial services, including banking, asset management, and investment services worldwide.
JPMorgan Chase is recognized for its extensive market presence and offers services to a broad spectrum of clients, including individual consumers, large corporations, and government entities, with a strong emphasis on innovation and customer service.
About Early Warning Services
JPMorgan Chase Bank, N.A., a subsidiary of JPMorgan Chase & Co., is based in Columbus, Ohio, and is the largest bank in the United States. As of mid-2024, it holds more than $3.5 trillion in total assets. The bank’s operations are divided into several segments: Consumer & Community Banking, Commercial & Investment Banking, and Asset & Wealth Management. It provides a wide range of financial services, including banking, asset management, and investment services worldwide.
JPMorgan Chase is recognized for its extensive market presence and offers services to a broad spectrum of clients, including individual consumers, large corporations, and government entities, with a strong emphasis on innovation and customer service.
About Zelle
Zelle, managed by Early Warning Services, enables quick electronic money transfers using linked email addresses or U.S. mobile phone numbers, often referred to as “tokens.” Users have the option to link multiple tokens to various banking institutions, which allows for swift transfers between banks.
Conclusion
The CFPB’s decision to withdraw its lawsuit against JPMorgan Chase, Bank of America, Wells Fargo, and Zelle operator Early Warning Services brings a sudden halt to what was shaping up to be a significant legal battle over consumer protection in digital payments. By dismissing the case with prejudice, the agency has closed the door on any future attempts to litigate these specific claims, leaving affected consumers without a direct path to recover fraud-related losses through this action.
This move reflects broader changes underway at the CFPB under new leadership, which has rolled back several enforcement efforts initiated during the previous administration. The shift has drawn criticism from former officials, consumer advocates, and even within the agency itself, raising concerns about the agency’s long-term ability to hold large financial institutions accountable.
While Zelle and the banks involved continue to defend their fraud prevention efforts, the withdrawal of the case leaves questions about the role of federal regulators in overseeing fast-growing digital payment platforms. As fraud risks persist, the burden may now shift to states, Congress, or voluntary industry reforms to address gaps in consumer protection. For now, users of peer-to-peer payment systems are left to rely largely on the internal policies of banks and platforms—an uncertain safeguard in an environment where fraud remains a growing concern.
A successful growth marketing strategy can result in consistent revenue and long-term growth. However, it’s essential to identify which methods are worth the investment and which may not meet expectations. Finding the best approach can be challenging, as no one-size-fits-all solution exists. Most businesses will require a combination of tactics to achieve sustainable results. Fortunately, there are numerous strategies to consider.
Here are key growth marketing tactics you can integrate into your plan immediately:
New Marketing Ideas to Help Your Business
1. Audit Your Website (and Optimize It)
Your website serves as the core of your marketing efforts. If it has issues, your marketing performance may suffer. Start by examining critical aspects like page speed, mobile responsiveness, and navigation. Slow-loading pages, confusing menus, or poor mobile design can deter visitors and hurt your search engine ranking. Use tools such as Google PageSpeed Insights and Google’s Mobile-Friendly Test to identify and address these problems, helping your site meet user expectations and search engine standards.
Next, assess your site’s content. Outdated or irrelevant information can harm both user experience and SEO. Update pages with accurate details, ensure keywords align with current search trends, and optimize meta tags. Also, check for duplicate or broken content, which can reduce credibility and rankings. Tools like Yoast SEO and Semrush can help pinpoint issues and suggest improvements.
Finally, review your site’s technical structure. Verify that redirects are set up correctly, internal links are well-organized, and the overall site architecture allows users and search engines to navigate smoothly. Ensure all security measures, such as SSL certificates, are active to protect your site and its visitors.
2. Set Up a Free Google My Business Profile
Setting up a Google Business Profile is a practical marketing strategy for local businesses. It provides a no-cost option for increased visibility. When you register your business, it appears in Google Maps, local search results, and the Knowledge Panel during branded searches.
The importance of this tool lies in its ability to attract local customers. Statistics show that around 70% of individuals searching locally visit a business within a five-mile radius. By maintaining accurate and current information on your Google Business Profile, you can draw in these local searchers and turn them into customers.
Optimizing your listing for a better presence in Google Maps and local searches is vital to enhance the effectiveness of your Google Business Profile. Establish a Google account specifically for your business, which helps keep personal and business data separate. Access your profile via the Google Business Profile site by selecting “Manage now.” You’ll need to verify your business by entering its name; if it isn’t listed, you can add it manually. Choose your business category carefully to ensure Google accurately connects you with the intended audience.
Further details such as your physical location, service areas, contact information, and website should be added next. These elements are key to your visibility in local searches and on Google Maps. To confirm ownership and unlock more features, Google offers verification options, including a postcard, phone, or email. Keeping your profile updated with the latest information, events, and promotions, and interacting with customer reviews enhances trust and engagement, boosts your local search ranking, and makes it easier for customers to discover and engage with your business.
3. Use Social Media Strategically
Social media marketing is an essential element of modern business strategies, serving as a platform for sharing promotional content and interacting with a large audience. With approximately 4.89 billion active users globally, social media offers various opportunities to connect with potential customers.
Different platforms target specific user groups:
Facebook: Facebook has more than 3 billion active users monthly, predominantly aged 25-34.
Instagram: Attracts a younger demographic, especially those aged 18-29.
Snapchat: Mainly used by people aged 18-24.
LinkedIn: Focuses on professionals, making it suitable for B2B marketing.
YouTube: Acts as the second most popular search engine after Google, appealing to a wide audience.
Knowing these demographics helps businesses to distribute their social media marketing budgets more effectively, aiming to reach the right audience. Different platforms necessitate different content strategies:
Facebook and Instagram are best suited for visual content like images and videos.
LinkedIn is ideal for sharing professional articles and industry insights.
Snapchat and TikTok favor short, engaging videos that attract younger viewers.
Creating content that matches the characteristics of each platform and meets audience expectations can increase engagement and improve conversion rates. For example, Audi effectively uses social media to maintain a consistent brand image across different platforms. On Instagram, they post high-quality images of their vehicles in attractive settings, strengthening their luxury brand image. This strategy has helped them build a significant following and showcases the effectiveness of well-tailored content that upholds brand values.
4. Harness Short-Form Video and Social Media Trends
Short-form video has become the dominant content format across social platforms in 2025. Platforms like TikTok, Instagram Reels, and YouTube Shorts continue to explode in popularity, with global consumption of short videos up 75% in the past year. Video content is expected to account for 82% of all internet traffic by 2025. Brands can’t afford to ignore this trend – engaging video content is now essential to capture attention.
Create bite-sized videos regularly: Demonstrate your product, share quick how-tos, or jump on trending audio challenges. These fun, easily digestible videos can dramatically boost your visibility in social feeds. Social videos generate 1,200% more shares than text and images combined, which can amplify your reach through viral sharing.
Leverage platform features: Use TikTok’s editing effects, Instagram’s interactive stickers, or YouTube Shorts’ captions to make videos more engaging. Interactive content is on the rise – for example, live-stream shopping events are gaining traction, with global live commerce sales projected to hit $500 billion by 2025. Consider hosting a live demo or Q&A to drive real-time engagement and even direct sales.
Diversify across channels: Don’t put all your effort into one network. Trends can shift quickly (note the uncertainty around TikTok’s regulatory status). A multi-platform strategy (e.g. Instagram + TikTok, or YouTube + Facebook) ensures you’ll reach your audience even if one algorithm changes. The key is to be where your customers are consuming content – and today, that’s overwhelmingly on mobile video.
Above all, keep it short, authentic, and frequent. A steady drumbeat of video content will keep your brand in front of followers as algorithms favor active creators. Monitor what’s trending each week and find creative ways to participate that align with your brand. Done right, a single clever video can drive huge end-of-year momentum.
5. Use Holiday-Based Visuals
In 2025, you must use holiday-themed visuals and posts to engage your audience during the festive season. Highlight special offers, create seasonal content, and tailor your messaging to reflect the celebrations. This approach can boost engagement, encourage sharing, and strengthen your brand’s connection with your audience.
As people indulge in holiday traditions like decorations, themed attire, or special treats, brands can participate by adding holiday-specific content to their social media strategies.
Create static images and videos that reflect popular holiday motifs, such as seasonal patterns, iconic imagery, and color schemes. These posts should align with your brand’s identity while adding fresh and timely elements that connect with the festive mood. Ensure consistency in your holiday content to present a cohesive look that enhances your audience’s experience. Each piece should also follow your brand guidelines to ensure your branding remains professional and recognizable throughout the season.
6. Automate and Streamline Your Content and Campaigns with AI
The rise of artificial intelligence is a game-changer for marketing in 2025. AI tools are helping businesses produce content, analyze data, and personalize campaigns faster and cheaper than ever. Over 56% of marketers report their companies are currently using AI in some marketing capacity, and some surveys put usage even higher. Embracing AI can give you a competitive edge in both efficiency and creativity.
Generative AI tools can help you brainstorm social posts, write ad copy variants, or even draft blog outlines. This speeds up your workflow while maintaining quality. For example, Meta’s new AI Sandbox for advertisers auto-generates multiple ad text variations and images, saving creative teams time.
You can use AI to A/B test different messages and quickly double down on what resonates with your audience. Plus, today’s AI chatbots are far more advanced than the clunky bots of a few years ago. With natural language processing, they can handle customer inquiries, recommend products, or capture leads 24/7 in a very human-like way. Implementing an AI-driven chatbot on your site or Facebook Messenger (now Meta Messenger) can improve customer service and free your team from repetitive Q&A. Many businesses also use chatbots for instant support on WhatsApp or other messaging apps, meeting customers where they are with immediate answers.
You can also take advantage of AI in your data analysis and ad targeting. Platforms like Google and Meta have AI-powered campaign tools (e.g., Google’s Performance Max or Meta’s Advantage+ ads) that automatically optimize your ad placements and budget across channels. AI crunches the numbers faster than any human, identifying which audience segments or creative elements drive the best results.
Marketers who leverage these can often stretch their budget further by letting the algorithm allocate spend to top-performing areas. Additionally, AI-driven analytics dashboards can spot trends in customer behavior (like an emerging product interest) and suggest actions, helping you stay agile in the last stretch of the year.
7. Collaborate with Influencers and Creators
Influencer marketing has matured by 2025 into a powerhouse channel for driving brand awareness and sales, when done thoughtfully. The industry has grown exponentially: it’s projected to reach $32.5 billion globally by the end of 2025, up from just $9.7 billion in 2020. Plus, over 80% of marketers now find influencer campaigns highly effective.
If you haven’t revisited your influencer strategy recently, now is the time. A well-chosen partnership in the last stretch of the year can expand your reach to new customers right when they’re primed to spend. Micro and nano-influencers (those with smaller, highly engaged followings) continue to be secret weapons for businesses. They often deliver better engagement rates and trust with audiences compared to big celebrities. Micro-influencers on Instagram (often defined as under ~50k followers) see stronger interaction rates, and they make up the vast majority of creators.
For a modest budget, you could partner with several niche influencers who speak directly to your target demographic. For example, if you sell fitness gear, collaborating with a few up-and-coming fitness coaches or yoga enthusiasts on Instagram/TikTok can yield authentic product shoutouts that followers trust. Authenticity is crucial – audiences today are quick to sniff out inauthentic paid posts. Look for partners who genuinely align with your brand’s niche or values.
When planning campaigns, give influencers creative freedom to present your product/service in their voice. They know what resonates with their followers. Whether it’s a TikTok challenge, an unboxing video, a tutorial, or a heartfelt story, content feels more genuine when the creator’s personality shines. Ensure disclosures are in place (transparency is a must), but aside from that, collaborate rather than dictate. The result will be content that audiences enjoy, which translates into higher engagement and conversions. Remember, consumers often see influencers as peers; one study found people view user/influencer content as more impactful in purchasing decisions than traditional brand content.
Consider timing and special campaigns for the end of the year. Perhaps line up an influencer “holiday gift picks” post featuring your product, or a New Year’s challenge that organically involves your service. Influencers can create a sense of trendiness or urgency around your offerings (“I’m using this planner to crush my 2025 goals, you guys have to try it!”). Their endorsement provides social proof to hesitant buyers. And it’s not just B2C – even B2B companies are leveraging influencers (or industry thought leaders) via webinars, LinkedIn posts, or podcasts to sway decision-makers.
If you’re concerned about budget, note that not all partnerships require hefty fees. Some micro-influencers will work in exchange for free products or commissions through affiliate links. Track the results (use unique discount codes or affiliate links for each influencer to measure sales they drive) and focus on return on investment. As with any marketing effort, some experiments will perform better than others. The goal by year-end is to identify 1-2 influencer relationships that pay off, then nurture those going forward. With smart collaboration, influencers and creators can introduce your business to new, eager audiences and add momentum to your Q4 marketing push.
8. Respond to All Reviews
Managing your business’s online reputation is crucial, as 93% of consumers consult online reviews before purchasing. It’s important to actively monitor and engage with both positive and negative reviews to build customer trust and loyalty. Promptly addressing negative feedback is key; acknowledging customer concerns, apologizing when appropriate, and suggesting a solution or further discussion offline show a commitment to customer satisfaction and can help protect your reputation.
Similarly, responding to positive reviews with gratitude can strengthen customer relationships and promote repeat business. Simply thanking customers can enhance community feelings among your clientele. Best practices in managing online reviews include responding quickly—53% of consumers expect businesses to reply to negative feedback within a week. Personalizing responses to address specific comments demonstrates genuine engagement while maintaining a professional tone, even in response to criticism, which is essential for keeping interactions respectful and constructive.
9. Maximize Email Marketing (and SMS) ROI
Email remains one of the highest-ROI marketing channels in 2025 – a reliable workhorse that should be in your year-end strategy. Nearly 4.5 billion people worldwide use email in 2025, and that number keeps growing. Crucially, email consistently delivers great returns: for every $1 spent on email marketing, the average return is about $36.
To finish strong, double down on email campaigns and refine them using today’s best practices. First, refresh your email list and content. Make sure you’re reaching an engaged audience – remove inactive subscribers and use a signup push (e.g., via your social media or website) to capture new leads before holiday promotions. An up-to-date list means better open rates and deliverability. Speaking of opens, note that 88% of users check email multiple times per day, so a compelling subject line or timely offer can quickly catch attention.
Aim for concise, value-driven email content that respects busy inboxes. Personalization is key in 2025 (consumers are tired of generic blasts). Simple touches like addressing recipients by name and segmenting your list by interest or purchase history go a long way. If you have the data, try dynamic content – for example, show different product recommendations to different segments within the same email. Remember, nearly 60% of consumers say marketing emails influence their purchase decisions, but they won’t be swayed by irrelevant content. Tailor your messaging to each audience subset for maximum impact.
Don’t overlook automation and triggered emails to capture low-hanging fruit. Set up or refine your automated flows: a welcome series for new subscribers, cart abandonment reminders for shoppers who left items in their basket, re-engagement emails to win back dormant customers, etc. Automated emails can generate 320% more revenue than non-automated sends by targeting the right person at the right moment.
As Q4 kicks in, consider a drip campaign counting down to year-end deals or offering tips that naturally lead into your product/service as the solution. Finally, consider SMS and messaging apps as a complement to email. Text messages have extraordinary open rates (often well above 90% within minutes). An SMS alert about a flash sale or an exclusive coupon code for your VIP customers can drive immediate action, especially during the holiday rush. Likewise, if you serve markets where WhatsApp or Telegram are popular, you can broadcast updates or deals there (just be mindful of not spamming and always get opt-in). These direct channels cut through the noise – for example, a short “Last chance for 25% off – today only!” text can nudge indecisive customers to convert before year-end.
10. Boost Holiday Engagement with User-Generated Content
Utilizing user-generated content (UGC) during the holiday season is an effective way to display your brand’s products through authentic customer experiences. UGC, such as customer-shared videos or photos of your products in festive settings, offers a realistic view that traditional advertisements often do not provide.
To encourage user participation, start conversations with your audience about their holiday plans and discuss how your products could enhance their celebrations. For example, a food company could invite customers to post recipes or photos of their holiday meals, including their products. Additionally, practice social listening by monitoring social media for organic mentions of your brand, and when you find positive posts, ask permission to share them on your official channels. This amplifies genuine customer voices.
The benefits of user-generated content are significant. UGC not only builds trust among potential customers, who generally view peer recommendations as more credible than traditional ads, but it also offers a cost-effective marketing strategy by reducing the need to produce costly original content. Moreover, sharing UGC enhances engagement by fostering a sense of community and encouraging more customers to interact with your brand, boosting overall involvement and loyalty.
11. Personalize the Customer Experience at Scale
One marketing approach that will not survive in 2025 is one-size-fits-all mass marketing. Today’s consumers expect personalization – they want to feel like you understand their needs and preferences. If you treat all customers the same, you risk blending into the background. On the other hand, tailoring your outreach can pay huge dividends. Consider that 49% of consumers say they’re more likely to become repeat buyers after a personalized shopping experience, and a vast majority of marketers report that personalization has a direct impact on improving sales. The message is clear: to finish strong, make your marketing messages as relevant and personal as possible. Start with your customer data.
Hopefully, over the years, you’ve been collecting first-party data – emails, purchase history, browsing behavior, survey responses, etc. Use this data to segment your audience into meaningful groups. For example, you might create segments like “loyal repeat buyers,” “high potential leads who haven’t purchased,” “customers interested in Category X but haven’t tried Category Y,” and so on. Then craft campaigns specific to each segment. A repeat buyer could receive an exclusive loyalty offer or early access to a new product (playing on their loyalty and FOMO).
A high-potential lead might get a targeted message addressing common objections and offering a first-time buyer discount. When customers feel you get them, they respond. 70% of customers expect companies to understand their individual needs in 2025’s market – if you don’t, your competitor might. Dynamic content and recommendations are powerful tools for personalization. On your website or in emails, you can use algorithms (or simpler rule-based systems) to show products or content based on what that person has viewed or purchased before.
Think of how Netflix or Amazon surfaces recommendations just for you – you can mimic this on a smaller scale. For instance, your e-commerce site can showcase a “Recommended for you” section, or your email to a user who bought product A can highlight accessories or related items to complement their purchase. Personalized product recs can increase conversion rates and basket sizes by suggesting exactly what the customer was likely looking for. Don’t forget about personalizing the experience beyond just products. Tailor the channel and timing to customer preferences. Some customers might prefer texts for urgent alerts (as mentioned earlier), others long-form content via email, and some might engage more with social media DMs or a phone call from a rep for B2B. Use preference centers or past interaction data to honor these choices. Also, ensure your website and ads use localization if relevant – for example, showing local store info or pricing in the customer’s currency/language.
These details make the experience feel bespoke. Another aspect of personalization is leveraging zero-party data, which is information customers voluntarily share about their preferences (through quizzes, wish lists, account settings, etc.). If a customer tells you their style, size, or business goals, make sure you use it. For instance, if you run a clothing box service and a subscriber indicates they dislike a certain color or pattern, your year-end marketing should highlight items that align with their stated tastes. It shows you listen and care. Implementing personalization at scale is made much easier with modern marketing tech – many email platforms, CRM systems, and e-commerce tools have built-in personalization and automation features.
If you have a modest list, even simple mail-merge personalization and a few segmented email versions can do the trick.
The important part is the mindset: think customer-first. Before sending any marketing message in Q4, ask “Is this relevant to this recipient? Does it address their interests or needs?” If not, rework it or don’t send it. As HubSpot’s research succinctly put it, mass-blast marketing needs to be abandoned. In its place, focus on quality interactions. By delivering the right message at the right time to the right people, you’ll not only boost your year-end sales but also lay the groundwork for stronger customer relationships in 2026. Personalization and attentiveness make customers feel valued, and a valued customer is likely to stick around (and spend more).
12. Creating a Referral Marketing Strategy to Motivate Existing Customers
Referral marketing proves highly effective, with 92% of people showing a preference for recommendations from friends over other marketing forms. This strong preference highlights the significant role of word-of-mouth (WOM) advertising. Known for its effectiveness, WOM advertising, however, presents challenges in its generation.
WOM advertising takes two main forms:
Organic WOM: This happens naturally when customers are satisfied with a product or service and share their experiences spontaneously.
Incentivized WOM: This involves referral programs and campaigns that actively encourage customers to talk about their experiences, thereby accelerating WOM within existing or new social groups.
These two forms work together; a robust marketing campaign enhances WOM and also draws new leads organically. Statistics show that 77% of consumers trust reviews over direct advertising from brands. With billions online, a single positive review can greatly influence your brand’s image. Although establishing WOM for a new brand can be demanding, certain tactics can improve this aspect of marketing.
Developing a referral program that rewards customers for sharing their experiences can be very beneficial. Possible rewards include discounts, gift cards, or other benefits that demonstrate appreciation and put the customer’s experience first, which is key to any inbound marketing strategy.
As your brand develops, generating WOM tends to become more manageable. Starting community groups centered around your brand can also support this environment. Over time, pleased customers often turn into brand advocates, promoting your brand through social media and other channels without additional prompting.
It’s crucial to ensure that every aspect of customer interaction, from navigating the website to completing a purchase, is positive. A strong foundation in customer service increases the chances of customers sharing good experiences, thus promoting your brand naturally.
13. Boost Engagement with Seasonal Content Strategies for Your Business
Developing seasonal content for your website can greatly increase audience engagement, especially during crucial times such as holidays. Here’s a strategy to apply this concept across various businesses:
Spas: With holidays often bringing stress, spas can offer content on relaxation and wellness tips to help visitors de-stress. Articles providing practical advice on handling holiday pressures can be particularly useful.
Auto Repair Shops: Publish articles that offer advice on preparing cars for colder conditions. Topics might include how to winterize cars and what essential items to keep in vehicles during winter, such as blankets and jumper cables.
Restaurants: Post holiday-themed recipes or cooking tips that feature your restaurant’s specialties. You could also promote special holiday menus or discounts and encourage customers to share their meal photos with a unique hashtag.
Fitness Centers: Create content around holiday fitness challenges or tips for maintaining health during the festive period. Showcase success stories or fitness journeys submitted by users to motivate your community.
Bookstores: Recommend holiday reading lists tailored to various ages or interests. Invite customers to post photos of their holiday reading nooks or favorite cozy spots to read your books.
Travel Agencies: Offer guides on top holiday destinations or tips for safe travel during the peak season. Include customer photos from trips organized through your agency to highlight authentic travel stories.
Home Services: Provide articles on preparing homes for seasonal changes. Suggestions on how to weather-proof homes or set up for holiday guests can be particularly engaging.
By preparing this content, you can publish it when it is most likely to attract attention. Keeping the content timely and updated each year is vital, ensuring it remains relevant to your audience’s interests and needs. Additionally, balancing evergreen content with seasonal topics can keep your website pertinent all year while addressing specific interests and trends during particular times.
14. Focus on Customer Retention and Loyalty Programs
Remember that retaining and upselling your existing customers can be one of the fastest ways to boost revenue as the year ends. There’s a famous business axiom that acquiring a new customer can cost five times more than retaining an existing one, and it holds in 2025. By late in the year, you’ve hopefully built up a base of customers; turning them into repeat buyers or subscribers can yield big wins. Even a small increase in retention can have an outsized effect on profits. (For example, a Harvard Business Review study found that increasing customer retention by just 5% can boost profits by 25% to 95%!) So, let’s capitalize on that.
Loyalty or rewards programs are a proven way to incentivize repeat business. If you don’t have one yet, consider launching a simple loyalty initiative for Q4: it could be as straightforward as “Spend $100, get a $10 coupon” or a points system for each purchase that unlocks a discount or freebie. If a formal program isn’t feasible immediately, even a limited-time VIP sale for past customers or a thank-you bonus (like a free upgrade or gift with their next purchase) can make your customers feel appreciated.
The goal is to say “thank you” to those who have supported you and give them a reason to choose you again for their needs. Exclusive access is another tactic – for instance, send loyal customers an early catalog of holiday deals or invite them to a closed preview of a new feature if you’re a software provider. Personal check-ins can also go a long way for retention. For B2B or higher-value B2C, have your sales or account team personally reach out to top clients with a year-end greeting and perhaps a special offer for renewal or upgrade. In the e-commerce world, a personalized “we miss you” email with a small discount can re-engage lapsed customers.
Showing that you remember them and want them back is often flattering to the customer. Use that to your advantage: for instance, “It’s been a while – here’s 20% off if you’d like to come back and see what’s new” can reactivate dormant accounts.
Upselling and cross-selling to current customers is typically easier than converting a cold prospect – these people already trust your brand. Analyze customer purchase patterns and see what complementary products or higher tiers of service might benefit them. Then reach out with personalized suggestions (“Since you enjoyed X, you might love our new Y” or “Upgrade now to lock in 2025 pricing for 2026”).
Because they know your value, they’ll be more open to these recommendations, especially if you frame them as helpful tips rather than pure sales pitches. Don’t forget to also keep your best customers engaged with non-sales interactions. Build community and loyalty by providing value: share a “year-in-review” insightful newsletter, host a customer appreciation event or webinar, or engage on social media by highlighting customer stories (tying back to UGC). Loyal customers are often happy to advocate for you – you might even implement a referral program in Q4, rewarding customers who refer a friend with a discount for both. This not only retains the existing customer (they get a perk) but also acquires a new one cost-effectively.
Keep an eye on customer service quality as well during the year-end rush. Nothing drives customers away faster than a poor support experience. Make sure your support team is prepared to handle holiday queries or issues quickly and kindly. A positive resolution turns a potential detractor into a loyal fan. To sum up, nurture the customers you already have. They are your easiest source of incremental revenue.
By rewarding loyalty, offering tailored suggestions, and making your existing customers feel valued, you’ll encourage repeat purchases that bolster your Q4 numbers. Plus, those happy customers can turn into ambassadors for your brand, seeding growth for the new year. Remember the adage: take care of your customers, and they’ll take care of your business.
15. Prepare Next Year’s Marketing Plan
To begin your marketing planning for the next year effectively, it is essential first to assess the current status of your marketing efforts. This approach allows adequate time to strategize and optimize for the upcoming year. Start by evaluating your existing marketing strategies and reviewing your performance metrics from this year to pinpoint what was successful and what was not. This analysis will help you identify areas for improvement and those where you have excelled.
Next, it’s crucial to set SMART goals for 2026, which should be specific, measurable, achievable, relevant, and time-bound. For example, you might aim to increase website traffic by 30% or expand your email list by 20,000 subscribers. These goals should include quantifiable benchmarks, such as monthly sales targets or weekly lead generation numbers, and should align with your overall business objectives and market conditions.
Social media will likely play a significant role in your marketing efforts for 2026, so establish specific SMART goals for this area as well, like boosting engagement rates or increasing your follower count. Additionally, schedule regular posts and ensure timely responses to enhance customer interaction.
Identify key milestones for the year, such as launching new products or entering new markets. Setting these milestones on a timeline will help you visualize the sequence of objectives throughout the year. Also, translate your objectives into concrete numbers, including projected revenue increases, customer acquisition targets, and expected market share growth, to provide clear targets and measure the success of your strategies.
Develop a detailed action plan for each SMART goal, specifying campaigns, budget allocations, and roles and responsibilities within your marketing team. Include necessary resources, such as digital tools or additional staff. Continuously monitor your progress and regularly adjust your strategies in response to market changes, performance data, and new opportunities.
Conclusion
2025’s marketing landscape is fast-paced and ever-evolving, but the core principle remains: focus on strategies that genuinely connect with your audience. By leveraging current trends – from short-form video and AI tools to influencer collaborations and personalization – you can cut through the noise and make a memorable impact. Just as importantly, doubling down on fundamentals like email marketing and customer retention ensures you’re not leaving easy wins on the table.
As the year winds down, be prepared to adapt quickly, measure what’s working, and iterate. Marketing is part art and part science: use the latest data and tech (as we’ve cited throughout) to inform your moves, but also trust your understanding of your customers. A professional, no-nonsense approach that delivers real value to your audience will always age well. Implement these ideas with confidence and creativity, and you’ll be well on your way to finishing 2025 with strong results, setting yourself up for an even more successful 2026.
Managing HR responsibilities, ranging from recruitment to payroll, conflict resolution, and legal compliance, is essential to running any business, regardless of size. Here are the top 12 HR tips for small businesses to help you manage your resources efficiently.
Small businesses employ different methods to handle these HR tasks. In some instances, the business owner might manage these responsibilities themselves; in others, they might be distributed among various employees. No matter how you run your HR department, your small business must manage HR effectively by staying organized and following all the best practices.
This blog will present helpful tips to streamline your HR tasks and help you create an efficient, compliant, and supportive workplace environment. These tips simplify your HR processes, making it easier for you to focus on growing your business while ensuring your team is well-managed and motivated.
What Is HR?
HR, or human resources, involves managing an organization’s employees to help achieve its goals. The HR department handles everything related to the workforce, from recruitment to termination, resignation, or retirement.
Key responsibilities include:
Attracting, hiring, and retaining talent
Managing payroll and ensuring adherence to tax regulations
Administering compensation packages and employee benefits
Promoting employee engagement, satisfaction, and well-being
Overseeing onboarding and exit procedures for employees
Implementing employee recognition programs
Conducting performance evaluations
Developing and maintaining a positive company culture
Preparing and revising training materials and employee guidelines
Coordinating employee training and skill development programs
Ensuring adherence to labor laws and regulations
Facilitating communication and participation among employees
Monitoring employee attendance and time tracking
For small businesses, HR tasks begin when they hire their first employee. It may be feasible to handle these duties alongside other management and ownership tasks. However, as the business expands, the complexity and volume of HR responsibilities typically necessitate dedicated support.
The Importance of HR Management for Small Businesses
Every business, regardless of size, can benefit from employing a dedicated HR team. A well-functioning HR department is crucial for fostering a positive relationship between your company and its employees. HR professionals ensure compliance with labor laws that promote satisfactory working conditions. Additionally, they facilitate communication between you and your employees, acting as mediators to exchange ideas and address concerns.
Incorporating at least one HR expert into your business can significantly free up your time. Once managed by HR, tasks such as recruiting, hiring, onboarding, and handling paperwork can allow you to focus on growing your business. Experienced HR professionals efficiently manage benefits programs, training, and compensation and guide managers on employee relations.
HR staff also serve as intermediaries between management and staff on various matters, including company practices, policies, and regulations. They ensure that all company policies and programs are implemented in a manner that is consistent with organizational goals and compliant with local, state, and federal laws.
Top 12 HR Practices for Small Businesses in 2026
HR best practices are essential for managing employee relations, promoting a positive workplace culture, enhancing efficiency, and staying compliant with changing regulations.
Regardless of your business size or HR management structure, it’s essential to allocate time to discuss these practices and determine how to implement them effectively.
1. Align HR Strategy With Business Goals
Align your HR strategy with your overall business strategy to ensure they contribute effectively toward common goals. These strategies must be in sync to avoid disruptions in achieving business objectives across different areas.
Your HR strategy should clearly outline your organization’s values, culture, policies, and people management processes. It should also include your Employee Value Proposition (EVP), which represents the unique combination of benefits, rewards, and growth opportunities you provide to employees in exchange for their contributions. This proposition should emphasize what distinguishes you from other employers in your industry.
Work with key stakeholders to evaluate both current and future staffing needs. Your EVP should emphasize your competitive strengths to help you attract and retain top talent.
2. Hire the Right Talent
Hiring effectively is crucial for business success. It involves more than just filling vacancies; it’s about identifying candidates who are truly suitable for their roles. Businesses aim to hire outstanding individuals who deliver significant value to the company. A structured and fair hiring process is vital to comply with legal standards and achieve diversity goals. A workforce that mirrors societal diversity improves the company’s understanding of consumer behavior and helps serve a diverse customer base more effectively.
Selecting the right candidates is key to gaining a competitive advantage. Highly skilled individuals in complex roles can be up to 800% more productive than average performers and top performers can be 400% more productive.
Many recruitment tools are designed to help pinpoint the best candidates. Companies often track recruitment metrics to assess the effectiveness of their hiring strategies.
Standard hiring methods include structured and unstructured interviews, cognitive tests, personality assessments, work simulations, peer reviews, and reference checks. These methods evaluate candidates based on the following:
Ability: Does the candidate possess the necessary skills for the job? Are they able to perform effectively?
Trainability: Can the candidate improve their skills through training? Do they have the potential for ongoing development?
Commitment: Is the candidate likely to be dedicated to their role and the company? Will they stay and continue to contribute productively?
3. Optimize Your Onboarding Process
A strong onboarding process is essential to ensure the new employees you hire can quickly adapt to their new environment during the crucial early days. Many small businesses often overlook this. Inadequate initial training and resources can lead to poor long-term performance and lower retention rates. New employees who feel neglected or confused initially are more likely to underperform or leave prematurely.
To begin with, it’s important to set clear expectations so that new hires thoroughly understand their roles. Ensure job postings clearly outline the responsibilities and desired qualities of the “ideal candidate.” When reviewing resumes, assess technical and soft skills, such as self-motivation and leadership potential. Develop interview questions aligned with the skills and personality traits essential to your business.
For example, if teamwork is vital, consider asking how they would handle conflicts with coworkers or contribute to team support. Keep candidates informed throughout the hiring process. Clearly outline the responsibilities of new hires, so they know what is expected of them. Provide practical training and relevant learning materials specific to their roles to help them perform effectively. Make it a point to check in frequently, especially during the initial weeks, and encourage them to ask any questions.
Once hired, provide a comprehensive onboarding experience to help them grasp their role and smoothly assimilate into the company culture. Small welcoming gestures like team introductions, a casual lunch, or a tour of the premises can make a significant difference. Investing effort in these initial stages can prevent future frustrations and enhance productivity, confidence, and employee loyalty. Effective onboarding not only sets the tone for new hires but also contributes to the overall success of your business.
4. Giving Effective Feedback
When offering feedback, ensure it is timely and precise to make it useful and actionable. A structured approach like the Situation-Behavior-Impact (SBI) model can help deliver clear feedback. Here is how to apply this method:
Situation: Specify the context in which the behavior occurred.
Behavior: Detail the actual, observable behavior without making assumptions.
Impact: Describe how the behavior influenced the team or project.
For instance, instead of saying, “Great job on the presentation,” you might say, “During yesterday’s client meeting, when you presented the updated project timelines, it clarified our team’s direction and reassured the client about our progress.”
This method helps the employee understand which actions were effective and how they contributed to the team’s goals. Offering feedback consistently during formal reviews is beneficial, as this promotes a culture of continuous improvement and open communication.
Additionally, when pointing out areas that need improvement, focus on specific behaviors instead of personal traits and recommend explicit actions for improvement. For example, if an employee needs to improve their time management, offer specific instances where their delays affected team deliverables and discuss possible strategies for better time management.
5. Invest in Training
As we mentioned above, investing in employee training brings a range of advantages to both the individuals involved and the company as a whole. Quality training boosts employee satisfaction and independence, equipping them with the skills needed to excel in their roles with increased confidence and capability. This results in a more driven workforce and improves overall job satisfaction and opportunities for career progression.
A strong training program can also give your company a competitive edge by ensuring your team is up-to-date with the latest industry trends and technologies. Moreover, it fosters a safer and more supportive workplace, which is crucial for sustaining high productivity and reducing employee turnover.
Various affordable training options are available for small businesses or those operating on tight budgets. These options include e-learning, on-the-job training, mentorship programs, and microlearning sessions, which deliver targeted training in short, digestible segments. These cost-effective and flexible training methods allow employees to learn at their convenience.
When crafting an effective training strategy, consider these steps:
Provide a variety of learning modalities to suit different preferences and needs.
Incorporate training in soft skills to improve communication, leadership, and customer service.
Ensure the training aligns with the company’s strategic objectives, particularly in preparation for quick growth, to prepare employees for future roles.
6. Keep Up With Employment Laws
Labor laws are always changing, affecting different aspects of employment, such as working hours, leave, benefits, and workplace safety. For instance, small businesses in the US must be aware of their responsibilities under various federal statutes such as:
Title VII of the Civil Rights Act of 1964
The Occupational Safety and Health Act of 1970
Titles I and V of the Americans with Disabilities Act of 1990
The Age Discrimination in Employment Act of 1967
The Fair Labor Standards Act
The Family and Medical Leave Act
The National Labor Relations Act
Ensure your company follows your area’s rules to prevent legal problems. Your HR department must clearly outline company policies about work schedules, attendance, leave, payroll, benefits, safety, and guidelines on harassment and discrimination.
You should also have procedures for when employees resign or are terminated. It’s a good idea to write down these policies in a company handbook, which should also explain your company’s vision, mission, and objectives. Additionally, you should set expectations for employee behavior during work hours. Give this handbook to all employees and make it part of the orientation for new hires.
7. Develop an Effective Payroll System
It is crucial to manage payroll efficiently to keep your team satisfied, minimize errors, and save time. However, many small businesses need help with this task. Setting up a robust payroll system requires time and expertise; without knowledge in this area, it can be challenging to establish an effective process.
Suppose you ignore to streamline your payroll process. In that case, it can result in excessive time spent on manual calculations during every pay period and increase the risk of costly mistakes with tax payments or filings.
Select dependable payroll software or a knowledgeable provider to reduce error risks to overcome these challenges and manage your payroll effectively. Implement direct deposit to provide convenience for your employees and add a layer of protection against errors and fraud.
Automate repetitive tasks within your payroll operations. Consider linking your timekeeping system with your payroll software or setting up automatic tax payments every quarter. Finally, make it a routine to meticulously check your calculations for deductions, earnings, and taxes each pay period to ensure accuracy and address any discrepancies promptly.
8. Understand Regulatory Compliance
Apart from employment laws, ensuring adherence to regulatory standards such as those set by the Occupational Safety and Health Administration (OSHA) and the Equal Employment Opportunity Commission (EEOC) is essential for maintaining a safe and healthy work environment. Compliance is key for avoiding fines and supporting a workplace free from safety hazards and discrimination.
OSHA regulations aim to reduce workplace risks, including injuries and illnesses. Following these rules can lead to lower healthcare expenses, fewer disruptions at work, enhanced employee morale, and a stronger business reputation. Compliance also greatly reduces the risk of legal issues related to workplace accidents or safety infractions.
The EEOC oversees the enforcement of federal laws against workplace discrimination. Familiarizing with and implementing EEOC guidelines is crucial for establishing a fair hiring process and work environment, which helps avoid legal problems and promotes a positive organizational culture.
If you are uncertain about the specific regulations that apply to your business, consider consulting state and local authorities for guidance.
9. Handling Tough Discussions
Tough discussions are a part of management, and a solid HR strategy can help facilitate these effectively.
Begin by inviting the employee in a non-intimidating manner. (Tip: Avoid saying, “Meet me in HR at 8:00 a.m. tomorrow.”) Then, plan ahead by clearly outlining what you need to discuss. It’s important to remain calm and communicate clearly and empathetically. Focus on the employee’s perspective, not just your own. This method helps make the conversation constructive and respectful, allowing the employee to grasp the concerns and how to progress positively.
10. Utilize HR Software for Streamlined HR Management
Adopting HR software is a wise decision to boost the efficiency and organization of your HR operations. HR software consolidates critical HR functions—like documentation management, attendance tracking, and performance monitoring—into a single secure platform. This consolidation simplifies workflows and enhances productivity within the HR department.
Key Benefits of HR Software:
Increased Efficiency: HR software automates many routine tasks, such as onboarding, payroll management, and performance evaluations, which traditionally take up significant HR time and effort. Automation helps eliminate repetitive manual tasks, freeing up time for more strategic initiatives.
Improved Compliance and Risk Management: HR software supports better compliance with labor laws and regulations by keeping detailed records and automating compliance-related tasks. This helps maintain standards and avoid legal issues.
Cost Savings: Although it requires an upfront investment, HR software can lead to substantial long-term savings. It reduces reliance on manual processes, decreases staffing costs, and minimizes errors that can be expensive to correct.
Data-Driven Insights: With built-in analytics, HR software provides valuable data on key HR metrics, enabling informed decisions about workforce management, identifying areas for cost reduction, and enhancing employee engagement.
Enhanced Employee Experience: HR software offers self-service portals where employees can manage their personal information, request leaves, access payslips, and more independently, enhancing their satisfaction by giving them control over their HR-related needs.
Scalability: HR software can scale to accommodate more employees and increasingly complex workflows without significantly modifying the existing setup as your company expands.
11. Introduce Flexible Work Arrangements
Flexible work arrangements help employees balance their work and personal lives, leading to greater job satisfaction and improved productivity.
You can choose from several models, such as remote work, flextime, or compressed workweeks, depending on what best fits your employees’ needs and your company’s goals.
If you’re planning to offer flexible work options this year, you might consider:
They allow employees to adjust their working hours to manage family obligations and personal needs better.
To keep productivity high, it focuses on results rather than strict office hours. It’s important to set clear and achievable performance targets to avoid overworking.
We are implementing technology that supports remote work and team collaboration effectively.
12. Focus on Mental Health
In the wake of the pandemic, mental health has become a primary concern in HR practices. Acknowledging and supporting your employees’ mental health and well-being is essential to maintain an open and supportive work environment.
Establishing a healthy workplace positively influences productivity and employee satisfaction. A significant number of employees prioritize this: According to research from the American Psychological Association, 81% of workers are likely to seek employers that support mental health in their future job searches.
What steps can you take to nurture a healthy and supportive work environment?
Promote open discussions about mental health at work. Create an atmosphere where employees feel comfortable and supported when discussing their mental health. This will help eliminate mental health stigma and encourage employees to share their experiences and challenges.
Develop mental health awareness initiatives. Start programs that increase understanding of mental health issues and provide support resources. Consider organizing workshops, webinars, or seminars with mental health professionals who can address stress management, work-life balance, and resilience.
Introduce employee Assistance Programs (EAPs). EAPs can provide critical support for employees dealing with personal or professional issues. These programs usually offer confidential counseling, mental health evaluations, and links to additional resources.
Conclusion
In 2026, small businesses will face various HR responsibilities essential for smooth operations and growth. By implementing the top HR tips outlined, businesses can effectively manage their workforce, ensure compliance with regulations, foster a positive company culture, and improve overall employee satisfaction.
Key strategies include aligning HR with business goals, optimizing the hiring and onboarding processes, and maintaining a strong focus on employee well-being, including mental health support. HR software can streamline operations, and flexible work arrangements can enhance productivity. With these practices, small businesses can build a motivated, well-managed team, allowing owners to focus more on business growth and less on administrative tasks.
Frequently Asked Questions
How can small businesses manage HR tasks effectively without a dedicated HR department?
Small businesses can use cloud-based HR software like Paycom, Rippling, and BambooHR to automate payroll and time-tracking tasks. Outsourcing functions such as recruitment can also be a cost-effective option.
What are the key HR compliance issues that small businesses must be aware of in 2026?
Small businesses must stay updated on labor laws, including those on workplace safety, discrimination, and wage standards. HR compliance software can help businesses stay current and avoid penalties.
What cost-effective training options are available for small businesses to develop their employees?
Small businesses can use online courses and e-learning platforms like LinkedIn Learning or Coursera for affordable employee training. These options help boost skills while aligning with company goals.
How can small businesses foster employee engagement and retention in 2026?
Businesses can offer flexible work arrangements to boost engagement and use tools like Bonusly for employee recognition. Regular feedback and appreciation are key to retaining employees.
Efficiently marketing products is a crucial step towards scaling a business. The journey may be challenging, but with the right growth hacking strategies, scalability becomes not just a possibility, but a potential for significant success.
Implementing various growth hacking techniques is within reach for companies aiming to reach a wide audience. While some of these techniques have only emerged in recent years, they have proven essential for the expansion of modern businesses. Many entrepreneurs have integrated them into their growth strategies after seeing beneficial outcomes and now is an ideal time for you to consider doing the same.
Entrepreneurs constantly search for effective growth hacks to increase their customer base and rapidly boost revenue. Growth hacking has established itself as an effective and reliable method for the rapid success of emerging startups. However, only a few businesses manage to implement these hacks perfectly. This blog provides insights into the top growth hacking strategies that have been successful across different industries.
Understanding Growth Hacking and Top Strategies for Startups
Growth hacking, or growth marketing, involves employing cost-effective and efficient digital marketing strategies to expand and maintain an active user base, increase product sales, and enhance visibility. The term “hacking” here refers to clever shortcuts—similar to life hacks that simplify daily tasks. While growth hacking is often associated with startups and small businesses, older firms or companies with limited budgets use it for rapid results. Any business aiming to sustain growth and user retention can adopt growth-hacking strategies. Here are the top strategies you can follow for success in 2026:
1. Freemiums and Free Trials
A proven growth hacking technique is the provision of freemiums or free trials for your product or service. By offering potential users a preview of what’s available, you can encourage them to commit to a paid plan or purchase additional features. This approach helps acquire new customers and demonstrates the value and advantages of your offerings.
When implementing freemiums or free trials, it’s crucial to find the right balance between offering sufficient value to engage users and motivating them to make a purchase. Introducing limited functionality or time-bound trials can lead to a sense of urgency and boost conversions. Moreover, utilizing user data and feedback during the trial phase can yield critical insights that help enhance your products and services.
2. Driving Growth with High-Quality Content
High-quality, informative content is fundamental to growth hacking for startups. Whether blog posts, engaging infographics, captivating videos, or interactive quizzes, content can educate, engage, and convert visitors into loyal customers.
In 2026, the COPE or “Create Once and Publish Everywhere” strategy is essential. Repurposing standout content across various platforms can enhance reach and SEO benefits. Moreover, cultivating an engaged community around your content is vital. Encourage discussions in forums, on Reddit, and within social media groups related to your field, establishing yourself as a strong leader.
Another effective strategy for content-driven growth is guest blogging on established blogs within your industry. This provides valuable backlinks and exposes you to a new audience, leveraging your expertise for expanded influence.
3. Utilize Platform Integration
Instead of building a user base from scratch, tap into an existing audience on a popular platform with millions of active users.
This approach, known as platform integration, was effectively utilized by Airbnb when they leveraged Craigslist to expand their user base significantly. Although Airbnb offered a more sophisticated platform, it initially lacked Craigslist’s vast user base. To bridge this gap, Airbnb listed its rentals on Craigslist, which exposed its offerings to a larger audience searching for vacation rentals.
Additionally, Airbnb complemented this strategy with an email campaign targeting Craigslist users, highlighting the ease and convenience of posting directly on Airbnb.
To apply this growth hack to your startup, identify platforms that already cater to a large target audience segment. Consider promoting your product through partnerships with these platforms. These partnerships can be financial, paying for placement, or through an affiliate arrangement where you pay a commission for sales generated through their platform.
4. Build a Pre-Launch Email List
Email marketing remains a top strategy for generating leads and conversions in the startup world. Focus on creating an email list to communicate effectively with your audience and build anticipation for your product or event. This approach not only allows you to deliver your message directly but also helps you acquire potential customers before you even launch.
Gather email addresses and remain active. Spend a few weeks before your launch generating excitement and making your audience look forward to what’s coming. Consider using email services like MailChimp, Zoho, or Outlook to manage your email list. These platforms enhance your ability to send out messages efficiently. Since timely communication is crucial for conversions, aim to reach your potential customers at least a week before launch.
5. Leveraging Partnerships for Growth
Many businesses fail to consider utilizing the power of partnerships as a growth hacking strategy. This strategy involves teaming up with non-competitive businesses that cater to your target audience beyond just product integration. By engaging in cross-promotions, hosting joint webinars, and producing collaborative content, you can effectively introduce your brand to a wider audience.
Another powerful aspect of partnerships is influencer marketing. Working with micro-influencers who resonate with your target demographic enhances your brand’s authenticity and credibility. Their genuine endorsements can be highly influential, boosting brand recognition and attracting new users.
Additionally, affiliate marketing serves as a strategic expansion of partnerships. You create a mutually beneficial relationship by incentivizing your existing customers to promote your brand and rewarding them with a commission for each sale they facilitate.
6. Use “Guerrilla Marketing” Strategy
Guerrilla marketing is a growth hacking technique that utilizes unconventional and cost-effective strategies to increase interest and enhance brand recognition. By embracing creativity and thinking innovatively, businesses can grab the attention of their target audience in surprising ways. Guerrilla marketing efforts often become viral, boosting brand exposure and attracting new customers (such as with Stanley Tumblers).
Examples of guerrilla marketing tactics include flash mobs, street art, or dramatic publicity stunts. These approaches aim to create an unforgettable and shareable experience, sparking discussions and driving social media engagement. Ensuring that the message and methods resonate with your brand’s identity and values is crucial to maintaining authenticity when orchestrating a guerrilla marketing campaign.
7. Incorporate Virality into Your Product
Integrating virality into your product’s core functionality can lead to a rapid increase in your user base. Consider the example of WhatsApp. The platform naturally encouraged new users to invite their friends and family to join them, offering free calls and messages as a compelling incentive. As more people joined and experienced the benefits, they, too, felt motivated to invite others, creating a self-sustaining cycle of growth and increasing engagement.
This concept of built-in virality, which contributed significantly to WhatsApp’s widespread popularity, is common among platform-based products. Other notable examples include Facebook, LinkedIn, and Craigslist, where network effects are leveraged to enhance user engagement and expand reach.
To successfully apply this growth hack in your startup, you should offer a unique value proposition—similar to WhatsApp’s free internet calls—that is accessible exclusively on your platform and becomes more beneficial as more users join. This encourages existing users to bring in new ones, effectively using your product’s functionality to drive its own expansion.
8. Maximizing Growth with Referral Programs
Referral programs are an effective growth hacking tactic that capitalizes on word-of-mouth marketing. By offering rewards to existing customers for referring their friends and connections, you can generate new leads and acquire customers more cost-effectively. These programs create a win-win scenario, providing benefits to your loyal customers while driving your business’s growth.
To ensure your referral program is successful, it’s crucial to offer attractive incentives that encourage participation, such as discounts, exclusive access, or monetary rewards. Additionally, simplifying the referral process makes it easier for users to participate, which can lead to higher engagement and more effective results. Monitoring and analyzing referral data allows you to continuously improve your program and gain valuable insights into your customer base.
9. Cultivate FOMO with Exclusivity
Utilizing exclusivity, such as offering early access passes, members-only sales, and VIP experiences, can effectively create a sense of FOMO (Fear of Missing Out). This strategy can make individuals feel special and encourage them to share their exclusive experiences with others. Consider providing early previews, additional features, or special discounts to select groups before a broader release, and actively promote these exclusives on social media to generate excitement.
For instance, Tesla initially released its roadsters exclusively to influencers, creating significant buzz as these vehicles started appearing on public roads. This approach has led to such high demand that people now camp out overnight to be among the first to purchase new models.
10. Stay Patient and Persistent
Growth hacking is more of a marathon than a sprint. Although some tactics may produce quick wins, achieving sustainable growth takes time, patience, and persistence. Keep your eyes on your long-term objectives, monitor your progress, and be ready to adjust your strategies as necessary.
Consistency is essential for long-term success. A startup’s journey is fraught with challenges and fluctuations, making resilience vital. Celebrate your small victories, learn from any setbacks, and continuously refine your growth hacking tactics to build and maintain momentum.
Conclusion
In 2026, the world of growth hacking for startups provides numerous strategies to help businesses achieve success. By adopting innovative techniques such as content-driven growth, platform integration, and referral programs, startups can effectively increase their customer base. Collaborating with partners, using guerrilla marketing, and incorporating virality into products can also amplify growth potential.
Additionally, by creating exclusivity and FOMO and being patient and persistent, startups can ensure sustainable progress. As startups navigate through the dynamic market, integrating these growth hacking strategies can pave the way for significant and long-lasting success.
As real-time payments gain traction across industries, CFOs are weighing the benefits against the potential risks. A significant majority of more than one thousand CFO respondents (68%), have expressed their intention to adopt real-time transaction solutions, also known as instant payments.
The promise of faster transactions, improved cash flow visibility, and streamlined operations is clear, but so are the challenges tied to fraud prevention, integration costs, and internal process changes. In this environment, finance leaders are taking a measured approach—exploring new opportunities while keeping a close eye on security and compliance.
Key Takeaways:
About half of U.S. companies now use instant-payment rails (FedNow or TCH’s RTP), up from 40% in 2023, with roughly 80% expecting to use them by 2026. The FedNow Service (launched July 2023) and the RTP network together now reach most regions – over 1,300 banks and credit unions are live on FedNow, and the RTP network serves 285,000+ businesses monthly.
Both rails have raised transaction limits. FedNow will soon allow $1 million transfers (up from $500K); The Clearing House increased RTP’s cap to $10 million. All real-time systems support ISO 20022, so payments carry rich remittance data (invoices, payer/payee details) for easy reconciliation.
New risk features help manage fraud. FedNow now offers account-velocity controls and “receive-only” modes to limit misuse, and both networks provide 24/7 monitoring. In fact, 42% of RTP transactions occur outside normal banking hours, underscoring round‑the‑clock use.
Today’s CFOs cite cost-cutting and risk management as top goals. Nearly 60% of finance leaders rank reducing payment risk as a priority. Instant payments can boost cash flow by speeding receivables (92% of firms say faster rails improve cash flow) and enable “just-in-time” payables. Many cite lower processing costs (versus wires) and richer data as benefits.
Despite the upside, many CFOs remain careful. Surveys show the cost of upgrading legacy systems is the biggest barrier (over half of businesses see real-time rails as “costly”). Treasury teams still rely on ACH for payroll and wires for large payments, so instant rails are often phased in selectively. A compelling business case is needed to rework established processes.
Other markets continue to make rapid gains. The UK’s Faster Payments (24/7 since 2008) now handles transactions up to £1 million, with volumes 15% higher in 2024. The EU is implementing an “Instant Credit Transfer” rule under PSD3 (effective late 2025) to make euro payments instant.
Rising U.S. Adoption of FedNow and Real-Time Payments
Adoption of real-time rails has accelerated. In late 2024, a major U.S. survey found 51% of firms were already using FedNow or RTP for business payments – a jump from 42% a year earlier. Crucially, 80% of companies plan to be on these instant systems within two years. In practical terms, 285,000+ businesses now send instant payments each month via TCH’s RTP network, which recently surpassed $500 billion in cumulative transaction value.
FedNow, though newer, has also scaled quickly; by April 2025, it counted 1,300+ participating banks and credit unions nationwide (95% of them small/mid-sized). In Q1 2025, FedNow settled about 1.3 million transactions (up 43% year-over-year) – roughly $540 million in value daily. Which simply means, instant payments have gone from niche to mainstream in U.S. corporate finance over just the past two years. This momentum is driven by expanding network reach. When FedNow launched in July 2023, it extended real-time rails to hundreds of banks and credit unions that were not on the RTP network.
The two systems now complement each other, One large U.S. bank reported that clients can send an “instant payment” without worrying which rail will be used – the bank routes it via FedNow or RTP as needed to hit the recipient. In practice, this means more payees (suppliers, payroll providers, etc.) can be reached instantly. As The Clearing House notes, nearly half of RTP activity happens overnight, on weekends or holidays, aligning with how a 24/7 business operates. All told, broader connectivity and availability have pulled more corporate treasury teams into experimenting with these rails.
Since 2023, both FedNow and RTP have rolled out significant enhancements. The Clearing House raised RTP’s single-payment limit from $1 million to $10 million (effective Feb 2025) to accommodate high-value B2B use cases like real estate closings or daily merchant settlements. The Federal Reserve likewise plans to double FedNow’s cap from $500K to $1 million in mid-2024, recognizing that larger supplier payments or urgent payroll top‑ups are needed for big corporations. (Notably, FedNow’s baseline $500K limit was already five times higher than the $100K it launched with in 2023.)
Both rails use the ISO 20022 messaging standard. This means each payment can include detailed invoice and remittance information – far beyond the minimal ACH fields. For example, a real-time corporate payment can carry the supplier’s name plus an itemized invoice breakdown, all instantly visible to the recipient. That data-rich transparency makes reconciliation easier and can reduce exceptions. In short, instant payments now rival wires in amount and exceed them in data, often at a fraction of the cost.
Additionally, instant transactions are irreversible “push” payments, so controlling fraud is critical. FedNow has introduced new built-in safeguards – banks can set velocity limits or account-level thresholds by customer segment (e.g., tiering limits for retail vs. corporate clients), and institutions may choose to be receive-only (able to accept but not send payments) while security is fine-tuned.
The Fed also offers payment inquiry support and optional monitoring; a fintech assessment notes that FedNow was launched with dedicated fraud-prevention tools and inquiry-of-sending features. On the RTP side, participant banks similarly use analytics and screening on their rails. Thus, while no system is impervious, both instant networks are adding controls to address the very bank and treasurer concerns around push-payment fraud. In practice, these upgrades are making real-time payments more versatile.
For example, FedNow now supports low-cost request-for-payment messages (invoices) for free (effective 2025), mirroring TCH’s Request-for-Payment, which streamlines billing and approval. Liquidity management features (instant transfers between Fed accounts) have also been enhanced. Combined with 24/7 availability, these evolving capabilities are closing the feature gap between instant rails and traditional methods, inching them toward ubiquity.
CFO Sentiment and Strategy
Today’s finance chiefs acknowledge the potential of real-time payments but remain deliberate in their approach. A 2024 U.S. Bank survey found that cutting costs and managing risk are top-of-mind priorities for CFOs. In payments specifically, 59% of finance leaders said “decreasing operational risk” is an important initiative, up sharply from past years.
This caution translates into the way treasurers handle new rails. Many firms continue to use the ACH network (batch-based, low-cost) for routine disbursements like payroll or vendor checks, and rely on wires for one-off large payments. Instant payments are often reserved for scenarios that justify the effort, late-stage payables, supply-chain finance, earned-wage access programs, or customer refunds, where speed directly improves business outcomes. Most treasurers agree that instant rails can improve cash management, but they ask if the benefits outweigh the work.
Altering long-established payment processes can be challenging, and a compelling business case is necessary to justify the transition.
For many companies, simply holding onto cash until the last moment using ACH already effectively stretches the float. To change that habit, CFOs need to see a clear ROI, for example, earning early-payment discounts or avoiding short‑term borrowing by using last-minute electronic payments. This balanced stance is echoed on the banking side. A January 2025 report notes 90% of banks agree customers would benefit from instant rails, yet many institutions remain hesitant. Roughly one-third of banks cite legacy core-system limitations and fraud concerns as barriers.
Indeed, a majority of banks and credit unions surveyed called the upfront cost of upgrading the biggest obstacle to offering faster payments. In other words, the ecosystem (both buyers and their banks) is still adapting. For now, many financial institutions have joined FedNow in a “receive only” mode to mitigate risk. CFOs, who must work through these banks, feel that caution, if the company’s bank has not fully embraced sending, can limit immediate use.
However, despite these hesitations, most CFOs recognize that instant payments offer clear financial benefits. The Federal Reserve’s 2024 Business Payments Study found that 92% of firms say faster payments improve cash flow by accelerating receipts and unlocking discounts. Over half of businesses reported instant rails lower transaction costs (versus checks or wires). Real-time confirmation of payment delivery also reduces errors and enables same-day reconciliation, which appeals to the treasury’s efficiency goals.
Many CFOs are therefore building real-time capabilities for key use cases rather than wholesale replacement – for example, sending large vendor payments or making ad-hoc “just-in-time” payables that previously could not clear. In parallel, they continue using instant rails for incoming payments (customers paying by same-day transfer, payroll feeds, or merchant payouts) to gain confidence in the system.
Benefits vs. Challenges for Businesses
Benefits
The chief appeal of instant payments for a company is liquidity management. When a payment clears in seconds, the recipient’s accounts receivable drops immediately, and the payer’s cash outflow is finalized (good funds), allowing finance to optimize cash on hand. Businesses can push out disbursements to the very end of the day, and likewise receive payments without delay, greatly improving working capital.
For example, some employers now use FedNow for off-cycle payroll runs, letting employees tap earned wages instantly while delaying the company’s funding by hours or days. Suppliers receive money faster and with detailed invoice data, which has been shown to improve relations and potentially negotiate better terms. Real-time rails also enhance transparency and accuracy. Unlike ACH entries or checks (where often little more than an ID or invoice number travels with the money), instant transfers can include the supplier’s name and a full breakdown of charges up front.
This two-way messaging (especially under ISO 20022) makes matching payments to invoices almost automatic. In practice, CFOs find that fewer staff hours are wasted chasing missing remittance info. Several studies highlight data as a top advantage, like in a FedPayments Council survey, 56% of businesses using instant payments said they experience lower payment-processing costs and fewer errors.
Finally, there is cost efficiency relative to wires. Typical domestic wire fees (often $15–$30 each) can be dozens of times higher than same-day credit transfer fees, which generally top out at a dollar or two per transaction. For midsize transactions, that difference adds up. As a result, treasurers view real-time credits somewhat like a hybrid of ACH and wires, immediate like a wire, but priced closer to an ACH or commercial card. Over time, large treasuries may even reroute some B2B payments (e.g. supplier draws, claims, rebates) from wires into instant rails to save fees while still meeting their payees’ timelines.
Challenges
These benefits come with caveats. The biggest practical hurdle is integration cost and complexity. Many companies’ ERP and treasury systems were built for batch processing and ACH/file-based uploads. Connecting them to FedNow or RTP’s APIs, or to a bank portal, requires IT investment. As one treasury survey put it, over half of businesses not using instant rails cite “cost and complexity” as the key barrier.
Similarly, smaller firms without a sophisticated treasury function may simply defer adoption until services are turnkey. Also, real-time rails are irreversible, so fraud protection is crucial. CFOs worry about authorized push-payment scams (where an employee is tricked into sending money) or about insufficient time to detect errors. Instant payments networks mitigate this by requiring payers to pre-validate recipients and by including fraud screening at the network level.
For instance, FedNow includes optional filters and the ability to quickly reverse unauthorized transactions under tight timeframes. Banks are also bolstering customer education around confirming payment requests. Nonetheless, many companies ramp up usage gradually while internal controls catch up, or use dedicated fraud-monitoring services as a supplement.
Another issue is that not every counterparty is reachable instantly yet. As of early 2025, roughly 1,300 institutions (out of 9,000 U.S. banks and credit unions) had joined FedNow, and about 400 institutions support RTP. This means a mid-market business may have some suppliers on instant rails, but others are still reliant on ACH. CFOs must therefore maintain dual processes during transition.
Over time, as more banks join and paytechs integrate (many payroll providers, bill-pay vendors, and AR platforms are enabling FedNow/RTP), this “network effect” will ease. But in the near term, CFOs often use instant payments primarily for suppliers and channels that explicitly accept them, while continuing legacy channels elsewhere.
Regulatory and Competitive Side
In the payments industry, competition and regulation are spurring improvements. In the U.S., regulators encourage instant-pay adoption. The Federal Reserve has waived FedNow participation fees for small banks through 2025 and has consulted on beneficial-rule enhancements. The Fed also carefully set FedNow’s initial pricing (e.g., just $0.045 per transfer in 2023) to build volume. On the wire-transfer side, the Federal Reserve’s wire system (Fedwire) and ACH continue alongside, but corporate governance increasingly demands that firms evaluate faster options.
Additionally, fintech providers and payment networks offer alternatives that target similar goals – payment-card networks (Visa Direct, Mastercard Send) and fintech services (Zelle, and business-centric push-to-card) allow faster payouts to vendors and consumers without needing bank details.
Many CFOs consider these alongside FedNow/RTP as part of a suite of “just-in-time” payment tools, especially for disbursements to individuals or international partners. On the legislative front, U.S. authorities are focused on fraud prevention (e.g., encouraging protections for push-pay scams) but have not mandated instant rails for businesses. In contrast, Europe’s regulators are moving more aggressively. A new “Instant Credit Transfer” requirement under PSD3 will mandate euro deposits be available within seconds across the EU (targeting Oct 2025).
Chinese and Indian real-time systems have already demonstrated that ubiquitous instant payments can become a de facto infrastructure. This global momentum puts pressure on the U.S. market to evolve, but U.S. innovation (with dual rails and open banking tools) offers flexibility. For CFOs, this means staying alert to changes. For example, interoperable cross-border schemes (like SWIFT’s GPI for instant transfers) and token-based payment rails may eventually link with domestic real-time networks, expanding reach.
Real-time payments are now common worldwide, and the U.S. trail is closing. The UK’s Faster Payments Service, long a success story, saw transaction volumes jump about 15% in 2024. Faster Payments now allows up to £1,000,000 per transfer, enabling large B2B and real-estate transactions instantly. In continental Europe, the Eurosystem’s TIPS platform (TARGET Instant Payment Settlement) already handles instant euro credit transfers 24/7, and most SEPA member banks support it. The upcoming EU Directive will push all euro-area banks to make instant credit transfers available as a default by late 2025.
In Asia, markets are even further along. For example, India’s UPI system processed 93.2 billion transactions in just H2 2024, demonstrating consumer and merchant comfort with instant pay. China and other countries also have prolific mobile-driven payment rails. While U.S. businesses deal mostly in domestic USD transfers, these global examples show the full potential; once nearly every party is “on network,” instant payments become the norm for nearly all disbursements and receipts. For American CFOs with overseas operations, these developments also signal that cross-border payment delays may become more unusual. Banks and fintechs are working on instant rails for global B2B settlements, and some service providers now link FedNow/RTP flows to foreign instant networks (for example, a U.S. supplier paid in USD could have the funds immediately released to a UK partner via Faster Payments). This “real-time globalization” is still emerging, but it underscores how interconnected payment infrastructures are.
Final Thoughts: The Road Ahead
By 2025, real-time payments will have shifted from a future concept to a core tool for corporate finance teams. Adoption is now essential for timely supply-chain and treasury operations. Still, CFOs and treasurers weigh the benefits of speed and visibility against implementation costs and the need for strong controls.
The next step is deeper integration with financial systems. ERPs and Treasury Management Systems are adding direct connections to FedNow and RTP APIs, making it easier to support new use cases. Banks are also upgrading, moving beyond ACH to offer real-time push payments as client demand grows.
Many companies are starting with targeted use cases, such as automating end-of-month supplier payments or offering instant refunds. ACH and wires will still be used where they make sense, but finance teams are learning to assess real-time payments like any other method.
Real-time payments in the U.S. are at a turning point. CFOs who stay proactive can gain a competitive edge, while waiting too long may mean missed opportunities.
Unlike many new corporate leaders, PayPal New CEO, Alex Chriss, has not hesitated to make significant directional changes early in his tenure. In the Q3 earnings call. Chriss, who took over as CEO after Dan Schulman on September 27th, emphasized his focus on achieving growth.
This marks a departure from Schulman’s emphasis on PayPal’s checkout service. Initially, this shift caused a decrease in investor confidence and a decline in the company’s stock value.
Key Takeaways:
New CEO’s Strategic Shift: Alex Chriss highlighted the importance of focusing on growth and moving away from the checkout service that Dan Schulman previously had priority on. Chriss’s leadership signifies a change in strategy aiming for an effective and growing organization.
Resilient Q3 Performance: Despite facing difficulties in the market and experiencing heightened competition, PayPal displayed a strong performance in Q3 of 2023. Some notable achievements during this period include a 15% rise in payment volume, an 8% increase in revenues, and a 20% growth in EPS. Moreover, the company exhibited good operating cash flow and free cash flow throughout this timeframe.
Strategic Overhaul: As part of its revamp, PayPal made notable changes to its operations, like divesting its logistics branch, Happy Returns to UPS. The company’s goal is to make operations more efficient and provide experiences for customers by implementing automation and enhancing the checkout process. Moreover, PayPal plans to utilize AI technology to engage consumers and improve its range of business solutions.
Financial Overview and Company Profile: PayPal provides an overview of its situation, including information about its cash holdings, investments, and debts. Additionally, the company demonstrates its dedication to rewarding shareholders through stock repurchases. Moreover, PayPal’s mission revolves around stimulating empowerment and focusing more on economic participation through its inclusive digital payment platform that serves millions of active account holders worldwide.
PayPal Stock Price On 12-18-2023 (11:00 am) ( Source Google Finance)
PayPal New CEO, Alex Chriss: Background
PayPal’s New CEO, Alex Chriss assumed the position of CEO on September 27, replacing Dan Schulman when PayPal was head-on with various challenges in the fintech industry. The company has faced a decrease in its stock value due to decreasing investor interest in fintech companies, tough competition from Apple, and slower growth in its branded checkout business over the past few years.
Given Chriss’s extensive experience at Intuit, he is expected to lead PayPal’s recovery. However, analysts on Wall Street caution that reviving the company might take a long time and extensive efforts.
The year 2023 proved difficult for PayPal, as its stock mostly traded at low levels compared to the long-term average. While this made the stock more affordable, potential investors were still worried about uncertainties in the economy and reduced consumer spending. However, there was a positive market response to the plans of PayPal’s new CEO, Alex Chriss. He aimed to streamline the company’s resources towards its growth priorities to create a leaner, more efficient, and effective organization. Overall, market observers hold a confident view of the stock’s long-term prospects.
Regarding growth, one of the primary hurdles facing the company is intense competition. The market dynamics have significantly changed since PayPal’s separation from eBay approximately eight years ago, with consumers now having alternative options, such as Apple Pay, that provide a fast and convenient checkout experience. The payment systems of Amazon and Google continue to gain traction, posing challenges for PayPal, which heavily relies on e-commerce for revenue generation. It is essential to note that the termination of PayPal’s operating agreement with eBay a few years ago has impeded its growth.
PayPal’s Third Quarter 2023 Earnings Reflect Resilience Amidst Market Challenges
Following a more-than-expected third-quarter report, PayPal experienced a much-needed upturn in its stock value, which had been struggling since its peak in 2021. Despite its position as a leading figure in the payments sector, PayPal has faced challenges in sustaining its growth momentum during the pandemic surge, leading to ongoing struggles in its stock performance.
Speaking about it, Alex Chriss, acknowledged the obstacles ahead, highlighting the competitive pressures from firms like Block (formerly Square) and Stripe, as well as traditional financial service providers such as Fiserv and FIS. To address these challenges and improve financial performance, PayPal aims to streamline certain aspects of its operations. Chriss emphasized the need to address the company’s high-cost structure, which has been impeding its agility and clarity of focus.
On November 1, 2023, PayPal disclosed its third quarter of 2023 earnings, showcasing a robust performance with notable growth in both revenue and EPS. The company’s Overall payment volume reached $387.7 billion, marking a 15% increase and a 13% growth on an FX-neutral basis. Notably, net revenues stood at $7.4 billion, demonstrating an 8% growth and a 9% FX-neutral increase. The GAAP operating income saw a 4% rise, amounting to $1.2 billion, while the operating income (excluding GAAP) showed an 8% increase, reaching $1.6 billion.
GAAP EPS was reported at $0.93, compared to $1.15 in the third quarter of 2022, whereas the EPS for non-GAAP showed an impressive 20% growth, totaling $1.30 compared to $1.08 in the prior year. Additionally, the company recorded a significant operating cash flow of $1.3 billion and a free cash flow of $1.1 billion.
PayPal’s Strategic Overhaul – Enhancing Consumer Experience and Streamlining Operations
PayPal recently divested its logistics arm, Happy Returns, to UPS, as part of its strategy to streamline operations and focus on its core payments model. CEO Chriss emphasized the need to address duplication and manual work, intending to invest in automation for improved efficiency.
During his initial month in the role, Chriss engaged with various stakeholders to outline a plan that aims to revolutionize product development and reporting practices. This plan, to be unveiled in the upcoming earnings call, involves a comprehensive overhaul of the consumer experience, centering on a seamless checkout process that adds value to each transaction.
For consumers, PayPal intends to leverage its rich database to power a sophisticated shopping recommendation engine and enhance incentive marketing using AI technology. In the business segment, the company plans to accelerate the advancement of PayPal Complete Payments, an offering tailored for digital merchants. Utilizing consumer data for refining checkout form autofill is also a focus.
PayPal’s New CEO also highlighted the potential of generative AI in fostering meaningful connections between consumers and merchants, ensuring responsible use of this technology. The company anticipates recruiting seasoned professionals to reinforce its talent pool in the upcoming months, recognizing the need for enhanced execution speed in driving growth and delivering on its promising outlook.
Jamie Miller has been appointed as the new CFO of PayPal to aid the company under its new expense management approach led by the new leader, Alex Chriss. Previously serving as the global CFO at EY, Miller brings a wealth of experience from her previous roles at General Electric and Cargill. She takes over from Gabrielle Rabinovitch, who has been serving as acting CFO during the transition period. In Q3, PayPal’s net income saw a 23% decline, settling down to around $1.02 billion YOY, with the company’s Q4 performance falling slightly below expectations till now, as noted by Rabinovitch.
Expanding Service Offerings to Braintree Customers
In a bid to cater to larger companies associated with Braintree, Chriss intends to broaden the range of services offered. Describing Braintree’s position as a foothold for future growth, Chriss emphasized the company’s commitment to addressing additional customer needs, including fraud management, payouts, chargeback automation, and Forex services.
According to William Blair, the company’s long-term prospects remain substantial, particularly as it has transitioned from a traditional checkout button to a comprehensive E2E solutions platform for both consumers and merchants. While it’s still early, the company’s sharp focus on leveraging its wealth of data for enhanced operational efficiency is encouraging for the future, as management emphasizes its commitment to pursuing profitable growth.
While acknowledging the dedication of PayPal’s current employees, Chriss also expressed the intention to bring in new talent to help achieve his objectives. In the meantime, he is diligently working to gain a comprehensive understanding of the company, with plans to present a more detailed strategy to analysts during the upcoming earnings call in February.
Key Highlights Of Q3 Results 2023
PayPal exhibited a robust performance in the third quarter of 2023, marked by an 8% increase in net revenues, which grew to 9% on an FX-neutral basis. The company saw a 4% rise in GAAP operating earnings, amounting to $1.2 billion, and an 8% increase in operating income (non-GAAP), reaching $1.6 billion. The GAAP EPS was $0.93, down from $1.15 in the third quarter of the prior year, while the EPS for non-GAAP stood at $1.30, demonstrating a 20% growth YOY.
As of September 30, 2023, PayPal’s cash equivalents and investments amounted to $15.4 billion, with a total debt of $10.6 billion. During the third quarter of 2023, the company bought back approximately 23 million common stocks, delivering $1.4 billion in returns to stockholders.
The company generated $1.3 billion in cash flow from operations and $1.1 billion in free cash flow during the quarter. These figures include a $0.8 billion of adverse impact from European BNPL loans originated as HFS in the period.
About PayPal
PayPal offers a secure and efficient way to send money, pay and create online invoices, and establish a merchant account. With a core belief in the transformative power of accessible financial services, PayPal is dedicated to democratizing financial opportunities and empowering individuals and businesses to participate and thrive in the global economy. Their inclusive digital payment platform empowers 277 million active account holders to transact with confidence, whether online, through a mobile device, an app, or in person.
Through a blend of innovative technology and strategic partnerships, PayPal continuously develops improved methods for managing and transferring funds, providing users with flexibility and options for sending, receiving, and paying. Operating in over 200 markets globally, the PayPal ecosystem, encompassing Venmo, Xoom, and Braintree, facilitates transactions in more than 100 currencies, allowing users to withdraw funds in 56 currencies and hold balances in their PayPal accounts in 25 currencies.
Conclusion
PayPal’s New CEO, Alex Chriss, left an indelible mark by charting a clear course for the company’s future. Departing from the previous strategy, Chriss outlined his vision for prioritizing profitable growth, setting the stage for a more efficient and agile organization. Despite market challenges, PayPal’s robust third-quarter performance, including notable increases in overall payment volume and net revenues, showcased the company’s resilience and enduring potential.
Moreover, the strategic overhaul, evidenced by the divestment of Happy Returns and a commitment to streamline operations, underscores Chriss’s dedication to optimizing consumer experiences and refining business offerings through advanced AI technologies. With the appointment of Jamie Miller as CFO, PayPal is poised to fortify its financial management and steer the company’s trajectory toward sustained growth.
As PayPal continues to empower millions of users worldwide through its secure and accessible financial services, Chriss’s leadership, coupled with the company’s continued dedication to innovation and strategic partnerships, bodes well for its continued success and enduring prominence in the global digital payment landscape.
Sezzle, one of the fastest growing payment platforms, has just unveiled a game-changing solution – Sezzle Pay Anywhere – that is set to revolutionize the way consumers shop and pay. But it’s not just about convenience; it’s about leveling the playing field for those who have faced barriers to traditional financing.
With this latest innovation, Sezzle is heralding a new era of responsible financing, offering unparalleled choice and flexibility to consumers seeking a seamless shopping experience.
Company Overview
Sezzle is a dynamic and forward-thinking financial technology company that has rapidly grown to prominence in the bustling world of online payments. Headquartered in Minneapolis, U.S., with a widespread presence in both the United States and Canada, the company has solidified its position as a leading player in the alternative payment sector. At its core, Sezzle offers a groundbreaking platform that empowers consumers with interest-free installment plans, fostering a seamless and responsible shopping experience at a wide array of online stores.
Sezzle revenue in $ million
Driven by a mission to make finance more accessible and inclusive, Sezzle has disrupted the traditional payment landscape by redefining the way consumers shop and pay for their purchases. With a commitment to innovation and customer satisfaction, the company has garnered a loyal customer base while forging strong partnerships with renowned retailers. As a publicly traded entity, Sezzle continues to inspire confidence and trust among its stakeholders as it pioneers the future of modern, flexible, and responsible financing.
What is Sezzle Pay Anywhere?
Sezzle Pay Anywhere is a groundbreaking subscription-based service offered by Sezzle Inc., designed to revolutionize the world of payments. It enables consumers to utilize their Sezzle Virtual Card for interest-free installment payments at any retailer or merchant where Visa Inc. transactions are accepted. This innovative payment solution offers unparalleled flexibility and convenience, catering to modern consumers’ evolving preferences for responsible financing options.
Whether shopping online, making in-store purchases, or paying bills, Sezzle Pay Anywhere empowers users to split their purchase amount into multiple installments, eliminating the need for immediate full payment. With a seamless integration process, transparent fee structure, and the added benefit of rewards and credit-building opportunities, Sezzle Pay Anywhere stands at the forefront of financial inclusion, ensuring consumers have access to a frictionless shopping experience across a vast network of participating merchants and retailers.
Why is Sezzle Pay Making A Move To BNPL?
BNPL is getting quickly popular with Gen Z.
With the booming popularity of the buy now, pay later (BNPL) trend, Sezzle Inc., a prominent payment provider, recognizes the importance of catering to evolving consumer needs and preferences. As forecasts project the U.S. BNPL volume to soar to a staggering $6.5 billion by 2027, Sezzle is strategically positioning itself to empower consumers with more flexibility and accessibility.
To achieve this goal, the company has recently unveiled Sezzle Pay Anywhere, a revolutionary subscription-based service designed to enhance the BNPL experience by enabling consumers to use Sezzle’s virtual card across various shopping platforms, including online, in-store and anywhere Visa Inc. transactions are accepted. In this article, we delve into the key factors driving Sezzle’s move into BNPL, the benefits it offers to both consumers and merchants and its anticipated impact on the future of payment solutions.
Catering to Consumer Preferences
The rapid ascent of BNPL in recent years has been fueled by its ability to offer consumers an alternative to traditional payment methods. Shoppers, especially millennials and Gen Z, appreciate the convenience of making purchases without the immediate burden of paying the full amount upfront.
By making the move to BNPL, Sezzle acknowledges the changing dynamics of consumer behavior and the increasing demand for flexible payment options. Sezzle Pay Anywhere emerges as a strategic response to consumer preferences, ensuring they can utilize the installment payment service across a wide range of retail settings and payment channels. This inclusivity opens up new avenues for Sezzle to reach a broader customer base and foster stronger brand loyalty.
Expanding Market Presence
As the BNPL market continues its meteoric rise, competition among payment providers intensifies. To maintain its competitive edge and solidify its position as a market leader, Sezzle is proactively expanding its market presence with the introduction of Sezzle Pay Anywhere.
By offering consumers the freedom to shop online, in physical stores, and virtually anywhere Visa Inc. transactions are accepted, Sezzle taps into a diverse and vast ecosystem of retailers and merchants. This move not only enhances Sezzle’s brand visibility but also establishes it as a versatile and comprehensive BNPL solution provider.
Enhancing Financial Inclusion
One of the key driving forces behind Sezzle’s move to BNPL is its commitment to financial inclusion. Traditional financing options often pose significant barriers for consumers with limited credit histories or those who face challenges accessing credit. Sezzle Pay Anywhere aims to bridge this gap by offering an interest-free installment payment service to consumers, regardless of their credit scores.
This not only provides responsible financing options by Sezzle to a broader spectrum of consumers but also instills confidence and financial empowerment among those who have previously been excluded from traditional payment methods.
Benefits for Merchants
Sezzle Pay Anywhere not only benefits consumers but also offers numerous advantages to merchants. By integrating Sezzle’s installment payment service into their checkout process, merchants can tap into a larger customer base and increase conversions.
The convenience of BNPL attracts impulse purchases and encourages higher cart values, thus driving revenue growth for businesses. Moreover, Sezzle’s commitment to responsible financing mitigates the risk of defaults, ensuring that merchants receive timely payments while offering consumers a frictionless shopping experience.
As the BNPL landscape continues to evolve, Sezzle’s move to introduce Sezzle Pay Anywhere represents a strategic leap forward in the payment industry. By catering to consumer preferences, expanding market presence, enhancing financial inclusion, and providing benefits to merchants, Sezzle is poised to revolutionize the way consumers shop and pay for their purchases. As Sezzle Pay Anywhere gradually rolls out and gains broader availability, it is expected to shape the future of payment solutions, empowering consumers with greater financial flexibility and driving the growth of e-commerce and retail industries alike.
Sezzle Pay, the innovative installment payment platform from Sezzle Inc., stands out as a pioneering solution that redefines the way consumers shop and pay for their purchases. Designed to provide responsible financing to underrepresented consumers, Sezzle Pay offers a comprehensive set of features that not only empower shoppers with flexible payment options but also incentivize them with rewards and opportunities to build credit. Let’s explore the key features that make Sezzle Pay a game-changer in the world of payments.
Bridging the Financing Gap
Sezzle Pay takes pride in addressing a significant challenge faced by many consumers: lack of access to responsible and flexible financing. By launching Sezzle Pay Anywhere, Sezzle is bridging this gap, ensuring shoppers can use the installment payment service across a vast network of retailers and payment channels. Whether consumers are shopping online, paying bills, or making in-store purchases, Sezzle Pay Anywhere enables them to enjoy the convenience of BNPL wherever Visa is accepted.
Responsible Financing
The core philosophy of Sezzle Pay revolves around promoting responsible financial practices. Unlike traditional credit options that may come with high interest rates and hidden fees, Sezzle Pay offers interest-free installment plans, providing consumers with a transparent and manageable way to spread out their payments. This approach fosters financial discipline and helps consumers stay within their budget while making essential purchases.
1% Cashback on Eligible Transactions
Sezzle Pay goes beyond just facilitating installment payments; it also rewards consumers for their loyalty and usage. With Sezzle Pay Anywhere, shoppers have the opportunity to earn 1% cashback on eligible transactions. This enticing incentive not only encourages consumers to use Sezzle Pay more frequently but also adds value to their shopping experience.
Building Credit with Sezzle Up
Sezzle Pay demonstrates its commitment to the financial well-being of consumers through its innovative feature, Sezzle Up. This opt-in program allows users to build their credit while utilizing Sezzle’s installment payment service responsibly. By making timely payments, consumers can improve their credit scores, paving the way for better financial opportunities in the future.
Seamless Integration
Sezzle Pay boasts a user-friendly and seamless integration process that makes it easy for consumers to access the service across various platforms. Whether it’s integrating into an online store’s checkout process or facilitating in-store transactions, Sezzle Pay ensures a smooth and hassle-free experience for both consumers and merchants.
Increased Conversions for Merchants
Merchants partnering with Sezzle Pay benefit from increased conversions and higher cart values. The convenience of BNPL attracts more customers, leading to reduced cart abandonment rates and an uptick in sales. Moreover, Sezzle’s responsible financing approach reduces the risk of defaults, giving merchants peace of mind and a reliable payment solution for their businesses.
Sezzle Pay’s key features encompass a holistic approach to payments, focusing on responsible financing, consumer rewards, and building credit. By bridging the financing gap and making installment payments accessible at any Visa-accepting retailer, Sezzle Pay empowers consumers with a flexible and transparent payment solution.
As it incentivizes responsible financial behavior through cashback rewards and Sezzle Up, the platform not only benefits consumers but also proves to be a valuable asset for merchants seeking increased conversions and customer loyalty. With its user-friendly integration and commitment to financial well-being, Sezzle Pay is set to reshape the payment landscape, leading the charge towards a more inclusive and responsible financial future.
The primary advantage of Sezzle Pay Anywhere is its universal accessibility. Consumers can use Sezzle’s installment payment service not only for online purchases but also for in-store transactions and anywhere Visa transactions are accepted. This broad acceptance ensures a seamless and consistent shopping experience, whether customers are shopping online or visiting physical retail locations.
Bridging the Financing Gap
Sezzle Pay Anywhere is specifically designed to cater to consumers who may have had difficulty accessing traditional financing options. By offering interest-free installment plans, Sezzle bridges the financing gap and provides a responsible financing alternative to individuals with limited credit histories or those facing financial constraints.
Increased Shopping Power
With Sezzle Pay Anywhere, consumers can enjoy increased shopping power. They can make purchases without the need for immediate full payment, making higher-priced items more attainable and encouraging impulse buying, thereby benefiting both consumers and merchants.
Seamless Integration
Sezzle Pay Anywhere seamlessly integrates with various retailers and payment platforms. This user-friendly integration ensures a smooth checkout process for consumers and a straightforward implementation for merchants, making it a hassle-free solution for both parties.
Rewards and Credit Building
Sezzle Pay Anywhere offers additional incentives to consumers. Shoppers can earn 1% cashback on eligible transactions, providing an added benefit to their shopping experience. Moreover, the opt-in Sezzle Up program allows consumers to build their credit by making timely payments, potentially improving their financial standing in the long run.
Consumer Loyalty
By providing a flexible and rewarding payment option, Sezzle Pay Anywhere fosters customer loyalty. Satisfied consumers are more likely to return to merchants who offer Sezzle Pay, leading to increased repeat business and enhanced brand loyalty for participating retailers.
Risk Mitigation for Merchants
For merchants, Sezzle Pay Anywhere offers a risk-mitigation advantage. With Sezzle handling the installment payments and ensuring timely disbursements, merchants are protected from potential defaults, allowing them to focus on their core business operations without financial uncertainty.
Increased Conversions and Sales
The availability of Sezzle Pay Anywhere at the point of purchase can significantly boost conversions for merchants. The convenience and affordability of BNPL options attract a broader customer base, reduce cart abandonment rates, and ultimately lead to increased sales for participating retailers.
Enhanced Customer Experience
Sezzle Pay Anywhere enhances the overall customer experience by providing a payment option that aligns with the preferences and financial situations of a diverse range of consumers. It eliminates the need for credit checks and empowers shoppers with more control over their purchases.
Financial Inclusion
Sezzle Pay Anywhere contributes to financial inclusion by extending responsible financing options to individuals who may have been excluded from traditional credit avenues. This empowerment fosters financial stability and opens doors to broader economic opportunities for consumers.
Overall, Sezzle Pay Anywhere offers a comprehensive set of benefits to consumers and merchants alike. Its universal accessibility, flexibility, and rewards make it an appealing payment solution for consumers, while merchants benefit from increased sales, risk mitigation, and enhanced customer loyalty. With its commitment to responsible financing and financial inclusion, Sezzle Pay Anywhere stands as a pioneering force in the world of modern payment solutions.
Conclusion
In conclusion, Sezzle Pay Anywhere emerges as a trailblazing payment solution that not only meets the evolving demands of modern consumers but also empowers merchants to thrive in a competitive landscape. With its universal accessibility, flexibility, and focus on responsible financing, Sezzle Pay Anywhere bridges the financing gap and extends financial empowerment to a broader audience.
By seamlessly integrating with various retailers and offering rewards through cashback and credit-building opportunities, Sezzle Pay Anywhere fosters consumer loyalty and enhances the overall shopping experience.
Moreover, its risk mitigation benefits and potential for increased conversions make it an invaluable asset for merchants seeking growth and success in the digital marketplace. As Sezzle continues to revolutionize the payment industry with its commitment to financial inclusion and responsible financing, Sezzle Pay Anywhere sets the stage for a future where convenience, accessibility, and consumer satisfaction reign supreme.
Embracing Sezzle Pay Anywhere not only marks a step towards financial empowerment for shoppers but also signifies a strategic move towards a more inclusive and prosperous retail landscape.
Frequently Asked Questions (FAQs)
How does Sezzle Pay Anywhere work?
To use Sezzle Pay Anywhere, consumers must first subscribe to the service. They can then choose Sezzle as their payment method during checkout at participating retailers or merchants. By using their Sezzle Virtual Card, they can split their purchase amount into multiple interest-free installments and pay over time.
Is Sezzle Pay Anywhere available everywhere?
Sezzle Pay Anywhere aims to be available wherever Visa Inc. transactions are accepted. While it is gradually rolling out, it is anticipated to be broadly available by the end of the third quarter. Consumers can check the Sezzle website or app for a list of participating retailers and merchants.
Are there any fees for using Sezzle Pay Anywhere?
As Sezzle Pay Anywhere is still in the beta stage, the fee structure is yet to be finalized. However, Sezzle has a transparent fee system for its installment payment service, and consumers can expect to have a clear understanding of any applicable fees once the service is fully available.
Can I earn rewards or build credit with Sezzle Pay Anywhere?
Yes, Sezzle Pay Anywhere offers additional benefits to users. Consumers can earn 1% cashback on eligible transactions, adding value to their shopping experience. Moreover, by opting into the Sezzle Up program, consumers can build their credit by making timely payments, potentially improving their financial standing in the long run.
Is Sezzle Pay Anywhere secure?
Yes, Sezzle Pay Anywhere prioritizes the security and privacy of its users. The platform implements robust security measures to safeguard personal and financial information, ensuring a safe and protected shopping experience for consumers.
Can I use Sezzle Pay Anywhere for all types of purchases?
Sezzle Pay Anywhere is designed for everyday purchases, whether it’s shopping online, paying bills, or making in-store purchases. However, some merchants may have restrictions on certain product categories or transactions, so it’s essential to review the terms and conditions of individual retailers.
Cookie Consent
We use cookies to enhance your browsing experience, analyze site traffic, and support our marketing.You can accept all cookies, reject non-essential ones, or manage your preferences below. Learn more in our Privacy Policy.
Cookie Preferences
Manage your cookie preferences below:
Essential cookies enable basic functions and are necessary for the proper function of the website.
Name
Description
Duration
Cookie Preferences
This cookie is used to store the user's cookie consent preferences.
180 days
These cookies are needed for adding comments on this website.
Name
Description
Duration
comment_author_email
Used to track the user across multiple sessions.
Session
comment_author_url
Used to track the user across multiple sessions.
Session
comment_author
Used to track the user across multiple sessions.
Session
Google Tag Manager simplifies the management of marketing tags on your website without code changes.
Name
Description
Duration
cookiePreferences
Registers cookie preferences of a user
2 years
td
Registers statistical data on users' behaviour on the website. Used for internal analytics by the website operator.
session
These cookies are used for managing login functionality on this website.
Name
Description
Duration
wordpress_logged_in
Used to store logged-in users.
Persistent
wordpress_sec
Used to track the user across multiple sessions.
15 days
wordpress_test_cookie
Used to determine if cookies are enabled.
Session
Statistics cookies collect information anonymously. This information helps us understand how visitors use our website.
Google Analytics is a powerful tool that tracks and analyzes website traffic for informed marketing decisions.
Contains information related to marketing campaigns of the user. These are shared with Google AdWords / Google Ads when the Google Ads and Google Analytics accounts are linked together.
90 days
__utma
ID used to identify users and sessions
2 years after last activity
__utmt
Used to monitor number of Google Analytics server requests
10 minutes
__utmb
Used to distinguish new sessions and visits. This cookie is set when the GA.js javascript library is loaded and there is no existing __utmb cookie. The cookie is updated every time data is sent to the Google Analytics server.
30 minutes after last activity
__utmc
Used only with old Urchin versions of Google Analytics and not with GA.js. Was used to distinguish between new sessions and visits at the end of a session.
End of session (browser)
__utmz
Contains information about the traffic source or campaign that directed user to the website. The cookie is set when the GA.js javascript is loaded and updated when data is sent to the Google Anaytics server
6 months after last activity
__utmv
Contains custom information set by the web developer via the _setCustomVar method in Google Analytics. This cookie is updated every time new data is sent to the Google Analytics server.
2 years after last activity
__utmx
Used to determine whether a user is included in an A / B or Multivariate test.
18 months
_ga
ID used to identify users
2 years
_gali
Used by Google Analytics to determine which links on a page are being clicked
30 seconds
_ga_
ID used to identify users
2 years
_gid
ID used to identify users for 24 hours after last activity
24 hours
_gat
Used to monitor number of Google Analytics server requests when using Google Tag Manager
1 minute
Marketing cookies are used to follow visitors to websites. The intention is to show ads that are relevant and engaging to the individual user.
Facebook Pixel is a web analytics service that tracks and reports website traffic.

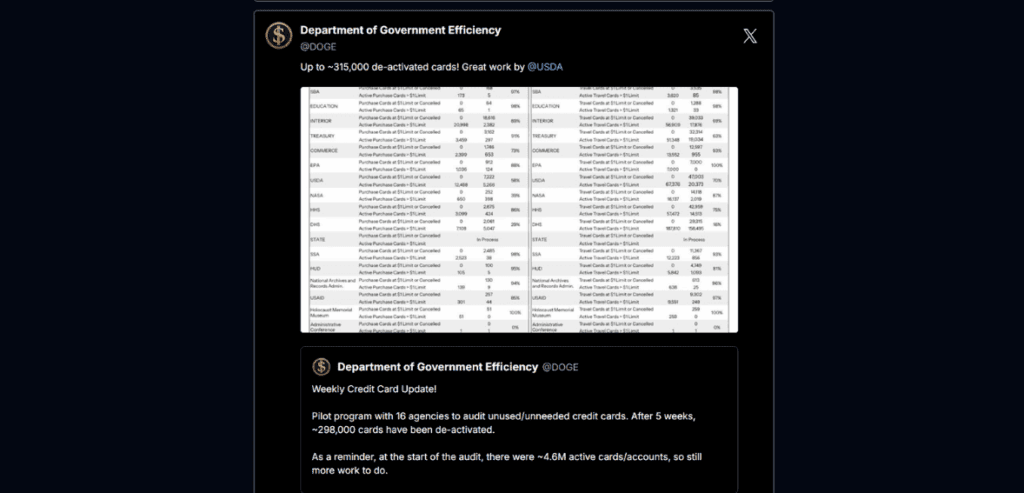
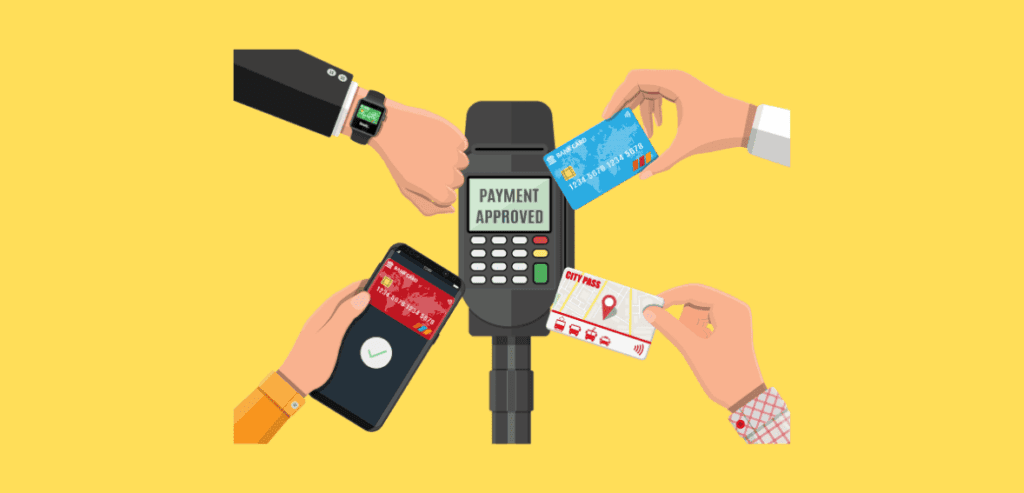
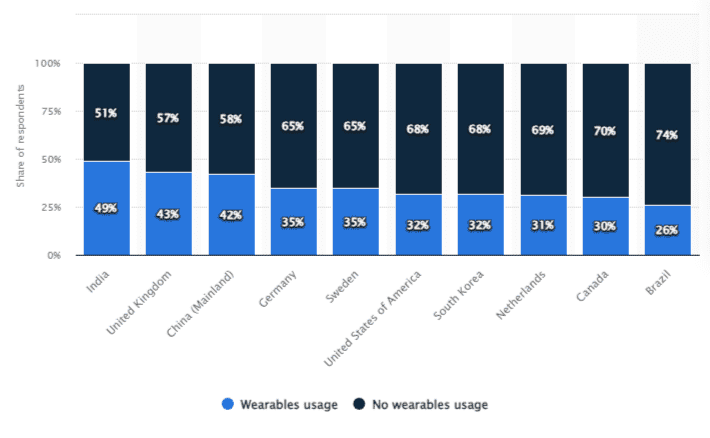

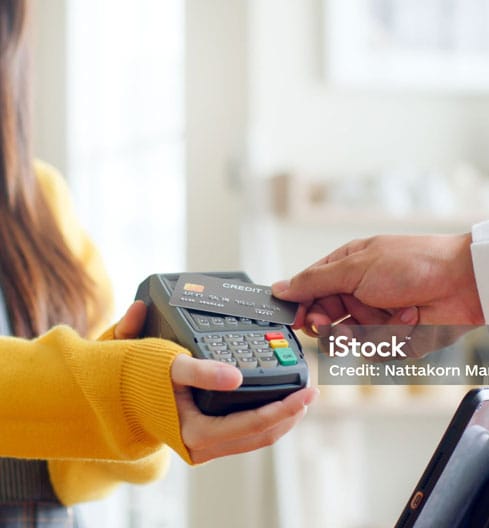
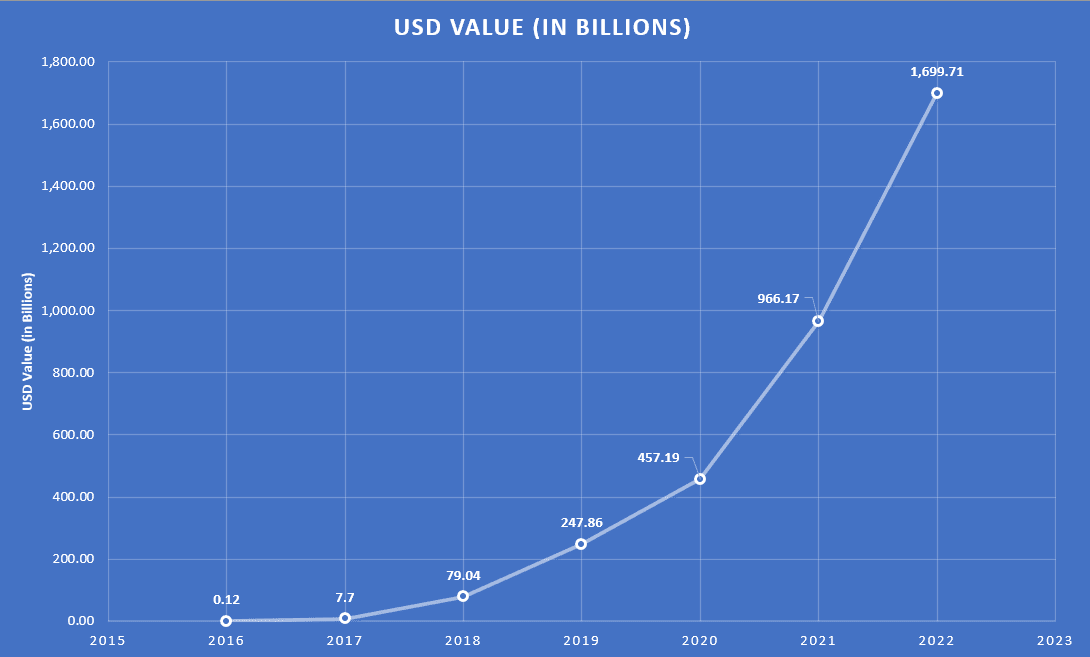
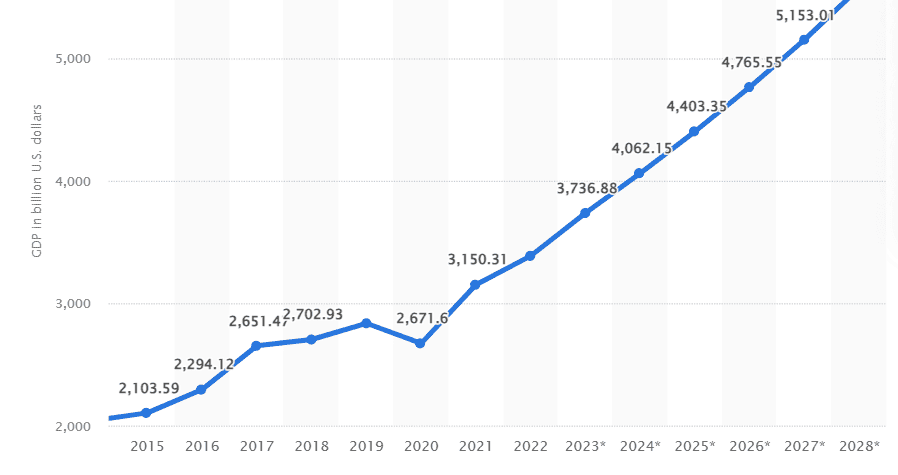
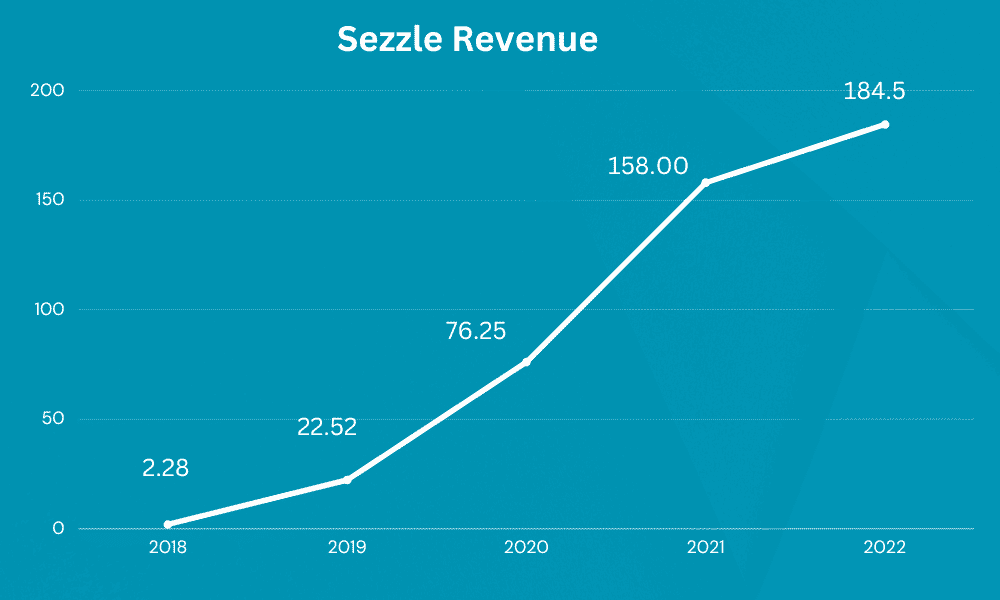
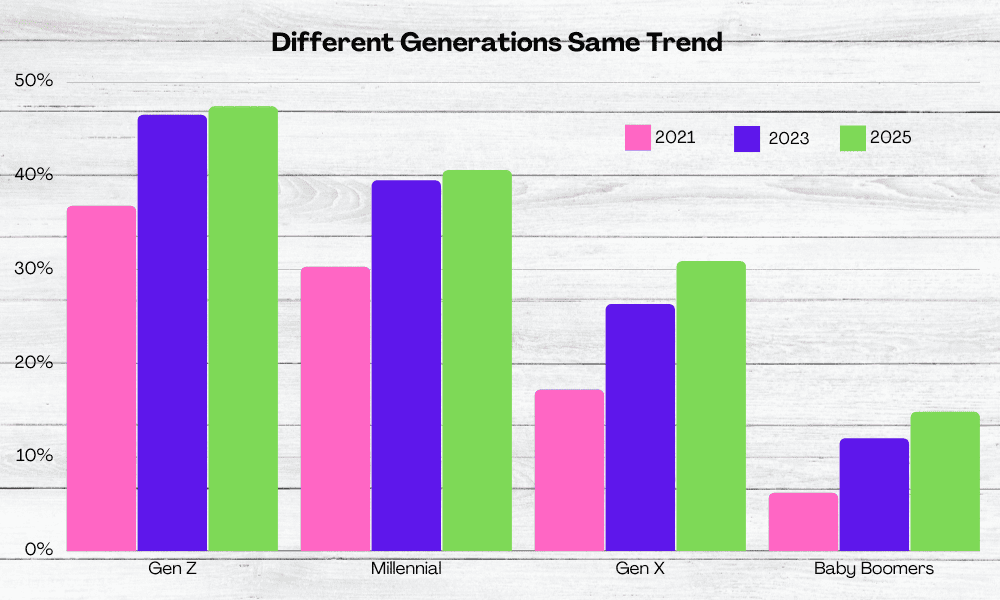
 Recommended :