Author Archives: hmsstage

Do Not Honor in credit card processing

Do Not Honor Error Code: What It Means and How to Fix It

Many merchants may scroll through their merchant account statements to review their processed transactions and see unsuccessful payments with the code: ‘05: DoNotHonor.’ So why does the do not honor error code show up? Who’s to blame for the do not honor decline; the merchant, the banks, or the customer?

Unfortunately, the answer is not always straightforward. Most merchants have seen the standard credit card transaction code ‘05’, also known as the Do Not Honor code. While frustratingly vague, this code can be challenging to explain to customers waiting expectantly to complete their transactions.

In this article, we are going to go into detail about what does do not honor mean, some reasons why a do not honor decline occurs, how to fix it, and why it would be necessary for merchants to familiarize themselves with this error code and the reasons for its occurrence. We also offer some recommendations on how to mitigate the fallout in regard to the customer experience once a do not honor decline is fired off from the issuer.

What does Do Not Honor mean?

Decline code 05, also known as the do not honor code, indicates that the credit card issuer has declined the transaction. It occurs when the credit card authorization request returns a decline because the cardholder’s issuing bank refuses to validate the transaction.

There are a variety of reasons that prompt the issuing bank to send back the do not honor decline.

Some reasons for a do no honor decline

There are many issues that the do not honor code may be referring to. The code is very similar to the Error 404 code many online customers encounter on websites they are trying to make purchases on. Much like the error 404 code, the 05: donothonor code is used because even the issuing bank may not be exactly sure why the charge is denied. As a result, this error code is issued by the issuing bank message as a blanket response to encompass the long list of possible defects in the transaction or in the cardholder’s actions that may have caused it.

Some of the main reasons this code is most commonly used include the following:

  • There is an outstanding preauthorization charge on the cardholder’s account, resulting in insufficient funds to process the current transaction
  • The client has attempted to make this payment after a series of denials on behalf of their issuing bank. After those repeated attempts, the bank has decided to block any activity on the card, flagging it as a risk of being a stolen card or otherwise used fraudulently.
  • The issuing bank is situated in a different country. As a result, the issuer has placed a geographical block on the customer’s card, blocking them from using it if they have not been informed that the cardholder may be traveling.
  • In rare cases, the payment is flagged by the issuing bank’s fraud prevention team because the transaction appears unusual in nature for several reasons, such as the payment being processed late at night or at a unique time based on the cardholder’s traditional shopping patterns, several transactions having occurred together in rapid succession, or the amount being charged is unusually high based on the client’s spending history.
  • The cardholder may be exceeding the card’s credit limit and thus cannot pay for the transaction.
  • It’s also a good idea to check if the card is valid and whether the merchant or the customer has entered all the information incorrectly, as these errors could also cause a decline.
  • There may also be a discrepancy in the security codes used. A mismatch between the AVS or CVC code on the card and what the cardholder or an employee entered when processing the transaction can also result in a do not honor decline.
  • There may be a problem authenticating the transaction. 3D Secure is a security protocol that Visa and Mastercard developed to help reduce the risk of fraud in online credit card transactions. It is also known as the “Verified by Visa” or “Mastercard SecureCode” program.

For online purchases with a credit card enrolled in 3D Secure, the consumer may be prompted to enter an additional security code, usually sent to your phone via SMS or your email address. This code must be entered before the transaction can be completed, providing the cardholder with an extra layer of protection. 3D Secure is designed to verify the cardholder’s identity and ensure that the person making the purchase is the actual owner of the card. This can help reduce the risk of fraudulent transactions, as it makes it more difficult for someone else to use your credit card without your knowledge.

  • At other times, a do not honor decline is the best way for the issuer to stop a transaction. The decline could stem from any abovementioned options and may be a precautionary effort to mitigate risk. However, in some instances where actual fraud is suspected, there are limitations around how the issuer can communicate that back to the merchant, based on an international standard messaging format called ISO 8583.

ISO 8583 is widely used in the payment card industry and is supported by many payment card networks, including Visa, Mastercard, and American Express. ISO 8583 defines a common set of data elements and rules for the exchange of payment card data between financial institutions. The standard is used for the exchange of payment card transactions and related messages between payment card issuers, acquirers, and other financial institutions. It is widely used in the banking and financial industry to facilitate the authorization, clearing, and settlement of payment card transactions.

There is a specific code issuer can use to communicate the potential of fraudulent activity, “59: Suspected fraud.” However, Visa maps a 59: Suspected fraud decline to the 05: donothonor decline option. The card network takes this action to avoid an uncomfortable or possibly dangerous situation in an in-store setting.

It is important to note that the 05: donothonor code doesn’t necessarily imply fraudulent behavior. According to an explanation issued by Visa, most Do Not Honor declines happened for transactions that had less to do with fraud than with a customer error.

According to Visa’s analysis of global declined transactions, do not honor declines are on the rise. In fact, 76% of all international do not honor declines were either a result of insufficient funds or do not honor.


How to fix do not honor declines?

The simplest solution is to ask the customer to use a different payment method or another card to process the transaction. If that is not an option, the next best alternative is to request the client that they contact their issuing bank and inform them of the transaction and the issue they are facing, explaining to the issuer any possible reason that may be causing the do not honor decline that is applicable for the customer. If it is the case, the customer should inform their issuing bank that the decline may be happening because they are traveling, are out of the country, and are trying to purchase a large ticket item that exceeds their usual spending behavior.

Finally, you can ask the client to wait for an extended period, for around three to four hours, before trying the transaction again. The client may attempt too many successive purchases simultaneously, failing card networks’ velocity checks.

Outside of the solutions outlined above, the unfortunate reality is that there are not many other options available for solving this error code as in most or almost every case, it is beyond rare to find out what exactly the specific cause for the error code to show up is.

Using automation to mitigate do not honor declines

Do not honor declines for online transactions can be a cause for concern for most merchants due to the potential loss of sales and customers, possibly permanently. Especially if the merchant cannot explain the reason for the decline, it’s possible that customers may attribute the do not honor decline to some issue with the merchant’s system. However, this does not have to be the case. Below are some potential solutions that merchants can use to fortify their processing platform to reduce any impact on revenue and customer relationships. 

The first option is to over-communicate and start by sending automated emails to customers impacted by do not honor declines, informing them of the error code so you can work with them to remedy the situation. Proactiveness would be the best weapon to turn a skeptical, possibly angry, customer into one that views the merchant as a trusted partner and adviser.

Another solution would be to issue a coupon with a follow-up email to those customers explaining what happened, some potential reasons as to why do not honor decline may have occurred, and reminding them of specific steps they should have taken by now. If the client was trying to buy particular items on sale or other limited-time offers, explain to the customer that they will still be eligible for the offer, extending the limited-time offer for a certain number of days upon receipt of the latest email. 

These automated outreach options are just some of the few ways merchants can stay proactive to mitigate the potentially adverse impacts of a complex transaction decline code. Once implemented, these options can immediately over-communicate with customers, not just for not honor code declines but for any possible error code or chargebacks. These efforts can go a long way in improving the customer experience and can be easily scaled.

Conclusion

The error code ‘05: DoNotHonor’ is very common and also vague in its appearance. Essentially Decline code 05, also known as the Do Not Honor code, is when the payment processing attempt results in a rejection of the transaction’s authentication because the issuer refuses to validate the transaction. The ability to pinpoint the exact source of the ‘05: DoNotHonor’ code is complex as there are many issues that this error code could potentially be referring to. The issuing bank issued the do not honor decline code as an umbrella code to encompass the long list of possible defects that may have caused it.

The best solution for the merchant when they receive these decline codes is to try to attempt the processing of the transaction again; if that doesn’t work, then it is recommended to ask the client to either use another card or pay by cash. The client should immediately try to contact their bank to resolve the issue.

Just because the code has shown up doesn’t mean you have lost the revenue. When it comes to online transactions, make sure your payment gateway is not experiencing any issues and communicate to your client about the error code. Most of the time, the do not honor code results from actions taken by the consumer or the merchant. Maybe the client didn’t inform the issuer that they would be traveling, resulting in a geographical block of their card. Perhaps the security code is being entered erroneously.

That’s not to say there is no cause for alarm, and merchants should not be vigilant. Just as there’s an increase in eCommerce sales and noncash payment methods, there has also been a spike in payments fraud. Merchants should be aware that do not honor code declines are very common, and they should have a firm grasp of what such a decline code means some possible reasons it occurs, and some steps to take to remedy the situation.

Frequently Asked Questions

  1. What does it mean when your bank declined the transaction with a u0022Do Not Honouru0022 message?

    When your bank declines a transaction with a u0022Do Not Honouru0022 message, it means that they have chosen not to authorize the transaction. This can happen for various reasons, such as insufficient funds, suspected fraudulent activity, or a security concern. It’s advisable to contact your bank to understand the specific reason for the declined transaction and to address any issues that may have led to the u0022Do Not Honouru0022 response.

  2. What is the meaning of u0022honor creditu0022?

    u0022Honor creditu0022 typically refers to the act of fulfilling financial obligations, particularly in the context of credit or loan agreements. It means making timely payments and meeting the terms and conditions outlined in the agreement, demonstrating responsible financial behavior. By honoring credit obligations, individuals or businesses establish a positive credit history, which can enhance their credibility and improve their chances of obtaining future credit or loan approvals.

  3. What does u0022Do Not Honoru0022 due to AVS CVV settings mean?

    When a transaction is declined with a u0022Do Not Honoru0022 message due to AVS (Address Verification System) CVV (Card Verification Value) settings, it suggests that the information provided during the transaction does not match the cardholder’s billing address or the CVV code on the credit card. This could be due to entering incorrect or incomplete information or using a card that has expired. It’s important to verify and enter accurate billing addresses and CVV information to ensure a successful transaction.

  4. What does u0022honoru0022 mean in banking?

    In the context of banking, u0022honoru0022 typically refers to the act of fulfilling financial obligations or commitments, particularly related to payments or transactions. When a bank honors a payment or transaction, it means they have approved and executed it as per the agreed terms and conditions. This includes processing checks, authorizing credit card transactions, or executing other financial services by the customer’s instructions and the bank’s policies.

  5. How do I fix my u0022Do Not Honoru0022 credit card?

    To address a u0022Do Not Honoru0022 issue with your credit card, there are a few steps you can take. First, ensure that you have sufficient funds in your account or available credit to cover the transaction. If funds are not the issue, contact your bank or credit card issuer to inquire about the specific reason for the declined transaction. They can provide guidance on resolving the issue, which may involve updating your account information, verifying transaction details, or resolving any security concerns.

  6. What is an example of u0022honoru0022 in a banking context?

    An example of u0022honoru0022 in a banking context is when a bank honors a check presented for payment. If a customer writes a check to another party, and there are sufficient funds in the customer’s account, the bank will honor the check by processing it and transferring the specified amount to the payee’s account. This demonstrates the bank’s fulfillment of its obligation to facilitate the payment as per the customer’s instruction and maintains the integrity of the banking system.   
amazon prime day traffic held up

Amazon Prime Day vs. Walmart+ Weekend: Recent Updates

Summer “Prime Day”–style events remain marquee dates in retail. Amazon’s official data and third-party analyses show Prime Day 2024 was the largest ever, about $14.2 billion in U.S. e‑commerce sales (up 11% YoY). According to a recent report, 60% of Amazon Prime Day households placed multiple orders, driving an average household spend of $152.

By contrast, Walmart’s member‑only June 2024 Walmart+ Week drew far fewer shoppers but higher per‑shopper spending. Surveys find 40% of consumers shopped on Prime Day versus 20% for Walmart+ Week. However, Walmart+ members who did shop spent roughly 45% more per shopper ($473 vs. $326 on Prime Day).

Key Takeaways
  • Amazon’s Prime Day continues to attract broad consumer awareness and volume of sales, while Walmart is building out its member events with new perks.
  • Both retailers note inflation-sensitive shoppers: about 60% said rising prices influenced their decision to participate.
  • Amazon’s strategy includes multiple Prime Day events (July and October) and deep discounts (average 22% off), while Walmart has offered perks like half-priced memberships for low-income consumers, free Paramount+ trials, and a Burger King benefit.
  • These tactics aim to grow Walmart+ subscribers (forecast to reach 31.8 M by end-2024) and close the gap with Amazon Prime’s 180M U.S. members (200 M+ globally).

Amazon Prime Day vs. Walmart+: Sales Performance & Volume

Amazon Prime Day vs. Walmart+ - sales performance

Amazon Prime Day 2024 emerged as a record-breaking event, marking the company’s biggest sales day ever. U.S. online spending surged to approximately $14.2 billion during the event, reflecting an 11% increase from the $12.7 billion recorded in 2023. Electronics and Back-to-School categories were standout performers, with electronics sales soaring by 61% and tablet sales climbing a staggering 117%. On July 16 alone, consumers across all retailers spent $7.2 billion online, setting a new single-day spending record according to Adobe Analytics.

In comparison, Walmart+ Week 2023, held from July 10 to 13, drew a smaller audience, with consumer spending estimated at $10.5 billion, still trailing Prime Day’s $12.7 billion from the same year. A notable portion of this spending was directed toward groceries, which made up 52% of total shopper expenditures. While total sales figures for Walmart+ Week 2024 remain undisclosed, surveys indicate that although participation was limited to about 20% of consumers (compared to nearly 40% for Prime Day), individual shopper spending was significantly higher. Moreover, spending during Walmart+ Week 2023 had already doubled compared to its 2022 iteration, signaling growing consumer interest in alternative sales events. 

Consumer Engagement and Digital Reach

Amazon Prime Day vs. Walmart+ - Consumer Engagement

Consumer awareness around major retail events shows a clear disparity, particularly between Amazon Prime Day and Walmart+ Week. In July 2023, around 40% of U.S. consumers reported shopping during Prime Day, while only about 20% did so during Walmart+ Week. Strikingly, nearly half of the surveyed consumers admitted they weren’t even aware that Walmart+ Week was taking place. In sharp contrast, nearly all Prime Day participants—about 98%—were aware of the event beforehand. This pattern persisted into 2024, with participation rates remaining relatively unchanged, highlighting Walmart’s ongoing challenge in boosting event visibility.

In terms of digital engagement, while detailed traffic data is limited, insights suggest Amazon significantly outpaces Walmart. The Amazon Commerce blog noted that nearly half of Prime Day purchases occurred on mobile devices, with a strong push from social media referrals. Although Walmart holds the #2 spot in U.S. online retail and typically experiences traffic surges during promotional events, specific figures for Walmart+ Week remain undisclosed. Anecdotal trends, however, consistently show that Amazon Prime Day drives far higher levels of web and app traffic compared to Walmart’s member-based events.

Consumer behavior during major retail events reveals distinct patterns between Amazon Prime Day and Walmart+ Week, particularly in order frequency, spending levels, and product categories. Prime Day continues to drive multiple small-to-midsize purchases. In 2023, 57% of Prime Day orders came from households placing two or more orders, with 11% making five or more. The average order value rose from $53.14 in 2022 to $56.64 in 2023, while average household spend climbed to approximately $134. By 2024, around 60% of Prime Day households placed multiple orders, pushing average household spend to about $152 and the typical order value to $58.

In contrast, Walmart+ Week shoppers displayed more concentrated, higher-value behavior. In 2023, the average Walmart+ shopper spent $200, significantly higher than Amazon’s $126 average. By 2024, that number soared to $473 per Walmart+ shopper, compared to $326 for Prime Day participants. Walmart+ Week buyers also purchased more items per trip, averaging 20 items per transaction versus just 11 for Amazon shoppers, reflecting bulk-buying behavior often centered on essentials.

Product category preferences further distinguish the events. Grocery dominated Walmart+ Week, accounting for 52% of spend in 2023 and purchased by over half of shoppers, twice the rate of Amazon’s grocery buyers. Prime Day, on the other hand, leaned heavily into electronics, apparel, beauty, and Amazon-branded devices. Notably, both events saw strong Health & Beauty category performance in 2024, with 62% of Walmart+ shoppers and 44% of Prime Day shoppers purchasing in that segment.

Despite the perception of deep discounts, a sizable portion of purchases were made at full price—41% during Prime Day and 44% during Walmart+ Week in 2024—indicating that shoppers use these events to stock up on necessities as much as to find deals. Amazon’s average discount was around 22% off list price. Inflation played a noticeable role in consumer behavior, with 62% of Prime Day and 55% of Walmart+ Week shoppers citing it as a factor in their purchase decisions. While Prime Day 2024 sales technically grew year-over-year, the modest 1.4% increase was largely attributed to a 6.4% rise in average ticket prices, suggesting that inflation, rather than higher unit volumes, drove the growth.  

Subscribers & Strategic Shifts

Amazon Prime Day vs. Walmart+ - Subscribers

Amazon and Walmart continue to chart divergent paths in membership scale and strategic positioning, though both are actively refining their subscription offerings and promotional approaches. As of March 2024, Amazon Prime boasted an estimated 180 million U.S. members—an 8% increase year-over-year—while its global paid membership surpassed 200 million. In contrast, Walmart+ remains significantly smaller but is gaining momentum, with an estimated 31.8 million members projected by the end of 2024, up from around 29 million in 2023. Despite its smaller scale, Walmart+ has achieved impressive year-over-year growth, particularly among younger and middle-income consumers.

When it comes to event participation, both Amazon and Walmart see about half of their members actively shop during their flagship sales, roughly a 56% participation rate. However, Amazon’s much larger subscriber base translates to twice as many shoppers overall during Prime Day compared to Walmart+ Week. This participation gap underscores the strategic importance for Walmart to grow its subscriber base, as increasing conversions from regular Walmart shoppers to Walmart+ members could significantly boost event performance and close the sales gap.

Both companies have also leaned into evolving their value propositions. Walmart has expanded Walmart+ benefits to include gas savings, free shipping, and exclusive perks through new partnerships. Notable additions include six months of free Paramount+ streaming and periodic Burger King discounts. Walmart also rolled out a 50% membership discount for low-income families, aligning more closely with Amazon’s long-standing Prime discount for SNAP recipients.

Amazon, meanwhile, has broadened its Prime Day strategy, adding a second event in October and sharpening its focus on innovation and small business support. The company continues to promote its latest devices and is increasingly integrating AI features, such as personalized shopping assistants, into the experience. Additionally, the broader retail landscape is now syncing with Prime Day’s calendar, competitors like Target, Best Buy, and TikTok launched parallel promotions, some seeing notable results. For instance, Walmart reported a 23% lift in sales during its July 2024 “Walmart Deals” event, reflecting the ripple effect of Amazon’s influence on the broader retail calendar.

Consumer Trends & Industry Context

Amazon Prime Day vs. Walmart+ Consumer Trends

Consumer trends surrounding major retail events like Amazon Prime Day and Walmart+ Week reveal evolving behaviors shaped by economic pressures, demographic shifts, and new payment habits. One notable shift is the rising use of buy-now-pay-later (BNPL) services. In 2024, approximately 7–7.6% of Prime Day orders were financed through BNPL, representing a 16% increase from the previous year. This trend is especially pronounced among lower-income shoppers and Gen Z consumers, who increasingly use flexible financing options to manage spending during high-volume sales events.

Demographic profiles also differ markedly between the two events. Prime Day tends to attract a more affluent, suburban, and female-skewing customer base. In contrast, Walmart+ Week resonates more with larger, value-driven households that prioritize grocery and bulk buying. About 40% of Walmart+ households have four or more members, compared to 32% among Amazon Prime households. Gen Z shoppers played a particularly active role during Walmart+ Week 2024, purchasing an average of 22 items per order, more than any other age group, further highlighting the generation’s appetite for bulk deals and practical essentials.

Against the backdrop of ongoing inflation and tightened household budgets, these summer sales events have become essential tools for driving volume and maintaining engagement. Retailers are increasingly positioning them not just as mid-year promotions, but as the unofficial start of the holiday shopping season. Deals on everyday goods and early gift purchases help shape consumer expectations, providing an early glimpse into spending patterns that are likely to extend into Q4. Walmart leadership has stressed the importance of making Walmart+ appeal to all income levels, reinforcing the brand’s broader ambition to serve as a value leader in a strained economic environment.

Conclusion

While Amazon Prime Day continues to dominate in scale and visibility, Walmart+ Week is gaining ground through deeper per-shopper engagement and targeted member incentives. Amazon leverages its massive subscriber base, strong mobile presence, and established brand awareness to drive high-volume sales, particularly in electronics and branded merchandise.

Walmart, meanwhile, is focusing on value-driven households with higher transaction sizes, especially in essential categories like groceries. Both retailers are adapting to inflation-conscious consumers and shifting payment habits, with flexible financing options and discount membership strategies. As mid-year sales events increasingly signal the start of the holiday shopping season, the competition between Amazon and Walmart reflects broader changes in consumer behavior and retail strategy.

Best Crypto Exсhаngеѕ and Apps оf 2023

Best Crypto Exchanges and Apps of 2022

A cryptocurrency exchange account is a good place to begin if you want to purchase or sell cryptocurrencies. You may purchase and sell cryptocurrencies as well as tokens such as Bitcoin, Ethereum, and Dogecoin on crypto exchanges, which operate similarly to online brokerage platforms.

Considerations such as the types of assets that may be used, the costs involved, the accepted forms of payment, and the safety measures in place should be taken into account while selecting a cryptocurrency exchange. When compiling this list of the top cryptocurrency exchanges, we took into account the aforementioned criteria to better assist you in making an informed decision.

List of Best Crypto Exchanges and Apps of 2022

Crypto.com

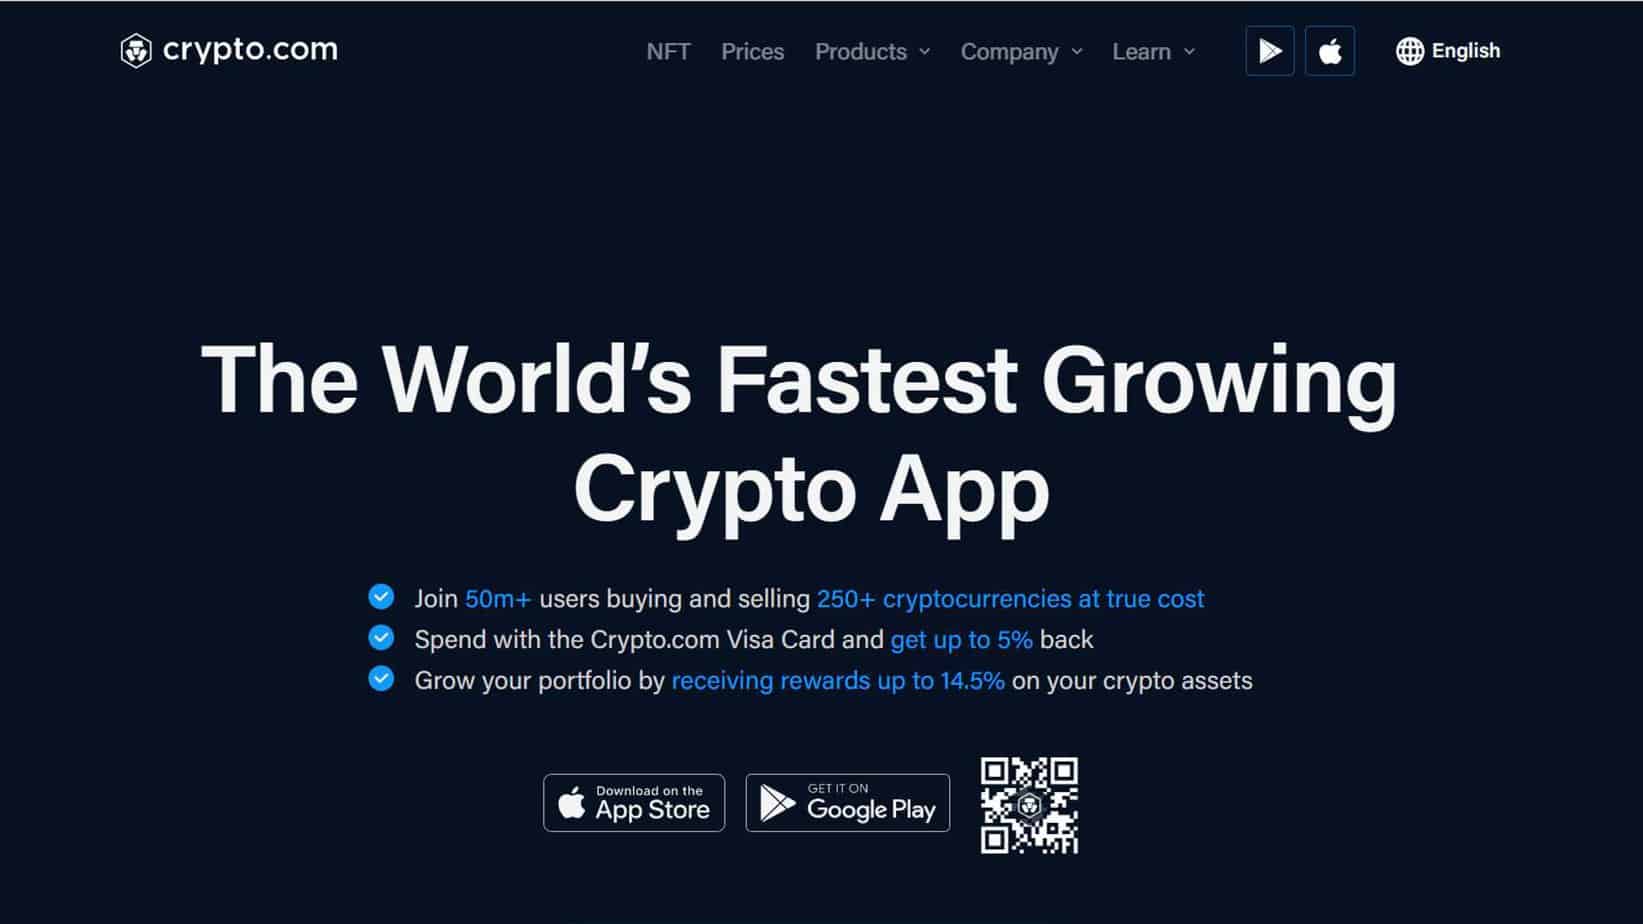
Since its 2016 inception, Crypto.com has grown to become one of the most prominent cryptocurrency trading platforms worldwide. Over 250 different cryptos are supported, and it’s presently available in 90 countries.

crypto

Image source

Crypto.com offers a wide range of digital asset goods, including cryptocurrency-yielding crypto items, a crypto visa card, and its own blockchain, Crypto.org Chain.

However, the Crypto.com mobile app sticks out the most. While most cryptocurrency exchanges’ mobile applications only mirror the cryptocurrency trading website, Crypto.com’s app was designed to provide customers with access to the whole ecosystem of this exchange while they’re on the move. Customers may use the app to purchase, trade, and pay using cryptocurrency, as well as earn interest on their holdings.

Even though Crypto.com has a ton of items and services, their customer service leaves a lot to be desired. In addition, trading costs of up to 0.075% may be incurred until larger quantities of trades are executed.

Crypto.com’s variety of goods and services, as well as its vast number of supported assets, make it a strong contender for the best mobile crypto trading experience.

Gemini

Gemini, introduced in 2014 by Tyler and Cameron Winklevoss, is notable for its commitment to stringent security measures and regulatory oversight. The New York-based exchange provides users with hot wallet insurance to protect their assets in the event of a hack. To further lessen the possibility of fraud, it also requires users to go through an identity verification procedure.

gemini

Image source

Gemini also offers the choice to evaluate and authorize trading account login devices, and it strongly recommends that its users implement two-factor authentication for further account security. Gemini’s SOC 2 certification is another noteworthy security aspect. This certification confirms that independent auditors have examined and confirmed the organization’s security and regulation compliance systems.

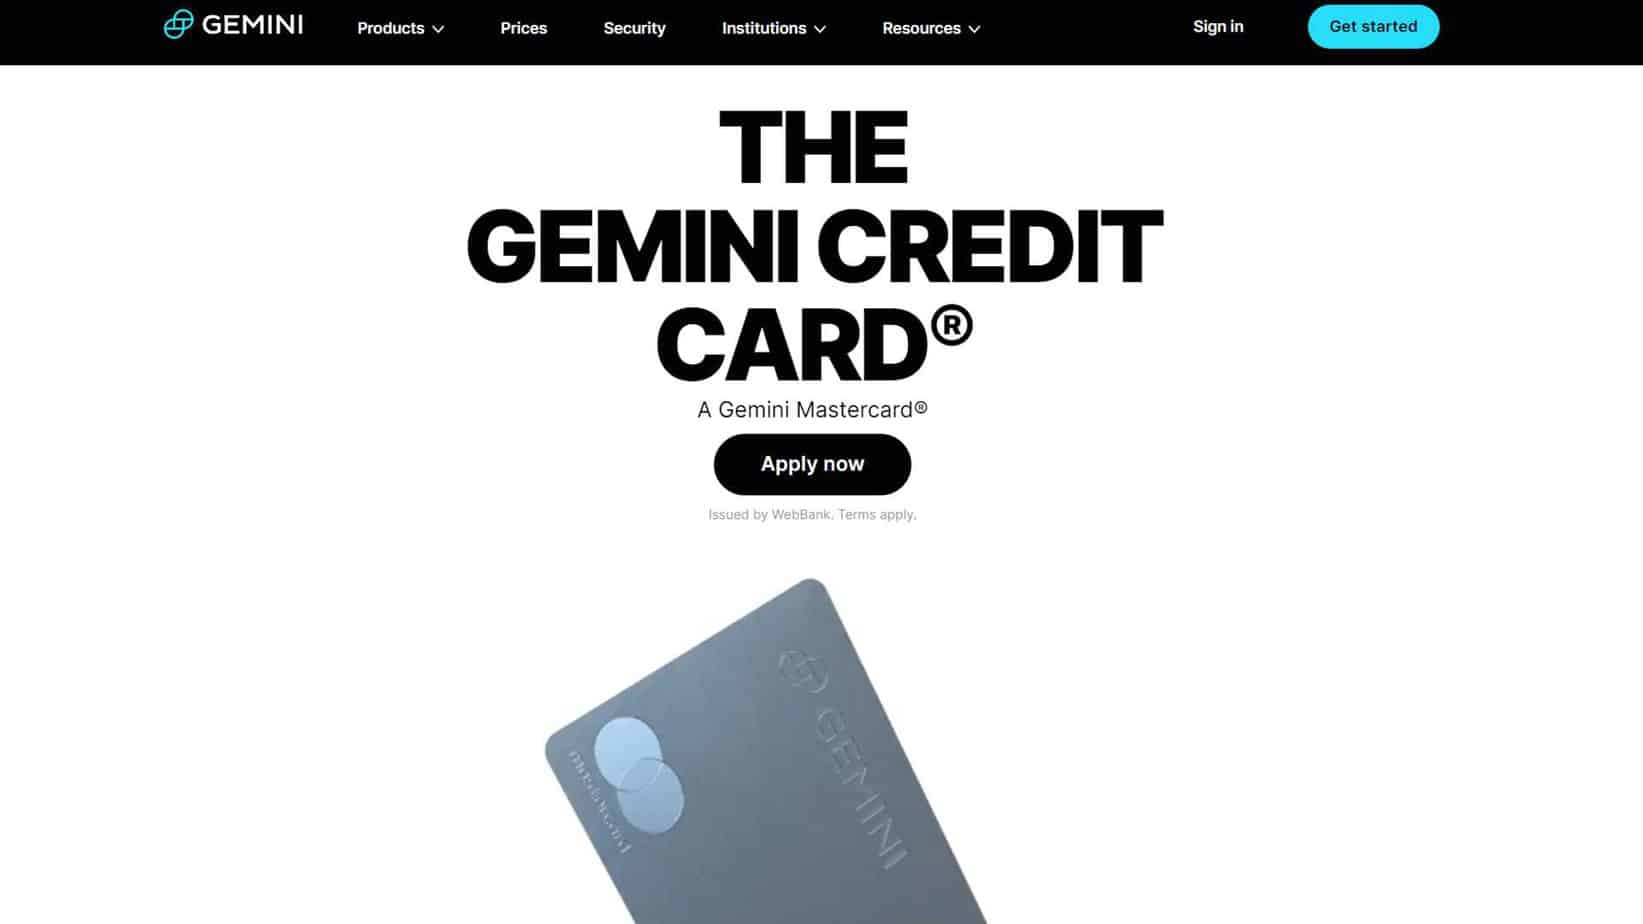
Gemini was designed with experienced traders in mind; it offers a top-notch trading dashboard and accepts more than seventy-five different cryptos and tokens. Gemini not only accepts cryptocurrencies as payment but also provides its customers with a cryptocurrency reward card.

There are distinct pricing systems for Gemini’s primary platform and its active trader platform. Trades over $200 cost a staggering 1.49% in commission on the major platform. Making and taking orders platform for active trading might cost up to 0.4% in fees. However, those costs will go down with more volume. The prices here are likewise quite steep. Gemini’s security features are among the best in the industry; thus, the somewhat hefty charge may be worth it.

Traders and investors who value safety in their transactions will find a lot to like in Gemini.

BitMart

image 22

Image source

BitMart was launched in 2017, and it is currently accessible in over 180 different countries across the world. Over a thousand different cryptos and tokens may be bought, sold, and stored there.

BitMart, a cryptocurrency exchange headquartered in the Cayman Islands, has quickly become a major market for lesser-known digital currencies. For investors seeking to diversify their portfolios with freshly launched or obscure crypto assets, BitMart may be the best option because it provides a wider variety of assets and trading pairings than its market-leading competitors.

Customers of BitMart may also utilize the Earn function of the exchange to get interested on cryptocurrency reserves. When users have the exchange’s native token, BMX, they are eligible for discounted trading fees.

Despite BitMart’s extensive features for seasoned crypto traders, the exchange has been met with mixed reviews from customers. There were multiple reports of withdrawal problems, inadequate customer service, and a lack of disclosure as examples of user concerns. Still, some praise may be found within the criticism.

Kraken

image 21

Image source

Kraken is one of the most trusted cryptocurrency exchanges since it has been around since 2011 and is accessible to users all over the globe. Kraken Pro is a high-quality trading platform offered by the San Francisco-based exchange, Kraken. Investors may buy, trade, and store over 120 cryptocurrencies on the site, and the costs are quite cheap.

In the earliest stages of the cryptocurrency industry, this feature-rich exchange quickly rose to prominence as the platform of choice for institutional investors. This reputation has been maintained.

Kraken provides not one but two platforms for its users: the primary trading platform and the more advanced Kraken Pro. The Pro interface of the exchange includes 13 different types of orders and lightning-fast execution, in addition to highly customized chart analysis tools and deep visibility into the order books. Kraken facilitates margin trading for cryptocurrencies and the execution of crypto derivatives trading methods in addition to traditional spot trading.

Cash App

image 20

Image source

Introduced in 2013 by Block, Inc. (formerly known as Square, Inc.), Cash App enables users in the US and UK to send, spend, deposit, and invest money. A mobile banking app that facilitates P2P payments and includes an investing component. Cash App users may put their money into stocks, ETFs, and even Bitcoin. Cash App stands out from its competitors because it allows users to transfer their Bitcoins to a different wallet service, something that neither Robinhood nor Venmo does.

Cash App Chief Executive Officer Jack Dorsey said in early 2022 that the business has begun pushing out features for the Bitcoin Lightning Network, which would allow for quick, nearly cost-free Bitcoin transfers.

Cash App’s custodial in-app wallet is the biggest negative of using the app to purchase and keep Bitcoin, as the corporation is responsible for safeguarding your digital assets. Although custodial wallets have many advantages, they are generally considered less safe than other types of wallets. However, given that Bitcoin may be removed from Cash App, cryptocurrency can be transferred to a private wallet for which you have the private keys.

Bisq

image 19

Image source

Bisq, which debuted in 2014, is a piece of open-source software that facilitates the decentralized trading of a variety of cryptocurrencies and tokens between users located anywhere in the world. At the moment, it can handle more than a hundred different types of digital content.

Users of this decentralized exchange are not subject to a mandatory “Know Your Customer” (KYC) authentication procedure, nor is the trading program restricted to users in any particular geographical region. Users of Bisq have the option of using bank wire transfers, ACH transactions, and even cash deposits for buying and selling Bitcoin and other cryptocurrencies.

Bisq is well-liked among Bitcoin purists because it upholds the principles upon which Bitcoin was founded—among them, decentralization, privacy, and sovereignty—but it is not an easy exchange for newcomers to use. New users may find the escrow method employed in peer-to-peer trading confusing, and both infrequent and frequent traders may be put off by the relatively delayed deal execution. Since trading volumes are less than those seen on consolidated worldwide exchanges, the marketplace is geared toward making smaller deals.

Bisq provides everything you need to purchase and sell Bitcoin on a decentralized, KYC-free platform, making it ideal for experienced crypto investors.

Conclusion

Choosing the right cryptocurrency exchange is crucial if you want to start trading or making an investment in cryptocurrencies. The greatest digital asset trading platform may be found regardless of whether you prioritize a wide variety of digital assets, reasonable costs, or a convenient mobile interface.

To get in on the action in the rapidly growing mobile trading market, we recommend Crypto.com. For the most privacy, Bisq is the greatest decentralized exchange, while Gemini has the highest security. Kraken is a great option for seasoned traders and those concerned about costs. Cash App serves the needs of Bitcoin traders, while Bitmart is our top pick for those interested in trading a wider variety of altcoins. Think about what you hope to achieve and what you need from this transaction.

recurring billing

Tips to Collect More Revenue Using Recurring Billing

Running a business is challenging, and there can be instances where some are searching for ways to increase the turnover of a business. Although recurring billing is commonplace, it is still avoided by many businesses. As such, this could mean that the company is missing out on revenue regularly. Recurring billing can significantly boost cash flow and customer lifetime value for businesses in 2025. The subscription economy has unlocked a lucrative revenue stream — it’s estimated at $3 trillion globally in 2025.

Companies from e-commerce retailers to SaaS vendors, streaming services to online educators, are adding subscription and membership options. Implementing these models well can turn one-time buyers into loyal, repeat customers. However, succeeding with recurring billing in 2025 requires attention to new challenges and trends.

The following is an overview of steps that can be taken to introduce recurring billing into a business model and use it effectively.

More Revenue Using Recurring Billing

Be Aware of The Challenges

Although recurring billing is a fantastic way of collecting more revenue, it is vital to be aware of the challenges that could be faced. When subscriptions have varying renewal dates or when promotional pricing ends, you need systems in place to deliver products or services on time and bill correctly. Customer churn is another reality. Across industries, average subscriber churn hovers around 4–5% per month​, meaning nearly one in twenty customers may cancel monthly. Consumer-facing sectors often see even higher churn: for example, digital media subscriptions had roughly 6.9% monthly churn in 2023​.

These figures underline the importance of planning retention strategies up front. Use analytics to track usage and cancellations, and define clear renewal and exit processes so changes are not disruptive. Being aware of these challenges lets you prepare contingency plans (e.g., automated notifications for renewals or flagging at-risk accounts) to keep revenue steady.

Ensure Security Is the Best it Can Be

Recurring Billing tips - Ensure Security

Regardless of the product or service being sold using recurring billing, the security of the website needs to be the best it can be. As well as instilling confidence in customers entering their details, it also ensures the sensitive information doesn’t fall into the wrong hands, which will do little to raise the profile of a brand.

Use a PCI-compliant payment system or subscription platform that tokenizes credit card data – this way, actual card numbers never reside in your database. Many billing providers offer a secure “vault” to store cards, which greatly simplifies PCI-DSS compliance​. Encrypt all data in transit and at rest, and implement fraud prevention measures (such as 3D Secure or machine-learning fraud filters). Remember that subscription businesses are attractive targets for hackers since they hold stored cards​. In practice, rely on proven payment gateways and update them regularly. Keeping security strong not only protects customer trust, it also avoids costly breaches and fines.

Provide Clear Terms and Contracts

Transparency is key to avoiding disputes and cancellations. When customers sign up for a subscription, give them a clear agreement or terms of service that outlines billing frequency, price (including any future price changes), refund policy, and cancellation rules. Many jurisdictions now require auto-renewal terms to be disclosed clearly (bold or larger font), so make sure your checkout and confirmation emails summarize the plan details. It’s best practice to email subscribers each invoice or renewal notice; this reminds them of the upcoming charge and provides an easy link to manage or cancel if needed.

By setting expectations (for example, “Your membership will renew automatically every 30 days at $X. You can cancel at any time.”), You reduce the risk of chargebacks and build trust. Providing a customer-friendly portal or account page for viewing and accepting the agreement is also effective. Clear communication about terms keeps customers informed and prevents misunderstandings.

Diversify Payment Methods and Streamline Billing

Recurring Billing tips - Payment Methods

Make it easy for customers to pay and prevent failed transactions. In 2025, consumers expect to pay with digital wallets and alternative methods. Over half of Americans already use mobile wallets (Apple Pay, Google Pay, etc.) more often than traditional cards​. Enable these wallet options alongside cards and ACH/bank debits. Payment surveys predict that QR-code checkout (33% of merchants), Buy-Now-Pay-Later plans (25%), and even cryptocurrencies (21%) will gain traction​.

While BNPL isn’t typically used for recurring charges today, just accepting it on initial orders can capture more customers. At minimum, support major credit/debit cards, top mobile wallets, and local popular methods (e.g., PayPal, SEPA, UPI, etc.), so you don’t lose sales to payment friction. Equally important is handling failed payments gracefully.

A common cause of involuntary churn is expired or declined cards. Provide customers with an easy way to update expired cards or switch payment methods (e.g. a link in their account settings or reminder emails). Use your processor’s account updater service to refresh changed card details automatically. Also implement smart retry and dunning processes: if a payment fails, send polite reminder emails and retry the charge after a short interval. These tactics pay off: one subscription platform reported saving 72% of at-risk subscribers with recovery events (dunning emails and retries), resulting in an 8.6% lift in revenue​. By broadening payment options and automating decline handling, you’ll reduce churn and keep monthly revenue more consistent.

Consider Products and Services That Can Be Used for Recurring Billing

Almost any consumable or ongoing service can be sold on a subscription basis. Look beyond the obvious SaaS or streaming examples. Think in terms of repeated customer needs. For instance, you could offer:

  • E-commerce Consumables: Set up “replenishment” subscriptions for products that run out regularly. This could be pet food, vitamins, coffee, personal care items or office supplies. Customers love not having to reorder these items manually.
  • Subscription Boxes: Curated monthly boxes (beauty, snacks, books, hobby kits, etc.) continue to grow. A personalized box can delight customers and create a habit. Offer customization so subscribers feel it’s tailored to them.
  • SaaS and Digital Services: The classic model. Offer tiered plans (basic, premium, enterprise) with monthly or annual billing. Consider usage-based add-ons (e.g. extra storage or premium features for an additional fee). For example, many accounting or marketing tools charge a base rate plus per-seat fees.
  • Education & E-Learning: Charge a monthly membership for access to a library of courses, tutoring hours, or professional training content. Many online learning platforms now bundle courses and charge a recurring fee. This can open your market to customers who prefer smaller monthly payments over a large one-time course fee.
  • Digital Media & Entertainment: Streaming video, music, podcasts, and digital news sites are obvious examples. You can also sell premium tiers (ad-free, offline access) or exclusive content via subscription. Think beyond media giants: even niche content creators (e.g. specialty magazines, indie game developers) can use membership fees.
  • Other Services: Many physical and service businesses are adding subscriptions. This includes gyms and fitness apps (monthly membership), meal-kit deliveries, automotive services (routine maintenance plans), pet-care services, or even curated fashion rentals. Even traditional retailers can add VIP clubs or maintenance programs on a subscription basis.

A recent study predicts that by 2025, about 75% of direct-to-consumer (DTC) businesses will offer some kind of subscription service​. Meanwhile, customers value subscription models: in 2024, the average consumer had over 8 active subscriptions​.

These trends mean it’s never been easier to justify finding a way to offer recurring billing in your niche. Audit your products and services for opportunities – you might discover new revenue simply by packaging things differently.

Recurring Billing Can Be Used for Gift Subscriptions

Recurring Billing - Gift Subscriptions

Practicality and affordability can be two of the most important components of a gift, so a subscription that allows people access to products and services they love can yield increased revenue for a business. The global gift market is worth tens of billions – for example, about $72.6 billion in 2024​.

You can capture some of this spend by making your subscription a gift. For instance, allow customers to purchase a 3-, 6- or 12-month prepaid subscription as a gift card or package. E-commerce sites do this by selling gift vouchers that auto-apply to a recurring plan when redeemed.

Bundles also work: offer a “starter kit” or welcome box for new subscribers, or partner with other brands to create co-branded gift subscriptions (e.g. a coffee company and a book club). Promote these especially around holidays, birthdays, and special events. By marketing subscriptions as gifts, with enticing options and packaging, you attract one-time buyers who can become recurring customers.

Recurring Billing in Digital Media and Entertainment

The media and streaming industry exemplifies how powerful recurring revenue can be. Platforms like Netflix, Disney+, Spotify and others have hundreds of millions of paying subscribers worldwide. Video streaming alone is a massive market: global streaming revenue was about $129.3 billion in 2024 and is projected to reach $416.8 billion by 2030​. It’s no surprise 88% of U.S. households now have at least one paid video streaming subscription​.

For any business with digital content, adding subscriptions is critical. Consider offering subscription packages or bundles of content (for example, grouping back-catalog movies, podcasts, or premium articles). Create multiple access tiers (e.g. basic/standard/premium or monthly/annual) and highlight features like ad-free viewing or offline access. The data shows consumers are willing to pay: on average, people spend about $61 per month across roughly four streaming services​.

To capture your share, focus on convenience and content — for instance, exclusive releases, bundled memberships with partners, or special rates for longer commitments. Flexible access (paying monthly) is especially attractive in media: a recent survey found 63% of subscribers prefer monthly billing over annual plans​

Offer Flexible Plans and Billing Options

Flexibility can dramatically improve retention. Offer multiple billing cycles (monthly, quarterly, annual) so customers can choose their preferred commitment. It’s common to discount longer-term plans, but don’t force annual billing if customers want to pay-as-you-go. Surveys show 46% of subscribers would stay if allowed to downgrade to a lower plan instead of leaving, and 39% would stay if they could pause their subscription​.

With this in mind, build features like “pause” or temporary hold on subscriptions (often used in fitness or meal plans). Allow easy plan changes (upgrading or downgrading tiers) without penalties. Also offer add-ons or one-time purchase upgrades (e.g. gift a workout class, book an expert session) to let customers customize their plan. In short, the easier you make it for customers to adjust their plan to fit their needs, the less likely they are to cancel entirely. Tracking trials and new sign-ups by plan type can also reveal which options are most appealing, so you can refine your offerings over time.

Proactively Engage Customers at Renewal and After Cancellation

Recurring Billing - Engage Customers

Don’t wait until a subscription lapses to reach out. As a subscriber’s term nears its end (or a free trial expires), engage them: send an email or notification checking in on their experience. Ask for feedback (“We hope you’re enjoying X. Can we do anything to improve your experience?”) and be ready to act on it. Offer a limited-time discount or bonus if they renew (e.g. “Renew now and get 10% off your next 3 months”).

Small gestures at renewal time can pay off: research shows 63% of subscribers will stay if given an attractive offer at renewal time​. Even after cancellation, keep the door open. Many customers return when their circumstances change or your offerings improve. In fact, studies find up to 20% of people who cancel a subscription reactivate it within six months​. They might come back with new pricing or added features. To capitalize on this, maintain a “win-back” campaign: add cancelled accounts to a nurture list and periodically send them updates on product news, special promotions, or changes they liked.

Also, make it easy to resubscribe (for example, by not deleting their account data immediately). Treat customer relationships as ongoing – check in with feedback surveys, loyalty rewards, and helpful content – and you’ll find many cancellations can turn into reactivations or positive reviews.

Leverage Automation, Analytics, and Smart Billing Tools

Use modern subscription management tools to automate the heavy lifting. A good recurring-billing platform can handle invoicing, payment collection, taxes, and compliance automatically. Look for systems with built-in analytics dashboards that track MRR (Monthly Recurring Revenue), churn, ARPU (average revenue per user), and other key metrics. These insights help you spot trends (e.g., which plan tiers lose customers) and make data-driven decisions. Many platforms now offer AI-driven features: for example, predictive analytics to identify accounts at risk of churning (based on usage patterns or payment history), enabling you to intervene early​.

Equally, automate your dunning workflows: send scheduled reminder emails or SMS for upcoming payments and failed charges. Personalize these messages – for instance, a gentle “Your subscription renews in 3 days” or “Your payment failed; update details here” – to recover more revenue. One platform’s data shows that targeted recovery emails can reclaim nearly 50% of failed payments, extending subscriber lifetimes by over four months​.

Finally, tie your billing system into marketing and CRM tools. When billing is integrated, you can trigger marketing campaigns (e.g. win-back offers) and personalize outreach based on subscription status. For example, if analytics show a segment of users is highly engaged but still on the basic plan, send them an upgrade offer. The combination of robust automation and constant measurement means you can fine-tune your strategy rapidly and focus on growth rather than manual billing chores.

Engage Customers and Build Loyalty

Even with automation, never underestimate the value of human-centered engagement. Use customer data to send personalized communications: birthday or anniversary discounts, usage tips, or thank-you notes for milestone renewals. Consider a loyalty or referral program that rewards long-term subscribers with perks (exclusive content, freebies, or credits). Engage subscribers outside the billing relationship too – for example, create a community (forums or social groups) or send newsletters featuring new features and how-tos.

As industry experts note, combining technology with a personal touch is most effective​. Use affordable marketing tools like email automation, chatbots, and analytics to stay in touch at scale, but complement them with real human interaction on critical accounts. When customers feel valued and part of a relationship (not just a number), they’re much more likely to stick around and even become advocates for your brand.

Conclusion

In 2025, maximizing recurring revenue means balancing solid technology with customer-centric strategies. By securing payments, offering flexible options, automating intelligently, and continuously engaging subscribers, you turn one-time buyers into loyal, long-term customers. Applying the tips above — updated for today’s market data and tools — will help your business capture more value from every subscriber and grow sustainably in the subscription economy.

Frequently Asked Questions

  1. What is recurring billing, and how can it grow my business?

    Recurring billing lets customers pay automatically on a set schedule. It creates steady cash flow, makes revenue easier to predict, and turns one-time buyers into long-term customers.

  2. What challenges should I expect when setting up recurring billing?

    You’ll need to manage renewals, promo expirations, and failed payments. Customer churn is common, so plan ahead with retention strategies and automated systems to reduce cancellations.

  3. How do I keep my recurring billing system secure and compliant?

    Use a PCI-compliant gateway, encrypt payment data, and store tokens securely. Add fraud tools like 3D Secure and clearly explain payment terms to protect both your business and your customers.

  4. Which payment methods should I offer for better results?

    Support cards, ACH/bank debits, and digital wallets like Apple Pay or Google Pay. Adding Buy Now, Pay Later can also increase sales and average order value.

  5. How can I reduce churn and keep subscribers longer?

    Let users pause their subscription instead of canceling, and run win-back campaigns with special offers. These small steps can lead to big gains in retention.