Author Archives: hostmerchantservices

digital payments for construction firms

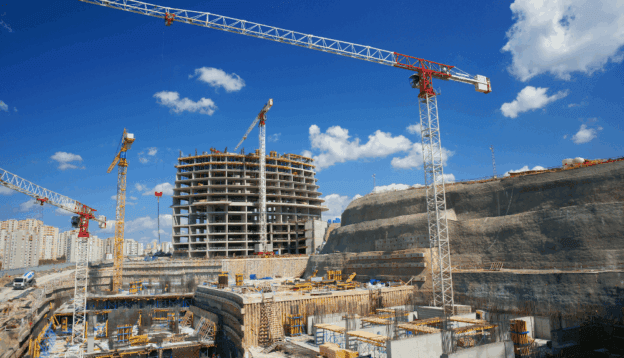
How Digital Payments Can Help Construction Firms Combat Housing Market Slowdown

The housing market slowdown, coupled with the pandemic’s impact on the construction industry’s cash flow and payment chain, has created a challenging situation for contractors. Many businesses are struggling to stay afloat as payment delays, supply chain disruptions, and rising materials prices make it difficult for them to keep up with their expenses.

However, there’s hope on the horizon. Construction firms are increasingly turning to digital payments to alleviate their cash flow headaches and ensure timely payments. We are witnessing a complete change in the construction industry in our analysis of the present and near future digital payment trends. In this article, we’ll explore how digital payments for construction firms can help combat the housing market slowdown and enhance their financial stability.

The State of Construction Payments

The State of Construction Payments

The construction industry has a significant impact on the economy, generating billions of dollars in revenue each year. However, despite its size and importance, the industry has long struggled with issues related to payments. The State of Construction Payments is an assessment of the current state of the industry regarding payments and the challenges that continue to hinder progress.

The construction industry is known for its complex payment process, which involves multiple parties, including contractors, subcontractors, suppliers, and owners. Each party has different responsibilities, timelines, and payment terms, which can lead to confusion and disputes. Additionally, delays in payments can have a significant impact on cash flow, making it difficult for contractors and suppliers to manage their finances and pay their own bills.

One of the main challenges in the construction industry is the prevalence of late payments. According to a report by the National Association of Credit Management, the construction industry has the highest rate of late payments compared to other industries. In fact, nearly 70% of construction companies report experiencing late payments, which can have a ripple effect throughout the industry. Late payments can lead to disputes, legal battles, and even bankruptcy for smaller businesses that are unable to manage cash flow.

Another challenge in the construction industry is the lack of transparency in payment processes. With so many parties involved, it can be difficult to keep track of payments and ensure that everyone is paid on time. The use of paper-based systems, such as checks and invoices, can also contribute to delays and errors. Additionally, some larger construction companies may intentionally delay payments in order to improve their own cash flow, leaving smaller contractors and suppliers in a difficult financial situation.

To address these challenges, the construction industry has been exploring various solutions, including electronic payments and technology-based platforms. Electronic payments can help streamline the payment process and reduce delays by enabling direct transfer of funds between parties. Technology-based platforms, such as construction management software, can also help improve transparency and reduce errors by providing a centralized platform for communication and documentation.

In addition, some states and countries have implemented legislation to protect contractors and suppliers from late payments. For example, in the United States, several states have enacted prompt payment laws, which require contractors to pay subcontractors and suppliers within a certain time frame. These laws can help improve cash flow and reduce disputes, but they can also place additional administrative burdens on contractors and lead to increased costs.

The State of Construction Payments remains a challenging issue for the industry. Late payments, lack of transparency, and disputes continue to hinder progress and impact cash flow for businesses of all sizes. However, with the adoption of technology-based solutions and the implementation of legislation to protect smaller contractors and suppliers, there is hope that the industry can move towards a more efficient and equitable payment system.

Digital Payments For Construction Firms – A Solution That Matters

digital payment for construction companies

Digital payments have emerged as a game-changing solution for the construction industry to combat the housing market slowdown. The global construction industry is one of the largest contributors to the economy, accounting for approximately 7% of the world’s GDP. However, it faces several challenges, including delayed payments, rising costs, and project delays. In recent years, digital payments have become an integral part of the construction industry, and they offer several advantages over traditional payment methods.

Digital payments involve the use of electronic payment systems that enable companies to make and receive payments electronically, without the need for cash or paper checks. These payment systems use a variety of technologies, including mobile payments, online payments, and electronic funds transfers. By adopting digital payments, construction firms can benefit in several ways.

Firstly, digital payments are faster and more secure than traditional payment methods. With digital payments, construction firms can process payments instantly, eliminating the need for paper checks and manual processing. This reduces the time it takes to receive payments, which is a significant issue for construction firms, who often have to wait for long periods before receiving payments from clients. Digital payments also offer enhanced security features, such as encryption, which ensures that transactions are secure and protected against fraud.

Secondly, digital payments are more cost-effective than traditional payment methods. By eliminating the need for paper checks, construction firms can reduce their transaction costs significantly. Moreover, digital payments are often offered at lower transaction fees, further reducing costs for construction firms.

Thirdly, digital payments provide greater transparency and accountability. Construction firms can use digital payments to track their transactions in real-time, providing them with a clear view of their cash flow and enabling them to manage their finances more effectively. Moreover, digital payments enable construction firms to maintain a digital record of all their transactions, which can be used for auditing and compliance purposes.

Finally, digital payments offer greater convenience and flexibility. Construction firms can use digital payments to make payments from anywhere, at any time, using a variety of devices, including smartphones, laptops, and tablets. This enables construction firms to manage their finances more efficiently, and it also makes it easier for them to pay their suppliers and subcontractors, who may be located in different parts of the world.

In the context of the housing market slowdown, digital payments can play a vital role in helping construction firms manage their finances more effectively. By reducing transaction costs, improving cash flow, and enhancing transparency and accountability, digital payments can help construction firms overcome the challenges of delayed payments, rising costs, and project delays. Moreover, digital payments can help construction firms stay competitive by enabling them to offer more flexible and convenient payment options to their clients.

Digital payments have become an essential tool for the construction industry to combat the challenges posed by the housing market slowdown. By offering faster, more secure, and cost-effective payment options, digital payments can help construction firms manage their finances more effectively, enabling them to complete projects on time and within budget. In the years to come, digital payments are likely to become even more widespread in the construction industry, as firms look to adopt new technologies to improve their operations and stay competitive in an increasingly challenging market.

Payment Speed Correlates with Project Type

Payment Speed Correlates with Project Type

In the construction industry, payment speed is a crucial factor for the successful completion of projects. However, payment speed can vary depending on the type of project, and it is essential to understand the correlation between payment speed and project type to improve payment processes and prevent delays.

Construction projects can be broadly categorized into three types: residential, commercial, and infrastructure. Each project type has its unique characteristics, and payment speed can differ depending on these characteristics. For instance, residential projects are typically smaller in scope and involve fewer stakeholders, making it easier to process payments quickly. In contrast, commercial and infrastructure projects are more complex and involve several stakeholders, making payment processing more time-consuming.

Residential construction projects involve the building of houses, apartments, and other types of residential properties. Payment speed for residential construction projects is relatively faster compared to commercial and infrastructure projects. The reason for this is that residential construction projects typically involve fewer stakeholders, such as architects, engineers, and contractors. As a result, the payment processing cycle is shorter, and payments are usually made quickly. Additionally, residential projects tend to be smaller in scale, which means there are fewer transactions to process, leading to faster payment processing times.

Commercial construction projects are typically larger in scale and involve more stakeholders than residential projects. Commercial projects can include buildings such as offices, hotels, and shopping centers. In these projects, payment processing can be more complicated as the transactions involved are more significant, and there are more parties involved. The payment cycle can also be longer as each stakeholder may have different terms and conditions for payment. The complexity of the payment process can lead to delays, which can impact the progress of the project.

Infrastructure projects include the construction of highways, bridges, airports, and other large public projects. These projects involve multiple stakeholders, including government agencies, contractors, and subcontractors. Payment processing for infrastructure projects is often slower than other project types due to the extensive bureaucracy involved. There are also more regulations and approvals needed before payments can be processed. Infrastructure projects also tend to be funded by the government, which can lead to delays in payments due to budget constraints and other bureaucratic processes.

The digitalization of payment processes can help mitigate some of the challenges associated with slow payment processing in construction projects. Digital payments can speed up payment processing times, improve accuracy, and reduce errors in payment processing. By digitizing payments, all stakeholders can access payment information in real-time, and transactions can be processed faster.

Digital payments can also help improve transparency in the payment process, reducing the likelihood of disputes or misunderstandings between stakeholders. The use of digital payments can also help improve communication and collaboration between stakeholders, which can further reduce the likelihood of delays.

Conclusion

Construction firms are facing significant challenges in the wake of the pandemic, including supply chain disruptions, rising materials prices, and payment delays. However, the industry is adapting to the changing landscape by embracing digital payments, preliminary notices, and mechanics liens to ensure timely payments.

Digital payments can help construction firms combat the housing market slowdown and enhance their financial stability. By adopting technology and automating their payment processes, contractors can reduce the time and effort they put into chasing payments, freeing up resources to focus on growth and innovation.

Top SaaS Companies in 2023

Top SaaS Companies to Watch in 2023

SaaS companies are changing the way businesses operate. With the rise of cloud computing, these companies offer software solutions that can be accessed from anywhere, anytime. This has led to increased flexibility, scalability, and cost-effectiveness for businesses of all sizes. In 2023, we can expect to see more SaaS companies emerge and existing ones continue to innovate. Let us look at the top SaaS companies in 2023 to watch closely.

Top SaaS Companies in 2023

Zoom

Company Overview

Zoom Video Communications, Inc. is a publicly-traded company headquartered in San Jose, California. It was founded by Eric Yuan, a former Cisco WebEx engineer, who wanted to create a video conferencing platform that was easy to use and reliable. Zoom’s mission is to make video communications frictionless.

Products and Services

Zoom offers a variety of products and services to meet the needs of individuals, businesses, and organizations of all sizes. Some of their main products include:

Zoom Meetings: a video conferencing solution for virtual meetings, webinars, and conference calls.

Zoom Rooms: a software-based conference room solution that enables users to join Zoom meetings from conference rooms.

Zoom Phone: a cloud-based phone system that enables users to make and receive calls over the internet.

Zoom Video Webinars: a solution for hosting virtual events such as webinars, virtual conferences, and town hall meetings.

In addition to these products, Zoom also offers various features and add-ons such as recording, virtual backgrounds, and integrations with other software applications.

Target Market

Zoom’s target market includes individuals, businesses, and organizations of all sizes who are in need of a reliable and user-friendly video conferencing solution. Zoom’s platform is suitable for a wide range of industries, including education, healthcare, finance, government, and more. With the COVID-19 pandemic causing a massive shift towards remote work and virtual meetings, Zoom has seen a significant increase in demand for its services.

Business Model

Zoom’s business model is based on a freemium pricing model, which means that they offer a basic version of their platform for free and charge a fee for additional features and add-ons. The free version of Zoom includes features such as unlimited one-on-one meetings and group meetings of up to 100 participants with a 40-minute time limit. Paid plans start at $14.99 per month per host and include features such as longer meeting durations, more participants, and additional administrative controls.

Funding

Zoom has raised over $1 billion in funding since its founding in 2011. In April 2019, Zoom went public on the NASDAQ stock exchange with an initial public offering (IPO) price of $36 per share. Since then, Zoom’s stock price has soared, and as of March 2023, it is trading at over $300 per share.

Interesting Points about the Brand

Zoom’s founder and CEO, Eric Yuan, was once a Cisco WebEx engineer who quit his job to start Zoom after being frustrated with the limitations of existing video conferencing solutions.

Zoom was initially launched as a B2B solution but has since expanded to include B2C offerings such as the free version of Zoom and Zoom for Home.

Zoom has faced some criticism for privacy and security concerns, particularly in 2020 when the platform experienced a surge in usage due to the COVID-19 pandemic. However, the company has taken steps to address these concerns and improve its security features.

Zoom has been recognized as one of the best places to work in the Bay Area, and it has won numerous awards for its culture and employee satisfaction

Wrike

Company Overview

Wrike is a software-as-a-service (SaaS) company that was founded in 2006 by Andrew Filev. The company is headquartered in San Jose, California, and has offices in several countries, including Ireland, Ukraine, and Russia. Since its inception, Wrike has grown rapidly, and today it has more than 20,000 customers worldwide. The company’s mission is to help teams work smarter, not harder, by providing them with a single platform to manage their projects, collaborate, and communicate.

Products and Services

Wrike’s flagship product is its project management and collaboration software. The software is cloud-based and is designed to help teams of all sizes manage their projects more efficiently. Some of the key features of Wrike’s software include task management, team collaboration, time tracking, customizable workflows, and project reporting. The software is also highly customizable and can be tailored to meet the specific needs of individual teams and organizations.

In addition to its project management software, Wrike also offers a range of other products and services, including:

Wrike for Marketers: A tailored solution designed specifically for marketing teams, which includes features like digital asset management, request forms, and proofing and approval workflows.

Wrike for Professional Services: A solution designed for service-based businesses, which includes features like resource management, project accounting, and billing and invoicing.

Wrike Analyze: A business intelligence tool that provides insights into project performance, team productivity, and resource utilization.

Target Market

Wrike’s software is designed to meet the needs of teams and organizations of all sizes and across a range of industries. The company’s target market includes:

Small and medium-sized businesses (SMBs) looking for a cost-effective project management solution.

Large enterprises that need a scalable, customizable project management solution.

Marketing teams that need a solution tailored to their specific needs.

Service-based businesses that need a solution for managing projects and resources.

Business Model

Wrike operates on a subscription-based business model, where customers pay a monthly or annual fee for access to its software. The company offers a range of pricing plans to suit the needs of different teams and organizations. Wrike’s pricing plans are based on the number of users and the features included in the plan. The company also offers a free trial of its software, which allows customers to test the software before making a purchase.

Funding

Since its inception, Wrike has raised over $25 million in funding. The company’s most recent funding round was in 2018, where it raised $10 million in a series D funding round led by Bain Capital Ventures. The funding was used to expand the company’s product offerings and accelerate its growth.

Interesting Points about the Brand

Here are some interesting points about Wrike that make it stand out from other SaaS companies:

Wrike was named one of the fastest-growing companies in North America by Deloitte in 2019.

The company has won several awards for its software, including the 2019 SaaS Award for Best Project Management Software and the 2020 Trust Radius Award for Best Customer Support.

Wrike has a strong focus on security and privacy. The company is SOC 2 compliant and has multiple security certifications, including ISO 27001 and GDPR.

The company has a strong commitment to sustainability and has implemented several initiatives to reduce its carbon footprint. These include using renewable energy sources, reducing waste, and promoting eco-friendly practices.

Wrike is a top SaaS company to watch out for in 2023. With its innovative software solutions, strong focus on customer satisfaction, and commitment to sustainability, Wrike is poised for continued success in the years to come.

Stripe

Company Overview

Stripe was founded in 2010 by brothers John and Patrick Collison, who grew up in rural Ireland and taught themselves to code at a young age. After selling their first company, Auctomatic, in 2008, they decided to start Stripe to solve the problem of online payments. Since then, Stripe has grown into one of the largest and most successful fintech companies in the world. The company is headquartered in San Francisco, California, and has offices in several other countries, including the UK, Ireland, Singapore, and Australia.

Products and Services

Stripe offers a range of online payment solutions for businesses, including:

Payments

Stripe’s Payments product allows businesses to accept payments from customers anywhere in the world, in more than 135 different currencies. Payments can be made using credit and debit cards, Apple Pay, Google Pay, and other popular payment methods.

Billing

Stripe’s Billing product allows businesses to create and manage subscriptions, send invoices, and handle other billing-related tasks in a streamlined and automated way.

Connect

Stripe’s Connect product allows businesses to build and manage online marketplaces, where buyers and sellers can transact securely and easily. Connect handles all of the complicated payment and regulatory issues that come with building a marketplace, so businesses can focus on building their product and growing their user base.

Radar

Stripe’s Radar product uses machine learning to help businesses detect and prevent fraud. Radar analyzes billions of data points to identify fraudulent activity, and can be customized to suit the specific needs of each business.

Target Market

Stripe’s target market is primarily small to medium-sized businesses that sell goods or services online. The company’s easy-to-use payment solutions, flexible APIs, and robust developer tools make it an attractive option for businesses of all sizes, from independent freelancers to large enterprise companies.

Business Model

Stripe’s business model is based on taking a small percentage of each transaction processed through its platform. The company charges a standard fee of 2.9% + 30¢ per successful transaction, with no additional monthly or setup fees. This pricing model makes Stripe an affordable option for businesses of all sizes, while still allowing the company to generate significant revenue.

Funding

Stripe has raised more than $2 billion in funding since its founding, from some of the world’s most prominent venture capital firms, including Sequoia Capital, Andreessen Horowitz, and General Catalyst. In March 2021, Stripe raised $600 million in a funding round that valued the company at $95 billion, making it one of the most valuable startups in the world.

Interesting Points about the Brand

Here are a few interesting points that make Stripe stand out as a top Saas company to watch out for in 2023:

Developer-friendly

Stripe is known for its developer-friendly APIs and robust set of tools for building custom payment solutions. This has made the company a favorite among developers and has helped to fuel its rapid growth.

Global reach

Stripe’s platform supports payments in more than 135 different currencies, making it an attractive option for businesses that operate globally. The company also has offices in several countries, including the UK, Ireland, and Australia.

Slack

Company Overview

Slack was founded in 2013 by Stewart Butterfield, who previously co-founded Flickr. The company is headquartered in San Francisco, California, and has additional offices in New York, Dublin, Vancouver, Tokyo, and Melbourne. Slack’s mission is to make people’s working lives simpler, more pleasant, and more productive.

Slack’s platform allows teams to collaborate and communicate through channels, direct messaging, and integrations with other tools. The platform offers features such as file sharing, video and voice calls, and custom app integrations. Slack has over 12 million daily active users as of 2023, and the company has been valued at over $23 billion.

Products and Services

Slack’s main product is its messaging platform, which allows teams to communicate and collaborate effectively. The platform offers features such as channels, direct messaging, video and voice calls, and file sharing. Slack also offers a variety of integrations with other tools, such as Google Drive, Trello, and Salesforce.

In addition to its messaging platform, Slack also offers a range of enterprise-level features for larger organizations, such as enterprise mobility management, security and compliance features, and enterprise grid for larger deployments.

Target Market

Slack’s target market is primarily teams and organizations of all sizes that require an efficient way to communicate and collaborate. The company has a strong presence in the technology industry, with customers such as Airbnb, Lyft, and Shopify. However, Slack has also gained popularity in other industries, such as finance, healthcare, and education.

Business Model

Slack operates on a freemium business model, which allows users to use the platform for free with limited features. The company generates revenue through its paid plans, which offer additional features such as unlimited message history, group voice and video calls, and priority support.

Slack’s paid plans are priced per user per month, with pricing ranging from $6.67 per user per month for the standard plan, to $15 per user per month for the plus plan. The company also offers enterprise-level features, which are priced on a case-by-case basis.

Funding

Slack has raised over $1.4 billion in funding to date. The company’s most recent funding round was in 2019, where it raised $427 million at a valuation of $7.1 billion. Notable investors in Slack include SoftBank, Accel, and Andreessen Horowitz.

Interesting Points about the Brand

Slack was originally developed as an internal tool for Stewart Butterfield’s game development company, Tiny Speck.

The name “Slack” is an acronym for “Searchable Log of All Conversation and Knowledge”.

Slack’s logo features a hashtag symbol, which has become synonymous with the company.

Slack has a strong culture of remote work, with over 70% of its employees working remotely.

In 2020, Slack was acquired by Salesforce for $27.7 billion, marking one of the largest tech acquisitions in history.

Atlassian

Company Overview

Atlassian was founded in 2002 in Sydney, Australia by Mike Cannon-Brookes and Scott Farquhar. The company started as a small software consulting business, but it has grown into a global leader in the software industry. Atlassian’s mission is to unleash the potential of every team, and its products and services are designed to help teams work better together.

Products and Services

Atlassian offers a wide range of products and services, including:

Jira Software

Jira Software is a project management tool that helps teams plan, track, and release software.

Confluence

Confluence is a team collaboration tool that helps teams create, organize, and share knowledge.

Trello

Trello is a visual collaboration tool that helps teams organize and prioritize their work.

Bitbucket

Bitbucket is a code collaboration tool that helps teams build, test, and deploy their code.

Jira Service Desk

Jira Service Desk is a service management tool that helps teams provide great service to their customers.

Target Market

Atlassian’s products and services are designed for teams of all sizes and industries. Its customers range from small startups to large enterprises. Atlassian’s focus is on helping teams work better together, regardless of their industry or size.

Business Model

Atlassian’s business model is based on a subscription-based model. Customers pay a monthly or annual fee to use Atlassian’s products and services. Atlassian also offers a free trial of its products and services, which allows customers to try them out before committing to a subscription.

Funding

Atlassian is a publicly traded company on the NASDAQ stock exchange under the ticker symbol TEAM. The company went public in 2015 and raised $462 million in its initial public offering (IPO).

Interesting Points about the Brand

Here are some interesting points about the Atlassian brand:

Work Culture

Atlassian is known for its unique work culture. The company has a “no bullshit” policy, which encourages employees to speak their minds and be honest with each other.

Collaboration

Atlassian’s products and services are designed to promote collaboration among teams. The company also promotes collaboration internally, with its employees working in open-plan offices and using tools like HipChat to communicate with each other.

Corporate Social Responsibility

Atlassian is committed to being a socially responsible company. The company has a program called “Atlassian Foundation,” which supports nonprofit organizations around the world.

Innovation

Atlassian is constantly innovating and releasing new products and services. The company is also known for its innovation in the workplace, with its “ShipIt Days” allowing employees to work on innovative projects outside of their usual work.

Customer Satisfaction

Atlassian is committed to providing great customer service. The company has a Net Promoter Score (NPS) of 71, which is considered to be excellent.

HubSpot

Company Overview

Hubspot was founded in 2006 by Brian Halligan and Dharmesh Shah, and it’s headquartered in Cambridge, Massachusetts. The company’s mission is to help businesses grow better, and they do this by providing a suite of software tools that enable companies to attract, engage, and delight customers.

Products and Services

Hubspot’s product suite is divided into four main categories: marketing, sales, service, and CRM. In the marketing category, Hubspot offers tools for content management, social media, SEO, email marketing, advertising, and analytics. The sales category includes tools for sales automation, pipeline management, and contact management. The service category provides tools for customer service and support, including a help desk and knowledge base. The CRM category ties everything together, providing a unified view of customer interactions across all channels.

Target Market

Hubspot’s target market is primarily small to medium-sized businesses (SMBs) that are looking for an all-in-one software solution to manage their marketing, sales, and customer service. However, the company has been expanding its offerings to include larger enterprises as well.

Business Model

Hubspot’s business model is subscription-based, with customers paying a monthly fee for access to the software. The company also offers add-on services, such as consulting and training, which generate additional revenue.

Funding

Hubspot has raised over $1 billion in funding since its inception, with its most recent funding round in 2021 raising $175 million. The company went public in 2014 and is traded on the New York Stock Exchange under the symbol HUBS.

Interesting Points about the Brand

Hubspot has a strong focus on inbound marketing, which emphasizes attracting customers through content and experiences rather than interruptive advertising.

The company has a robust community of users and partners, with over 100,000 customers and 3,000 agency partners worldwide.

Hubspot has a strong commitment to sustainability, with initiatives such as carbon neutrality and a focus on reducing waste.

Hubspot is a top Saas company to watch out for in 2023 due to its innovative product suite, commitment to customer success, and strong financial backing. As businesses continue to seek all-in-one solutions to manage their operations, Hubspot is well-positioned to meet this demand and continue its growth trajectory.

Asana

Company Overview

Asana is a privately held company that provides a cloud-based project management software platform for individuals and teams to track and manage their work. The platform offers various features, including task management, project tracking, team collaboration, and reporting. Asana’s platform can be accessed through a web application or a mobile app, and it offers integrations with various third-party apps, including Google Drive, Slack, and Dropbox.

Products and Services

Asana offers a range of products and services to help individuals and teams manage their work efficiently. Some of its notable products and services include:

Asana Work Graph

Asana’s Work Graph is a proprietary technology that powers its platform, allowing individuals and teams to track and manage their work effectively. It is a data architecture that organizes and connects all the work that happens within an organization, including tasks, projects, people, and data.

Asana Premium

Asana Premium is a paid version of the platform that offers advanced features such as custom fields, project portfolios, and admin controls. The Premium version is designed for larger teams or organizations that require more complex project management capabilities.

Asana Business

Asana Business is a higher-tier subscription service that offers advanced security features and priority support. The Business version is designed for organizations that require a higher level of security and compliance.

Target Market

Asana targets a broad market of individuals and teams who need to manage their work effectively. Its platform is suitable for a range of industries, including marketing, design, engineering, and project management. Asana’s target market includes small enterprises that require a scalable and flexible project management solution.

Business Model

Asana’s business model is based on a subscription-based SaaS model. The company offers a free version of its platform, which includes basic project management features. It also offers paid versions of its platform with more advanced features, such as Asana Premium and Asana Business. Asana’s revenue is generated primarily from its paid subscription services.

Funding

Since its founding in 2008, Asana has raised over $200 million in funding. Its investors include some of the leading venture capital firms, including Benchmark Capital, Founders Fund, and 8VC. In 2018, Asana raised $75 million in a funding round led by Generation Investment Management, bringing the company’s valuation to over $1.5 billion.

Interesting Points about the Brand

Asana has several interesting points that make it stand out in the SaaS industry. Here are a few notable points:

Dustin Moskovitz, one of Asana’s co-founders, was also a co-founder of Facebook. He left Facebook in 2008 to start Asana.

Asana’s Work Graph is a proprietary technology that sets it apart from other project management software providers. It offers a unique approach to managing work by connecting all aspects of a project in one place.

Asana’s platform is highly customizable, allowing teams to create custom workflows, fields, and templates. This makes it a flexible solution for teams with unique project management needs.

Asana’s platform integrates with over 100 third-party apps, making it a versatile tool for managing work across various platforms and applications.

Top SaaS Companies to Watch in 2023

SaaS companies are changing the way businesses operate. With the rise of cloud computing, these companies offer software solutions that can be accessed from anywhere, anytime. This has led to increased flexibility, scalability, and cost-effectiveness for businesses of all sizes. In 2023, we can expect to see more SaaS companies emerge and existing ones continue to innovate. Let’s take a look at 10 SaaS companies that are making moves in 2023.

Top SaaS Companies to Watch in 2023

============================

Zoom

Zoom is a cloud-based video conferencing platform that enables users to host virtual meetings, webinars, and conference calls. Founded in 2011, Zoom has become one of the most popular video conferencing software in the world, with over 300 million daily meeting participants in 2020. Zoom’s success can be attributed to its user-friendly interface, reliability, and scalability. In this article, we will dive into the details of Zoom’s company overview, products and services, target market, business model, funding, and interesting points about the brand.

Company Overview

Zoom Video Communications, Inc. is a publicly-traded company headquartered in San Jose, California. It was founded by Eric Yuan, a former Cisco WebEx engineer, who wanted to create a video conferencing platform that was easy to use and reliable. Zoom’s mission is to make video communications frictionless.

Products and Services

Zoom offers a variety of products and services to meet the needs of individuals, businesses, and organizations of all sizes. Some of their main products include:

Zoom Meetings: a video conferencing solution for virtual meetings, webinars, and conference calls.

Zoom Rooms: a software-based conference room solution that enables users to join Zoom meetings from conference rooms.

Zoom Phone: a cloud-based phone system that enables users to make and receive calls over the internet.

Zoom Video Webinars: a solution for hosting virtual events such as webinars, virtual conferences, and town hall meetings.

In addition to these products, Zoom also offers various features and add-ons such as recording, virtual backgrounds, and integrations with other software applications.

Target Market

Zoom’s target market includes individuals, businesses, and organizations of all sizes who are in need of a reliable and user-friendly video conferencing solution. Zoom’s platform is suitable for a wide range of industries, including education, healthcare, finance, government, and more. With the COVID-19 pandemic causing a massive shift towards remote work and virtual meetings, Zoom has seen a significant increase in demand for its services.

Business Model

Zoom’s business model is based on a freemium pricing model, which means that they offer a basic version of their platform for free and charge a fee for additional features and add-ons. The free version of Zoom includes features such as unlimited one-on-one meetings and group meetings of up to 100 participants with a 40-minute time limit. Paid plans start at $14.99 per month per host and include features such as longer meeting durations, more participants, and additional administrative controls.

Funding

Zoom has raised over $1 billion in funding since its founding in 2011. In April 2019, Zoom went public on the NASDAQ stock exchange with an initial public offering (IPO) price of $36 per share. Since then, Zoom’s stock price has soared, and as of March 2023, it is trading at over $300 per share.

Interesting Points about the Brand

Zoom’s founder and CEO, Eric Yuan, was once a Cisco WebEx engineer who quit his job to start Zoom after being frustrated with the limitations of existing video conferencing solutions.

Zoom was initially launched as a B2B solution but has since expanded to include B2C offerings such as the free version of Zoom and Zoom for Home.

Zoom has faced some criticism for privacy and security concerns, particularly in 2020 when the platform experienced a surge in usage due to the COVID-19 pandemic. However, the company has taken steps to address these concerns and improve its security features.

Zoom has been recognized as one of the best places to work in the Bay Area, and it has won numerous awards for its culture and employee satisfaction

==============================

Wrike

In today’s fast-paced business world, SaaS companies are quickly becoming the go-to choice for many organizations. These companies offer software solutions that are cost-effective, easy to use, and scalable. Among the top SaaS companies to watch out for in 2023 is Wrike. Wrike is a cloud-based project management and collaboration software that helps businesses streamline their operations and improve productivity. In this article, we will take a closer look at Wrike, including its company overview, products and services, target market, business model, funding, and some interesting points about the brand.

Company Overview

Wrike is a software-as-a-service (SaaS) company that was founded in 2006 by Andrew Filev. The company is headquartered in San Jose, California, and has offices in several countries, including Ireland, Ukraine, and Russia. Since its inception, Wrike has grown rapidly, and today it has more than 20,000 customers worldwide. The company’s mission is to help teams work smarter, not harder, by providing them with a single platform to manage their projects, collaborate, and communicate.

Products and Services

Wrike’s flagship product is its project management and collaboration software. The software is cloud-based and is designed to help teams of all sizes manage their projects more efficiently. Some of the key features of Wrike’s software include task management, team collaboration, time tracking, customizable workflows, and project reporting. The software is also highly customizable and can be tailored to meet the specific needs of individual teams and organizations.

In addition to its project management software, Wrike also offers a range of other products and services, including:

Wrike for Marketers: A tailored solution designed specifically for marketing teams, which includes features like digital asset management, request forms, and proofing and approval workflows.

Wrike for Professional Services: A solution designed for service-based businesses, which includes features like resource management, project accounting, and billing and invoicing.

Wrike Analyze: A business intelligence tool that provides insights into project performance, team productivity, and resource utilization.

Target Market

Wrike’s software is designed to meet the needs of teams and organizations of all sizes and across a range of industries. The company’s target market includes:

Small and medium-sized businesses (SMBs) looking for a cost-effective project management solution.

Large enterprises that need a scalable, customizable project management solution.

Marketing teams that need a solution tailored to their specific needs.

Service-based businesses that need a solution for managing projects and resources.

Business Model

Wrike operates on a subscription-based business model, where customers pay a monthly or annual fee for access to its software. The company offers a range of pricing plans to suit the needs of different teams and organizations. Wrike’s pricing plans are based on the number of users and the features included in the plan. The company also offers a free trial of its software, which allows customers to test the software before making a purchase.

Funding

Since its inception, Wrike has raised over $25 million in funding. The company’s most recent funding round was in 2018, where it raised $10 million in a series D funding round led by Bain Capital Ventures. The funding was used to expand the company’s product offerings and accelerate its growth.

Interesting Points about the Brand

Here are some interesting points about Wrike that make it stand out from other SaaS companies:

Wrike was named one of the fastest-growing companies in North America by Deloitte in 2019.

The company has won several awards for its software, including the 2019 SaaS Award for Best Project Management Software and the 2020 Trust Radius Award for Best Customer Support.

Wrike has a strong focus on security and privacy. The company is SOC 2 compliant and has multiple security certifications, including ISO 27001 and GDPR.

The company has a strong commitment to sustainability and has implemented several initiatives to reduce its carbon footprint. These include using renewable energy sources, reducing waste, and promoting eco-friendly practices.

Overall, Wrike is a top SaaS company to watch out for in 2023. With its innovative software solutions, strong focus on customer satisfaction, and commitment to sustainability, Wrike is poised for continued success in the years to come.

==========================

Stripe

Stripe is a Silicon Valley-based financial technology company founded in 2010 that offers a variety of online payment solutions for businesses of all sizes. The company has rapidly become one of the most successful startups in the world, with a valuation of over $95 billion as of 2022. In this article, we’ll delve deeper into Stripe’s products and services, target market, business model, funding, and other interesting points about the brand that make it a top Saas company to watch out for in 2023.

Company Overview

Stripe was founded in 2010 by brothers John and Patrick Collison, who grew up in rural Ireland and taught themselves to code at a young age. After selling their first company, Auctomatic, in 2008, they decided to start Stripe to solve the problem of online payments. Since then, Stripe has grown into one of the largest and most successful fintech companies in the world. The company is headquartered in San Francisco, California, and has offices in several other countries, including the UK, Ireland, Singapore, and Australia.

Products and Services

Stripe offers a range of online payment solutions for businesses, including:

Payments

Stripe’s Payments product allows businesses to accept payments from customers anywhere in the world, in more than 135 different currencies. Payments can be made using credit and debit cards, Apple Pay, Google Pay, and other popular payment methods.

Billing

Stripe’s Billing product allows businesses to create and manage subscriptions, send invoices, and handle other billing-related tasks in a streamlined and automated way.

Connect

Stripe’s Connect product allows businesses to build and manage online marketplaces, where buyers and sellers can transact securely and easily. Connect handles all of the complicated payment and regulatory issues that come with building a marketplace, so businesses can focus on building their product and growing their user base.

Radar

Stripe’s Radar product uses machine learning to help businesses detect and prevent fraud. Radar analyzes billions of data points to identify fraudulent activity, and can be customized to suit the specific needs of each business.

Target Market

Stripe’s target market is primarily small to medium-sized businesses that sell goods or services online. The company’s easy-to-use payment solutions, flexible APIs, and robust developer tools make it an attractive option for businesses of all sizes, from independent freelancers to large enterprise companies.

Business Model

Stripe’s business model is based on taking a small percentage of each transaction processed through its platform. The company charges a standard fee of 2.9% + 30¢ per successful transaction, with no additional monthly or setup fees. This pricing model makes Stripe an affordable option for businesses of all sizes, while still allowing the company to generate significant revenue.

Funding

Stripe has raised more than $2 billion in funding since its founding, from some of the world’s most prominent venture capital firms, including Sequoia Capital, Andreessen Horowitz, and General Catalyst. In March 2021, Stripe raised $600 million in a funding round that valued the company at $95 billion, making it one of the most valuable startups in the world.

Interesting Points about the Brand

Here are a few interesting points that make Stripe stand out as a top Saas company to watch out for in 2023:

Developer-friendly

Stripe is known for its developer-friendly APIs and robust set of tools for building custom payment solutions. This has made the company a favorite among developers and has helped to fuel its rapid growth.

Global reach

Stripe’s platform supports payments in more than 135 different currencies, making it an attractive option for businesses that operate globally. The company also has offices in several countries, including the UK, Ireland, and Australia.

——————————————–

Slack

Slack is a software-as-a-service (SaaS) company that provides a messaging platform for teams to collaborate and communicate effectively. The company has gained significant popularity in recent years, and as we move into 2023, it remains one of the top SaaS companies to watch out for. In this article, we will explore Slack’s company overview, products and services, target market, business model, funding, and interesting points about the brand.

Company Overview

Slack was founded in 2013 by Stewart Butterfield, who previously co-founded Flickr. The company is headquartered in San Francisco, California, and has additional offices in New York, Dublin, Vancouver, Tokyo, and Melbourne. Slack’s mission is to make people’s working lives simpler, more pleasant, and more productive.

Slack’s platform allows teams to collaborate and communicate through channels, direct messaging, and integrations with other tools. The platform offers features such as file sharing, video and voice calls, and custom app integrations. Slack has over 12 million daily active users as of 2023, and the company has been valued at over $23 billion.

Products and Services

Slack’s main product is its messaging platform, which allows teams to communicate and collaborate effectively. The platform offers features such as channels, direct messaging, video and voice calls, and file sharing. Slack also offers a variety of integrations with other tools, such as Google Drive, Trello, and Salesforce.

In addition to its messaging platform, Slack also offers a range of enterprise-level features for larger organizations, such as enterprise mobility management, security and compliance features, and enterprise grid for larger deployments.

Target Market

Slack’s target market is primarily teams and organizations of all sizes that require an efficient way to communicate and collaborate. The company has a strong presence in the technology industry, with customers such as Airbnb, Lyft, and Shopify. However, Slack has also gained popularity in other industries, such as finance, healthcare, and education.

Business Model

Slack operates on a freemium business model, which allows users to use the platform for free with limited features. The company generates revenue through its paid plans, which offer additional features such as unlimited message history, group voice and video calls, and priority support.

Slack’s paid plans are priced per user per month, with pricing ranging from $6.67 per user per month for the standard plan, to $15 per user per month for the plus plan. The company also offers enterprise-level features, which are priced on a case-by-case basis.

Funding

Slack has raised over $1.4 billion in funding to date. The company’s most recent funding round was in 2019, where it raised $427 million at a valuation of $7.1 billion. Notable investors in Slack include SoftBank, Accel, and Andreessen Horowitz.

Interesting Points about the Brand

Slack was originally developed as an internal tool for Stewart Butterfield’s game development company, Tiny Speck.

The name “Slack” is an acronym for “Searchable Log of All Conversation and Knowledge”.

Slack’s logo features a hashtag symbol, which has become synonymous with the company.

Slack has a strong culture of remote work, with over 70% of its employees working remotely.

In 2020, Slack was acquired by Salesforce for $27.7 billion, marking one of the largest tech acquisitions in history.

——————————–

Atlassian

In the world of technology, software as a service (SaaS) has become a popular delivery model for software applications. One of the top SaaS companies to watch out for in 2023 is Atlassian. This article will provide an overview of Atlassian, its products and services, target market, business model, funding, and interesting points about the brand.

Company Overview

Atlassian was founded in 2002 in Sydney, Australia by Mike Cannon-Brookes and Scott Farquhar. The company started as a small software consulting business, but it has grown into a global leader in the software industry. Atlassian’s mission is to unleash the potential of every team, and its products and services are designed to help teams work better together.

Products and Services

Atlassian offers a wide range of products and services, including:

Jira Software

Jira Software is a project management tool that helps teams plan, track, and release software.

Confluence

Confluence is a team collaboration tool that helps teams create, organize, and share knowledge.

Trello

Trello is a visual collaboration tool that helps teams organize and prioritize their work.

Bitbucket

Bitbucket is a code collaboration tool that helps teams build, test, and deploy their code.

Jira Service Desk

Jira Service Desk is a service management tool that helps teams provide great service to their customers.

Target Market

Atlassian’s products and services are designed for teams of all sizes and industries. Its customers range from small startups to large enterprises. Atlassian’s focus is on helping teams work better together, regardless of their industry or size.

Business Model

Atlassian’s business model is based on a subscription-based model. Customers pay a monthly or annual fee to use Atlassian’s products and services. Atlassian also offers a free trial of its products and services, which allows customers to try them out before committing to a subscription.

Funding

Atlassian is a publicly traded company on the NASDAQ stock exchange under the ticker symbol TEAM. The company went public in 2015 and raised $462 million in its initial public offering (IPO).

Interesting Points about the Brand

Here are some interesting points about the Atlassian brand:

Work Culture

Atlassian is known for its unique work culture. The company has a “no bullshit” policy, which encourages employees to speak their minds and be honest with each other.

Collaboration

Atlassian’s products and services are designed to promote collaboration among teams. The company also promotes collaboration internally, with its employees working in open-plan offices and using tools like HipChat to communicate with each other.

Corporate Social Responsibility

Atlassian is committed to being a socially responsible company. The company has a program called “Atlassian Foundation,” which supports nonprofit organizations around the world.

Innovation

Atlassian is constantly innovating and releasing new products and services. The company is also known for its innovation in the workplace, with its “ShipIt Days” allowing employees to work on innovative projects outside of their usual work.

Customer Satisfaction

Atlassian is committed to providing great customer service. The company has a Net Promoter Score (NPS) of 71, which is considered to be excellent.

==============================

HubSpot

As we step into 2023, the world of software as a service (SaaS) is rapidly expanding, and there is a lot of buzz around Hubspot. Hubspot is a leading CRM, marketing, sales, and customer service software provider, and there are many reasons why it’s a top company to watch out for in 2023. In this article, we’ll dive into Hubspot’s company overview, products and services, target market, business model, funding, and interesting points about the brand.

Company Overview

Hubspot was founded in 2006 by Brian Halligan and Dharmesh Shah, and it’s headquartered in Cambridge, Massachusetts. The company’s mission is to help businesses grow better, and they do this by providing a suite of software tools that enable companies to attract, engage, and delight customers.

Products and Services

Hubspot’s product suite is divided into four main categories: marketing, sales, service, and CRM. In the marketing category, Hubspot offers tools for content management, social media, SEO, email marketing, advertising, and analytics. The sales category includes tools for sales automation, pipeline management, and contact management. The service category provides tools for customer service and support, including a help desk and knowledge base. The CRM category ties everything together, providing a unified view of customer interactions across all channels.

Target Market

Hubspot’s target market is primarily small to medium-sized businesses (SMBs) that are looking for an all-in-one software solution to manage their marketing, sales, and customer service. However, the company has been expanding its offerings to include larger enterprises as well.

Business Model

Hubspot’s business model is subscription-based, with customers paying a monthly fee for access to the software. The company also offers add-on services, such as consulting and training, which generate additional revenue.

Funding

Hubspot has raised over $1 billion in funding since its inception, with its most recent funding round in 2021 raising $175 million. The company went public in 2014 and is traded on the New York Stock Exchange under the symbol HUBS.

Interesting Points about the Brand

Hubspot has a strong focus on inbound marketing, which emphasizes attracting customers through content and experiences rather than interruptive advertising.

The company has a robust community of users and partners, with over 100,000 customers and 3,000 agency partners worldwide.

Hubspot has a strong commitment to sustainability, with initiatives such as carbon neutrality and a focus on reducing waste.

In conclusion, Hubspot is a top Saas company to watch out for in 2023 due to its innovative product suite, commitment to customer success, and strong financial backing. As businesses continue to seek all-in-one solutions to manage their operations, Hubspot is well-positioned to meet this demand and continue its growth trajectory.

——————————————

Asana is a cloud-based project management software company founded in 2008 by Dustin Moskovitz and Justin Rosenstein. The company has been growing rapidly and has become a popular SaaS (Software as a Service) provider in the project management industry. In this article, we will discuss the various aspects of Asana, including its company overview, products and services, target market, business model, funding, and interesting points about the brand.

Company Overview

Asana is a privately held company that provides a cloud-based project management software platform for individuals and teams to track and manage their work. The platform offers various features, including task management, project tracking, team collaboration, and reporting. Asana’s platform can be accessed through a web application or a mobile app, and it offers integrations with various third-party apps, including Google Drive, Slack, and Dropbox.

Products and Services

Asana offers a range of products and services to help individuals and teams manage their work efficiently. Some of its notable products and services include:

Asana Work Graph

Asana’s Work Graph is a proprietary technology that powers its platform, allowing individuals and teams to track and manage their work effectively. It is a data architecture that organizes and connects all the work that happens within an organization, including tasks, projects, people, and data.

Asana Premium

Asana Premium is a paid version of the platform that offers advanced features such as custom fields, project portfolios, and admin controls. The Premium version is designed for larger teams or organizations that require more complex project management capabilities.

Asana Business

Asana Business is a higher-tier subscription service that offers advanced security features and priority support. The Business version is designed for organizations that require a higher level of security and compliance.

Target Market

Asana targets a broad market of individuals and teams who need to manage their work effectively. Its platform is suitable for a range of industries, including marketing, design, engineering, and project management. Asana’s target market includes small enterprises that require a scalable and flexible project management solution.

Business Model

Asana’s business model is based on a subscription-based SaaS model. The company offers a free version of its platform, which includes basic project management features. It also offers paid versions of its platform with more advanced features, such as Asana Premium and Asana Business. Asana’s revenue is generated primarily from its paid subscription services.

Funding

Since its founding in 2008, Asana has raised over $200 million in funding. Its investors include some of the leading venture capital firms, including Benchmark Capital, Founders Fund, and 8VC. In 2018, Asana raised $75 million in a funding round led by Generation Investment Management, bringing the company’s valuation to over $1.5 billion.

Interesting Points about the Brand

Asana has several interesting points that make it stand out in the SaaS industry. Here are a few notable points:

1. Co-Founder Dustin Moskovitz was also a Facebook Co-Founder

Dustin Moskovitz, one of Asana’s co-founders, was also a co-founder of Facebook. He left Facebook in 2008 to start Asana.

2. Asana’s Work Graph is a Unique Approach to Project Management

Asana’s Work Graph is a proprietary technology that sets it apart from other project management software providers. It offers a unique approach to managing work by connecting all aspects of a project in one place.

3. Asana’s Platform is Highly Customizable

Asana’s platform is highly customizable, allowing teams to create custom workflows, fields, and templates. This makes it a flexible solution for teams with unique project management needs.

4. Asana’s Platform Integrates with Over 100 Apps

Asana’s platform integrates with over 100 third-party apps, making it a versatile tool for managing work across various platforms and applications.

=======================

DocuSign

DocuSign is one of the most innovative SaaS companies that provide a complete suite of digital signature and transaction management solutions for businesses. The company is known for its secure, reliable, and easy-to-use platform that enables businesses to sign, send, and manage documents online, anytime, and anywhere. In this article, we will explore DocuSign’s company overview, products and services, target market, business model, funding, and interesting points about the brand.

Company Overview

DocuSign was founded in 2003 by Tom Gonser, Court Lorenzini, and Eric Ranft in Seattle, Washington. The company started as a digital signature service and has grown into a leading global SaaS platform for managing electronic agreements. As of 2023, DocuSign has more than 1,800 employees and offices in over 12 countries worldwide. The company has been recognized as one of the fastest-growing SaaS companies in the world, with a 42% year-over-year growth rate.

Products and Services

DocuSign offers a wide range of products and services that help businesses of all sizes to streamline their workflow and increase productivity. Some of the most popular products and services offered by DocuSign include:

eSignature: A secure and legally binding way to sign documents electronically.

DocuSign Rooms: A virtual workspace for real estate transactions that enables agents to share, collaborate, and manage documents online.

DocuSign Gen: A tool that automates the creation and distribution of customized documents such as contracts, agreements, and invoices.

DocuSign Identify: A digital identity verification solution that helps businesses verify the identity of signers remotely.

Target Market

DocuSign’s target market includes businesses of all sizes and industries that need to sign and manage documents online securely. The company’s customers include real estate agents, healthcare providers, financial services firms, legal professionals, and government agencies. DocuSign’s solutions are especially useful for businesses that require secure and legally binding signatures for compliance reasons.

Business Model

DocuSign’s business model is based on a subscription-based software as a service (SaaS) model. The company offers various pricing plans that allow customers to choose the features and services that meet their specific needs. DocuSign’s pricing plans are based on the number of users, the number of documents, and the level of support required.

Funding

DocuSign has raised over $600 million in funding from leading investors, including Salesforce Ventures, Google Ventures, and Visa. The company went public in 2018 and is listed on the NASDAQ under the ticker symbol DOCU.

Interesting Points about the Brand

Here are some interesting points about the DocuSign brand:

DocuSign was named one of the world’s most innovative companies by Forbes in 2021.

The company has over 750,000 customers worldwide, including more than 800 of the Fortune 1000 companies.

DocuSign has processed over 1.5 billion electronic signatures since its inception.

The company’s CEO, Dan Springer, was named Glassdoor’s Highest Rated CEO in 2018 and 2019.

DocuSign has been recognized as one of the best places to work by Glassdoor and Fortune magazine.

Twilio

Company Overview

Founded by Jeff Lawson, Evan Cooke, and John Wolthuis in 2008, Twilio is one of the most well known companies in the world. Twilio , cloud communications platform, is headquartered in San Francisco, California. It provides APIs for developers messaging, videos and voice to be easily integrated into their applications. With many offices in different countries of the world Twilio has been expanding ever since its inception.

Twilio offers a wide range of products and services that enable developers to build and integrate communication functionalities into their applications. Some of Twilio’s popular products and services include:

Twilio Allows developers to add SMS, MMS, and WhatsApp messaging to their applications. It also enables developers to add voice through VoIP, SIP, and other voice protocols. Programmable video feature provides APIs for developers to add real-time video and group chat with their application

Twilio has a super network that provides a global carrier hat connects to over 5 billion mobile devices and 3.5 billion landlines worldwide.

Target Market

Twilio’s products and services are designed to meet the communication needs of businesses of all sizes, from startups to enterprise-level organizations. Twilio serves customers across a range of industries, including healthcare, finance, retail, and more.

Business Model

Twilio has a pay-as-you-go pricing system, where you only pay for what you use. The company’s pricing is based on usage, such as the number of messages or minutes used, and varies depending on the country and region.

Twilio raised more than $1.4 billion funding since its inception. The company went public in 2016 and is listed on the New York Stock Exchange (NYSE) under the ticker symbol TWLO.

Some Lesser Known Facts About Twilio

Twilio is known for its strong developer community and support. The company offers extensive documentation, tutorials, and community forums to help developers integrate Twilio’s products and services into their applications.

Twilio has a strong commitment to diversity and inclusion. Twilio implemented several initiatives to increase diversity in its workforce and support underrepresented groups in technology.

Twilio is identified and valued for its innovative products and services. It  won several awards, including the 2020 CODiE Award for Best Communication Platform as a Service and the 2020 DevOps Excellence Award for Best Innovation in DevOps Tooling.

Twilio is a top SaaS company to watch out for in 2023. With its innovative cloud communications platform, extensive range of products and services, and commitment to diversity and inclusion, Twilio is poised for continued success in the years to come.

DocuSign

Company Overview

DocuSign was founded in 2003 by Tom Gonser, Court Lorenzini, and Eric Ranft in Seattle, Washington. The company started as a digital signature service and has grown into a leading global SaaS platform for managing electronic agreements. As of 2023, DocuSign has more than 1,800 employees and offices in over 12 countries worldwide. The company has been recognized as one of the fastest-growing SaaS companies in the world, with a 42% year-over-year growth rate.

Products and Services

DocuSign offers a wide range of products and services that help businesses of all sizes to streamline their workflow and increase productivity. Some of the most popular products and services offered by DocuSign include:

eSignature: A secure and legally binding way to sign documents electronically.

DocuSign Rooms: A virtual workspace for real estate transactions that enables agents to share, collaborate, and manage documents online.

DocuSign Gen: A tool that automates the creation and distribution of customized documents such as contracts, agreements, and invoices.

DocuSign Identify: A digital identity verification solution that helps businesses verify the identity of signers remotely.

Target Market

DocuSign’s target market includes businesses of all sizes and industries that need to sign and manage documents online securely. The company’s customers include real estate agents, healthcare providers, financial services firms, legal professionals, and government agencies. DocuSign’s solutions are especially useful for businesses that require secure and legally binding signatures for compliance reasons.

Business Model

DocuSign’s business model is based on a subscription-based software as a service (SaaS) model. The company offers various pricing plans that allow customers to choose the features and services that meet their specific needs. DocuSign’s pricing plans are based on the number of users, the number of documents, and the level of support required.

Funding

DocuSign has raised over $600 million in funding from leading investors, including Salesforce Ventures, Google Ventures, and Visa. The company went public in 2018 and is listed on the NASDAQ under the ticker symbol DOCU.

Interesting Points about the Brand

Here are some interesting points about the DocuSign brand:

DocuSign was named one of the world’s most innovative companies by Forbes in 2021.

The company has over 750,000 customers worldwide, including more than 800 of the Fortune 1000 companies.

DocuSign has processed over 1.5 billion electronic signatures since its inception.

The company’s CEO, Dan Springer, was named Glassdoor’s Highest Rated CEO in 2018 and 2019.

DocuSign has been recognized as one of the best places to work by Glassdoor and Fortune magazine.

Conclusion

The SaaS industry is rapidly growing and evolving, with new players entering the market every year. However, certain companies stand out as ones to watch in 2023 based on their innovative products and services, strong financials, and commitment to customer success. Companies like Wrike and Asana are leading the way in their respective industries and are poised for continued growth and success in the years to come. As businesses continue to rely more on cloud-based software solutions, it is important to keep an eye on these top SaaS companies and their developments. By staying informed about the latest trends and innovations, businesses can stay ahead of the curve and maintain their competitive edge.

Incredible Impact of ChatGPT on Payments Industry

Impact of ChatGPT on Payments in 2023?

In the world of technology, the introduction of artificial intelligence (AI) has revolutionized many industries. One of the most advanced chatbots in the market today is ChatGPT, developed by OpenAI. ChatGPT is transforming the financial industry by providing 24/7 support, quick response times, and automating routine tasks. This has led to increased efficiency, cost savings, and improved customer service.

In this article, we will explore the impact of ChatGPT on payments industry and its implications for the future of AI in finance.

Payments are an integral part of the financial industry, and the payments landscape is rapidly changing. With the rise of FinTech companies, payments have become faster, more secure, and more convenient than ever before. However, with this increased convenience comes increased complexity, and customers are looking for ways to simplify their payment processes. This is where ChatGPT comes in.

What is ChatGPT?

ChatGPT is a large language model developed by OpenAI, based on the GPT-3.5 architecture. It is a computer program designed to process and understand human language, and generate responses that are natural-sounding and coherent.

ChatGPT is trained on a massive amount of data, including books, websites, and other text sources, which allows it to have a vast knowledge base and to understand a wide range of topics. It can also generate new text on its own, using its understanding of language and its training data to produce responses that are often creative and insightful.

One of the key features of ChatGPT is its ability to learn from interactions with users. As people ask it questions or provide input, it can incorporate that information into its understanding and use it to improve its responses in the future.

ChatGPT has many potential applications, such as in customer service, education, and entertainment. It can also be used to assist people with disabilities, such as those who have difficulty speaking or writing.

OpenAI – What you should know?

Elon Musk along with Sam Altman and Greg Brockman founded OpenAi in 2015. It has since become one of the most prominent organizations in the field of AI research. It is a research organization that wants to improve the world by developing advanced artificial intelligence (AI) systems.

The organization is focused on developing cutting-edge AI technologies that can help to solve some of the world’s most challenging problems, such as climate change, economic inequality, and disease. TFor this, OpenAI has assembled a team of leading AI researchers and developers from around the world, who work together to explore the potential of AI and develop new and innovative applications for this technology.

One of OpenAI’s most famous achievements is the development of the GPT (Generative Pre-trained Transformer) series of language models, which includes GPT-3. These models use deep learning techniques to analyze vast amounts of data and generate human-like responses to a wide range of queries, making them useful for a variety of applications such as natural language processing, content creation, and chatbots.

In addition to its research efforts, OpenAI also seeks to promote responsible development and deployment of AI technologies. The organization advocates for transparency and collaboration in the development of AI systems, and works to ensure that AI is used for the betterment of society.

Impact of ChatGPT on Payments Industry

ai impact on finance

As an AI language model, ChatGPT’s role in payments is limited to providing customer support through chatbots and assisting with natural language processing tasks related to payment systems. Chatbots powered by ChatGPT can help customers with common payment-related inquiries, such as checking their account balance, making a payment, or disputing a charge. They can also provide personalized recommendations and offers based on a customer’s transaction history.
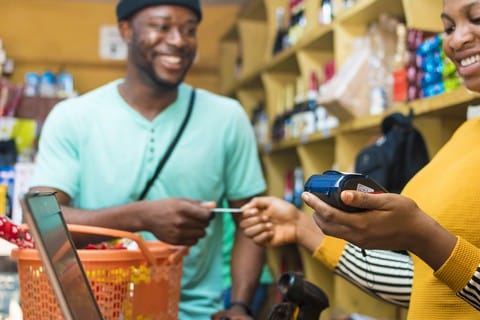
ChatGPT can analyze and process natural language queries related to payments, such as voice commands or messages sent through chat or email. This can help improve the accuracy and speed of payment processing systems, reducing errors and delays in transactions.

However, it’s important to note that ChatGPT does not have access to any sensitive payment information, such as credit card numbers or bank account details. Its role is limited to processing natural language queries and providing responses based on pre-existing knowledge and data. All payment transactions are still securely processed by the payment gateway or financial institution.

The Impact of ChatGPT on the Payments Industry

payments industry

As an AI-powered conversational agent, ChatGPT will impact the payments industry also. Here are some of the ways in which ChatGPT can make a difference:

Improved Customer Experience

 ChatGPT can provide an enhanced customer experience by answering customer queries and resolving issues quickly and efficiently. This can lead to increased customer satisfaction and loyalty, which can ultimately drive revenue growth.

Streamlined Payments

ChatGPT can automate the payment process by enabling customers to make payments through the chat interface. This can simplify the payment process for customers, reduce the need for manual intervention, and speed up the overall payment process.

Fraud Detection

ChatGPT can monitor transactions in real-time and detect fraudulent activity. This can help prevent fraud and improve security for both customers and merchants.

Personalized Recommendations

ChatGPT can analyze customer data and make personalized recommendations for products or services that may be of interest to the customer. This can help increase sales and revenue for merchants.

Operational Efficiency

ChatGPT can automate routine tasks such as customer inquiries and dispute resolution, freeing up human resources to focus on more strategic tasks. This can help increase operational efficiency and reduce costs for merchants.

ChatGPT  will significantly improve the payments industry by providing a more personalized and efficient customer experience, streamlining payments, detecting fraud, and increasing operational efficiency.

The Implications of ChatGPT on the Future of AI in Finance

peer to peer concept blockchain technology 212774474

ChatGPT represents a significant milestone in the development of artificial intelligence (AI) and its potential applications in the finance industry. The implications of ChatGPT on the future of AI in finance are extensive and far-reaching. Here are some possible implications:

Improved customer service

 ChatGPT can improve customer service in the finance industry by providing real-time support to customers. It can handle inquiries, provide information on financial products and services, and guide customers through various processes such as loan applications, account opening, and investment decisions.

Enhanced fraud detection

ChatGPT can help in fraud detection by analyzing customer transactions and flagging any suspicious activities. It can also provide personalized security advice to customers based on their spending patterns.

Automated financial analysis

ChatGPT can perform financial analysis tasks such as risk assessment, portfolio management, and investment recommendations. It can analyze large volumes of financial data and provide insights helping in making informed investment decisions.

Efficient compliance monitoring

ChatGPT can assist in compliance monitoring by analyzing regulatory requirements and ensuring that financial institutions comply with them. It can also keep track of changes in regulations and help institutions adjust their policies accordingly.

Improved data analysis

ChatGPT can help in analyzing large amounts of financial data, enabling financial institutions to make more informed decisions. It can also identify patterns in financial data that may be difficult to detect with traditional methods.

ChatGPT can revolutionize the finance industry by providing innovative solutions that can improve efficiency, accuracy, and customer service. As AI technology continues to evolve, we can expect to see more advanced applications of ChatGPT and other AI-based solutions in the finance industry. However, it is important to note that with any new technology, there are also potential risks and challenges, such as data privacy concerns, bias in decision-making, and cybersecurity threats. Therefore, it is essential to approach the integration of AI in finance with caution and develop robust frameworks for responsible AI development and deployment.

What are the Challenges of Using ChatGPT in Payments?

While ChatGPT will potentially transform the payments industry, there are several challenges that must be addressed before its widespread adoption.

Data Privacy and Security

ChatGPT requires access to large amounts of sensitive financial and personal data in order to provide accurate and personalized responses. This raises concerns about data privacy and security, particularly in the wake of high-profile data breaches and cyber attacks.

Accuracy and Trustworthiness

ChatGPT’s responses are only as accurate as the data it is trained on. While it has the ability to learn and adapt over time, there is a risk of bias and errors in its responses, which could lead to incorrect financial decisions or harm to the user.

Regulatory Compliance

The use of ChatGPT in payments must comply with relevant regulations, such as Know Your Customer (KYC) and Anti-Money Laundering (AML) laws. This requires the development of robust compliance and governance frameworks to ensure that ChatGPT is used in a responsible and ethical manner.

Integration with Existing Systems

ChatGPT must be integrated with existing payment systems and platforms to enable seamless transactions. This requires a significant investment in infrastructure and technology, and may involve complex interoperability issues.

User Acceptance and Adoption

Finally, the success of ChatGPT in payments will depend on user acceptance and adoption. While many consumers are comfortable with chatbots and virtual assistants, others may be skeptical or resistant to using AI-powered tools for financial transactions. This highlights the need for effective marketing and education campaigns to build trust and confidence in ChatGPT.

Conclusion

ChatGPT is transforming the financial industry by providing a highly advanced chatbot that can answer questions and provide information in a conversational manner. The technology is helping financial institutions to improve efficiency, reduce costs, and improve customer service, and is playing a key role in the transformation of the FinTech industry.

However, there are also challenges that need to be addressed, including security, regulatory compliance, and accessibility. As the technology continues to evolve and become more widely adopted, it will be important for financial institutions to address these challenges and ensure that ChatGPT is used in a responsible and ethical manner that benefits both customers and the industry as a whole.

A2A Payment

A2A Payment (Account to Account Payment) Trends and Technologies

Account-to-account payment or A2A payment solution is progressively replacing traditional payment methods, such as bank cards or cash. It is being widely used in eCommerce payments and will account for almost 20% of it in 2023.

If you want to send funds directly from your account to another account, say a merchant’s account, then A2A payments allow that without any difficulty. The rise of open banking has facilitated A2A payment adoption in recent years. A2A transactions are becoming increasingly prevalent and offer a host of advantages over other payment methods. These include lower transaction costs, higher conversion rates, enhanced security features, and seamless payment experiences.

This article delves into the latest trends and technologies used for A2A payments, its growth, future prospects, and latest developments.

A2A transfers involve a direct bank account to bank account transfer of funds. The transfer of funds generally takes place from the payer’s bank directly to the bank of the merchant. This mode of payment eliminates the need for intermediaries and facilitates quicker transactions, making it a preferred payment option for many. By choosing A2A payments, customers can ensure that their funds reach the intended recipient quickly and securely, without incurring any additional fees.

The popularity of A2A payments has soared in recent years, with experts predicting that by 2023, it will account for approximately 20% of all eCommerce payments across the globe. This article explores the A2A payments’ latest trends and technologies, innovation, its growth, future prospects, and latest developments.

What Are the Driving Factors Behind the Rising Popularity of A2A Payments?

A2A payments has was already available for merchants and users for some years now. However, businesses have traditionally opted for card network schemes because A2A payments did not offer benefits that would exceed those given by card companies.

Recently, however, Open Banking allowed third party economic service suppliers, thus giving a huge scope for A2A payments. This has caused a surge in A2A transactions as it offers several benefits, including easy client reach, no intermediaries, improved rate of conversion, lower cost of transaction, easy and quick settlements, and easy, smooth and secured payments.

Easy client reach is an exceptional feature of A2A payments. A2A payment can be made to a wider range of clients, including those who do not have access to credit or debit cards.

There are no intermediaries thus there is no need for a middleman to facilitate the transaction, reducing the risk of fraud and errors in the transaction process.

Rates of conversion are improved. With A2A There is a higher likelihood of completing a sale as the payment process is streamlined, leading to a better user experience.

The cost of transaction is low. And therefore, it makes A2A payments an attractive option for businesses looking to save money. Settlements that are quick and easy enable faster payment processing, while exclusively robust security ensures that transactions are secure and protected against fraud. The payments are frictionless and easy. This makes A2A payments convenient for users and widely accepted.

These benefits makes A2A transactions an increasingly popular payment method for both businesses and consumers. It is expected that this trend will continue in the future as A2A payments continue to offer more advantages over traditional card network schemes.

The growth of A2A payments can be attributed to several factors:

Cost-effectiveness

A2A payments are cheaper than traditional payment methods, such as credit cards, which charge merchants a fee of 2-3% per transaction. A2A payments eliminate the need for intermediaries, which reduces transaction costs for both merchants and consumers.

Convenience

 A2A payments are fast and convenient, allowing consumers to transfer money between bank accounts instantly. This is particularly useful for bill payments and other regular transactions, such as paying rent or making loan repayments.

Security

A2A payments are considered more secure than traditional payment methods, as they eliminate the need for consumers to provide sensitive financial information, such as credit card details, to third-party payment processors.

Open banking

The emergence of open banking regulations in many countries has encouraged the development of A2A payment systems. Open banking allows third-party developers to access financial data and payment systems, creating new opportunities for innovation in the payments industry.

Digitalization

The rapid digitalization of the global economy has driven the growth of A2A payments. As consumers increasingly conduct transactions online, the demand for fast and convenient payment options has grown.

A2A Payments – Global Reach and Acceptance

A2A (account-to-account) payments is significant due to the rapid growth and adoption of digital payment solutions. A2A payments are becoming increasingly popular as businesses and individuals seek faster, more efficient, and cost-effective ways to transfer money globally.

A2A payments are facilitated by digital payment platforms and software, which are designed to allow payments to be made directly between bank accounts, without the need for intermediaries like credit cards or payment gateways. This means that funds can be transferred faster and more securely, with fewer fees and transaction costs.

In recent years, the adoption of A2A payment solutions has been driven by several factors. Firstly, the growing demand for faster and more efficient payment methods, particularly in the context of global commerce and cross-border transactions. With businesses operating in multiple countries and consumers shopping online from all over the world, the need for fast and secure payment solutions has become critical.

Secondly, the rise of mobile and digital technology has played a significant role in fueling the growth of A2A payments. With the proliferation of smartphones and mobile devices, consumers are increasingly looking for ways to make payments and manage their finances on the go. This has led to the development of mobile payment solutions that enable A2A payments via mobile devices.

Finally, the COVID-19 pandemic has also accelerated the adoption of digital payment solutions, including A2A payments. With lockdowns and social distancing measures in place, consumers and businesses have turned to digital payment methods as a way to continue making transactions without the need for physical contact.

Today, many countries in the world are using A2A payment, with many digital payment platforms offering A2A payment solutions for both domestic and cross-border transactions. These solutions are being adopted by businesses of all sizes, from large multinational corporations to small and medium-sized enterprises (SMEs) and even individual consumers.

A2A Payments Trend: Current State and Future Prospects

As digital payments continue to gain popularity, Account-to-Account (A2A) payments are becoming increasingly common. A2A payments are electronic transfers of funds between bank accounts without the need for intermediaries such as credit cards or payment gateways.

Europe’s A2A Payment Landscape

image 1
image source – Wikipedia

European Payments Initiative (EPI) in European countries is becoming rapidly popular by days. This is a strong and fast growing coalition. At the moment it has more than 30 banks and present in 7 countries in the EU zone.

At present, the EPI manages a significant portion of all transactions in Europe, accounting for 65% of the total volume. The organization’s wants to establish a cohesive payment system that will serve as the new industry benchmark for financial transactions across the European Union. This will be useful for markets from Europe and outside.

A2A payment model forms the backbone of this ambitious project, which is set to revolutionize the way consumers and merchants conduct business.

The United States’ A2A Payment Landscape

FedNow instant payment service is already been used by some limited users as a trial. Federal Reserve plans to launch it in 2023. This service will provide instantaneous, around-the-clock, low-cost payments to consumers and businesses alike. With the FedNow instant payment service, the Federal Reserve hopes to establish a modern payment system that serves the public interest by providing a foundation for innovation in faster payments.

Australia’s A2A Payment Landscape

BPAY Group, NPP Australia and Eftpos merged and created the Australia Payments in 2021. This combination is working on improving the management of investment and augmentation of payment systems offered by each individual.

This unification is all set to enhance the overall efficiency of payment operations while also broadening the range of payment alternatives for customers, thus offering greater convenience and flexibility. As a result, Australia Payments Plus promises to bring about a significant transformation in the payment landscape in Australia.

A2A Payments – Challenges

A2A payments have revolutionized the way we conduct transactions, making it easier and faster for individuals and businesses to transfer funds. However, with the emergence of this new technology, there are several challenges that come with it.

One of the biggest challenges is security. With A2A payments, the risk of fraud and cybercrime increases. There is a need for robust security measures to protect against unauthorized access, data breaches, and identity theft. As more transactions are conducted online, it is essential to implement multi-factor authentication and encryption technologies to safeguard sensitive information.

Another challenge is interoperability. A2A payments involve multiple parties such as banks, payment processors, and other financial institutions. Ensuring that these systems can communicate with each other effectively is crucial for seamless transactions. There is a need for standardized protocols and formats to ensure interoperability between different systems.

The lack of standardization is also a significant challenge. Different payment systems have different standards and protocols, making it difficult for them to work together. There is a need for a common standard that can be used across all payment systems to ensure uniformity and interoperability.

Moreover, there are regulatory challenges. A2A payments are subject to various regulations and compliance requirements, which vary by jurisdiction. It is essential to comply with these regulations to avoid penalties and legal action.

Finally, there is a need to educate consumers and businesses about the benefits and risks of A2A payments. Many people are still not aware of the technology, and some may be hesitant to use it due to security concerns. Raising awareness and providing education about the benefits and risks of A2A payments is crucial for its widespread adoption.

A2A payments have tremendous potential to revolutionize the way we conduct transactions. However, there are several challenges that need to be addressed, including security, interoperability, standardization, regulation, and education. By addressing these challenges, A2A payments can become a reliable and secure way to transfer funds globally.

Future Outlook of A2A Payments

The future outlook of A2A payments is very promising. With the continuous growth of digitalization and e-commerce, the demand for instant and secure payments between businesses and individuals will only continue to increase. In addition, the ongoing pandemic has accelerated the shift towards cashless transactions, further fueling the growth of A2A payments.

One of the major developments in the A2A payments industry is the emergence of blockchain technology, which is expected to revolutionize the way A2A payments are processed. Blockchain technology provides a decentralized and transparent system that eliminates the need for intermediaries and ensures secure and instant transactions. This technology is already being adopted by various companies and financial institutions and is expected to become more widespread in the coming years.

Moreover, collaborations and partnerships between banks, payment providers, and fintech companies are also expected to increase in order to provide seamless and efficient A2A payment services. These partnerships will allow for greater integration between different payment systems and enhance the overall user experience.

Another significant trend in the A2A payments industry is the shift towards mobile payments. As smartphones become more ubiquitous and digital wallets become more popular, the use of mobile devices for A2A payments is expected to increase. This will provide greater convenience and accessibility for users, allowing them to make payments on-the-go without the need for physical cards or cash.

The future of A2A payments looks very bright. With the increasing demand for instant and secure payments, the adoption of new technologies such as blockchain, and the rise of mobile payments, the A2A payments industry is poised for continued growth and innovation. As more businesses and individuals shift towards digital payments, A2A payments will become an even more integral part of the global financial ecosystem.

Conclusion

Account-to-account (A2A) payments are a rapidly growing payment method that offer numerous benefits, including lower transaction costs, instant settlements, and advanced security measures. The adoption of open banking and real-time payment infrastructures has accelerated the growth of A2A transactions, and the ongoing COVID-19 pandemic has further boosted their adoption.

While A2A payments still face challenges related to standardization, security, and data privacy, industry stakeholders are working to address these issues and create a more robust and secure payment ecosystem.

With the potential to comprise 20% of global eCommerce payments by 2023, A2A payments are poised to become an essential part of the payments landscape, creating a promising future for this payment method.

Sezzle Files For Listing on Nasdaq

Sezzle Buy Now, Pay Later (BNPL) Firm to List on Nasdaq

The world of e-commerce has been changing rapidly in recent years, with more and more people turning to online shopping for convenience and affordability. One of the biggest trends in e-commerce is the rise of Buy Now, Pay Later (BNPL) services, which allow customers to pay for their purchases in installments rather than all at once. Sezzle is one of the leading BNPL firms in the United States, and the recent announcement that Sezzle files for listing on Nasdaq is the talk of the town. In this article, we’ll take a closer look at Sezzle as a company and its plans for the future.

What is Sezzle?

Sezzle is a financial technology company based in Minneapolis, Minnesota that offers Buy Now, Pay Later (BNPL) services to customers across the United States and Canada. Sezzle was founded in 2016 with the mission to provide customers with a flexible and affordable way to pay for their purchases.

Sezzle allows customers to pay for their purchases in four interest-free installments, with no credit check or hidden fees. Customers can sign up for Sezzle’s service through its website or mobile app and link their debit or credit card. When making a purchase from a merchant that partners with Sezzle, customers can select Sezzle as their payment option and complete their transaction as they normally would.

Once the purchase is complete, Sezzle pays the merchant in full and the customer pays Sezzle back in four equal installments over the course of six weeks. Sezzle charges no interest or fees as long as the customer makes their payments on time. Sezzle also offers customers the ability to reschedule their payments if they need more time to pay.

Sezzle’s BNPL services are designed to help customers afford purchases they might not be able to make otherwise. Sezzle’s services are particularly popular among young people, who may not have established credit histories or the financial means to pay for large purchases upfront.

In addition to providing a flexible and affordable payment option for customers, Sezzle also offers benefits to merchants. Sezzle can help increase sales and customer loyalty by offering customers a flexible payment option. Sezzle also takes on the risk of payment defaults and chargebacks, which can be a significant burden for merchants.

Sezzle has rapidly grown since its founding in 2016 and now has over 2 million active users and partnerships with over 34,000 merchants. Sezzle has also been recognized for its innovative approach to BNPL services and has won numerous awards for its services and technology.

Sezzle Files For Listing on Nasdaq

Sezzle’s journey to the Nasdaq began in 2019 when the company completed its initial public offering (IPO) on the Australian Securities Exchange (ASX). Sezzle became the first American fintech company to list on the ASX, which provided the company with access to capital and a global investor base.

Since going public on the ASX, Sezzle has experienced rapid growth and expanded its presence in the United States and Canada. Sezzle’s services have become increasingly popular among young people, who value the company’s flexible and affordable payment options.

In 2020, Sezzle announced that it had applied for a dual listing on the Nasdaq, which would allow the company to access a larger pool of investors and potentially increase its valuation. Sezzle’s application was approved by the Nasdaq in December 2020, and the company began trading on the Nasdaq under the ticker symbol “SZL” in January 2021.

Sezzle’s listing on the Nasdaq was a significant milestone for the company and the BNPL industry as a whole. The listing provided Sezzle with access to a larger investor base and increased visibility, which could help the company continue to grow and expand its services.

Sezzle’s successful journey to the Nasdaq is a testament to the company’s innovative approach to BNPL services and its commitment to providing customers with a flexible and affordable way to pay for their purchases. As Sezzle continues to grow and expand, it is likely that the company will continue to play a significant role in the evolution of the BNPL industry.

Why is Sezzle’s Nasdaq Listing Important?

Sezzle’s Nasdaq listing is important for several reasons. First, the listing provides Sezzle with access to a larger pool of investors and increased visibility, which could help the company continue to grow and expand its services. The Nasdaq is one of the world’s largest stock exchanges, with a global investor base and a reputation for listing innovative and high-growth companies. Sezzle’s listing on the Nasdaq could help the company attract new investors and potentially increase its valuation.

Second, Sezzle’s Nasdaq listing is a significant milestone for the BNPL industry as a whole. The BNPL industry has experienced rapid growth in recent years, driven by changing consumer preferences and a shift away from traditional credit products. Sezzle’s successful listing on the Nasdaq could help validate the BNPL business model and attract additional investment and attention to the industry.

Third, Sezzle’s Nasdaq listing could help the company compete more effectively with other BNPL firms, such as Afterpay and Klarna, which are also listed on major stock exchanges. The BNPL industry is becoming increasingly crowded and competitive, with new entrants launching services and traditional lenders entering the space. Sezzle’s listing on the Nasdaq could help the company differentiate itself from competitors and position itself as a leading player in the industry.

Overall, Sezzle’s Nasdaq listing is an important milestone for the company and the BNPL industry as a whole. The listing provides Sezzle with access to a larger investor base and increased visibility, which could help the company continue to grow and expand its services. It also validates the BNPL business model and could attract additional investment and attention to the industry. As the BNPL industry continues to evolve and mature, Sezzle’s Nasdaq listing could help the company remain a competitive and innovative player in the space.

The Benefits of Sezzle’s BNPL Services

Sezzle’s BNPL (Buy Now Pay Later) services offer several benefits to consumers, retailers, and the economy as a whole.

Firstly, Sezzle’s BNPL services provide consumers with a flexible and affordable way to pay for their purchases. Sezzle allows consumers to break their payments into smaller, interest-free installments, making it easier for them to manage their budgets and pay for larger purchases over time. This can help consumers avoid high-interest credit cards and other costly financing options, and reduce the risk of falling into debt.

Secondly, Sezzle’s BNPL services can help retailers increase their sales and customer loyalty. By offering Sezzle’s payment options at checkout, retailers can appeal to a wider range of consumers who might not be able to afford a purchase outright. Sezzle’s payment options can also help retailers reduce cart abandonment rates and increase average order value, as consumers are more likely to complete their purchases when they have access to flexible payment options.

Thirdly, Sezzle’s BNPL services can benefit the economy as a whole by increasing consumer spending and supporting small businesses. By providing consumers with affordable financing options, Sezzle can help stimulate demand for goods and services, which can lead to job creation and economic growth. Sezzle’s services can also help small businesses compete more effectively with larger retailers by offering flexible payment options that can attract new customers and increase sales.

The Future of Sezzle

Sezzle, has announced its intention to list shares of common stock on the Nasdaq Global Market. The move will enable the company to expand its potential investor base to the United States, as its shares of common stock continue to trade on the Australian Securities Exchange (ASX). Sezzle also plans to undertake a reverse split of its common stock to meet or exceed the minimum $4 bid price required by Nasdaq Global Market, subject to stockholder approval.

Sezzle’s decision to list on Nasdaq is seen as a natural evolution, given that the company is already filing necessary reports with the Securities and Exchange Commission (SEC). Although it is not seeking to raise capital as part of the listing, Sezzle’s CEO Charlie Youakim has expressed excitement about expanding the company’s potential investor base.

This announcement comes on the heels of Sezzle’s impressive fourth-quarter earnings release, which reported a record income of $38.3 million, a 16.2% jump from the previous year. The company has also identified other revenue sources that could bring in an additional $10 million in 2023.

Sezzle’s success is attributed to the hard choices and tough actions it took to reach profitability, as the company pivoted its model in late 2021. Partners who had grown frustrated with Sezzle’s changes eventually saw the firm’s perceptive approach to fixing its model and appreciated its transparency. Sezzle’s CEO believes that honesty helped to build smarter relationships with its partners.

Sezzle’s decision to list on Nasdaq is a significant move for the company, enabling it to expand its reach and offer its BNPL services to a wider audience.

Conclusion

Sezzle’s decision to list on the Nasdaq is a significant milestone for the company and the BNPL industry as a whole. As Sezzle continues to grow and expand, it will be interesting to see how the company competes with other BNPL firms and how the industry as a whole evolves to meet the changing needs of consumers.

Gen Z Focused Payment Options

Gen Z Focused Payment Options and Technology Trends

As Gen Z becomes the largest demographic in the workforce, they are reshaping the way we think about payments and financial technology. This generation has grown up with mobile devices and instant gratification, and they expect the same level of convenience in their financial transactions. This article will explore the gen Z focused payment options and technology trends that are most important to Gen Z and how financial services providers can meet their needs.

Gen Z Focused Payment Options and Technology Trends – 2023

Gen Z and Cash

cash vs credit card usage

Gen Z is the demographic cohort that follows the millennials, typically born between the mid-1990s and mid-2010s. This group has grown up in a digital age, and their relationship with cash is quite different from previous generations. Gen Z is less reliant on cash for everyday transactions, with many preferring to use digital payment options.

The rise of online shopping and e-commerce has also contributed to this trend, as many Gen Zers are more comfortable making purchases using their smartphones or computers rather than carrying cash. Additionally, the COVID-19 pandemic has accelerated the move away from cash as people are looking for contactless payment options to reduce the risk of infection. Overall, Gen Z is a generation that is driving the shift towards digital payments and the adoption of new payment technologies.

P2P Payments

peer to peer payment

P2P (peer-to-peer) payments refer to a type of digital payment that allows individuals to transfer money from one person to another using a mobile app or website. These payments can be made between friends, family members, or even strangers, and are often used to split bills, pay for goods and services, or simply send money to someone else.

P2P payments are becoming increasingly popular among younger generations, including Gen Z, as they offer a convenient and secure way to transfer funds without the need for cash or checks. In most cases, users can link their bank accounts or credit/debit cards to the P2P app, making it easy to send and receive money with just a few taps on their mobile device. Some popular P2P payment apps include Venmo, Zelle, PayPal, and Cash App.

BNPL

bnpl services

BNPL (Buy Now, Pay Later) is a type of payment option that allows customers to make purchases without having to pay for them upfront. With BNPL, customers can split their purchases into smaller, interest-free installments that are paid over a set period of time.

This option is becoming increasingly popular among Gen Z consumers who may not have access to traditional credit options, or who prefer not to use credit cards due to concerns about high-interest rates and debt. BNPL allows consumers to make purchases that they may not have been able to afford otherwise, and it also provides them with greater flexibility and control over their spending.

Some popular BNPL services include Afterpay, Klarna, and Affirm. While BNPL can be a convenient option for some consumers, it’s important to understand the terms and conditions of the service, as missed payments or late fees can have negative consequences, including damage to credit scores.

Mobile Wallets

mobile wallet

Mobile wallets are a type of digital payment solution that allows users to store and manage their payment information on their smartphones. These wallets can be used to make purchases in stores, online, or within mobile apps, eliminating the need for physical cash or cards. Mobile wallets typically work by linking a user’s bank account or credit/debit card to their smartphone, allowing them to make transactions with just a few taps on their device. Popular mobile wallets include Apple Pay, Google Pay, and Samsung Pay.

These wallets use Near Field Communication (NFC) technology, allowing users to tap their phone against a compatible payment terminal to complete a transaction. Mobile wallets offer several advantages over traditional payment methods, including faster checkout times, enhanced security features, and the ability to track and manage to spend more easily. Additionally, some mobile wallets offer rewards or cashback programs for using their services, making them an attractive option for many consumers, including Gen Z.

Cryptocurrency

Best Crypto Exсhаngеѕ and Apps оf 2023

Cryptocurrency refers to a digital or virtual currency that uses encryption techniques to secure and verify transactions and control the creation of new units. Unlike traditional currencies, which are backed by governments or central authorities, cryptocurrencies operate on decentralized networks that are managed by a community of users.

This means that they are not subject to the same regulations or controls as traditional currencies, and their value can fluctuate rapidly based on market demand and other factors. Some popular cryptocurrencies include Bitcoin, Ethereum, and Litecoin. Cryptocurrencies are becoming increasingly popular among Gen Z consumers who value privacy, decentralization, and the ability to conduct transactions without the need for intermediaries like banks or payment processors.

Cryptocurrencies can be bought and sold on exchanges, and can also be used to make purchases with merchants who accept them as payment. While the adoption of cryptocurrencies is still relatively low compared to traditional currencies, many experts believe that they have the potential to transform the way we think about money and finance in the future.

Financial Education

business statistics success concept businessman analytics financial chart and graph 88207955

Financial education refers to the process of teaching individuals the skills and knowledge needed to manage their finances effectively. This can include topics such as budgeting, saving, investing, debt management, and understanding financial products and services.

Financial education is important for individuals of all ages, but it is particularly critical for Gen Z consumers who are just entering the workforce and starting to make financial decisions that will impact their long-term financial well-being. Many Gen Z consumers have grown up in a world of economic uncertainty and financial instability, and may not have had access to the same level of financial education and resources as previous generations.

As a result, there is a growing need for financial education programs that can help Gen Z consumers develop the skills and knowledge they need to make informed financial decisions and achieve their financial goals.

Some organizations and initiatives that offer financial education programs and resources include government agencies, non-profit organizations, and financial institutions. By investing in financial education, Gen Z consumers can take control of their financial futures and build a foundation for long-term financial success.

Sustainable Finance

World Wide Business And Financial Success 4299789

Sustainable finance refers to financial products and services that promote sustainable development and environmental responsibility. This includes investments in renewable energy, clean technologies, and other environmentally friendly projects, as well as loans and other financial products that support sustainable businesses and practices.

Sustainable finance is becoming increasingly important as individuals and organizations seek to address the challenges of climate change and other environmental issues. For Gen Z consumers, who are often passionate about social and environmental causes, sustainable finance represents an opportunity to align their financial goals with their values and make a positive impact on the world.

Some examples of sustainable finance products and services include green bonds, which fund environmentally sustainable projects and impact investing, which seeks to generate both financial returns and positive social or environmental outcomes. As sustainable finance continues to gain momentum, it has the potential to drive positive change and encourage more sustainable practices in the financial industry and beyond.

Personalization

personalized finance

Personalization refers to the process of tailoring products, services, or experiences to meet the specific needs and preferences of individual consumers. In the context of finance, personalization can include everything from customized investment portfolios to personalized marketing messages and offers. Personalization is becoming increasingly important as consumers, including Gen Z consumers, seek more personalized and relevant experiences from the brands and companies they interact with.

Personalization can help financial institutions build stronger relationships with their customers and provide a more engaging and satisfying experience. Some examples of personalization in finance include personalized investment recommendations based on an individual’s risk tolerance and financial goals, targeted marketing messages and offers based on an individual’s spending habits and preferences, and customized user interfaces that make it easier for individuals to manage their finances.

As technology continues to evolve, the potential for personalization in finance is only expected to grow, providing opportunities for financial institutions to differentiate themselves and better serve their customers.

Conclusion

To conclude, Gen Z is reshaping the payments and financial technology landscape with their demand for convenience, digital options, and personalized experiences. Financial services providers that can meet these needs will be well-positioned to capture the loyalty of this influential demographic. By offering P2P payments, BNPL, mobile wallets, cryptocurrency, financial education, sustainable finance, and personalization, financial services providers can stay ahead of the curve and meet the needs of this important demographic.

Embedded Finance Trends for 2023

Embedded Finance Trends for 2023: Navigating the Future of Financial Services

Embedded finance has emerged as one of the most significant trends in the financial services industry in recent years. It refers to the integration of financial products and services into non-financial applications and platforms, such as e-commerce sites, social media, and messaging apps. By offering seamless, personalized, and context-specific financial services, embedded finance has the potential to revolutionize the way people interact with money.

As we head into 2023, it is essential to examine the latest trends and developments in embedded finance and how they are likely to shape the future of financial services. In this article, we will explore some of the most significant embedded finance trends for 2023 and their implications for consumers, businesses, and financial institutions.

Top Embedded Finance Trends for 2023

The Rise of Super Apps

apps that loan money

The concept of Super Apps is not new, but it has gained significant attention and popularity in recent years. A Super App is essentially an all-in-one app that offers multiple services and functions beyond its primary purpose. It is a single platform that integrates various services, including e-commerce, payments, ride-hailing, food delivery, social media, and much more.

The Rise of Super Apps has been primarily driven by the increasing adoption of smartphones and the rise of digital platforms. With the increasing reliance on digital services, users are looking for an all-in-one solution that can cater to their diverse needs. Super Apps provide the convenience of having multiple services on a single platform, eliminating the need to download multiple apps and switch between them.

One of the most prominent examples of Super Apps is WeChat, a popular messaging app in China that has over a billion monthly active users. WeChat offers a wide range of services, including messaging, mobile payments, ride-hailing, food delivery, online shopping, and more. Users can even book doctor appointments and pay utility bills through the app.

Another popular Super App is Grab, a Southeast Asian ride-hailing and delivery platform that offers multiple services, including food delivery, e-commerce, payments, and financial services. Grab has over 100 million downloads and is expanding its services beyond ride-hailing and food delivery.

The Rise of Super Apps is also attracting the attention of traditional financial institutions, which are partnering with Super Apps to provide their services to a broader audience. For instance, Ant Group’s Alipay and Tencent’s WeChat Pay have become the primary mobile payment providers in China, with millions of users making transactions through their apps.

Super Apps are also offering new opportunities for businesses to reach a broader audience and expand their customer base. By integrating their services into a Super App, businesses can leverage the app’s user base and provide their services to a broader audience.

Open Banking and APIs

api banking

Open Banking refers to the practice of opening up banking data and infrastructure to third-party providers (TPPs) through the use of application programming interfaces (APIs). APIs are sets of protocols and standards used for building and integrating software applications. In the context of Open Banking, APIs enable TPPs to access and use banking data and services, such as account information, payment initiation, and other financial products and services offered by banks and other financial institutions.

Open Banking and APIs are designed to create a more competitive and innovative financial services industry by enabling new players to enter the market and offer more customer-centric products and services. With Open Banking, customers can use third-party apps and services to manage their finances more efficiently, access a wider range of financial products, and benefit from more personalized and tailored services.

DeFi – Decentralized Finance

defi

A new form of the financial system that operates on the decentralized blockchain network is known as DeFi or Decentralized Finance. Blockchain technology is used as the base to build financial applications. Thus, it enables peer-to-peer transactions.  No intermediaries such as banks are required to complete these transactions.

DeFi aims to make financial services accessible to everyone, regardless of their location, financial status, or credit score. It does this by using smart contracts, which are self-executing contracts that can be programmed to execute automatically when certain conditions are met.

Popular DeFi applications

Decentralized exchanges (DEXs) – These are platforms where users can trade cryptocurrencies without the need for a centralized intermediary. DEXs use smart contracts to execute trades automatically.

Lending and borrowing platforms – These platforms allow users to lend and borrow cryptocurrencies without the need for a centralized intermediary. The interest rates on these platforms are determined by supply and demand.

Stablecoins – These are cryptocurrencies that are pegged to the value of a fiat currency, such as the US dollar. They are designed to provide stability to the volatile cryptocurrency market.

Prediction markets – These platforms allow users to bet on the outcome of events, such as elections or sporting events. The prices of the bets are determined by the market, which is usually more accurate than traditional polling methods.

Digital Currencies – Digital currencies, also known as virtual currencies or cryptocurrencies, are digital assets designed to work as a medium of exchange. They use strong cryptography to secure financial transactions and to control the creation of additional units.

Digital currencies operate independently of central banks and are based on decentralized systems known as blockchain technology. They are not backed by any physical asset or government, and their value is determined purely by market supply and demand.

One of the most well-known digital currencies is Bitcoin, which was introduced in 2009. Since then, many other digital currencies have been created, including Ethereum, Litecoin, and Ripple, among others.

The use of digital currencies has grown rapidly in recent years, with many businesses and individuals accepting them as payment. They offer several advantages, including faster and cheaper transactions compared to traditional banking methods. They also provide increased privacy, as transactions can be made anonymously.

Increased Personalization

personalization

Increased personalization refers to the trend of financial institutions and technology companies tailoring their products and services to meet the unique needs and preferences of individual consumers. This trend is being driven by the availability of data and the use of advanced analytics and artificial intelligence to process that data.

Personalization can take many forms in the financial industry. For example, banks and other financial institutions may offer personalized recommendations on savings plans, investment strategies, or loan products based on a customer’s financial history, risk profile, and goals. Similarly, technology companies may provide personalized budgeting and financial planning tools that are customized to an individual’s spending habits and income levels.

The benefits of increased personalization are clear. By tailoring their offerings to individual customers, financial institutions and technology companies can improve customer satisfaction, increase engagement and loyalty, and ultimately drive growth and revenue. Additionally, personalization can help individuals make better financial decisions by providing them with more targeted and relevant information and advice.

Focus on Financial Inclusion

Financial inclusion is the process of ensuring that individuals and businesses have access to financial services and products that are affordable and meet their needs. The goal of financial inclusion is to provide access to financial services to those who have traditionally been excluded from the financial system. This can include people who live in rural areas, those who have low incomes, and those who have limited access to traditional banking services.

There are several reasons why financial inclusion is important. For one, it helps to reduce poverty and promote economic growth by giving people the tools they need to save, invest, and start businesses. Financial inclusion also helps to promote social inclusion, as it allows individuals and communities to participate more fully in society.

In recent years, there has been a growing focus on financial inclusion, particularly in developing countries where large segments of the population are unbanked or underbanked. Governments, NGOs, and private sector organizations are working to increase access to financial services through a variety of initiatives, such as microfinance programs, mobile banking, and digital payment systems.

Technology has played a key role in advancing financial inclusion, as it has enabled the development of innovative financial products and services that are accessible to a wider range of people. For example, mobile banking has become a popular way for people to access financial services, particularly in areas where traditional banking services are scarce. Digital payment systems have also made it easier for people to make transactions and manage their money, regardless of their location or financial status.

Increased Regulation

Increased regulation refers to the trend of governments and regulatory bodies imposing stricter rules and guidelines on financial institutions, such as banks and fintech companies, in order to protect consumers and maintain the stability of the financial system.

The financial crisis of 2008 highlighted the need for more robust regulation in the financial industry, and since then, there has been a push for greater oversight and transparency. The goal of increased regulation is to prevent fraudulent activities, reduce systemic risks, and safeguard consumer interests.

One of the most significant regulatory frameworks is the Basel Accords, a set of international banking regulations developed by the Basel Committee on Banking Supervision. These accords aim to ensure that banks maintain adequate capital reserves and manage risks effectively.

In addition to banking regulations, there are also increasing regulations around digital currencies, such as Bitcoin and other cryptocurrencies. Governments and regulatory bodies are looking to ensure that these currencies are not used for illicit activities, such as money laundering or terrorist financing.

Increased regulation can present challenges for financial institutions, as they need to devote more resources to compliance efforts. However, it also provides a level of assurance for consumers and helps to maintain the stability of the financial system.

Conclusion

In conclusion, embedded finance is poised to transform the financial services industry in 2023 and beyond, offering more personalized, accessible, and seamless financial services to consumers and businesses. By staying ahead of the latest trends and developments, financial institutions and fintechs can take advantage of the opportunities presented by embedded finance and provide their customers with innovative and value-added financial products and services.

Regulatory Outlook for Credit Card

Regulatory Outlook for Credit Card Processing Fees in 2023

Credit card processing fees have been a topic of concern for merchants and consumers for a long time. The fees associated with processing credit card transactions have been a significant source of revenue for banks and payment processing companies. However, over the past few years, there has been a push for regulation to curb these fees. In this article, we will discuss the regulatory outlook for credit card processing fees in 2023 and the impact it may have on the payment industry.

The payment industry has seen significant growth over the past decade. The rise of e-commerce and the increasing use of mobile devices for online purchases have made payment processing an essential part of the modern economy. However, along with this growth, credit card processing fees have also increased, becoming a significant expense for merchants. This has led to a call for regulation to limit these fees and make the payment industry more transparent.

The Credit Card Competition Act

Cardholder Data

The Credit Card Competition Act is a proposed legislation that aims to regulate credit card processing fees by introducing more competition in the industry. The act was first introduced in 2021 and is expected to be reviewed and potentially passed in 2023.

The main objective of the act is to reduce the fees charged by credit card networks and processors to merchants. The act proposes several measures to achieve this, including allowing merchants to choose which credit card networks they want to use, prohibiting credit card networks from requiring merchants to accept all of their cards, and preventing credit card networks from restricting merchants from offering discounts to customers who use lower-cost payment methods.

The act is also expected to improve transparency in the credit card processing industry by requiring credit card networks to disclose their fees and terms to merchants in a clear and concise manner.

If the Credit Card Competition Act is passed, it could have a significant impact on the credit card processing industry and the fees charged to merchants. However, it is important to note that the act is still in the proposal stage and may undergo changes before it is passed into law.

Impact of the CCCA on Payment Processing Companies

payment processing

The Credit Card Competition Act (CCCA) is expected to have a significant impact on payment processing companies if it is passed into law in 2023. As the act aims to introduce more competition in the credit card processing industry, payment processing companies will need to adapt to these changes to remain competitive and compliant with the new regulations.

One of the main impacts of the CCCA on payment processing companies is likely to be a reduction in the fees they charge merchants for processing credit card payments. As the act aims to increase competition in the industry, payment processing companies will need to reduce their fees to remain competitive and attract merchants.

To achieve this, payment processing companies may need to invest in new technologies and processes that reduce their costs and improve their efficiency. They may also need to explore new revenue streams, such as offering value-added services to merchants, to offset the reduction in fees.

The CCCA is also expected to improve transparency in the credit card processing industry, which could benefit payment processing companies that are transparent in their pricing and terms. Companies that are transparent and clear in their fees and services may be more attractive to merchants who are looking for clarity and simplicity in their payment processing.

The impact of the CCCA on payment processing companies will depend on how they adapt to the new regulations and competition in the industry. Companies that are able to innovate and offer value to their merchants while remaining compliant with the new regulations are likely to thrive in the changing landscape of the credit card processing industry.

Impact of the CCCA on Merchants

newtek merchant solutions review

The Credit Card Competition Act (CCCA) is expected to have a significant impact on merchants if it is passed into law in 2023. As the act aims to introduce more competition in the credit card processing industry, merchants may see changes in the fees they are charged for processing credit card payments and have more options to choose from.

One of the main impacts of the CCCA on merchants is likely to be a reduction in the fees they are charged by credit card networks and payment processing companies. As the act aims to increase competition in the industry, merchants may be able to negotiate lower fees or switch to payment processing companies that offer more competitive pricing.

The CCCA may also give merchants more control over which credit card networks they use and which cards they accept. Currently, merchants are often required to accept all cards from a particular network, even if some cards have higher processing fees. The CCCA would allow merchants to choose which networks and cards they want to accept, potentially reducing their processing costs.

The act is also expected to improve transparency in the credit card processing industry, which could benefit merchants by providing them with more information about the fees they are charged and the services they receive. This increased transparency may help merchants to make more informed decisions about which payment processing companies and credit card networks to work with.

Overall, the impact of the CCCA on merchants will depend on how they adapt to the new regulations and competition in the industry. Merchants that are able to negotiate lower fees, choose the payment processing companies and credit card networks that work best for them, and take advantage of new innovations in the industry are likely to benefit from the changing landscape of the credit card processing industry.

Regulatory Outlook in 2023 for the Payment Industry

The payment industry is a heavily regulated sector, and there are several regulatory trends that are shaping the industry’s future. These trends include the following:

Digital Identity Verification: Regulatory bodies are increasingly focusing on digital identity verification to prevent fraud and improve security in payment transactions. As such, payment companies are required to implement stricter identity verification measures to ensure the safety and security of transactions.

Open Banking: Open banking refers to the practice of opening up banking data and services to third-party providers. This trend is becoming increasingly popular as it enables new entrants to offer innovative payment services and products, resulting in increased competition and better pricing for consumers.

Data Protection: Data protection is a key regulatory trend in the payment industry. Companies are required to ensure that they handle customer data securely and that they comply with data protection regulations, such as GDPR in Europe and CCPA in California.

Cross-border Payments: Cross-border payments are becoming more prevalent as the world becomes more connected. Regulatory bodies are increasingly focusing on developing regulations to ensure that cross-border payment transactions are secure, efficient, and transparent.

Payment Innovation: Regulatory bodies are actively encouraging payment innovation to promote the development of new payment technologies and products. As such, payment companies are investing heavily in research and development to create innovative payment solutions that meet the changing needs of consumers.

Regulatory trends in the payment industry are focused on improving security, promoting innovation, and increasing competition. Payment companies that stay ahead of these trends and adapt to new regulatory requirements are likely to succeed in the evolving payment landscape.

Conclusion

The regulatory outlook for credit card processing fees in 2023 is complex and evolving. The introduction of the Credit Card Competition Act and other regulatory trends will likely result in increased competition and greater transparency in the credit card industry. Merchants may benefit from reduced processing fees, but payment processing companies will need to adapt to new regulations and find new ways to generate revenue.

It is clear that regulatory bodies are committed to promoting innovation and competition in the payment industry while ensuring that transactions are secure and transparent. Payment processing companies must continue to invest in research and development to create innovative payment solutions that meet evolving consumer needs and comply with new regulatory requirements.

To summarize, the regulatory landscape for credit card processing fees in 2023 is one of change and uncertainty. Payment processing companies and merchants must stay informed about regulatory developments and adapt to new requirements to succeed in the dynamic payment industry. By embracing innovation and remaining vigilant about compliance, payment processing companies and merchants can thrive in the evolving payment landscape.

Why Did Silicon Valley Bank Fail

Why Did Silicon Valley Bank Fail and What Does it Mean for the Banking System?

Silicon Valley Bank (SVB), a California-based financial institution, was once known as a champion of the tech industry, providing loans and services to many of the biggest names in the sector. However, in March 2023, the bank collapsed, causing shockwaves throughout the financial world. In this article, we’ll take a deep dive into why did Silicon Valley Bank fail, and what its collapse means for the broader banking system.

Silicon Valley Bank – The Background

image
Image source

Silicon Valley Bank (SVB) was founded in 1983 with a focus on providing banking services to technology startups in Silicon Valley. The bank’s mission was to support the growth of technology companies by providing them with the financial resources they needed to succeed. It was the time, older banks were reluctant to lend funds to startups. The reason being these start-ups are seen as high-risk businesses with uncertain revenue streams. SVB looked at this gap as an opportunity and tried to fill in and thus became the first of a few banks to specialize in lending to technology startups.

Over time, SVB’s focus expanded beyond Silicon Valley to include other technology hubs in the United States and around the world. The bank’s services also expanded beyond lending to include a bigger range of banking and financial services, such as cash management, foreign exchange, and venture capital financing.

SVB quickly became a well-respected institution in the technology industry, with a reputation for understanding the unique needs and challenges faced by technology startups. The bank’s success was fueled by the rapid growth of the technology industry in the 1990s and 2000s, which created a steady stream of new startups in need of financing.

However, as the technology industry matured, SVB faced increasing competition from traditional banks and many financial companies. The bank’s concentration in lending to technology startups also made it vulnerable to economic downturns, as these startups are often the first to feel the effects of a recession.

In the years leading up to its collapse, SVB had struggled with a high level of non-performing loans, declining profitability, and an inadequate level of capital to absorb losses. These factors ultimately led to the bank’s failure and the subsequent fallout for the banking system as a whole.

Why Did Silicon Valley Bank Fail? The Warning Signs

There were several warning signs leading up to the collapse and fall of SVB. The most significant was the bank’s high level of non-performing loans. Non-performing loans are loans that are in default or are not being repaid according to the original terms of the loan agreement. In the case of SVB, the bank had a significant number of loans that were not being repaid, which put a strain on the bank’s capital reserves and profitability.

Another warning sign was the declining profitability of the bank. SVB had experienced a decline in profitability in the years leading up to its collapse, which was due in part to the high level of non-performing loans. Additionally, the bank had been facing increasing competition from traditional banks and other financial institutions, which put pressure on its revenue streams.

The inadequate level of capital to absorb losses was another warning sign. Banks are required to maintain a minimum level of capital to absorb losses and protect depositors. However, SVB had a low level of capital relative to the size of its loan portfolio, which made it vulnerable to losses in the event of a downturn in the economy.

Finally, there were concerns about the bank’s risk management practices. SVB had a reputation for taking on risky loans and investing in high-risk ventures. While this approach had served the bank well in the early years, it had become increasingly risky as the technology industry matured and economic conditions became more uncertain.

The Collapse

The Silicon Valley Bank (SVB) debacle occurred in the aftermath of the global financial crisis of 2022-2023. The crisis had a significant impact on the technology industry, which had been a  primary driver of SVB’s growth and success. Many of the bank’s borrowers were technology startups that were hit hard by the crisis and were unable to repay their loans.

As the number of non-performing loans increased, SVB’s capital reserves were depleted, and the bank was forced to take write-downs on its loan portfolio. This put further pressure on the bank’s profitability and capital position, making it increasingly vulnerable to losses.

In an attempt to shore up its finances, SVB raised additional capital from investors, but this proved insufficient to address the bank’s underlying problems. Eventually, the bank was unable to meet its obligations and was forced to declare bankruptcy.

The Fallout

The fallout of SVB was significant and far-reaching. The most immediate effect was the loss of jobs and livelihoods for the bank’s employees and clients. Many of the bank’s clients were technology startups that relied on SVB for funding, and the fall of the bank left them without access to the capital they needed to continue operating.

The failure of SVB also had wider implications for the financial system as a whole. It undermined confidence in the banking system and raised concerns about the stability of other banks and financial institutions. There were fears that the failure of SVB could trigger a wider financial crisis, similar to the one that occurred in 2008.

In response to the falling of SVB, regulators and policymakers took a number of steps to shore up the financial system and prevent similar failures from occurring in the future. These included reforms to strengthen bank regulation and supervision, improvements in risk management practices, and the development of contingency plans to address potential bank failures.

The SVB catastrophe also led to a wider debate about the role of technology in the economy and the risks associated with investing in high-growth, high-risk industries. Some analysts argued that the failure of SVB was a symptom of a broader problem with the technology industry, which was characterized by a high degree of speculation and risk-taking.

Effect on Banking System?

The Silicon Valley Bank fall had significant implications for the banking system as a whole, highlighting a number of key issues that regulators and policymakers needed to address.

A significant implication of the disruption of SVB was the impact it had on the perception of the banking industry as a whole. The failure of this most prominent bank in the technology industry raised concerns about the health of the broader banking system and led to a loss of confidence among investors and the public.

Another key implication of the failure of SVB was the need for greater regulatory oversight of the banking industry. The failure of the bank highlighted the risks associated with lending to high-growth, high-risk industries, and underscored the need for regulators to have greater visibility into the activities of banks and to have the tools and resources they need to identify and mitigate potential risks.

The destruction of SVB also raised questions about the effectiveness of the existing regulatory framework for banks. Many analysts pointed to the fact that the bank had a considerable scope  of regulatory oversight, yet still failed, highlighting the need for reforms to strengthen the regulatory framework and ensure that regulators have the tools and resources they need to identify and address potential risks.

The crash of SVB highlighted the attention of diversification in banking. The bank had become heavily reliant on lending to the technology industry, leaving it vulnerable to the specific risks associated with this industry. This underscored the relevance of banks diversifying their loan portfolios and reducing their reliance on any one industry or sector.

Effect on Tech Industry?

Silicon Valley Bank (SVB) collapse had significant implications for the tech industry, which had been heavily reliant on the bank for financing and other services.

A key implication of the downfall of SVB was the impact it had on access to financing for tech startups. SVB had been a major provider of financing to the tech industry, and its collapse left many startups without access to the funding they needed to grow and expand their businesses.

The collapse of SVB also had a broader impact on the health of the tech industry as a whole. The loss of confidence in the banking system and the regulatory framework that followed the SVB debacle made it more difficult for startups to attract new investors and customers and led to a slowdown in the growth of the industry as a whole.

The SVB fall and collapse also highlighted the need for greater transparency and accountability in the tech industry. Many analysts pointed to the fact that the bank had been subject to a gamut of regulatory oversight, yet still failed, highlighting the need for reforms to strengthen the regulatory framework and ensure that companies are held accountable for their actions.

Reasons for Silicon Valley Bank’s Failure

Risky Loans: Silicon Valley Bank’s portfolio was heavily concentrated in loans to technology startups. These startups were often high-risk ventures that had not yet proven their ability to generate revenue. When the economy took a downturn, many of these startups were unable to pay back their loans, leading to massive defaults.

Poor Risk Management: Despite the high-risk nature of the loans, Silicon Valley Bank did not have adequate risk management measures in place. This meant that the bank was not properly prepared for the level of defaults that occurred.

Overreliance on Deposits: Silicon Valley Bank was heavily reliant on deposits from technology startups. When these startups began to fail, the bank was left with a large amount of non-performing loans and a severe lack of liquidity.

Inadequate Capital: Silicon Valley Bank did not have enough capital to absorb the losses from the defaults. This meant that the bank was unable to stay afloat when the defaults began to pile up.

What Does This Mean for the Banking System in the Future?

bank

Greater Scrutiny: This collapse has led to greater scrutiny of banks that heavily rely on one industry or type of borrower. Regulators are now looking at the risks associated with lending to startups and other high-risk ventures.

Need for Better Risk Management: The SVB has highlighted the need for better risk management measures in banks. Banks must have adequate safeguards in place to ensure that they can weather economic downturns and mitigate risk.

Importance of Capital Adequacy: Silicon Valley Bank’s collapse has also emphasized the emphasis of having adequate capital to absorb losses. Banks must have enough capital to withstand even severe economic shocks.

Ripple Effects: The collapse could have ripple effects throughout the banking system. Other banks that have lent heavily to technology startups may also face a wave of defaults and losses.

Conclusion

breakdown of the largest banks in usa

The collapse of SVB is a stark reminder of the fragility of the banking system. The bank’s failure was caused by a combination of risky loans, poor risk management, overreliance on deposits, and inadequate capital. The aftermath of the collapse has led to greater scrutiny of banks that heavily rely on one industry or type of borrower, the need for better risk management measures in banks, the gravity of capital adequacy, and the possibility of ripple effects throughout the banking system.

It is essential for banks to learn from Silicon Valley Bank’s collapse and take steps to ensure that they are adequately prepared for economic shocks. With better risk management measures, greater capital adequacy, and a more diversified portfolio of borrowers, banks can better withstand economic downturns and contribute to a more stable financial system.

Surcharge Rules By Visa

Updates to Surcharge Rules By Visa in the US and Canada as of April 15, 2023

Visa has recently announced updates to its surcharge rules for merchants operating in the US and Canada. Effective as of April 15, 2023, merchants in these two countries will now be subject to updated terms related to credit card surcharging.

In this article, we will explore these new surcharge rules by Visa and related updates to analyze their potential impact on consumers and merchants.

What are the new surcharge rules by Visa?

Starting on April 15, 2023, Visa, one of the largest payment networks in the world updated its surcharge rules for merchants in the US and Canada. The new rules have a few implications for merchants, with the main implication being that Visa will now impose a restriction on credit card surcharges and will only allow merchants to charge a maximum of 3% on each transaction. In addition to Visa lowering the maximum surcharge amount from 4% to 3%, merchants are also now only required to notify their acquirers, not Visa, 30 days before beginning surcharging a surcharge program.

Under the new rules, merchants must disclose the surcharge amount to the customer either at the point of sale or on the customer’s receipt. The surcharge amount must be displayed in dollars and cents, and it must not exceed the merchant’s actual cost of accepting Visa credit cards. If a merchant invoices a customer for services and implements a surcharge, they are obligated to disclose the surcharge amount on the invoice.

It’s worth noting that the new rules apply only to credit card transactions processed through Visa payment networks. It is prohibited by federal law for merchants to impose a surcharge on debit card transactions processed through Visa and other payment networks, such as Mastercard, American Express, or Discover.

It’s important to note that not all merchants choose to apply surcharges to credit card transactions. Some merchants may choose not to apply surcharges due to the risk of upsetting their customers or because the cost savings of applying surcharges may not outweigh the potential negative impact on customer satisfaction.

What is the reason for the updates?

There are many reasons why Visa made updates to their surcharge rules in the United States and Canada. One of the speculations around why Visa may have updated their rules is because by making minor adjustments to the maximum surcharge limit, this will help the card networks mitigate their risk and it is a preventative measure to handling customer dissatisfaction.

The new rules enable merchants to apply a surcharge to credit card transactions processed through Visa payment networks, as long as certain conditions are met. These conditions include disclosing the surcharge amount to the customer before the transaction takes place and ensuring that the surcharge amount does not exceed the merchant’s actual cost of accepting Visa credit cards.

The updates to Visa’s surcharge rules are intended to give merchants more flexibility when it comes to processing credit card transactions and to promote transparency in pricing. By allowing merchants to apply surcharges to credit card transactions, customers can better understand the true cost of using credit cards for purchases, which can help them make more informed spending decisions. This could potentially result in more customers purchasing with cash if businesses intend to surcharge customers when using a credit card.

What is the impact on consumers?

consumer with card

The impact of the updates to Visa’s surcharge rules on consumers is a matter of debate. Some consumer advocates have expressed concern that the new rules could lead to higher prices for consumers, as merchants may seek to pass on the cost of accepting credit cards to their customers through surcharges.

However, it’s important to note that merchants are required to disclose the surcharge amount to customers before the transaction takes place, either at the point of sale or on the customer receipt. This means that customers will have the opportunity to make a decision about whether or not to proceed with the transaction, based on the disclosed surcharge amount.

In addition, the new rules only apply to credit card transactions processed through Visa payment networks. Customers can still use other forms of payment, such as debit cards or cash, to avoid potential surcharges. Furthermore, not all merchants may choose to apply surcharges, as they understand it’s potential negative impact on customers.

The impact of the updates to Visa’s surcharge rules on consumers remains to be seen. While some consumers may be unhappy about the potential for surcharges, others may appreciate the increased transparency in pricing that the new rules provide.

It’s important for consumers to be aware of the new surcharge rules and to carefully consider their payment options when making purchases, in order to make the best financial decisions for their individual circumstances.

What is the impact on merchants?

The updates to Visa’s surcharge rules will have a significant impact on merchants. The new rules give merchants the option to apply a surcharge to credit card transactions processed through Visa payment networks, which can help them offset the cost of accepting credit card payments. It is important to note that surcharging programs are illegal in Connecticut and Massachusetts, so this update excludes those states.

This can be particularly beneficial for small businesses that may have tight profit margins and may struggle to absorb the fees associated with credit card transactions. By applying a surcharge, merchants can pass on some of the costs to customers who choose to pay with credit cards, while still accepting credit card payments as a payment option.

However, it’s important to note that merchants who choose to apply surcharges must comply with certain conditions, such as disclosing the surcharge amount to customers before the transaction takes place and ensuring that the surcharge amount does not exceed their actual cost of accepting Visa credit cards.

In addition, merchants may need to update their point-of-sale systems and provide staff training to ensure that they are able to accurately calculate and apply surcharges in accordance with the new rules. Failure to comply with the rules can result in legal action and financial penalties.

The impact of the updates to Visa’s surcharge rules on merchants is mixed. While the ability to apply surcharges may provide some cost relief for merchants, it also comes with added compliance requirements and potential legal risks. It’s important for merchants to carefully consider the potential benefits and drawbacks of applying surcharges and to ensure that they are in compliance with all relevant regulations.

What should consumers and merchants do?

Visa 22456825

Consumers and merchants both have a role to play in adapting to the updates to Visa’s surcharge rules. Here are some steps that both groups can take:

For consumers:

Be aware of the potential for surcharges when making credit card purchases through Visa payment networks.

Read any signage or disclosures at the point of sale or on the receipt to determine if a surcharge will be applied.

Consider using alternative payment methods, such as debit cards or cash, if surcharges are a concern.

Compare prices and fees across different merchants to make the most informed purchasing decisions.

For merchants:

Determine whether or not to apply surcharges based on careful consideration of the potential benefits and drawbacks.

Ensure compliance with all relevant regulations and conditions for applying surcharges.

Train staff on how to accurately explain to customers how surcharges are applied in accordance with the new rules.

Consider updating point-of-sale systems to ensure that surcharges are applied accurately and transparently.

It’s also important for both consumers and merchants to stay up to date on any further updates or changes to Visa’s surcharge rules, as they may impact their respective roles and responsibilities. By working together to adapt to the new rules, both groups can help ensure that credit card payments through Visa payment networks continue to be a viable and convenient option for everyone involved.

Conclusion

The updates to Visa’s surcharge rules in the US and Canada that became effective on April 15, 2023, represent a significant change for consumers and merchants. While the impact on consumers is likely to be relatively modest, merchants will need to carefully consider whether or not to apply surcharges, and if so, how to do so in compliance with the new regulations.

In order to comply, merchants are implementing a cash discount program which is legal in all 50 states compared to compliant surcharging which is only legal in 48 states. Visa has stated that a true cash discount program is outside the purview of the surcharge rules. Visa has also said that they along with the other card networks are not able to prohibit merchants from offering a discount for any payment method that the merchant allows their customers to use, even cash. They have made it clear that there is no limit on the size of the discount the merchant can offer to their customers.

Ultimately, the updates to Visa surcharging will impact merchants directly, however it truly depends on if the merchant decides to absorb the costs or include their customers as a part of helping pay these fees. With careful attention to the details of the new rules and a commitment to maintaining clear communication and compliance, merchants can continue to provide top tier shopping experiences for their customers and maintain a compliant standing when processing credit card payments through Visa’s card networks.