Author Archives: hostmerchantservices

Top Job Website Alternatives to Indeed

Top Job Website Alternatives to Indeed

The job market is vast, with about 50% of employees considering changing jobs in 2024 and 85% planning to explore new job opportunities. Many are turning to job portal sites and apps to find new roles, locations, and better compensation.

Indeed is currently one of the most popular job-seeking platforms. However, it has several issues, including scams, irrelevant job matches, and intense competition. Consequently, job seekers are exploring additional platforms beyond Indeed to increase their visibility.

This blog will be useful if you have encountered these issues and are searching for reliable alternatives to Indeed. We will guide you through some well-reviewed platforms to enhance your job search. Let’s explore these alternatives before downloading any apps or visiting any websites.
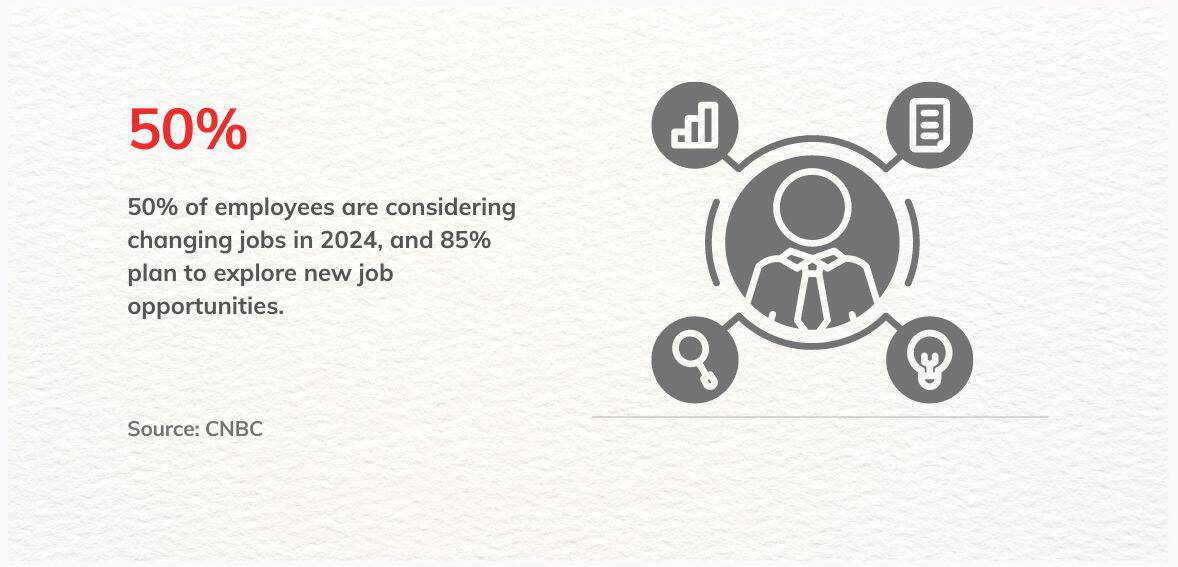
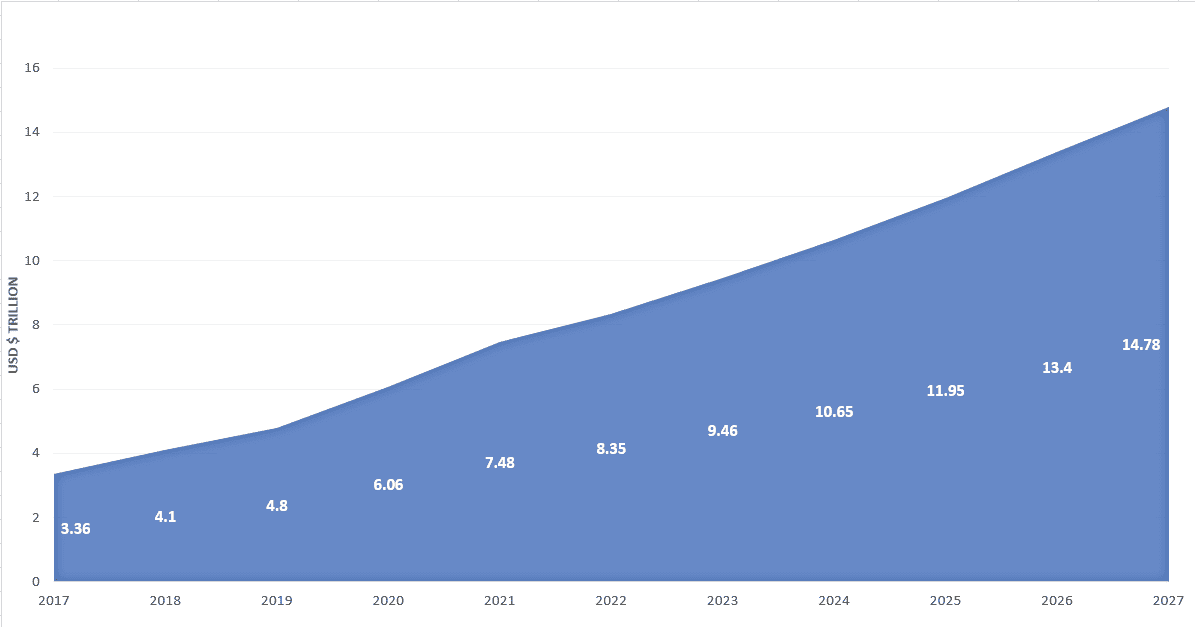
US job infographics

Source: CNBC

Best Alternatives to Indeed in 2026

In today’s dynamic environment, locating suitable talent for your business can be difficult. However, job portals offer a solution to streamline your recruitment efforts. Here are some top job portals for posting vacancies in 2024.

1. LinkedIn

Advantages

  • Excellent for professional networking
  • Simplifies the process of locating and contacting recruiters and managers
  • Facilitates the display of past employment and achievements

Disadvantages

  • Frequent spam and scam messages
  • Some job postings are outdated or already filled
  • Top job search functionalities are exclusive to premium members
LinkedIn

Image source

LinkedIn, founded in 2003, is the largest global professional networking platform, boasting 875 million users from various industries worldwide. It functions simultaneously as a repository for job openings, a digital resume hub, and a platform for professional social networking.

Your LinkedIn profile acts as a public digital resume and portfolio. Once you apply for a position, it is shared with recruiters, making it crucial to dedicate time and effort to ensure it is comprehensive, accurate, and optimized for searches. Creating a LinkedIn profile and exploring job opportunities is free, but a monthly premium subscription is available for $39.99. This subscription offers additional features like seeing who has viewed your profile, obtaining detailed insights about other candidates for the jobs you are interested in, and the option to message people you haven’t connected with yet.

You can use your LinkedIn profile to apply for jobs and send connection requests—similar to friend requests on Facebook—to expand your professional network. If your profile is search-optimized, recruiters might also contact you directly to discuss specific job opportunities.

LinkedIn Key Features
  • Strong professional networking features
  • Job listings across various industries
  • Resources for skill validation and peer recommendations
  • Accessible via both web and mobile applications
LinkedIn Pricing

LinkedIn provides multiple Premium subscription options tailored to different needs, all available at varying prices. As mentioned, the Premium Career plan costs $39.99 monthly and is designed for individuals looking to advance their careers.

The Premium Business plan is available for businesses expanding their professional networks at $47.99 monthly. The Sales Navigator Core, priced at $79.99 per user monthly, offers specialized tools for sales professionals. Lastly, the Recruiter Lite option, which costs $140 per month, caters to those in hiring and recruitment.

2. ZipRecruiter

Advantages

  • Unlike other job platforms that require a 30-day commitment to job postings,
  • ZipRecruiter offers flexibility by allowing employers to replace job openings as soon as they are filled.
  • The platform’s candidate search and application review tools simplify organizing and filtering applicants to identify suitable candidates efficiently.
  • ZipRecruiter’s distribution network helps employers quickly attract more qualified candidates.

Disadvantages

  • Users sometimes receive applicants who need to meet the job qualifications.
  • ZipRecruiter may be too expensive for some smaller companies.
  • The platform needs to include features to assess candidates’ skills effectively.  
ZipRecruiter

Image source

ZipRecruiter is recognized as a leading model in the online job market that many businesses aim to replicate. As a job portal, it facilitates the connection between job seekers and employers, offering a straightforward way to match skilled candidates with recruiters.

Since its launch in 2010, it has become a popular choice among online recruitment platforms, with 430 million applications submitted through the site to date. It stands out as a top alternative to other job portals like Indeed.

ZipRecruiter Key Features
  • Distribute your job posting to over 100 sites with a single click.
  • Organize and evaluate candidates using a unified dashboard.
  • Encourage applications by sending pre-written, personalized invitations to candidates.
  • Receive personalized job recommendations through AI-driven matching.
  • Get immediate notifications for updates on new job listings.
ZipRecruiter Pricing

ZipRecruiter offers a four-day free trial with various pricing plans tailored for SMBs. The cost of using ZipRecruiter’s Standard and Premium plans is based on the number of job postings an employer needs.

Employers can opt for a discounted monthly rate, paying a flat rate for each job posting monthly. After the trial, the Standard plan is $16 per day per job or $299 monthly. The Premium plan is $24 per day per job or $419 monthly. The Pro plan is available at $719 per month.

3. Monster

Advantages

  • Intuitive interface for straightforward use.
  • Community-based networking possibilities.
  • Customized job suggestions according to user profiles.Includes a tool for comparing salaries.

Disadvantages

  • Some users experience intermittent problems during the application process.
  • Intense competition for sought-after job positions.    
Monster

Image source

Monster has been a prominent job search platform for 25 years, continually adapting to maintain its competitiveness. The website provides essential tools such as job search engines that allow users to filter opportunities by keywords and companies, and it also enables users to upload their resumes directly.

To set itself apart, Monster has significantly invested in developing its mobile applications for iOS and Android. The app is well-regarded for its user-friendly design and includes features like one-click applications and swipe-to-apply functionality.

Additionally, the site offers extra resources aimed at job seekers, especially recent college graduates in need of guidance for job hunting. Among these resources, its free resume assessment is precious, providing users with useful feedback alongside tools for salary and career advice.

Monster Key Features
  • Unlimited access to resume searches
  • Unlimited number of job applicants
  • Job postings that can be used multiple times
  • Email notifications sent to potential candidates about your job
  • Email notifications are sent to you about new resumes that match your criteria
  • A performance enhancement feature that distributes your listing across hundreds of additional sites
Monster Pricing

Monster offers three different plans. Monster+ offers job listings at $12 per day for each posting. For those seeking more features, the Standard Upgrade is $399 per month and includes up to three active job listings. Alternatively, the Premium Upgrade provides up to five active monthly job listings for $649.

4. Glassdoor

Advantages

  • No cost for job seekers.
  • Transparent access to salary and employer details.
  • Numerous company reviews from employees.

Disadvantages

  • Limited profile customization options.
  • Employee reviews may exhibit positive or negative biases.   
Glassdoor

Image source

Glassdoor is a job search website where employees can anonymously post details about their companies, including salary data, benefits, and company reviews. As one of the pioneering platforms to gather such data, Glassdoor has accumulated a vast database of salary information, which is highly useful for job seekers researching potential employers.

However, it’s important to approach the information on Glassdoor with caution since it predominantly comes from user submissions. The data may not always be reliable, and employees can post negative reviews about their employers. Job candidates should consider this information alongside more verifiable data to make well-rounded employment decisions.

Glassdoor Key Features
  • Allows job seekers to make informed decisions by providing reviews and ratings from current and former employees.
  • Provides detailed information about salary ranges and benefits
  • Users can find job postings spanning a wide range of sectors
  • Job seekers can create profiles where they upload resumes and detail their job preferences
  • Users can set alerts for specific types of jobs, ensuring they receive immediate updates when new postings that fit their criteria become available
  • Glassdoor provides valuable educational materials that offer guidance on job market trends and tips for job seekers
Glassdoor Pricing

Glassdoor provides its services for free to job seekers but charges businesses based on their size and selected service tier. The cost ranges from $13,400 to $27,000 for businesses with up to 200 employees. This price increases for larger organizations; businesses with around 1,000 employees can expect to pay between $13,900 and $25,700. For those exceeding 1,000 employees, prices vary from $33,900 to $64,700.

Additionally, Glassdoor has three service tiers. The ‘Standard’ tier costs between $252 and $356, while the ‘Select’ tier ranges from $744 to $4,719. The ‘Free’ tier is available at no cost. Contact Glassdoor’s sales department directly for more detailed pricing, particularly for the ‘Select’ tier. Keep in mind these prices are approximate and may change. Always verify the current rates with Glassdoor before making a decision.

5. Snagajob

Advantages

  • Straightforward employee onboarding.
  • Attentive customer support.Adaptable to specific company requirements.

Disadvantages

  • Limited options for customizing reports.
  • Advertisements around job postings can create a cluttered appearance.

Snagajob

Image source

Snagajob is a job platform tailored for hourly workers. It allows employers to post jobs at no cost while also offering premium services to enhance the visibility of their job listings. The platform includes advanced search filters and an applicant tracking system to help employers manage hiring processes efficiently.

Established in 2000, Snagajob has grown to be a leading online marketplace for hourly employment, connecting workers with local job opportunities.

The site primarily lists hourly positions in sectors such as healthcare, best resume writers, customer service, hospitality, retail sales, security, and food delivery. Job seekers can filter their search to find part-time or full-time jobs, including those labeled as “Urgently Hiring.”

To apply for a job, click the “Apply Now” button, which will direct you to the employer’s website. Additionally, by registering with Snagajob, you can sign up to receive email alerts for new job listings that align with your interests.

Snagajob Key Features
  • Specializes in hourly and part-time job listings
  • Mobile-optimized platform for job searching on the move
  • Tools for tracking applications, simplifying management
Snagajob Pricing

Snagajob necessitates contacting the company directly to obtain comprehensive pricing information. However, their job posting registration page indicates that pricing begins at $89 per month.

6. Wellfound

Advantages

  • Ideal platform for discovering startup companies
  • Efficient job listing search capabilities
  • Robust profile creation tools for job seekers
  • Specialized website for locating startup job opportunities
  • Transparent information on salary and equity
  • Offers both local and remote positions at startups

Disadvantages

  • There is a smaller selection of jobs than on some other platforms
  • Exclusively lists startup roles

Wellfound

Image source

Wellfound is dedicated to startup and tech job listings. It features a comprehensive job board where job seekers can access extensive details about each position, such as salary and benefits. The website’s application process is streamlined, enabling users to upload their resumes and apply for jobs with a single click. Additionally, the platform offers a feature to monitor the status of job applications directly on the site.

A notable aspect of Wellfound is the customizable profile settings, which allow users to outline preferences such as desired company size, location, and other attributes. Users can also indicate the type of work environment and company culture they seek.

Wellfound Key Features
  • Enables job seekers to connect directly with founders and hiring managers at top startups
  • Allows job seekers to create detailed profiles
  • Wellfound provides sophisticated search filters and an applicant tracking system.
  • Clear and user-friendly interface
  • Effective job seeker profiling via quizzes
Wellfound Pricing

Wellfound, previously known as AngelList Talent, provides job posting services at no cost, targeting individuals in the technology and startup sectors. The platform boasts a reach of over 10 million potential candidates and includes features such as sophisticated search filters, direct messaging capabilities, and an applicant tracking system. For those seeking more specialized functionalities, Wellfound offers a variety of paid plans.

The “Recruit Pro” plan is $499 per month and comes with enhanced search capabilities, pitch templates, instant scheduling, and options to access resumes and social media profiles. Additionally, Wellfound has a “Curated” service that gives recruiters access to select candidates who are prepared for interviews, with the possibility to negotiate custom packages tailored to meet specific recruitment needs.

Conclusion

Navigating the job market can be challenging, especially with the pitfalls some popular platforms like Indeed present. Job seekers facing issues such as scams, irrelevant matches, and high competition can benefit from exploring alternative job portals. Each highlighted platform—LinkedIn, ZipRecruiter, Monster, Glassdoor, Snagajob, and Wellfound—offers unique advantages tailored to different needs.

LinkedIn stands out for professional networking and comprehensive profile management, while ZipRecruiter’s flexibility and powerful search tools are excellent for employers. Monster’s user-friendly interface and additional resources are great for job seekers, particularly recent graduates. Glassdoor provides valuable insights into company cultures and salaries, though its user-generated content should be considered carefully. Snagajob specializes in hourly and part-time positions, making it ideal for those sectors. Finally, Wellfound caters to the tech and startup community with a focus on transparency and efficient application processes.
7 Steps for Manufacturing a Product

7 Steps for Manufacturing a Product

Manufacturing a product involves crucial steps that transform raw materials into finished goods ready for market. This process requires meticulous planning, precise execution, and a deep understanding of various production techniques. This guide outlines the seven essential steps for manufacturing a product, offering insights and best practices to ensure efficiency, quality, and compliance with industry standards.

What Is Manufacturing?

Manufacturing involves transforming raw materials into finished products through multiple steps. This includes design, material selection, processing, assembly, and quality assurance. The goal is to enhance the value and utility of the original materials, resulting in diverse products such as household items, electronics, vehicles, and construction materials. This complex process is crucial for economic growth as it generates employment, encourages innovation, and drives technological progress.

Manufacturing goes beyond just assembling items. It combines innovation, efficiency, and sustainability. It incorporates advanced technologies and methods to address changing societal needs. Manufacturing is not limited to heavy machinery or large-scale production; it also involves precision, customization, and various skills across different industries and sizes.

7 Steps for Manufacturing a Product

7 Steps for Manufacturing a Product

1. Conceptualize and Ideate the Product

At this initial stage, a product’s functional and performance specifications and detailed profiles of target customers and their needs are established. During this phase, customer needs and ideas for innovative functions are discussed and evaluated to identify effective solutions that meet specific market demands.

This stage serves as the foundation for the final product. If you don’t yet have a concept, you can generate one through team brainstorming sessions. Key topics for discussion should include:

  • Demand:

When assessing the need for a product, it is essential to determine if there is an actual demand for it. Consider whether the product addresses a specific issue or enhances the user experience. Analyze the market to see if other products meet this need and identify how your product differs from these offerings.

It’s crucial to pinpoint what unique value or innovation your product brings to the market that sets it apart from the competition.

  • Target Market:

For the market aspect, it is important to identify who the product is intended for. It is vital to clearly understand the target audience’s demographics, behaviors, and preferences. Assess who will use the product and how they will use it, ensuring the market you are targeting is accessible.

Additionally, determine the potential market size and thoroughly analyze the competition to gauge your product’s position and what market share it might capture.

  • Resources:

In terms of resources, evaluate your company’s resources, including manpower, space, and financial capacity, to ensure you can meet production and distribution demands. Consider operational needs such as storage, handling, and inventory management and whether you have the infrastructure and staff to support these functions.

Also, assess your ability to dedicate time to manage all stages of the product life cycle, from production through to delivery and customer support.

  • Budget:

Understanding the cost structure is critical to maintaining profitability. This includes analyzing expenses related to raw materials, labor, and overhead. While precise cost figures may not be available initially, obtaining preliminary estimates will help establish a baseline for expected costs.

Engage with multiple suppliers to secure competitive pricing and gain insights into cost variability, vital for effective budgeting and financial planning.

2. Design Your Product

Design Your Product

At this stage, armed with insights from your research, begin designing your product. Always prioritize the customer’s needs and usage expectations. Also, any production constraints identified during the research phase should be considered. This is when the design process is closely integrated with research and development.

Expressing your vision clearly is crucial, as others cannot visualize your ideas without assistance.

If you possess skills in graphic design, leverage them to create your product design. However, artistic expertise is not required; the primary goal is to convey your concept clearly to others, such as local craftsmen, who will help realize your vision. Do your best, and remember to record the date of your design to secure your ideas when discussing them with others.

To document the date of your idea, consider these methods:

  • Metadata of digital files: This can verify the original date of your concept.
  • Physical documentation: Date any drawings, photograph them, and email the images to yourself to create a timestamp.
  • Obtain notarization: While it may seem excessive, having a notary witness authenticate your signature and the date on the document could be beneficial if the idea holds significant value.

3. Develop a Prototype

Creating a prototype of your product is essential before seeking a manufacturer. It doesn’t need to be the final version; start with a basic, functional model.

This phase is crucial in product development, allowing you to refine your design through various iterations until it’s ready for mass production. However, not all prototypes can be made at home—constructing complex items like wireless headphones or high-performance computers is more challenging than simpler projects like lamps or wallets. If creating a prototype on your own isn’t feasible, you might need to collaborate with others during this step.

Many entrepreneurs turn to third parties for prototyping. However, small to medium businesses often find that they don’t require the services of expensive product development consulting firms. Instead, tap into your own network for support. Seek advice from someone experienced in manufacturing who can offer mentorship. Utilizing the expertise within your circle can be invaluable and help pave the way for your product’s success.

Remember to Protect Your Idea

At this point, it is important to secure legal measures to prevent others from copying and selling your product. You might consider a Non-Disclosure Agreement (NDA). An NDA formed between you and your collaborators limits the disclosure of details about your product and its manufacturing process.

Another protective measure is the Non-Compete Agreement, typically established between you and your manufacturer or other crucial partners. This agreement prevents these parties from using your ideas to establish a competing business or to develop similar products.

In the United States, you can also apply for a patent on your product within one year after its first sale. Holding a patent grants you the sole rights to manufacture, use, and sell your invention, which bars others in the U.S. from doing so. However, it’s important to note that a U.S. patent does not prevent international entities from duplicating your design since they do not fall under U.S. jurisdiction.

4. Find a Manufacturer

Find a Manufacturer

After finalizing a product prototype that meets your expectations, the next step is to collect the necessary materials and establish relationships with production partners. This phase involves creating your supply chain, which includes selecting vendors, organizing activities, and managing resources essential for manufacturing and delivering the product to customers.

Finding a manufacturing partner involves several steps, especially if you move beyond small-scale, home-based production like sewing dresses. Begin by leveraging your existing connections; inquire within your network for any recommended manufacturers. If you’re starting without contacts, search for contract manufacturers who have experience with products akin to what you intend to make.

Research is crucial. Examine their websites, look up customer reviews, and, if possible, visit their facilities to gain a firsthand understanding of their operations. This effort is essential to ensuring thoroughness in your selection process.

Consider the following when evaluating potential partners:

  • Do they have experience with new products in your specific category?
  • Are they based locally or situated in a different region?
  • Can they handle the volume you need at a minimum order level?
  • What are their production lead times and overall turnaround?
  • What does their reputation suggest about their reliability and quality?

It’s advisable to contact other businesses directly to gather insights into their experiences with the manufacturer. This can help you avoid being misled by overly positive website descriptions or counterfeit reviews.

5. Ask for Quotes From Multiple Sources

When choosing manufacturers, it is important to gather quotes from various sources to compare costs, check each manufacturer’s capabilities, and develop effective production strategies. Start by giving each potential manufacturer detailed specifications, such as product designs, materials, quantities, and any specific requirements. Clear, detailed initial communication will help ensure the accuracy of the quotes you receive and reduce the risk of misunderstandings.

Contact a range of domestic and international suppliers using methods like email, phone calls, or online platforms. Be sure to follow up regularly to get timely responses. After collecting the quotes, carefully analyze them, looking at costs, lead times, quality guarantees, and any additional services. Watch for hidden fees or extra charges that could increase your production costs. Also consider other expenses like shipping, taxes, and customs duties to fully understand the total cost of working with overseas suppliers.

Do not hesitate to negotiate after receiving the quotes. Encourage suppliers to match or lower their competitors’ prices to get the best deal. Discuss options for discounts on large orders or favorable payment terms that meet your budget, timeline, and quality requirements.

While cost is a key factor, each supplier’s reliability, reputation, history, and communication skills are also considered for delivering quality products on time. Choose a supplier that offers competitive pricing and fits well with your broader business goals.

Finish the selection process by choosing a manufacturing partner who offers competitive pricing, quality service, and strong customer support. Before proceeding with production, make sure all agreements and relevant details are documented in writing. This detailed approach will help you choose a manufacturer who best meets your needs and supports your long-term goals.

Consider Your ROI

By now, you should better understand the costs of producing your product. And it’s time you analyze all the data you’ve collected to determine your cost of goods sold (COGS), set a retail price, and calculate your gross margin.

Your calculation should include raw materials, initial factory setup costs, manufacturing, and shipping. It should also include additional expenses such as import fees and any duties required to deliver the product to your customer. These charges can significantly affect your COGS, especially if your production is located internationally.

A sample of a product costing sheet in a spreadsheet is included here. You can use and modify this example to construct your own sheet.

If you have received multiple quotes for materials or manufacturers during the sourcing stage, consider adding various columns to your spreadsheet for each line item to compare costs. Alternatively, you could make a second version of the spreadsheet to assess the costs of local versus overseas production.

6. Testing, Feedback and Conditions

Testing, Feedback and Conditions

Evaluating your product’s design based on initial reactions is helpful, but understanding its real-world resilience requires thorough quality testing. Your testing should mimic typical customer usage and expose the product to daily wear and tear to assess its long-term performance.

Product testing can vary in complexity. It might involve simple repeated use or advanced simulations of environmental impacts like vibrations and temperature changes. The type of testing depends on the nature of your product and its specific applications.

Gathering feedback and possibly conducting additional tests before launching your product is crucial to guaranteeing the highest quality product. This feedback can be sourced from focus groups and input from your team, friends, and family. The broader the feedback, the better. Any improvements should be made before the official launch. It’s important to listen and pose open questions actively to elicit genuine feedback.

Once your product is ready, visiting your supplier at the production site is an essential step in evaluating them and establishing a relationship. An on-site visit allows you to inspect the factory and helps build a solid working relationship.

On-site visits also serve as a safeguard against scams, particularly with suppliers abroad who may misrepresent themselves as manufacturers when they are merely resellers. By visiting the manufacturing site, you ensure direct dealings with the actual manufacturer.

Meeting with suppliers in person is an effective way to choose your final options. If in-person visiting isn’t feasible, arranging video meetings is an excellent alternative to interacting with and viewing the manufacturing facilities.

So, How Do You Start With the Terms?

When beginning discussions about a contract with a manufacturer following the approval of a product sample, it is important to clearly define and discuss key elements such as payment terms, order quantities, and delivery details.

  • Minimum Order Quantities (MOQs):

Negotiate MOQs that align with your sales capacity and the manufacturer’s production limits. Although manufacturers may initially propose high MOQs, these figures are typically open to negotiation. Aim for a quantity that supports profitability and ongoing operations for both parties. It helps to enter these discussions with a solid understanding of your projected sales and storage capacity.

  • Payment Terms:

It is crucial to negotiate fair payment terms. Manufacturers often require full payment upfront, especially from new clients. As your business relationship develops, consider proposing a split payment arrangement where half of the payment is made in advance and the remainder when the goods are received. This method reduces financial risk for both parties.

  • Logistics:

Address logistics to determine the expected production-to-delivery schedule and identify potential delays that could impact the supply chain. Important points include securing your place in the production line and understanding shipping costs. Ensure the manufacturer commits to a specific production, packaging, shipping, and delivery timeline for effective planning and accountability.

  • Establish Quality Control Protocols:

Implement rigorous quality control measures to guarantee that your products meet your specifications and expectations. Develop inspection procedures and testing protocols and set criteria for acceptance with your manufacturing partners. Create detailed procedures for addressing any issues related to quality, such as defects or deviations from the agreed standards.

  • Set Liability and Warranty Clauses:

Define the terms of liability and warranty to safeguard both parties in case of product faults or performance shortcomings. Specify the duration of warranties, the conditions under which warranty claims can be made, and the responsibilities regarding the repair or replacement of products. Also, delineate who bears the liability for any damages, losses, or legal obligations stemming from product issues or regulatory non-compliance.

  • Protect Intellectual Property:

Secure your intellectual property by enforcing confidentiality agreements, non-disclosure clauses, and clearly defined ownership rights over designs and proprietary information. Detail the ownership of any intellectual property developed during manufacturing, including how it may be used or shared.

  • Review and Confirm Contractual Agreements:

Thoroughly review all contractual terms to ensure they are accurate, comprehensive, and compliant with applicable laws. Consider consulting with a legal expert to draft or assess agreements and contracts. Once all documents meet the necessary standards, ensure they are signed by all involved parties to formalize the agreement before beginning production.

7. Launch and Promote the Product

Launch and Promote the Product

At this point, you have a profitable product that is ready to be introduced to consumers. The final step in this process is the product launch, where the product development team passes responsibility to the marketing team.

If your budget does not allow for expensive advertising, there are still effective strategies you can use:

  • Optimize Your Website: Develop a professional, user-friendly website that facilitates easy online purchasing. Investing in a skilled graphic design firm can enhance your site’s appeal and functionality.
  • Gift Guide Features: Aim to include your product in popular gift guides, increasing visibility during key shopping periods.
  • Enable Instagram Shopping: Use Instagram Shopping to make your products easily purchasable directly through Instagram, tapping into a large and engaged audience.
  • Collect Customer Reviews: Encourage early customers to leave reviews, boosting credibility and attracting more buyers.
Marketing the Product

While the process may seem daunting, it is manageable with diligent planning and execution. After manufacturing the product and launching it, it’s time to establish business demands by focusing on marketing.

  • Utilize Social Media Platforms:

Establish social media profiles to represent your business online. Marketing through social media is a cost-effective method of engaging with a targeted audience. The followers you acquire should be considered prospective leads and customers, which can grow your business’s outreach.

  • Implement Email Marketing Strategies:

Email marketing offers a significant return on investment, making it a valuable tool for manufacturers. Initiate campaigns targeting registered users on your website, potentially converting these leads into substantial business gains.

  • Optimize with SEO Techniques:

Incorporate search engine optimization (SEO) into your content creation strategy. Learning and applying SEO techniques may require time and effort, but it is a cost-free approach that can increase your visibility and attract more followers and customers.

  • Launch Targeted Advertising Campaigns:

Use platforms like Google Ads and LinkedIn for targeted advertising. These platforms allow you to define your audience by industry, job roles, and other demographics. This strategy ensures the appropriate audience sees your marketing efforts, enhancing ad effectiveness and boosting your marketing ROI.

  • Apply Advanced Analytics:

Use analytical tools such as Google Analytics to monitor and evaluate your marketing activities’ performance continuously. Track metrics like website traffic, user engagement, and the efficacy of different campaigns. This analysis helps you understand which strategies succeed and which need adjustment, enabling strategic improvements to better meet your business goals and adapt to market changes.

Conclusion

Starting the process of manufacturing a product involves a detailed procedure that combines creativity with practicality. The seven essential steps include conceptualizing, designing, prototyping, protecting your idea, finding a manufacturer, obtaining quotes, and considering your ROI. Following these steps sets the foundation for a successful venture. Each stage requires careful attention and strategic decision-making to ensure your product effectively meets market demands.

Plus, safeguarding intellectual property and establishing robust quality control measures are crucial for long-term success and brand integrity. As you navigate these steps, remember the importance of market research, budgeting, and forging strong partnerships with manufacturers. Finally, launching and marketing your product marks the culmination of this process, requiring savvy promotional strategies to reach and resonate with your target audience.

Adhering to these principles and adapting to market feedback will allow you to confidently bring your vision to life and thrive in the competitive manufacturing landscape.

Frequently Asked Questions

  1. What should I consider when designing my product?

    When designing a product, it’s crucial to consider the materials you’ll use, as they impact its functionality, aesthetics, and durability. Research various materials and consult with manufacturers to understand your options. The design phase should also involve creating detailed sketches or models of your product, which will guide the manufacturing process.

  2. How do I find the right manufacturer for my product?

    Finding a suitable manufacturer involves assessing their reliability, production capabilities, and cost-effectiveness. You can use platforms like Alibaba or ThomasNet to find manufacturers. It’s beneficial to get multiple quotes and samples before making a decision. Consider domestic and overseas options, weighing costs, communication ease, and shipping logistics.

  3. What is the importance of prototyping, and how do I go about it?

    Prototyping is essential for testing the design and functionality of your product before mass production. It allows you to make necessary adjustments based on feedback and performance. Depending on the complexity of your product, you may need to work with a manufacturer that can produce a prototype or use online tools and software if it’s a digital product.

  4. How should I handle the quoting process with manufacturers?

    When obtaining quotes, provide detailed information about your product, including specifications and quantities. This helps manufacturers give you accurate pricing. It is recommended that you request quotes from multiple manufacturers to compare prices and services. Ensure that the quotes include all potential costs to avoid surprises later.

Best Banks for Small Business in 2024

Best Banks for Small Business in 2024

Once your small business begins earning profits and incurring expenses, you will need a business bank account for daily operations and managing cash flow. A dedicated account enhances your business’s credibility, keeps personal and business finances separate, and might improve your chances of securing a line of credit (LOC). However, with over 4,800 banks in the US, this article aims to guide you in selecting the best banks for small businesses in 2024.

According to a 2023 survey, 96% of small-business owners report having a business banking account. Choosing a top bank for small businesses can assist with various tasks, from managing payroll to allocating funds for office supplies, even if you need to improve with numbers. For entrepreneurs, while opening a business bank account may initially seem cumbersome, it ultimately simplifies financial management by clearly showing expenses, payments, and paid bills.

Things to Factor In While Choosing the Right Bank for Your Business

While several personal/business-related preferences come into play when choosing a business account for your small business, here are some important aspects to consider:

1. Online or In-Person?

For small business owners, selecting a bank offering online and in-person banking services is crucial. Whether you operate a digital storefront or a physical one, the ability to manage your finances through online and mobile banking applications is essential. This allows you to oversee your financial activities and transactions at your convenience.

However, the availability of online banking does not diminish the necessity for physical branch services. This is particularly true for businesses that handle cash transactions, as frequent cash deposits are a routine requirement. Physical branches also provide more comprehensive customer support.

2. What Services Do You Need?

When choosing a bank, certain fundamental services are essential for business operations. These include:

  • Checking and savings accounts
  • Business credit and debit cards
  • Checkbooks and deposit-only cards
  • Online business banking platforms
  • Accounts for employees

It’s important to investigate each service, paying close attention to any associated fees or requirements. While some banks charge fees for checking accounts, others may offer free business checking with no required minimum balance. Since fees and requirements can vary significantly between banks, it’s beneficial to compare options thoroughly.

Additionally, if your business may need further financial services like LOCs, inquire about these upfront to avoid surprises after you’ve committed to a banking relationship.

3.   Bank’s Location

The location of a bank should be another major factor in your decision. Evaluate the bank’s distance from your office, home, and frequent travel destinations. Consider how often you need to make deposits or withdrawals, require bank-issued certified checks, or use ATMs during travel.

The frequency with which you’ll need to visit a bank and your travel needs should influence your choice. If your business operations require frequent bank visits or if you travel widely and rely on accessible ATMs, choose a bank that aligns with these needs.

4.   Fees and Charges

The cumulative impact of banking fees, even those that seem small, can be significant over time. Selecting a bank that minimizes fees on business accounts and maximizes the availability of free transactions and services is advisable.

Important fees to compare among banks include ATM usage fees, transaction fees, maintenance fees, and monthly service charges.

5.   Incentives for Businesses

Banks and credit unions often provide benefits and incentives to attract business account holders. For example, startups might receive a cash bonus for opening a new business checking account, or banks might eliminate minimum deposit requirements for business savings accounts.

Other incentives to consider include:

  • Unlimited free transactions
  • High interest rates on savings and money market accounts
  • No-fee business checking accounts
  • Complimentary online bill payment
  • Competitive interest rates on business credit cards
  • No annual fees on business debit cards
  • Complimentary cash deposits
  • Unlimited free check deposits
  • Free use of ATMs
  • No minimum balance requirements
  • ATM fee reimbursements while using machines from other banks

6.   Integration Options

While benefits like low fees and free accounts are important, don’t overlook essential operational services such as payroll management. Payroll can become complex as your business expands.

Choose a bank that offers comprehensive payroll services, including direct deposit payments to employees, payroll tax filing, and HR task management. These services help simplify the complexities associated with growing business operations.

7.   Support Options

When selecting a bank for your business, consider the support and expertise available. Many banks offer dedicated staff to assist in managing and developing your business. These specialists can guide managing finances, funding expansion, and handling operations such as taxes and payroll.

As you evaluate your banking options, consider not only your current needs but also the potential future demands as your business expands. Access to knowledgeable bank staff who understand your business and its financial background can be invaluable. While you can hire external consultants, having access to advice from someone within the bank who is already familiar with your account details and business history can be extremely beneficial.

How to Open a Business Checking Account?

To open a business checking account, you can visit a bank branch, call, use the bank’s website, or access mobile banking services. However, keep in mind that not all banks offer all these methods.

You may also have the opportunity to establish additional accounts, such as a business savings account, a business credit card account, or a merchant services account, which allows you to process credit and debit card payments from customers.

Before opening your account, decide on the location and method, then collect all necessary information to provide to a bank representative or enter it through an online application. Be aware that the bank may perform a credit check when you apply for a business checking account.

Choosing the right business bank account depends on your specific business needs. Still, all accounts should meet basic functions like receiving customer payments, handling payroll, and managing costs to suppliers and other business partners.

Top Banks for Small Businesses in 2024

Based on extensive research and key factors for opening a business bank account, we have selected our top choice for 2024:

1. Axos Bank

Pros

  • No monthly fees or initial deposit is required.
  • Unlimited transactions without fees and no charge for incoming wires.Provides unlimited reimbursements for domestic ATM fees.
  • Customer support is available 24/7.
  • A welcome bonus is available for new customers (subject to terms).
  • Offers integration with QuickBooks to simplify business management.

Cons

  • Depositing cash may be challenging for business owners.
  • Bonuses are only available for accounts with an average daily balance of $25,000 or more.
  • Does not offer interest on account balances.
Axos Bank

Image source

Axos Bank offers various checking accounts suitable for different types of businesses, making it a top choice for small businesses. You can easily get interest rates up to 1.01% APY for balances under $50,000 with a Business Interest Checking account, which requires no monthly fee with a minimum balance of $5,000. This account allows up to 100 monthly free transactions and 60 remote deposit items. The Axos Bank Basic Business Checking account also eliminates the monthly fee regardless of the balance. It offers unlimited transactions and ATM reimbursements, ideal for newer businesses or those with frequent banking activities.

The bank also provides several savings products, including the Axos Bank Business Savings, Business Money Market Account, Non-Profit Money Market Account, and Business Certificate of Deposit. However, these savings options typically offer a maximum yield of 0.20% APY, which is relatively low compared to other online banks. Axos Bank may be a good option for those seeking a business checking account. However, other institutions might offer better options if your priority is a savings account or certificate of deposit with higher returns.

2. Chase

Pros

  • No charge for credit card payment processing via the mobile app
  • Unlimited electronic transactionsSelf-managed escrow services are available
  • The mobile app has received high ratingsBanking fees waived for military members.

Cons

  • Limited to 20 paper transactions per month
  • Does not reimburse fees for using ATMs outside its network
  • Checking accounts do not accrue interest
Chase bank

Image source

As the largest bank in the US by assets, Chase Bank offers a range of banking products and services tailored to support small businesses. Chase is an appealing option for both well-established companies and those just starting out. Operating under the broader umbrella of J.P. Morgan Chase and headquartered in New York City, Chase Bank commands over $2.6 trillion in assets and maintains a global presence. It boasts a network of 15,000 ATMs and more than 4,700 branches.

The bank’s extensive resources offer significant advantages to small business owners, including substantial rewards, account bonuses, and the convenience of physical branches across North America for face-to-face services. Additionally, Chase provides other financial products such as small business loans, credit cards, and savings accounts.

Chase Bank offers various checking account options designed to meet the diverse needs of different businesses. The Business Complete Banking℠ account charges a monthly fee of $15, which can be waived under certain conditions. It allows unlimited electronic transactions and includes 20 free paper transactions monthly. The cash deposit limit is $5,000 per month without fees, and after that, a fee of $2.50 per $1,000 deposited applies. Incoming wire transfers are free, while outgoing transfers incur a $35 fee.

The Performance Business Checking® account has a monthly fee of $30, which is also waivable. This account offers unlimited electronic deposits and up to 250 free transactions monthly. The free monthly cash deposit limit is set at $20,000; deposits exceeding this amount are charged at $2.50 per $1,000. The wire transfer policy includes no fees for incoming transfers and allows for two free outgoing transfers per month, with each subsequent transfer costing $35.

Lastly, the Platinum Business Checking℠ account features a higher monthly fee of $95, which can be waived under specific conditions. It includes unlimited electronic deposits and up to 500 free transactions each month. The account allows up to $25,000 in cash deposits each month free of charge, with additional deposits incurring a fee of $2.50 per $1,000. Wire transfers are free for incoming, and the first four outgoing transfers each month are also free, with a $35 fee applying to further outgoing transfers.

3. Capital One

Pros

  • Unlimited transactions without fees.
  • Comprehensive range of business services, such as credit cards and loans.
  • Access to 70,000 ATMs without fees, including those in the Capital One, Allpoint, and MoneyPass networks.

Cons

  • No options for free business checking accounts.
  • Restricted service areas; applications must be made in person.
  • Monthly free cash deposit limit of $5,000.
Capital One

Image source

Capital One provides two types of business checking accounts. The Basic account features include unlimited electronic deposits, mobile and online banking access, and a low minimum balance to waive fees.

The Unlimited business account combines the benefits of two Basic accounts and suits businesses with more complex financial needs. Additionally, Capital One offers various business credit cards with cash back or travel rewards, which are ideal for international travel due to the absence of foreign transaction fees. The bank is known for its responsive and well-informed customer service.

It’s important to note that the small business account is limited to particular states and requires an in-branch application.

Capital One’s services and fee structures are competitive compared to other major banks. It also provides a vast ATM network, which is convenient for customers who prefer banking in person. The network includes over 70,000 Allpoint and MoneyPass ATMs nationwide, accessible without fees. While Capital One’s checking accounts do not offer an Annual Percentage Yield (APY), opening a savings account can provide an interest rate of 0.2%. Capital One also offers small business loans and LOCs, but only to customers with a checking account, with credit lines up to $5 million.

Capital One’s Basic Checking account has a monthly fee of $15, which is higher than American Express, which does not charge a maintenance fee. This fee is waived if the balance exceeds $2,000. The account allows up to $5,000 in free cash deposits per month and charges standard fees for wire transfers. The Unlimited Checking account has a $35 monthly fee, waived if the balance is $25,000 or more. This account allows unlimited free cash deposits and does not charge for incoming wires. Customers can also make up to five free outgoing wire transfers each month.

4. Bluevine

Pros

  • Account balances up to $250,000 earn an interest of 2.00%; conditions apply.
  • There are no monthly fees or requirements for a minimum opening deposit.
  • Account holders can access up to $3 million in FDIC insurance through the Insured Cash Sweep service.
  • The account offers unlimited transactions without any fees and does not charge for overdrafts.
  • Incoming wires are free, and the fees for outgoing wire transfers are low.
  • There are no fees for using MoneyPass ATMs.

Cons

  • There is a fee for cash deposits.
  • Fees apply when using ATMs outside of the network.
  • The service does not support joint accounts.
Bluevine

Image source

Unlike most traditional accounts, Bluevine, a fintech lender, offers small business checking accounts that earn interest. This service is particularly beneficial if you’re considering a LOC, as your banking history with Bluevine could improve your chances of approval. In 2020, Bluevine partnered with banks to provide these accounts, utilizing sweep accounts to offer up to $3 million in FDIC coverage through various partner banks.

Bluevine operates digitally, allowing unlimited transactions while enforcing limits on monthly deposits and withdrawals. The company does not charge fees for ACH transactions, overdrafts, incoming wire transfers, or ATM use within its network. Additionally, Bluevine offers a 1.5% annual percentage yield (APY) on balances up to $100,000 under certain conditions. Balances up to $250,000 can earn 2.00% APY if you spend $500 monthly using the BlueVine Business Debit Mastercard or receive $2,500 in customer payments.

Clients receive two free checkbooks annually and can manage their finances with up to five subaccounts. The checking account includes features like unlimited transactions, overdraft protection, and QuickBooks integration without a monthly fee. BlueVine customers have access to 37,000 surcharge-free ATMs and 90,000 retail locations for cash deposits.

5. Bank of America

Pros

  • Comprehensive business banking options that combine checking and savings accounts.
  • The choice between two tiers of business banking accounts.
  • Digital resources such as Cash Flow Monitor and Erica assist in monitoring expenditures.
  • Access to specialized support from small business experts.

Cons

  • Customer service is not available 24 hours a day.
  • A limited number of ATMs compared to some competitors.
  • Charges monthly fees for account maintenance.
Bank of America

Image source

Bank of America is a major financial institution that offers banking products and wealth management services to individuals, businesses, corporations, and governments. It operates branches across most US states and provides access to 16,000 ATMs for free. The bank also supports online banking and a mobile application, which holds a rating of over four stars on both the App Store and Google Play.

Bank of America is recognized for its provision of unlimited electronic transactions, high cash deposit limits, and multiple account opening methods.

The Bank of America Business Advantage Fundamentals Banking account allows for up to $7,500 in cash deposits each month without a fee and includes business and employee debit cards. Features such as the Cash Flow Monitor help users with cash flow projections, transaction monitoring, and balance tracking. Access to dedicated small business specialists is also provided.

To avoid the $16 monthly service fee, customers can maintain a $5,000 combined average monthly balance or make at least $250 in new qualified debit card purchases monthly.

6. US Bank

Pros

  • The Silver Business Checking account does not require a monthly service fee.
  • New customers can receive a welcome bonus, subject to specific conditions.
  • Customers can use 4,700 U.S. Bank ATMs without incurring fees and have access to 2,900 bank branches.
  • Accounts overdrawn by $50 or less are not subject to overdraft fees.

Cons

  • There are restrictions on the amount of cash that can be deposited.
  • The bank’s website has complex information regarding terms and fees.
  • There is a cap of 125 transactions per month without fees.
  • There is a $1 charge for each outgoing domestic ACH transfer.
US Bank

Image source

US Bank is distinguished among large banks for its free business checking option. The Silver Business Checking account is free of monthly maintenance fees and minimum balance requirements. It is ideal for businesses with a relatively small number of monthly transactions, such as a contractor with a primary client. US Bank operates over 2,000 branches, mainly on the West Coast, catering to small, regional businesses that value in-person banking and tailored support.

As businesses expand, US Bank provides various services, such as payment processing solutions, SBA loans, payroll support, and cash management services.

US Bank provides three tiers of checking accounts. The Platinum package, costing $30 monthly, allows 500 transactions, with each additional transaction priced at $0.40. The Gold package includes 300 monthly transactions for a $20 fee, with each extra transaction costing $0.45. The Silver Business Checking Account allows 125 free monthly transactions, with additional transactions costing $0.50 each. In comparison, some competitors like Bluevine do not charge transaction fees, which could make US Bank’s fees appear steep.

The bank provides a variety of borrowing options, including business credit cards, lines of credit, and various loans. Its business credit cards offer advantages such as no annual fees, cash back, rewards programs, and competitive interest rates. Additionally, the bank’s selection of small business loans is tailored to accommodate a range of business needs, with loan amounts up to $250,000 available through Quick Online loans and up to $12.375 million for government-backed loans.

7. Lili

Pros

  • Lili does not require monthly fees, a minimum balance, or a minimum opening deposit.
  • There is no limit on the number of transactions without fees.
  • Customers have free access to any MoneyPass ATM.
  • Cash can be deposited through the Green Dot Network.
  • Lili offers tools for managing business expenses and tax planning.
  • Direct deposit with Lili allows for early access to funds, potentially two days earlier than usual.

Cons

  • Lili lacks advanced business features, such as third-party integrations, provision of multiple debit cards, and options for joint accounts.
  • ATMs outside the network are charged $2.50, and international ATM use is charged $5.
  • Lili does not offer paper checks.
Lili

Image source

Lili Premium Business Banking offers free overdraft protection up to $200 and includes a Metal Visa Business Pro debit card that earns cash-back rewards. This card can be used at over 38,000 in-network ATMs across the nation. Account holders benefit from dedicated account specialists and priority customer support.

The service features Smart Bookkeeping, which allows you to attach expense receipts and organize finances for easier tax preparation and offers tools for creating on-demand profit and loss and cash flow statements. Additionally, you can instantly accept payments, create and send invoices and manage business income taxes.

Lili is a digital bank ideal for small businesses that primarily operate electronically and rarely handle cash or checks. The Lili business checking account has a Visa debit card, which is widely accepted and secured against unauthorized charges. Lili also provides a comprehensive suite of services, including banking, accounting, invoicing, and tax preparation. The bank offers four account tiers, with the first basic level being free and higher tiers priced between $15 and $55 per month, offering more advanced features.

With low or no fees on ACH transactions, ATM use, foreign transactions, incoming domestic wire transfers, and no minimum balance requirement, Lili is a cost-effective choice for sole proprietors and owner-operators in information-centric businesses. However, companies that handle a lot of cash might find the account less accommodating. Other benefits include a $0 minimum deposit requirement, the ability to transfer excess funds to a savings account, and the opportunity to earn 2% APY on those savings.

8. American Express

Pros

  • There are no monthly maintenance fees.
  • Accounts with balances up to $500,000 earn an annual percentage yield (APY) of 1.30%.
  • Users earn Membership Rewards® points with business debit card purchases.
  • Regular welcome offers are available.
  • Customer support is available 24/7.

Cons

  • Cash deposits are not accepted.
  • There are no physical branch locations.
American Express

Image source

American Express Business Checking responds to current business banking needs by offering a fee-free service and not requiring a minimum balance in its standard business checking account. The account supports unlimited transactions.

American Express has integrated with Kabbage, enhancing its offerings with ready access to Kabbage’s financial products. This integration positions American Express Business Checking as an attractive option for business owners seeking banking solutions and LOCs. It provides easy approval for small business LOCs up to $250,000 through Kabbage Funding.

American Express Business Checking is tailored to suit businesses’ specific requirements. It incorporates advanced fraud protection measures to protect against unauthorized activities and ensure financial security.

This account offers no monthly fees, no minimum balance requirements, and unlimited transactions; plus, it is an interest-bearing account with a 1.30% APY. Users of the Business Debit Card can earn membership rewards points that may be redeemed directly or transferred to travel partners like Delta Air Lines, Hilton, and Marriott. Additionally, American Express customers can access over 70,000 ATMs nationwide via Allpoint and MoneyPass networks.

Conclusion

Selecting the best bank for your small business in 2024 depends on various factors, including your specific needs and priorities. Whether you prioritize low fees, comprehensive online services, or access to physical branches, options like Axos Bank, Chase, Capital One, Bluevine, Bank of America, US Bank, Lili, and American Express offer diverse features to meet these needs. By evaluating the pros and cons of each bank, you can find the one that aligns with your business goals and operational requirements.

A well-chosen bank can simplify financial management, support business growth, and provide valuable resources and incentives to enhance your business operations.

Frequently Asked Questions

  1. What should I consider when choosing a bank for my small business?

    When choosing a bank, consider these factors: available online and in-person services, fees for account maintenance and transactions, business-friendly features like high transaction limits and mobile apps, and the quality of customer support and financial expertise offered.

  2. How do I open a business checking account?

    To open a business checking account, choose a bank, gather necessary documents like your business license and EIN, apply online or at a branch, and review the account’s terms and fees before finalizing.

  3. Are there any benefits to opening a business account at a bank rather than using personal accounts for business transactions?

    Yes, benefits include enhanced professionalism, easier financial management, improved credit opportunities, and access to services tailored to business needs, like higher transaction limits and merchant services.

  4. Can I switch my business banking to another bank if I am dissatisfied with my current bank?

    Yes, you can switch banks. Research and select a new bank, open a new business account, transfer funds, update automatic payments, and close your old account once all transactions are settled.

Best Business Credit Cards for 2024

Best Business Credit Cards for 2024

If you run a business, you understand the value of having additional funds available. A business credit card can be extremely helpful for many reasons. It assists in separating personal and business expenses, simplifying financial management, especially during tax season. It also provides crucial financial support during tough times. Additionally, many business cards offer the option to issue free cards for employees. We have evaluated many widely used options and selected the best business credit cards for 2024 that may be ideal for your business, regardless of the industry. Continue reading to find out more.

Top Business Credit Cards for 2024

Below is a list of popular business credit cards. These cards are sorted based on their diverse features, which are suitable for different customer types. Detailed information about each card’s welcome bonuses and other features is below.

1. Ink Business Unlimited® Credit Card

Ink Business Unlimited® Credit Card

Image source

The Ink Business Unlimited Credit Card may be suitable if you want a versatile cash-back credit card without an annual fee. It’s particularly advantageous for small business owners who prefer simplicity and cost-effectiveness in their financial tools.

Here are some of the highlights of the Ink Business Unlimited:

  • Receive 1.5% cash back on all your business-related purchases continuously.
  • When you spend $6,000 in the first three months after creating your account, you will receive a $750 extra cash back.
  • There is no annual fee.
  • This account is FDIC-backed.
  • Redeem rewards for gift cards, travel, cash back, and more through Chase Ultimate Rewards®.
  • A 3% fee applies to foreign transactions.
  • Your account is monitored continuously to detect unusual credit card activity.
  • Add employee cards, too, at no additional cost. You can set individual spending limits for improved financial management.
  • Benefit from an introductory 0% APR on purchases for the first 12 months.
  • Zero Liability protection means you are not held responsible for unauthorized charges made with your card or account information.

2. American Express Blue Business® Plus Credit Card

American Express Blue Business® Plus Credit Card

Image source

The Blue Business Plus Credit Card from AmEx offers a straightforward way for business owners to accumulate American Express Membership Rewards points. This card provides a competitive earning rate of 2 Membership Rewards points per dollar on standard business expenses such as office supplies or dining with clients, up to the first $50,000 spent annually, and then 1 point per dollar on subsequent purchases. Additionally, this card does not require an annual fee.

Here are some of the highlights of the Blue Business Plus Credit Card:

  • An introductory APR of 0% on purchases for 12 months from the date of account opening, followed by a variable rate of 18.49% to 26.49%, depending on creditworthiness and other factors. The APR will not exceed 29.99%.
  • A welcome offer of 15,000 Membership Rewards® points after making $3,000 in eligible purchases within the first three months of membership.
  • The Expanded Buying Power feature allows you to spend beyond the set credit limit. The amount you can spend above your credit limit varies based on card usage, payment history, credit record, financial resources, and other factors.
  • Zero annual fee.

3. Capital One Spark Cash Plus

Capital One Spark Cash Plus

Image source

The Capital One Spark Cash Plus card is well-suited for businesses with substantial spending requirements. It offers 2% cash back on all purchases without any limitations or specific categories to monitor.

This card includes a $150 annual fee, which is waived for the first year. Additionally, it provides an opportunity to earn a substantial cash bonus: $500 after you spend $5,000 in the first three months and another $500 after spending $50,000 within the first six months of account opening.

The card features complimentary employee cards, enhancing your ability to monitor and control team expenditures. You also gain access to advanced security measures such as fraud alerts and a $0 fraud liability policy to safeguard your business finances. With a simple rewards structure and significant benefits, the Capital One Spark Cash Plus card is a strong option for businesses aiming to optimize their cash-back earnings and streamline expense management.

Here are some of the highlights of the Capital One Spark Cash Plus:

  • A one-time $1,200 cash bonus after spending $30,000 within the first three months.
  • Free additional cards for employees, with all purchases on these cards also earning unlimited 2% cash back.
  • The spending limit is flexible and adjusted according to your spending habits, payment history, and credit profile.
  • The card operates on a pay-in-full model each month—Hence, there is no APR.
  • Unlimited 5% cash back on hotel and car rentals booked through Capital One Travel.
  • The annual fee is refundable if your yearly spending reaches $150,000.

4. Business Platinum Card® from American Express

Business Platinum Card® from American Express

Image source

The Business Platinum Card from AmEx offers substantial rewards and benefits, making it a suitable choice for business owners. It features a strong welcome bonus, especially beneficial for those with significant initial spending. The card provides tiered rewards on purchases in key business categories, increasing the value of each dollar spent.

Additionally, it offers statement credits on various business essentials, which can improve cash flow and add value to the card. The card includes excellent travel benefits for those who travel frequently, providing comfort and convenience. Despite its high annual fee, the potential returns from spending can offset this cost for businesses with high expenditures.

Here are some of the highlights of the Business Platinum Card:

  • Earn 150,000 Membership Rewards® points after spending $20,000 on eligible purchases within the first three months.
  • Receive 5X Membership Rewards® points on flights and prepaid hotels booked through AmexTravel.com.
  • Earn an additional 0.5 points per dollar on large purchases of $5,000 or more at U.S. suppliers of construction materials, hardware, electronics, cloud services, and shipping, up to $2 million per calendar year. Earn 1X points on other eligible purchases.
  • Receive a $200 credit each calendar year for incidental airline fees.
  • Access over $1,000 in credits for select business expenses in the first year (enrollment required).
  • Enjoy complimentary access to more than 1,400 airport lounges worldwide with the American Express Global Lounge Collection®.
  • Receive up to $189 in credits annually for CLEAR® Plus membership.
  • The annual fee is $695.

5. Ink Business Cash® Credit Card

Ink Business Cash® Credit Card

Image source

The Ink Business Cash® Credit Card is a practical choice for small businesses, offering rewarding benefits for typical business expenses. This card features an appealing introductory offer and does not charge an annual fee. It also provides a zero percent introductory APR on purchases. Employees can be added to this account without additional costs.

However, be aware of the foreign transaction fees and the necessity to manage repayments effectively once the promotional period ends to avoid high interest rates.

Here are some of the highlights of the Ink Business Cash:

  • Receive 5% cash back on the first $25,000 spent annually on combined purchases at office supply stores and on cable, internet, and phone services.
  • Receive a $350 bonus after $3,000 worth of spending within the first three months and a $400 bonus after spending $6,000 within the first six months of opening your account.
  • Benefit from a 10% Business Relationship Bonus when you hold both the Ink Business Cash card and a Chase Business Checking account by the end of your first year.
  • Earn 2% cash back on transactions up to $25,000 annual spending at restaurants and gas stations. All other transactions receive 1% cash back.
  • Redeem your rewards for cash back, gift cards, travel, and more through Chase Ultimate Rewards®.
  • Zero Liability protection means you are not held accountable for unauthorized charges made with your card or account information.
  • Take advantage of 0% APR for the first 12 months on purchases.

6. Capital One Venture X Business Credit Card

Capital One Venture X Business Credit Card

Image source

The Capital One Venture X Business card offers a diverse rewards program for small business owners. This card allows you to earn 2x miles on every purchase, potentially earning up to 10x miles for bookings made through Capital One Travel. It operates on a pay-in-full basis with no preset spending limit, requiring the full balance to be cleared monthly. An annual fee of $395 is charged, but cardholders receive a $300 travel credit annually for bookings made via Capital One Travel and an additional 10,000 bonus miles each renewal year.

Card benefits include reimbursement for TSA PreCheck or Global Entry fees and complimentary access to over 1,300 lounges globally. Miles can be redeemed for travel, statement credits, and more, and can also be transferred to over 15 airline and hotel partners for potentially greater value.

Here are some of the highlights of the Capital One Venture X Business:

  • Receive 150,000 bonus miles after spending $30,000 within the first three months from account opening.
  • Earn unlimited 2X miles on every purchase without any restrictions.
  • Enjoy 10,000 bonus miles on your annual account anniversary and a $300 travel booking credit.
  • Earn 10X miles on rental cars and hotels and 5X miles on the flights booked from Capital One Travel.
  • Get up to $100 credit for TSA PreCheck® or Global Entry and unlimited pass to Capital One, including affiliated lounges worldwide.
  • Provide your team with free employee and virtual cards, facilitating the easy accumulation of rewards and integration with accounting systems.
  • Enhance your experience at select luxury hotels and resorts with a $100 credit and additional premium benefits per stay.

7. Ink Business Preferred® Credit Card

Ink Business Preferred® Credit Card

Image source

The Ink Business Preferred Credit Card is designed for business owners who want to maximize rewards on typical expenses like travel, shipping, and telecommunications services.

Points earned with this card can be used for cash back, gift cards, or unique experiences, with each point valued at one cent – When used for travel via Chase TravelSM, points gain a 25% increase in value, offering 1.25 cents per point. Points can be transferred to 14 airline and hotel partners affiliated with Chase for additional value.

Here are some of the highlights of the Ink Business Preferred:

  • A bonus of 100,000 points after spending $8,000 within the first three months of account opening, equivalent to $1,000 cash back or $1,250 for travel when redeemed through Chase Travel℠.
  • Three points per dollar on the first $150,000 spent annually on travel and selected business categories, and one point per dollar on all other transactions.
  • Continuous monitoring to detect unusual purchases on your card.
  • Zero Liability protection, ensuring you are not responsible for unauthorized charges.
  • Points redemption options include cash back, gift cards, and travel, with no expiration as long as the account remains active.
  • Points are valued 25% higher when redeemed for travel through Chase Travel℠.
  • Purchase Protection covers new purchases for 120 days against damage or theft, up to $10,000 per claim and $50,000 per account.

8. Ramp Corporate Card

Ramp Corporate Card

Image source

The Ramp Corporate Card is suitable for startups needing a credit history. To qualify, startups need an Employer Identification Number (EIN) and at least $50,000 in a business bank account. Ramp does not require a credit check or personal guarantee. The card provides cash back on purchases and includes expense management software to help organize your business finances.

Key features of the Ramp Corporate Card include receipt matching, subscription management, and AI-driven spending analysis. It is a good option for startups looking to manage expenses and earn rewards on business purchases.

Here are some of the highlights of the Ramp Corporate Card:

  • Unlimited 1.5% cash back on all purchases without a minimum spending requirement.
  • There are no annual or foreign transaction fees.
  • There is no need for a personal credit check or guarantee.
  • Ability to issue an unlimited number of virtual and physical cards for employees.
  • Built-in controls to prevent spending that violates company policies, with restrictions possible by category or merchant.
  • As a Visa-powered corporate charge card, businesses must settle their full balance monthly.
  • A minimum of $75,000 in any U.S. business bank account is required.
  • Primary operations and spending must be within the U.S., although Ramp does support international transactions without transaction fees.
  • This offer is available to corporations, LLCs, and limited partnerships only. Individuals, sole proprietorships, and unregistered businesses do not qualify.

Which Credit Card Is Best for Your Business?

Choosing the best business credit card for your company involves understanding your business’s unique needs and spending habits. Here’s a guide to help you select a card that maximizes benefits for your company:

  • Assess Your Spending Patterns: Consider where your business spends the most money. Different cards offer rewards for various categories, such as travel, office supplies, or dining. For example, the Ink Business Cash® Credit Card offers significant cash back on office supply purchases and telecommunications services, making it a strong choice for businesses with high office-related expenses.
  • Consider Cash Flow Needs: If your business experiences seasonal fluctuations or you often face delayed payments, a card offering a 0% introductory APR, like the American Express Blue Business® Plus, can provide a buffer by allowing you to carry a balance without incurring interest for a set period.
  • Evaluate Fee Structures: Weigh the benefits of any rewards against potential fees. Cards like the Capital One Spark Cash Plus have an annual fee, but the cash-back benefits can offset this cost if your spending is high enough. Conversely, a card with no annual fee, like the Ink Business Unlimited®, might be more appealing if you’re cost-conscious.
  • Look at Additional Perks: Some cards come packed with extras that can be highly beneficial. For instance, the Business Platinum Card® from American Express offers extensive travel benefits, including access to airport lounges and hotel credits, which are valuable for businesses with frequent travel needs.
  • Employee Management: If you need to issue cards to employees, look for options that allow you to set individual spending limits and monitor transactions easily. The Capital One Spark Cash Plus and others offer free employee cards, which can simplify expense tracking and reinforce spending controls.

Conclusion

Selecting your company’s best business credit card can significantly improve financial management and provide valuable rewards. Each card offers unique benefits tailored to business needs, from cash-back rewards and travel perks to streamlined expense management and zero liability protection.

Cards like the Ink Business Unlimited® Credit Card and the American Express Blue Business® Plus Credit Card provide versatile rewards without annual fees, making them ideal for small businesses. For larger spending, the Capital One Spark Cash Plus and the Business Platinum Card® from American Express offer substantial cash-back and rewards opportunities. Choosing the right card can enhance your business’s financial flexibility and support its growth in 2024.

Fintech Trends to Watch in the Second Half of 2024

Hot Fintech Trends to Watch in the Second Half of 2024

Financial technology products and solutions are integral to daily life. The methods consumers use to access bank accounts, make purchases, and obtain loans are undergoing significant changes. The fintech sector has experienced rapid growth and challenging periods. However, emerging trends are shaping its future direction. For those interested in what lies ahead for this expanding industry, we have listed the key fintech trends to watch in the second half of 2024. These trends, derived from research and data from various fintech sources, aim to provide valuable insights for fintech developers and service providers.

Currently, approximately 90% of people in the US utilize fintech services. The global fintech market is projected to grow from $209.7 billion in 2024 to $644.6 billion by 2029.

Top 7 Fintech Trends to Watch in the Second Half of 2024

1. Embedded Finance on the Rise

Embedded finance involves incorporating financial services within non-financial websites and applications. A recent study predicts that the embedded finance market will grow significantly, expecting to generate around $320 billion in revenues by 2030, primarily driven by payments, lending, and insurance.

Embedded Finance on the Rise - Global neobanks market value projection infographic

Source: Mordor Intelligence

This approach allows financial services to be integrated directly into various non-financial platforms, facilitating the everyday use of financial features. It effectively eliminates the barriers between financial services and other sectors, providing users easy access to financial tools without needing separate banking or financial apps. For fintech companies, it increases customer access, enabling the use of digital wallets and other fintech payment methods during online transactions, including the use of online savings accounts.

Notable trends in fintech include offering interest-free loans at the point of online checkout, creating straightforward one-click payment applications, and launching branded checking accounts and debit cards tailored for primary users.

2. Growing Adoption of Open Banking

Recent data suggests the open banking market is set to expand significantly. Statista forecasts that by 2024, 63.8 million people will utilize open banking services. Open banking represents a significant transformation in financial services, primarily focusing on efficiently sharing and using financial data. This technology provides enhanced payment experiences through API-driven services, responding to the need for quicker, more secure, and customer-focused solutions.

Open banking allows for the regulated exchange of financial information. Account holders can approve the secure sharing of their financial data with alternative financial institutions. These third-party providers can access client financial information through accessible APIs. This setup benefits numerous fintech startups and companies involved in budgeting, expense tracking, financial planning, lending, and more.

Growing Adoption of Open Banking - Transaction value in the neobanking market infographics

Source: Statista

As more entities adopt open banking, regulatory bodies worldwide are updating their frameworks to support this shift, ensuring consumer protection and data security. The European Union’s PSD2 and the UK’s Open Banking Standard are leading examples of such regulations. These rules not only require the secure sharing of data but also demand customer consent, setting benchmarks for other regions.

Despite its potential, only 10% of open banking’s capabilities have been tapped into. The sector continues to hold considerable potential, with users gradually recognizing the benefits of open data. This exchange of information fosters academic research, software development, and the improvement of financial services.

3. NeoBank’s Appeal to GenZ

The shift toward home-based activities during the pandemic has also impacted the financial sector, leading to a rise in neo-banks. These digital-only banks mirror the services of traditional banks but operate without physical branches, instead relying entirely on digital platforms.

Neo-banks maintain the essential features of traditional banks but offer a smaller range of services, focusing on quality and reduced fees. Interest in neo-banks is increasing, with projections suggesting nearly 400 million users by the end of 2024, underscoring the growth of digital banking.

Gen Z, a key demographic for this global fintech trend, typically makes its first purchases earlier than prior generations. They prefer a fluid digital experience and are receptive to automated customer service. Disliking paperwork and valuing time efficiency, Gen Z finds the neo-bank model appealing for its ease in setting up accounts and integrating with digital wallets, banking systems, or eCommerce platforms.

Many traditional banks are rebranding or establishing neo-bank subsidiaries to keep up with this trend. As of January 2023, over 350 neo-banks were operational. Bloomberg predicts that by 2026, the number of neo-bank users will reach 224 million.

4. AI’s Growing Role in Banking and Financial Services

AI machine learning and large language models (LLMs) are poised to continue their transformative impact on banking and financial services into late 2024 and 2025. The focus will shift from enhancing internal efficiencies to deploying more customer-oriented services.

Financial service companies will increasingly use AI-driven chat agents, offering users real-time support and insights. Banks and financial institutions are set to use AI to tailor financial solutions and streamline loan application processes. AI and ML algorithms will evaluate data to determine creditworthiness, detect trends, and optimize loan conditions.
Additionally, AI will personalize user experiences in embedded payment solutions while boosting security with sophisticated fraud detection techniques. AI, combined with robotic process automation (RPA), will enable firms to refine internal operations, thereby increasing efficiency and allowing staff to concentrate on higher-value tasks.

However, deploying customer-facing AI applications involves greater challenges than internal applications, primarily due to increased regulatory oversight. As a result, fintechs will likely approach this area with caution.

5. Regtech Solutions Will Streamline Operations

Financial institutions handle vast quantities of data every day. This data is too intricate and extensive to sift through manually. Additionally, these companies must deeply understand the extensive array of laws and regulations they are required to follow.

This is the role of regtech, or regulatory technology.

Regtech solutions employ cloud computing, machine learning, and big data analytics to detect and mitigate risks, ensuring compliance with regulations.

Such technologies deliver increased operational efficiency, enhanced precision, and deeper insights across the organization. The regtech sector is projected to grow by 200% by 2026.

Financial institutions investing in regtech solutions anticipate significant cost savings, particularly as penalties for non-compliance can reach millions of dollars. For example, Bank of America once incurred a $42 million penalty from New York State for inadequate disclosures regarding the handling of client share orders.

Regtech Solutions Will Streamline Operations infographics

Source: Fortune

RegTech simplifies how organizations interact with regulatory bodies, allowing for uninterrupted data transmission, ongoing compliance monitoring (such as adherence to PCI compliance standards), and the tracking of financial crimes.

6. ESG Drives New Fintech Opportunities

The imminent climate-related disclosure requirement from the U.S. Securities and Exchange Commission marks a significant change in business regulations. Fintech companies must know their emissions and demonstrate efforts to reduce climate risk. Leaders must establish systems, possibly collaborating with their finance teams, to report ESG data publicly.

This requirement shift paves the way for the rise of new fintechs dedicated to ESG-oriented activities. These include tracking carbon and managing supply chains, financing alternative energy and climate projects, and managing property and energy.

Fintechs focusing on ESG stand to increase and draw significant investment to bolster these initiatives.

7. Robotic Process Automation to Streamline Routine Finance Tasks

Robotic Process Automation (RPA) is reshaping finance departments in numerous industries by automating routine and labor-intensive tasks, thus improving efficiency and accuracy. Several financial institutions have adopted RPA to streamline processes like data collection for customer due diligence and KYC, reducing the time required from minutes to mere seconds.

RPA is progressing from automating individual tasks to entire processes, significantly enhancing the precision of financial analysis and forecasts. This advancement aids finance functions such as invoice management and account reconciliation and extends to more complex activities like tax calculations and financial reporting.

user penetration of fintech to rise due to robotic process automation infographics

Source: Statista

Plus, combining RPA with cognitive automation technologies, such as machine learning and natural language processing, creates new opportunities for finance departments. These technologies enable more sophisticated applications like auditing expense reports and managing compliance more effectively.

Financial leaders increasingly acknowledge the benefits of RPA in driving cost reductions and operational efficiencies. The global RPA market size is projected to reach $50.50 billion by 2030.

Conclusion

As the fintech sector evolves, developers and service providers must stay informed on emerging trends. The second half of 2024 promises significant developments, including the rise of embedded finance, the expanding adoption of open banking, and the growing appeal of neo-banks among GenZ. AI continues to revolutionize banking and financial services, offering enhanced customer experiences and improved operational efficiencies. Regtech solutions are set to streamline regulatory compliance, reducing risks and costs.

Additionally, ESG initiatives are creating new fintech opportunities, while Robotic Process Automation (RPA) is transforming routine finance tasks. Embracing these trends will enable fintech companies to innovate, stay competitive, and meet the evolving needs of their customers.

Top Ways to Make Money Online, Offline, and From Home

Top Ways to Make Money Online, Offline, and from Home

With rising inflation, the prices of many items have reached new heights. It’s worthwhile for everyone to consider earning a side income tailored to their skills and knowledge. There are numerous ways to make money online, offline, and from home.

You’ll find a variety of simple tasks that can help you earn extra money. Almost daily, new platforms emerge designed to facilitate money-making through online freelancing in innovative ways. Traditional methods are also viable; for instance, driving for ride-sharing services remains a popular way to earn. From teenagers to senior citizens, everyone has the opportunity to earn quick extra cash.

In the following sections, we’ll explore diverse ways to make money quickly, whether online, offline, or from home.

What Are the Best Ways to Make Money Online?

What Are the Best Ways to Make Money Online?

Many people aspire to work online, drawn by the potential benefits, but weighing these against the possible drawbacks before committing is essential. The primary advantage of online work is its flexibility; you can choose your work environment and schedule. This also eliminates the need for commuting, saving both time and money.

If you’re looking for effective ways to start earning money online today, here are some viable options to explore:

1. Launch Your Blog

Expected Earning: $500 to $10,000+ per month

If you have a passion for writing and prefer to avoid the traditional 9-5 job structure, starting a blog might be the right choice. A blog is a platform where you can consistently share your insights or expertise with an audience. Initially, you’ll need to set up a website, which you can either build yourself using user-friendly platforms like Wix or outsource to a professional developer.

Once your website is operational, the focus shifts to producing engaging content regularly and promoting your blog to draw in readers and subscribers. Building a sizable audience is essential for generating income from your blog. Revenue can be earned through affiliate marketing, where you recommend products, or through advertisements. Additionally, you could develop and sell your products or services directly on your blog.

2. Exploring Freelance Opportunities

Freelancing opens a realm of income opportunities for various skills and interests. Here are some of the most sought-after freelance roles:

  • Web Developer ($30 to $150 per hour): If you’re proficient in web development, you can earn by building websites for clients. Successful web developers combine functionality with aesthetic appeal to create websites that meet client needs.
  • Graphic Designer ($25 to $85 per hour): For those with a knack for art, freelancing as a graphic designer might be ideal. This role involves creating eye-catching graphics for logos, posters, and ads, providing a profitable avenue for those with creative skills.
  • Social Media Manager ($50 to $75 per hour): As a freelance social media manager, you would manage the online presence of businesses or individuals, crafting content, developing strategies, engaging with audiences, and analyzing performance metrics.
  • Virtual Assistant ($15 to $30 per hour): This role supports businesses remotely by managing emails, scheduling appointments, and preparing documents, offering a flexible way to work from anywhere.
  • Data Entry Specialist ($10 to $20 per hour): If you have a keen eye for detail, data entry could be a suitable freelance job. This role involves accurately entering information into digital systems like spreadsheets or databases.

Websites like Freelancer, Fiverr, and Upwork are excellent places to start looking for freelance work. These platforms cater to freelancers seeking to supplement their income or considering a full transition to self-employment.

Additionally, our virtual job board is an invaluable resource for expanding your online career. It offers a comprehensive list of remote and freelance job opportunities, including virtual assistant roles and other freelance positions.

Your earnings as a freelancer will vary based on your skills, specialization, location, and market demand. Freelancers can earn anything from a few hundred to several thousand dollars per project, with highly experienced professionals potentially commanding even higher fees.

3. Transcription Work

Expected Earning: $2 to $25 per hour

Transcription involves converting audio files into written text, similar to data entry but with a focus on audio content. This job requires fast and accurate typing skills.

Websites like Rev and Transcribe Me offer opportunities for transcriptionists. Initially, the pay might be modest, but as you improve your typing speed and accuracy, your potential to earn more will increase.

4. Affiliate Marketing

Expected Earning: $100 to $10,000+ per month

Leveraging a strong online presence can make affiliate marketing a profitable venture. In affiliate marketing, you promote products or services from other companies on your platform and earn a commission for each purchase made via your referral links.

The key to success in this field is to partner with the right companies and tailor your promotions to match your audience’s interests.

Affiliate Marketing

5. Online Courses and Tutoring

Expected Earning: $20 to $60 per hour

The demand for online learning is continuously growing. If you possess specialized knowledge in a particular area, you might consider creating an online course on platforms like Thinkific.

Additionally, online tutoring offers an opportunity to impart math, science, or languages expertise through platforms like Tutor.com.

6 Starting a YouTube Channel

Expected Earning: $3 to $5 per 1,000 views

Creating a YouTube channel offers multiple avenues to generate income online. A common method is incorporating AdSense ads into your videos, which earns you money each time an ad is clicked. Additionally, you can promote products directly in your videos by using or wearing them, linking to your online store where viewers can purchase these items or partnering with third parties to advertise their products. Ensure your promotions are attractive to your audience.

Another revenue option is through sponsored content, where you can profit by featuring branded products or producing content specifically for marketing purposes.

7.   Launching a Dropshipping Business

Expected Earning: $500 to $5,000+ per month

Dropshipping is a straightforward and potentially profitable business model. It eliminates the need for inventory storage, as you serve as an intermediary. Source products at wholesale prices from suppliers online, then sell them at a markup to make a profit.

With thousands of suppliers, you can deal in a wide range of products, from electronics and apparel to jewelry and health foods. For this business, you’ll need your website or online store to market and sell the products effectively.

8.   Participating in Online Surveys

Expected Earning: $1 to $5 per survey

You can indeed earn money by participating in online surveys. Numerous survey sites allow you to fill out surveys during your free time in exchange for gift cards or cash. However, it’s important to note that some survey sites offer better rewards than others.

Branded surveys, for instance, are popular for their attractive features, like sign-up bonuses, competitions, loyalty programs, and competitive payouts, with potential earnings of up to $5 per survey. Payment methods vary among survey programs: some may offer a bonus upon registration, others might credit cash to your online account, and some provide loyalty points redeemable for gift cards at popular stores or restaurants.

It’s also crucial to choose surveys that match your background to increase your chances of qualifying and maximizing your earnings.

9. Writing and Publishing an Ebook

Expected Earning: $500 to $5,000 per book
Writing and Publishing an Ebook

Another approach if you are a keen writer and possess knowledge on a specific topic is to consider writing and publishing an ebook as a way to earn money online.

Ensure that your ebook’s subject aligns with your blog’s theme to enhance sales prospects, as your blog audience is already interested in your niche. Additionally, you could grow a newsletter list to promote your ebook to potential buyers.

10. Begin Investing

Expected Earning: Varies widely based on market performance

Although it’s worth exploring alternative investment options such as real estate and cryptocurrency, take notice of the traditional stock market. Many people think they can’t invest in stocks due to a lack of funds.

Fortunately, entering the stock market usually doesn’t require a minimum balance. Numerous brokerage platforms are available, and you should watch a YouTube channel that reviews these platforms to help you choose the one that best suits your needs.

However, investing in the stock market requires caution. Predicting market movements is challenging, and anyone claiming certainty about future trends likely doesn’t have your best interests in mind.

Therefore, consider taking some courses, watching videos, or reading books about the stock market. It’s wise to diversify your investments, and investing in an industry you are familiar with can be a strategic move.

What Are the Best Ways to Earn Money at Home?

What Are the Best Ways to Earn Money at Home?

Apart from all the “online” options that we have discussed above, here are some more ideas to earn some extra bucks while sitting at your home:

1. In-Home Daycare

Expected Earning: $200 to $800 per week

Starting an in-home daycare could be a rewarding option if you enjoy caring for children or are already watching your own kids at home. These daycares often offer lower rates than traditional centers, potentially drawing a consistent clientele.

Your earnings will vary based on your location, how many children you can accommodate, and their ages. Typically, providers set a daily or weekly fee.

2. Pet Sitting

Expected Earning: $15 to $40 per visit

For those who love animals, pet sitting is another viable income source. This role involves caring for pets, often at the owner’s residence. If you choose to host pets at your own home, consider investing in marketing and insurance to enhance your business’s credibility.

Consulting with an accountant, bookkeeper, or lawyer about liability issues is also advisable.

3. Room Rentals

Expected Earning: $50 to $200 per night

Renting out an unused bedroom or basement can provide extra income with platforms like Vrbo or Airbnb.

You can attract guests by creating an appealing listing that highlights your space’s features and amenities. Simplifying access, such as using a lockbox for keys and employing a cleaning service, can help streamline the process, turning it into a source of passive income.

4. Selling Handmade Crafts and Art

Expected Earning: $500 to $3,000+ per month

Consider selling your creations online if you’re skilled in arts or crafts, including painting, sewing, or crafting. You can establish a personal website with an e-commerce platform or utilize established online marketplaces like Redbubble, Amazon, or Etsy.

Selling through these marketplaces can simplify the process as they handle much of the marketing and traffic, but they take a portion of your earnings or charge fees. If you prefer to retain full profit, creating your website might be the way to go, although it requires more investment in terms of design, security, and overall management.

5. Car Rental

Expected Earning: $30 to $100 per day

Renting out your car is an alternative if you’re hesitant to rent out your home. Ensure your vehicle meets the necessary standards for cleanliness and maintenance as required by the rental platform. Additionally, confirm that your car insurance covers this type of usage.

It’s also important to understand the insurance and liability coverage offered by the rental platform, especially if the renter incurs traffic violations or is involved in an accident.

6. Remote Customer Service Jobs

Expected Earning: $12 to $20 per hour

For those interested in more traditional employment that allows you to work from home, remote customer service positions are a good choice.

Many customer service jobs today are home-based rather than in call centers. This role typically requires specific equipment like a headset with a microphone and a quiet work environment to handle calls effectively.

What Are the Best Ways to Earn Money Offline?

What Are the Best Ways to Earn Money Offline?

1. Work as a Rideshare or Delivery Driver

Expected Earning: $15 to $25 per hour

Working as a driver for popular delivery or rideshare companies offers a way to earn money quickly with a flexible schedule. This type of job is active and allows you to set your own hours. It provides opportunities to interact with new people and discover different areas.

To drive for companies like Uber or Lyft, you need a vehicle insured and in good condition, typically no older than 10 years, a clean driving record, and a valid driver’s license. The entry requirements are minimal, and you can start driving once approved.

Consider these platforms if you’re interested in such work:

  • Uber
  • Lyft
  • Uber Eats
  • Instacart
  • Grubhub
  • Amazon Flex
  • DoorDash

2. Work as a Fitness Instructor or Personal Trainer

Expected Earning: $30 to $70 per hour

If fitness is your passion and you have knowledge in a particular exercise discipline, working as a fitness instructor or personal trainer could be a rewarding career path. You could lead group fitness classes or conduct individual training sessions to assist others in reaching their health and fitness objectives.

Start by acquiring the required certifications and qualifications. Then, advertise your services at local gyms, community centers, or through social media. Design customized workout plans for your clients to keep active, motivate others, and make money from your passion.

3. Launch a Food Truck or Side Food Venture

Expected Earning: $1,000 to $5,000+ per month

In the world of culinary delights, great and unique offerings are always sought after. If you have a distinct concept for a food item or service, pursuing it could lead to substantial rewards. Food trucks, especially, have carved out a niche in various sectors, including events like weddings where they are becoming increasingly popular.

Remember, every successful product in a grocery store began as an idea. Consider local preferences, health and safety regulations, and potential hotspots for parking your food truck to maximize visibility and attract a steady stream of customers.

4. Start an Errand or Cleaning Service

Expected Earning: $20 to $50 per hour

In today’s fast-paced world, many people, including busy professionals and seniors, struggle to find time for everyday chores like cleaning or running errands. Starting a service that offers high-quality, reliable help in these areas can be lucrative. Focus on building a reputation for dependable and efficient service to command premium rates. Market your services through local community centers, social media, and by word of mouth.

Consider leveraging or emulating platforms that connect consumers with immediate help for daily tasks. These platforms include services such as cleaning, moving, delivery, and handyman tasks. By creating or joining a similar platform, you can reach a broader audience that seeks quick and efficient solutions to their routine needs. This approach not only diversifies your service offerings but also enhances your accessibility to potential clients looking for flexible and prompt service solutions.

Conclusion

In today’s economy, there are numerous opportunities to generate supplementary income. Whether you prefer working online, offline, or from home, the options available cater to a wide range of skill sets and preferences. From blogging and freelancing to more traditional roles like providing ride-sharing services, each avenue comes with its own set of advantages.

Flexibility and accessibility are key perks, allowing individuals from diverse backgrounds to seek out additional income. Exploring these opportunities can assist you in identifying the best fit for your lifestyle, enabling you to effectively capitalize on your skills and interests to increase your earnings.

The Future of Digital Wallets

The Future of Digital Wallets

Digital wallets are becoming increasingly important in today’s digital transformation, significantly altering how we handle our finances. In 2022, approximately 2.8 billion mobile wallets were in use globally, making up about half of all e-commerce payment transactions. Research predicts that by 2026, the number of digital wallet users will rise to over 5.2 billion, representing more than half of the world’s population. As we look to the future, it’s essential to examine the emerging trends and innovations that will influence the future of digital wallets.

What Are Digital Wallets?

Digital wallets, or e-wallets, are electronic devices or online services that facilitate digital transactions and streamline payment management. These wallets store various payment methods, such as credit card and bank account details, allowing users to purchase goods and services across numerous platforms.

Digital wallets provide a convenient, quick, and secure payment method, eliminating the need for physical cards and cash. Additionally, they typically offer features like transaction histories, loyalty rewards, and budgeting tools, making them essential in modern financial management.

Evolution and History of Digital Wallets From 1990s to 2024

Evolution and History of Digital Wallets From 1990s to 2024

The history of digital wallets is marked by pivotal technological developments and increasing adoption across the globe. The concept was first introduced in 1997 when Coca-Cola enabled consumers in Helsinki to purchase drinks via SMS. This early example was followed by the launch of PayPal in 1999, which quickly became a preferred method for securing online transactions, highlighting the importance of digital wallets in e-commerce.

The early 2000s witnessed significant milestones that shaped the digital wallet landscape:

  • In 2003, Alibaba introduced Alipay in China, revolutionizing regional payment methods and setting a model for future digital wallets.
  • M-PESA was launched in Kenya in 2007, providing essential mobile money transfer and financial services, especially for populations without traditional bank accounts.
  • The emergence of Bitcoin in 2009 introduced the concept of decentralized digital payments, leading to the development of cryptocurrency wallets.

In 2011, Google Wallet was introduced, allowing users to store card information and make mobile payments. This initiative was initially limited to specific phones and banks. This innovation was followed by Apple’s introduction of Passbook in 2012, which evolved into Apple Wallet, broadening its capabilities beyond mere payment information.

The integration of financial transactions with social media platforms was showcased in 2013 when WeChat Pay was incorporated into the WeChat messaging platform. The launch of Apple Pay in 2014, followed by Android Pay and Samsung Pay in 2015, extended digital wallet services to a global audience, simplifying payments via smartphones and contributing significantly to the rise of digital wallets worldwide.

These services have progressively incorporated features such as loyalty programs, budgeting tools, and biometric security measures, enhancing their appeal and security. The adoption of NFC technology and tokenization in recent years has further enhanced payment safety and convenience.

By 2023, digital wallets accounted for $13.9 trillion in global transaction value, covering half of all online and 30% of in-person sales at retail points. This trend is expected to accelerate, with projections indicating that digital wallets could manage over $25 trillion in global transactions by 2027, driven by their convenience, security, and rapid adoption of mobile technologies.

These continuous advancements highlight the critical role of digital wallet technologies in transforming financial transactions and shaping the interactions between businesses and consumers in the evolving digital economy.

The Rise of Super Apps and Super Wallets

The Rise of Super Apps and Super Wallets

The digital world is continually changing, and super apps have emerged as a significant force within this ecosystem. But what exactly is a super app?

A super app is a comprehensive digital platform that combines various services like gaming, shopping, transportation, and payments into one cohesive experience. It goes beyond being just another mobile app—it’s a versatile tool that offers everything from instant messaging and social media to e-commerce, digital payments, and transportation services. The goal of super apps is to simplify life by consolidating multiple functionalities into one platform, increasing daily usage and user engagement due to its convenience.

The popularity of super apps is especially noticeable in markets across Asia, Africa, and Central America. Companies like WeChat, Paytm, Gojek Tech, and Grab have captured significant market shares by integrating numerous services into a single, easy-to-use interface. Even Elon Musk has plans to transform X, previously known as Twitter, into a super app.

On the other hand, digital “super wallets” are expanding the scope of financial services accessible to users. Beyond merely facilitating payments, these wallets enable investments, loans, account tracking, and more. While traditional mobile wallets primarily secure tokenized information for credit cards, debit cards, and bank accounts, the newer digital wallets enhance functionality by incorporating additional financial services such as loans, insurance, investments, and digital banking.

In the US, several fintech companies are entering the arena of super apps, hinting at an upcoming surge in competition. Success in this space, marked by becoming the go-to super app with widespread customer trust and adoption, could make a company exceptionally valuable. PayPal, for instance, launched its financial super app in 2021, positioning itself against major players like WeChat and AliPay.

This app builds on PayPal’s existing services, such as its mobile wallet and P2P payments, by adding features like high-yield savings accounts through a partnership with Synchrony Bank Financial, a bill management tool, an early access direct deposit feature, credit and “buy now, pay later” (BNPL) options, gift card and rewards, and an in-app shopping function with loyalty rewards. Through these enhancements, PayPal is striving to craft a comprehensive financial ecosystem where users have little reason to look elsewhere.

Similarly, Venmo, a PayPal subsidiary popular among Gen Z users, is expanding its offerings. Since its acquisition, Venmo has introduced a cash account, debit and credit cards, direct deposits, in-store QR payments, shopping, and crypto investments, further diversifying its functionalities.

Future of Digital Wallets: Trends and Technology Predictions

future of digital wallet infographic

Source: Juniper Research

As digital wallets become more popular, the industry is expected to expand and innovate continuously. Here’s a look at some anticipated trends and developments in the digital wallet sector:

Artificial Intelligence Integration

A key trend is incorporating artificial intelligence (AI) in digital wallets. AI enhances the banking experience by offering personalized recommendations and alerts.

For example, digital wallets might use AI to recommend the most suitable credit card or payment method based on a user’s spending patterns. AI also plays a crucial role in fraud prevention by analyzing transaction data in real-time to identify and stop fraudulent activities.

Worldwide Payments and Remittances

Digital wallets utilizing blockchain technology are also revolutionizing global payments and remittances. Traditional services like MoneyGram and Western Union often impose high fees and can take several days to process international transfers. In contrast, blockchain-enabled digital wallets provide a faster, more cost-effective alternative for international money transfers, benefiting global remittances and e-commerce.

As digital wallets continue to embrace blockchain technology and support new applications such as cryptocurrencies, smart contracts, and global transactions, they are set to change financial services fundamentally. The future of fintech is likely to be dominated by platforms that offer open, decentralized, and secure access to digital assets and programmable money. Digital wallets are expected to lead this transformative era.

Expansion Into New Markets

Digital wallets are also making headway into new markets. With increasing access to smartphones and the internet globally, these wallets are becoming a favored payment option.

Companies are targeting expansion in regions like developing countries, where traditional banking facilities are less accessible. In places like India, digital wallets are widely used for transactions, including in rural areas where conventional banking is limited.

Adapting to Consumer Behavior

Banks face the challenge of adapting to changing consumer behaviors as digital wallets gain traction. They need to ensure that their services are compatible with digital wallet platforms and invest in the necessary infrastructure to support these services.

Plus, understanding and responding to shifts in customer preferences is vital. Younger consumers are more inclined to use digital wallets, necessitating banks to tailor their offerings to appeal to this demographic. Banks might also consider implementing small business phone systems to enhance communication with younger customers.

The Smart Contract Revolution

The Smart Contract Revolution

Blockchain platforms such as Ethereum are pioneering the use of “smart contracts,” which are self-executing contracts with the terms of the agreement directly written into code. These smart contracts eliminate the need for intermediaries by automatically enforcing agreements. Digital wallets integrate smart contract capabilities and enable users to effortlessly create and interact with these advanced contracts, potentially transforming business practices.

Decentralized Finance (DeFi) Integration

Digital wallets are poised for significant changes with the addition of decentralized finance (DeFi) features. These features will allow users to directly participate in decentralized lending, borrowing, and earning interest through digital wallets. This shift towards decentralization gives users direct control over their financial transactions and eliminates the need for traditional financial intermediaries such as banks and brokers.

Incorporating DeFi capabilities into digital wallets could create a more inclusive financial environment. Users from diverse economic backgrounds, including those previously excluded from traditional banking systems, will have the opportunity to access financial services. This could change the way people manage their finances, making it more democratic and widely accessible. The ability to manage assets in a secure, decentralized setting could also increase trust and adoption of digital financial services, potentially broadening the scope for investment and wealth building for a larger group of people.

Central Bank Digital Currencies (CBDCs)

Recent studies show that over 80% of the world’s central banks actively research or test Central Bank Digital Currencies (CBDCs). Following this trend, digital wallets are expected to add support for CBDCs soon, making it easier for users to switch between traditional and digital currencies.

This addition is likely to enhance the efficiency of financial transactions significantly. By facilitating immediate, digital transfers of money issued by central banks, CBDCs could lower the costs and time linked to traditional banking operations. Moreover, including CBDCs in digital wallets is a step towards an increasing shift towards a cashless society. It simplifies transactions and promotes financial inclusion by offering accessible digital currency options for those without traditional banking accounts. This development is expected to improve overall economic efficiency and foster the wider use of digital financial services globally.

Predictive Analysis:

Leveraging predictive analytics with digital wallets offers a pathway to craft personalized application user experiences. This technique enables businesses to anticipate user needs and tailor interactions based on individual behavior and preferences.

Companies can predict future buying behaviors by analyzing transaction patterns and user data, thus facilitating more tailored and proactive customer service. This strategic application of predictive analytics enhances user satisfaction and streamlines transaction processes, making them more efficient.

Enhanced Authentication:

Integrating digital wallets with the biometric capabilities of smartphones and other devices significantly enhances security. This security measure is becoming a standard practice among global digital wallets, attracting users by offering stronger protection of their financial information.

Biometric authentication reinforces security and simplifies the transaction process. Users can complete payments swiftly and securely, enhancing overall transaction efficiency and user trust in the digital wallet platform.

Conclusion

Digital wallets are poised to revolutionize financial transactions, reflecting a significant shift from traditional banking. With the number of users projected to exceed 5.2 billion by 2026, their impact on global commerce is undeniable. The evolution from basic payment tools to multifaceted super apps and super wallets showcases their expanding role in daily life.

Future AI, blockchain, and biometric security advancements will further enhance their functionality and security. As they integrate features like smart contracts, DeFi, and CBDCs, digital wallets will continue transforming the financial landscape, making transactions more efficient, secure, and accessible worldwide. Businesses and consumers must stay informed and adaptable to harness these innovations effectively.

Walgreens to Close Significant Number of Underperforming Stores

Walgreens to Close Significant Number of Underperforming Stores

Walgreens plans to close many of its stores in the United States. Targeting underperforming stores, the closures are due to continuous struggles with profitability and declining margins. These closures are part of Walgreens’ ongoing effort to optimize its store network. Although the number of stores to be closed has not been disclosed, CEO Tim Wentworth indicated that a substantial portion of the underperforming stores would close.

The company is adjusting its store presence, with approximately 25% of its 8,700 locations deemed non-contributory to its long-term goals. Walgreens’ stock price fell in pre-market trading on Thursday following a reduction in its profit forecast for 2024. The stock has declined over 45% in the past year.

Key Takeaways
  • Strategic Store Closures: Walgreens is undertaking significant store closures across the United States to address profitability challenges and declining margins. Approximately 25% of its locations are targeted for closure, reflecting a strategic effort to optimize its store network amidst challenging market conditions.
  • Financial Impact and Market Response: The announcement of store closures coincided with a sharp decline in Walgreens’ stock price, highlighting investor concerns over the company’s profit forecast for 2024. Despite recent sales and operating income improvements, Walgreens continues to navigate substantial losses from previous years.
  • Industry-wide Challenges: Like its competitors, Walgreens faces industry challenges such as reduced profits from prescription services and heightened competition from larger retail chains and online platforms like Amazon. Adjustments in product offerings and strategic shifts towards house brands aim to enhance profitability and competitiveness in the retail pharmacy sector.
  • Future Strategic Focus: Looking ahead, Walgreens is prioritizing its core retail pharmacy business while exploring new payment structures with insurers and benefit managers. Despite ongoing market uncertainties and competitive pressures, this strategic realignment underscores its commitment to sustainable growth and operational efficiency.

Walgreens’ Strategic Restructuring Amidst Challenging Market Conditions

Walgreens' Strategic Restructuring Amidst Challenging Market Conditions

Walgreens intends to shut down many of its underperforming stores throughout the United States as part of a strategy to mitigate losses. This move was announced alongside the company’s third-quarter earnings in a press release that received an adverse reaction from Wall Street. Following the announcement, Walgreens’ stock price fell more than 20% due to difficult trends in the pharmacy sector and a tougher-than-expected consumer environment in the U.S.
The decision to close these struggling stores aims to improve the company’s performance as it enters a new quarter. However, the specific number and locations of the stores to be closed were not revealed. However, the decision to close stores will be based on each store’s profitability and shrink levels, consumer behavior, and local competition. Walgreens may also close stores that are near another Walgreens location. The company plans to reassign nearly all employees affected by these closures to other stores to prevent widespread job losses.
A Walgreens representative stated that about 25% of its stores are not aligned with the company’s long-term goals, and a substantial number of these stores are expected to close within the next three years.

CEO Wentworth stated in a press release that the company is dealing with a challenging operating environment, facing ongoing pressures on the US consumer and recent market dynamics that have reduced pharmacy margins. He noted that these factors are reflected in the company’s results and projections. Inflation has significantly impacted the drugstore business, affecting both the retail and pharmacy ends. Wentworth also mentioned that consumers are becoming more selective and sensitive to prices. He added that he expects the challenging conditions in the US to persist without foreseeable improvement.
The company indicated it might consider further store closures if profitability does not improve.

Walgreens reported a 2.6% increase in sales to $36.4 billion and a quarterly operating income of $111 million, a significant improvement from a $477 million loss last year. Boots Alliance also reported net earnings of $344 million for the quarter. However, the company is still addressing earlier losses from this year, with an operating loss of $13.1 billion and a net loss of $5.6 billion, up from $2.9 billion year over year.

Sales in the US retail pharmacy segment grew by 2.3% YOY to $28.5 billion, and U.S. healthcare sales increased by 7.6% to $2.1 billion for the quarter. VillageMD and Shields contributed to this growth, with sales up 7% and 24%, respectively, from last year. Notably, Walgreens is reducing its stake in VillageMD and has shifted its strategy away from investing in medical offices. Last year, Walgreens began reducing VillageMD’s footprint to boost the division’s profitability. Earlier this year, Walgreens intensified its cost-saving efforts by increasing the number of VillageMD clinic closures, although its strategy has since evolved.
Furthermore, the U.S. healthcare business reduced its operating losses from $522 million last year to $220 million in the third quarter.

Wentworth added that guided by its strategic review, its focus is on enhancing its core business, retail pharmacy, which is crucial to the future of healthcare. They are urgently addressing key challenges and striving to create growth opportunities. While many of these initiatives will require time, he expressed confidence in having the right team and strategy to drive a turnaround for Walgreens, which their customers and patients rely on.

Adapting to Industry Challenges

Adapting to Industry Shifts…

Walgreens’ competitors like Rite Aid and CVS have also encountered significant difficulties, primarily driven by reduced profits from their prescription filling operations. These issues arise from lower reimbursement rates for prescription drugs and heightened competition from new market players like Amazon, which has expanded into prescription services via its online platform.

Additionally, these chains face competition at the front end of their stores—areas selling daily necessities like snacks and household items—from larger retailers like Target and dollar stores, which generally offer lower prices and greater convenience.

Walgreens is adapting its strategy to address these industry-wide issues. The company is modifying its product selection by discontinuing eight national brands in favor of its house brands and selecting “preferred partners,” especially in health and wellness categories. This adjustment aims to sharpen their focus and improve profitability in their retail operations.

Despite these ongoing challenges, drugstores saw a temporary increase in business during the pandemic, spurred by the demand for COVID-19 vaccines and a general rise in health consciousness. Nevertheless, this surge did not fully mitigate the persistent decline in in-store visits and prescription volumes, which were also affected by a decrease in elective medical procedures.

What Does the Future Hold for Walgreens?

What Does the Future Hold for Walgreens?

Continuing forward, Walgreens is concentrating its approach once again on its main line of retail pharmacies. The firm intends to launch a retail pharmacy action plan to improve customer experience in its stores, better integrate its pharmacy and healthcare operations, and focus on products that sell—particularly in women’s health.

Furthermore, Walgreens is attempting to stabilize an unstable reimbursement environment by modifying the payment structure for its pharmacies through negotiations with pharmacy benefit managers and health insurers. This measure is similar to what its national rival CVS did last year to boost sluggish income by changing how it paid for prescription medications. According to Wentworth, the present pharmacy approach is unworkable.

Walgreens is not giving up on the healthcare industry entirely, either. The business does not intend to sell its specialist pharmacy, Shields Health Solutions, or Boots drugstore network in the United Kingdom. As previously said, Shields helped the division record a second straight quarter of positive adjusted profitability during the third quarter by continuously supporting expansion in the US healthcare industry.

Walgreens has been cutting costs, as evidenced by the large number of corporate employees it let go at the end of last year. It has also recently sold off other healthcare assets, such as its shares in drug distributor Cencora and home infusion provider Option Care Health.

About Walgreens

Walgreens Co., established in 1901 by Charles R. Walgreen Sr., is a U.S.-based drugstore chain headquartered in Deerfield, Illinois. The company operates numerous stores nationwide, offering prescription and over-the-counter drugs, general merchandise such as household items, food, personal and beauty care products, photofinishing services, and candy.

The company offers various nationwide pharmacy services, including retail and specialty pharmacy, infusion and respiratory services, mail services, and clinics in convenient places and workplaces. Walgreens specializes in managing complex and chronic health conditions through these services. It provides infusion therapy for conditions like cancer, chronic pain, heart failure, and other infections, which can be administered at homes, workplaces, physician offices, or at Walgreens’ alternative treatment sites.

Walgreens’ advanced pharmacy system improves pharmacists’ ability to access patient records, assisting with prescription refills, emergency supplies, prescription transfers, and consultations for ongoing treatment. The company also operates websites that sell products from beauty and personal care items to home medical equipment and health supplements.

Conclusion

Walgreens’ decision to close many underperforming stores underscores its commitment to strategic optimization amidst challenging market conditions. With a clear focus on enhancing profitability and aligning with long-term goals, these closures are part of a broader effort to streamline operations and navigate a complex economic landscape. CEO Tim Wentworth’s proactive approach reflects a necessary adaptation to sustain competitiveness and drive future growth in the retail pharmacy sector.

As Walgreens continues to refine its business strategy and prioritize core operations, including innovative healthcare services, the company remains poised to navigate ongoing challenges and capitalize on emerging opportunities in the evolving healthcare marketplace.

what is tipflation?

What Is Tipflation?

Tipflation is a combination of tip and inflation. It is a new phenomenon in which servers expect more tips than ever before because of consistent inflation since 2021. This is a shift from the traditional tipping norms after the pandemic. For decades, the typical tip in the US hovered around 15%, but this rate has risen over the last 15 years, with the average American now tipping closer to 20%.

If you find the tipping screen that pops up when you buy a sandwich or a coffee confusing or frustrating and makes you feel guilty or ashamed, you’re not alone. A recent survey reveals that many Americans share these feelings. In this blog, we’ll focus on tipflation, the discomfort it’s causing, and its pros and cons.

But first, let’s briefly review how we arrived at this point.

How Tipping Culture Came in America? A Brief History

How Tipping Culture Came in America? A Brief History

The origin of tipping has yet to be definitively known, but historical evidence indicates it was practiced in Tudor England from 1485 to 1603. During this period, visitors would give tips to the servants of their hosts as a thank-you for providing services during their stay. By the 19th century, boxes marked “to insure promptness (TIP)” appeared in English coffeehouses and inns, promoting tipping in exchange for swift and good service.

In the 1800s, Americans who traveled abroad and observed tipping in Europe decided to adopt this practice back in the US, keen to follow European traditions. The practice became widespread as a business strategy in the post-Civil War reconstruction era. Some hospitality businesses, notably employing freed slaves, paid them minimal wages and suggested that customers leave tips instead.

Today, tipping is standard in many service industries, irrespective of whether workers are paid the tipped minimum wage of $2.13 or the regular minimum wage of $7.25 per hour. Tipping is common in industries involving bartenders, restaurant servers, delivery personnel, drivers, porters, valets, baristas, and hairstylists.

Understanding Tipflation

Understanding Tipflation

Tipflation is a term gaining popularity online. As we have just gone through, tipping, giving a small sum of money to service providers such as waiters, hairdressers, or taxi drivers, is typically voluntary and reflects the customer’s satisfaction with the service – ranging from 15% to around 30%.

Tipping practices vary globally, being customary in countries like the US, the UK, and Canada but less common and even obscure in places like Japan, China, India, New Zealand, and even Australia.

Traditionally, tipping has been confined to service sectors where employers pay lower hourly wages. Still, employees retain the tips—a system seen as beneficial for both parties, particularly in the US.

Tipflation describes the trend of increasing demands for tips across a broader range of industries, extending beyond traditional service roles to include jobs and services previously untipped. This expansion is influenced by social norms, peer pressure, and feelings such as guilt or gratitude, but it is also significantly driven by technology and changes in payment systems, accelerated by the pandemic. Companies like Square facilitate tipping on any transaction, making it easier to add a tip with just a few clicks.

As these systems become widespread, the number of tips and the percentage of customers who tip will likely increase business revenue. This shift is evident when a payment kiosk turns towards a customer, signaling an upcoming prompt for a tip on a transaction that traditionally wouldn’t involve one.

With this new approach, businesses find innovative ways to encourage tipping or donations. However, tipflation is complicating the already contentious debate over tipping. While some view it as a personal choice unaffected by external pressures, others consider it a social and moral duty reflecting service quality. The evolving practice of tipflation is muddying these waters, leading to a backlash—so much so that a recent survey indicates that 66% of Americans now view tipping negatively, which could impact those who rely on tips as a significant part of their income.

What Causes Tipflation?

What Causes Tipflation?

The growing gap between wages and the cost of living, especially for those in the hospitality sector, has led people to increase their tipping voluntarily. Social pressures and expectations also contribute, creating a feeling of obligation to tip.

The pandemic played a role in accelerating tipflation, with many individuals tipping more generously to support service industry workers facing financial difficulties. Due to the pandemic and shifts in lifestyle, sales in the US food delivery industry increased by $28 billion from 2019 to 2020.

These workers, often on the front lines, fulfilled essential tasks such as running errands and delivering meals through various apps. During this time, leaving a 30% tip became a common practice, a trend that has persisted. Despite the end of pandemic-related restrictions, many of the increased service charges and tipping norms have persisted.

Low wages in the service industry further drive tipflation. Many workers depend on tips to supplement inadequate salaries, creating an impression that higher tips are essential for proper compensation. Companies have responded by setting higher default tipping options and encouraging customers to tip more.

What’s a Tip Creep in All This?

What’s a Tip Creep in All This?

Tip creep refers to a trend influenced by the shift to digital point-of-sale systems and app-based service platforms, which plays a role in the broader phenomenon of tipflation. These systems typically present customers with preset tipping options at the end of a transaction, regardless of the service quality, prompting users to leave a tip.

This method of soliciting tips can feel more compulsory than the passive presence of a cash tip jar on a counter. The constant prompts from digital screens can overwhelm and pressure customers into deciding whether to tip and how much to give.

Plus, attempting to leave a custom tip amount often proves cumbersome due to the design of many digital systems, which complicates entering a specific dollar value. Coupled with the social pressure of not wanting to appear stingy or ungrateful in the presence of staff, this setup can lead consumers to default to higher, preset tip percentages.

Previously, not leaving a tip was a standard default. However, digital payment technologies now typically require users to choose not to leave a tip actively. Behavioral economics suggests that people generally prefer to avoid making financial decisions, and these systems effectively force decisions on users who might prefer not to engage with them at all.

The Both Sides of Tipping Culture

Tipping presents both advantages and challenges within service industries. On the positive side, it allows some workers to earn more than they would with a fixed wage, especially in sectors where tipping is common and generous. This system also enables customers to reward exceptional service or express appreciation for a well-done job.

However, the tipping culture has significant drawbacks. Workers who rely on tips and do not receive sufficient amounts may face financial insecurity and struggle to meet basic needs. This dependency can burden customers with the expectation to tip, adding the stress of calculating appropriate gratuities.

About 30% of survey participants believe that tipping culture has become excessive, noting a rise in businesses prompting customers to tip at checkout. Many find preset tip screens irritating. 32% of Americans argue that companies should increase employee wages instead of depending on gratuities.

Furthermore, non-tipped employees might earn less than their tipped colleagues despite having similar job responsibilities. Overall, tipping contributes to income disparities and fosters a reliance on customer generosity rather than ensuring fair compensation from employers.

How Are Businesses Leveraging Tipping Culture to Their Benefit?

How Are Businesses Leveraging Tipping Culture to Their Benefit?

Businesses have found financial advantages in the current tipping system, particularly in the US, where, as mentioned, the minimum wage for tipped workers is $2.13 per hour, significantly lower than the standard minimum wage of $7.25 per hour. This legal framework allows companies to pay their employees below the minimum wage, relying on customer tips to supplement their earnings. This dependency on tips is bolstered by the “tip credit” policy adopted by the U.S. Congress in the 1960s, which permitted employers to pay a lower wage provided that tips make up the difference to reach a decent earning level, often expected to be 15-30% of service fees.

For businesses, particularly those operating with narrow profit margins, this system helps reduce labor costs since the tips contributed by customers help cover a substantial part of what would otherwise be direct wages from employers. While there have been efforts in some regions to increase the minimum wage, there are also discussions about potentially removing the minimum wage requirement for tipped workers altogether.

This arrangement leaves many customers questioning why they are responsible for ensuring fair compensation for service workers rather than the businesses that employ them.

Should You Tip? If So, How Much?

Should You Tip? If So, How Much?

As of 2024, attitudes toward tipping have shifted, even in the United States (being the bearer of the tipping culture). Many view it as a form of social pressure, particularly with online transactions or at new venues that offer limited choice in whether to tip.

The issue is that expected tipping amounts have increased. Restaurants dealing with higher food and labor costs have come to depend more on tips to compensate their employees, often incorporating suggested higher tip percentages in online payment systems.

The suitable tip amount varies based on the service provided and the quality of the service. According to many etiquette experts, a standard tip for services in the U.S. is about 20% of the total bill, with 30% considered quite generous. Since several employees, like restaurant servers and bartenders, make below the federal minimum wage, tipping them is considered appropriate.

Conclusion

Tipflation reflects a shift in tipping norms, extending beyond traditional service roles and impacting a broader range of industries. This trend has been accelerated by digital payment systems, inflation, and social pressures, resulting in increased tipping amounts and more frequent prompts. While tipping can reward exceptional service and support workers financially, it also raises concerns about fairness and the adequacy of wages.

Many Americans now view tipping as a source of discomfort, leading to calls for higher wages from employers instead of relying on customer gratuities. Understanding the complexities of tipflation helps navigate this evolving landscape and highlights the ongoing debate over tipping practices and their implications.

Frequently Asked Questions

  1. What is tipflation?

    Tipflation refers to the rising expectation for higher tips, often driven by digital payment systems suggesting preset tip amounts. This has led to tipping prompts in more service areas where tipping was uncommon.

  2. Why has tipflation become a prominent issue now?

    The pandemic increased sympathy towards service workers, leading to higher tips. Digital payment technologies have made suggesting and receiving tips easier. Inflation has also increased the base amounts from which tips are calculated.

  3. What are the historical roots of tipping?

    Tipping began in Tudor, England, to ensure prompt service and became popular in the U.S. in the 19th century, particularly post-Civil War, to compensate for low wages by encouraging customer tips.

  4. How should consumers handle tip requests and manage tip fatigue?

    Consumers can manage tip fatigue by budgeting for gratuities, understanding tipping etiquette, and tipping based on service quality. Carrying cash can also provide more control over tipping habits.

Apple Teleport

AI Advances Bring Apple’s Teleportation and Time Travel “Almost” Real

In a world where communication and travel are essential, Apple has introduced a revolutionary concept called Apple Teleport. This innovative idea is designed to change how we connect and move using advanced technologies. Apple Teleport, with a price tag of $29 million, aims to eliminate the challenges of distance and physical constraints, allowing for the instant transportation of individuals and objects across great distances, potentially in the future.

While it’s important to be optimistic, and we acknowledge the enthusiasm of forward-thinkers and technology enthusiasts, the reality of teleportation and time travel remains far off. So, what exactly is Apple Teleporter? This initiative is essentially a striking demonstration of AI’s ability to generate futuristic concepts that are as persuasive as fictional. Continue reading to learn more!

What Is Apple Teleport?

4 5

Many images and videos are circulating widely, and Apple has presumably launched a teleportation device named Apple Teleport at one of their events. Scientific advancements supposedly power this device and enable users to teleport instantly from one location to another. It is a transformative invention that will alter how people travel and connect.

Even Tim Cook, the CEO of the company, is featured in a viral video with a voiceover stating that today marks the beginning of a new era. He suggests that Apple’s Teleportation Device will overcome geographical barriers and expand the possibilities of human experience. He states that their goal has always been to develop products that significantly improve lives, and Apple Teleport is the epitome of this ambition. He imagines scenarios where people can visit the most remote places or reunite with loved ones instantly—highlighting seemingly limitless possibilities.

However, Apple Teleporter is part of an ambitious yet fictional vision that may not be possible, at least not in this decade. At the core of these misleading Apple Teleporter images and reports are generative AI models. These models are programmed to create new content based on the data they’ve been trained on.

These models utilize various neural network architectures, such as transformers for text (for example, Gemini, ChatGPT) and Generative Adversarial Networks (GANs) or diffusion models for images (for example, Midjourney, DALL-E).

How Can You Create These Types of Images Yourself?

3 5

First, you need to come up with some ideas you might like. You can request ideas from ChatGPT to begin.

You can give any prompt, like “Suggest some unique and funny product ideas that could be launched at an Apple Event this year.”

To which it generated:

  • Apple iBrush: “Brush smarter, smile brighter.”

A smart toothbrush that connects to your iPhone to track your brushing habits. It offers real-time feedback on brushing techniques, tracks dental health metrics, and even entertains you with jokes or trivia while you brush. The iBrush can also play your favorite playlist or podcasts via Bluetooth.

  • iMoodRing: “Wear your feelings on your finger.”

A modern twist on the classic mood ring that syncs with your Apple Watch to give more accurate readings. The iMoodRing changes color based on your mood, as detected by sensors that monitor heart rate, body temperature, and other biometrics. It can send notifications to your phone with mood-boosting activities or messages.

  • Apple AirCan: “Take a breath of adventure.”

A futuristic can of air that promises the “purest, cleanest air” from exotic locations worldwide. It comes in flavors like “Mountain Breeze,” “Ocean Mist,” and “Forest Fresh.” Each can have an AR feature that lets you see the scenic view from the air’s origin on your iPhone.

After having an idea and short content for your image, now you can use Midjourney,

Midjourney is an AI image generator that operates through Discord, allowing you to create images from text prompts. Here’s how to use Midjourney to generate images:

  • Register for both Discord and Midjourney.
  • Join the Midjourney Discord channel by accepting an invitation.
  • Navigate to the #newbies channel and type /subscribe.
  • Select a Midjourney subscription plan.
  • Initiate image generation by typing /imagining.
  • In the prompt field, enter a description of the image you want to create. For example: “Create an image of Tim Cook presenting a new Apple product at an Apple Event. He stands on stage with the iconic Apple backdrop, showcasing {YOUR PRODUCT}. The product is displayed prominently. Tim Cook has a playful smile, and the atmosphere is lighthearted yet professional.”
  • Send your message to start the process.

The development of imaginative products like Apple Teleport highlights the remarkable ability of artificial intelligence to generate creative content that is more than just entertainment and amusement. There are loads of possibilities in Pandora’s box that have yet to be opened.

This demonstrates the vast potential of AI technologies, such as OpenAI’s models like SORA, which can create highly advanced AI-generated videos that might surpass what is possible with high-end cameras. The future leans towards AI, and with these tools, a wide range of possibilities emerges—from teleportation to space exploration, reaching as far as Neptune and even the sun!

What Can You Expect in the Upcoming Apple Event?

Top 21 Ideas for Starting a Successful Retail Business

Even though Apple Teleport will not be released for some time, the company is anticipated to reveal new goods at WWDC, which takes place from June 10 to June 14.

Though specific goods to be unveiled are unknown, there are speculations of new iPads, Macs, and Apple accessories. This is what we could observe:

  • Mac Mini with M3 and M3 Pro Chips: With the iMac and MacBook Pro already equipped with M3 series chips, it seems logical that the Mac mini will soon follow. Although there are rumors that the Mac mini might wait for the M4 chips, missing the M3 update would leave a noticeable gap, especially since the Mac mini could be the only desktop model offering the M3 Pro chip.
  • Mac Studio with M3 Max and M3 Ultra Chips: The Mac Studio is also due for an update to include the M3 Max and M3 Ultra chips.
  • Redesigned Magic Keyboard: This new design features a larger trackpad and a partially aluminum enclosure.
  • New Apple Pencil: Expect at least one new model.

Significant developments are also likely for iPads. The M2 chip will be available in two new iPad Air versions, which will have a bigger 12.9-inch screen. Significant improvements are in store for the iPad Pro models, including adding an M3 CPU, OLED screens, a slimmer design, and a front camera best suited for landscape orientation. These devices might also have MagSafe charging capabilities and a revised rear camera bump.

Finally, Apple is set to introduce new color options for the iPhone 15 and iPhone 15 Plus, as well as coordinating options for Apple Watch bands and iPhone cases. These developments are intended to provide users with additional customization options, facilitating individual expression through color. The new cases improve the phone’s look and can be customized with a custom lanyard, allowing users to incorporate themes such as their favorite anime or movie. This add-on adds a unique touch and boosts security and convenience by making the phone easier to carry and less likely to be misplaced.

Conclusion

Apple’s concept of teleportation and time travel through Apple Teleport highlights the immense creative potential of AI. However, it remains firmly within the realm of fiction for now. The viral images and videos demonstrate how generative AI models can craft compelling and futuristic scenarios. While we may see such groundbreaking technology later, Apple continues to push boundaries in innovation.

Upcoming announcements at WWDC may include new products like the Mac mini, Mac Studio, iPads, and more, demonstrating Apple’s ongoing commitment to enhancing user experiences through advanced technology. As AI and other technologies evolve, the possibilities for future innovations remain excitingly vast.