Shopify Scams to Watch Out For

Payment Processing for Medical Practices

In the healthcare sector, where patient well-being and confidentiality are paramount, the security of financial transactions is critical. This isn’t just about processing payments but it is also about protecting sensitive patient information, from medical histories to financial records, with the highest level of diligence.

The industry is uniquely challenged and tasked with adhering to stringent regulations like the Health Insurance Portability and Accountability Act (HIPAA) while accommodating diverse services and their associated costs. This article aims to unravel the complexities of payment processing for medical practices, emphasizing the importance of selecting services that not only meet compliance standards but also enhance operational efficiency and patient satisfaction. With healthcare providers facing everything from routine preventive care charges to unforeseen emergency fees, the choice of merchant services and payment processing systems is pivotal in streamlining care delivery and ensuring the security and convenience of patient transactions.

Recurring Payments and Payment Plans

Medical care can be expensive. When patients cannot afford to pay their entire bill, they need credit card processing services that support payment plans and recurring payment options. This service allows patients to make payments online or during visits to your medical practice.
Recurring Payments and Payment Plans

Online Bill Pay

If patients are not required to pay their bills when services are rendered, an online bill pay option can make it easier and more convenient for patients to pay. This option can also reduce the need for collections and reminders. If your merchant services include an online payment portal, patients can pay their bill on their terms when they receive it in the mail.

Accept FSA/HSA

Flexible Spending Accounts (FSAs) and Health Savings Accounts (HRAs) give consumers a flexible option to pay for medical expenses with a tax-exempt trust. Today, these accounts come with a debit card that can be used on qualified medical expenses. HRA and FSA use are on the rise and it’s important for your practice to be set up to receive these payments, not just for patient convenience but also to increase collection activity.

A specialized medical merchant account can allow your practice to accept FSA and HRA debit cards by giving your practice a special MCC code that alerts the card issuer that your services or products are related to medical care.

Intuitive Dashboard for Staff

Your staff can benefit from a user-friendly system that shows updated patient balances and streamlines the checkout process. This also improves patient satisfaction and reduces unnecessary wait time. A good system will provide prompts to staff for outstanding patient balances with a real-time POS collection dashboard and other tools to manage billing.

Secure Data Storage

Security is always a big concern with payment processing, but medical offices face unique security concerns and requirements to keep patients’ data safe. Patients should be confident that their payments will be secure and their information will remain private at your practice. Medical merchant services specialize in payment solutions designed for medical providers that are PCI- and HIPAA-compliant.

If your practice is ready to begin accepting credit cards and HRA/FSA cards, or you are unhappy with your current payment processor, it’s time to make a change. Be sure you choose a processor that offers specialized tools to help your medical practice grow. At Host Merchant Services, we offer merchant accounts customized to your practice’s needs without hidden fees or costly term commitments.

Use Of Payment Processing In Medical Practices
Use Of Payment Processing In Medical Practices

Using payment processing for medical practices brings many benefits that extend beyond the mere transaction of funds. These advantages enhance operational efficiency, patient satisfaction, and financial security within the healthcare sector. Here are some key benefits:

Improved Cash Flow Management: Payment processing solutions facilitate faster transaction times, reducing the waiting period for payments to clear. This efficiency in processing payments leads to improved cash flow management, ensuring that medical practices have the necessary funds for daily operations, purchasing supplies, or investing in new technologies.

Enhanced Security: Security is paramount in healthcare, especially when dealing with sensitive patient information, including financial data. Modern payment processing systems have advanced security features like encryption and tokenization, significantly reducing the risk of data breaches and fraud. Compliance with regulations such as HIPAA is also ensured, protecting both the practice and its patients.

Increased Patient Satisfaction: The convenience offered by versatile payment processing options, such as credit/debit cards, online payments, and mobile wallets, meets the expectations of today’s tech-savvy patients. Easy and flexible payment solutions contribute to a better overall patient experience, increasing satisfaction and loyalty.

Streamlined Billing and Accounting Processes: Payment processing systems often come with integrated billing and accounting features that automate many of the tasks associated with financial management. This automation reduces errors, saves time, and allows staff to focus more on patient care than administrative tasks.

Access to Reporting and Analytics: Comprehensive reporting tools provided by payment processing systems offer valuable insights into financial trends, patient payment behaviors, and overall practice performance. These analytics can inform strategic decisions and help practices identify areas for improvement or investment.

Reduced Administrative Burden: Automating the payment process reduces the administrative burden on staff, freeing them from manual entry tasks and minimizing the chances of errors. This efficiency saves time and reduces the costs associated with managing payments, billing, and collections.

Compliance and Risk Management: Payment processors that comply with industry standards and regulations help medical practices manage risk more effectively. By ensuring that payment processing meets legal and regulatory requirements, practices can avoid costly fines and penalties associated with non-compliance.

Tips To Choose the Right Payment Processing Services for Medical Practices?
What are the Features to Look for in Payment Processing Services for Medical Practices?

When selecting payment processing services for medical practices, it’s crucial to choose a system that handles transactions efficiently and meets the healthcare industry’s unique needs. Here are essential features to look for:

  1. Compliance and Security: The service should adhere to industry standards, including the Health Insurance Portability and Accountability Act (HIPAA), to protect sensitive patient information. It should also employ robust security measures, such as encryption, tokenization, and PCI DSS compliance, to safeguard financial data against breaches and fraud.
  2. Integration Capabilities: Look for a payment processor that seamlessly integrates with your existing healthcare management systems, such as electronic health records (EHR), practice management software, and accounting systems. This integration streamlines workflows, reduces manual data entry, and minimizes errors.
  3. Multiple Payment Options: To enhance patient satisfaction and convenience, the service should support a variety of payment methods, including credit and debit cards, online payments, mobile payments, and possibly even payment plans for higher-cost procedures.
  4. Transparent Pricing: Opt for a payment processor with clear, straightforward pricing structures without hidden fees. This transparency helps medical practices manage finances better and avoid unexpected costs.
  5. Recurring Billing and Payment Plans: For practices that offer payment plans or manage recurring payments for ongoing treatments, the payment processor should provide features that automate these processes, including automatic billing and notifications.
  6. Robust Reporting and Analytics: Access to detailed reports and analytics enables practices to track financial performance, patient payment trends, and other vital metrics. This information is crucial for informed decision-making and financial planning.
  7. Customer Support: Reliable, responsive customer support is essential, especially in the healthcare sector, where timely payment processing is crucial. Ensure the service offers comprehensive support through various channels and has a strong reputation for resolving issues promptly.
  8. Ease of Use: The payment processing service should offer a user-friendly interface for staff and patients. Simplifying the payment process can reduce administrative burdens and improve patient experience.
  9. Mobile Payments and Portability: With the increasing use of smartphones and tablets in healthcare settings, the ability to process payments on mobile devices offers flexibility for practitioners and patients. This makes transactions possible anywhere, from bedside to remote consultations.
  10. Security of Patient Data: Beyond financial data, ensure the payment processor can securely handle and store patient health information if it’s involved in the transaction process, maintaining compliance with HIPAA and other relevant privacy laws.

Selecting a payment processing service that encompasses these features can significantly contribute to the efficiency, security, and patient satisfaction of medical practice, ultimately supporting its financial health and compliance with industry regulations.

Conclusion

To sum up, selecting the right payment processing solution is a crucial decision for medical practices, essential for safeguarding patient information, enhancing operational efficiency, and ensuring seamless financial transactions. The perfect blend of compliance, security, convenience, and integration capabilities not only streamlines the payment process but also reinforces patient trust and satisfaction.

As healthcare continues to evolve in its embrace of digital solutions, prioritizing a payment processing system that meets the unique demands of the medical field is indispensable. Ultimately, the right payment processing service empowers medical practices to focus on their primary goal: delivering exemplary patient care underpinned by a robust, secure, and efficient financial infrastructure.
High Risk Illustration SR18 3R1 1

5 Tips for High Risk Merchants 2026

5 tips for high risk merchants

5 Tips for High Risk Merchants

If your business is considered high-risk, it can seem impossible to find a payment processing company that will accept you. The truth is getting merchant services when your business is risky isn’t as difficult as it may seem. The key is taking steps to improve your chances before you apply for a high risk merchant account and working with a company that specializes in potentially risky businesses. The following tips can help you get approved for a merchant account and minimize your costs, whether you accept credit cards online or with a credit card machine.

#1. Be Upfront With the Processor
Don’t make the mistake of trying to lie or misrepresent your business when you apply for merchant services. If you do not fully disclose the services or products you offer, the credit card processing company will find out anyway. Your merchant account will probably be closed without notice and your business will be disrupted. If you are honest and work with a reliable processing company, you can still qualify for merchant account services.

Remember: getting a high-risk merchant account isn’t a bad thing; it just means the payment processor knows the risks associated with your business and is prepared for certain issues like higher-than-average chargebacks.

#2. Provide Previous History
If you have had a merchant account before, provide your previous processing history when you apply for a new merchant account. This will allow the processor to review your history and make an informed decision. Even if you have been denied service or dropped in the past, you can still find a payment processor who will work with you.

#3. Renegotiate Later
If your business is new, you will probably have a more restrictive account with higher terms because you do not have any processing history. You can renegotiate your reserves, rates, and other terms with your processor in a few months once you have sufficient history to review.

#4. Manage Chargebacks
A high chargeback ratio is one of the most common reasons for a high-risk merchant to have their account closed. The good news is there are several steps you can take to prevent chargebacks and address them before they become a problem. You can keep your chargeback ratio low by:

  • Making your refund policy clear on the receipt. Make sure you direct customers to contact you directly if they are unsatisfied rather than contacting their credit card issuer. A clear refund policy can also help you win invalid disputes.
  • Look for red flags that indicate fraud. You may require information that a hacker or thief is unlikely to have, such as the card CVV and address verification to make sure the billing address matches the card issuer’s provided contact information.
  • Use a chargeback alert system to alert you to chargebacks. This will give you 3 days to issue a full refund before the chargeback is initiated.
  • Send follow-up emails or a confirmation phone call after sales to confirm a customer is happy.

#5. Choose the Right Processor
There are many choices for high-risk merchants today, but they are not equal. Just because your business is considered risky does not mean you can’t qualify for excellent customer service and quality payment processing service. Make sure you choose the right processor by selecting a company that handles PCI compliance without cancellation fees and costly term commitments. A high-quality processor will guarantee to not increase your markup rate later.

At Host Merchant Services, we understand how important card processing is to your business. No matter what type of business you operate, your volume, or your past processing history, we offer top-rated merchant account services to help your business grow.

What is interchange pricing Infographic SR18 3R1 1

What Is Interchange Plus Pricing?

What is Interchange Plus Pricing

What Is Interchange Plus Pricing?

Accepting credit cards increases customer convenience and helps increase your sales, but the cost of merchant services can be a bit confusing and eat into your profits. You don’t want to pay more than you need to for payment processing, but how do you choose a merchant account provider that charges the best rates? Knowing how much you will pay in advance for credit card processing isn’t easy, especially when the provider uses a complicated pricing system like tiered pricing.

As a merchant, the safest and most upfront pricing model is interchange plus pricing, also known as cost plus pricing. Unlike other pricing models, the interchange plus system breaks down the charges so you can see the markup you are charged to process a transaction. Here’s a look at how interchange plus pricing works and how it protects you from being overcharged.

Understanding Interchange Fees
When a credit card transaction is processed, there are several entities involved. The first is the acquiring bank or merchant services provider. The card issuing bank physically issues the card that the customer is using. The credit card association, which may be Mastercard, Visa, or Discover, is responsible for setting the credit card processing rates for these transactions.

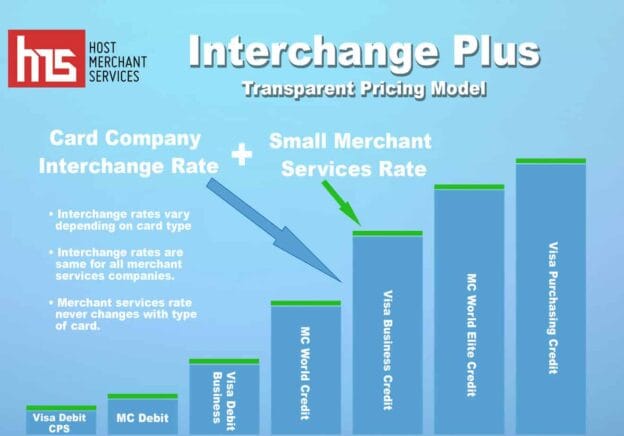
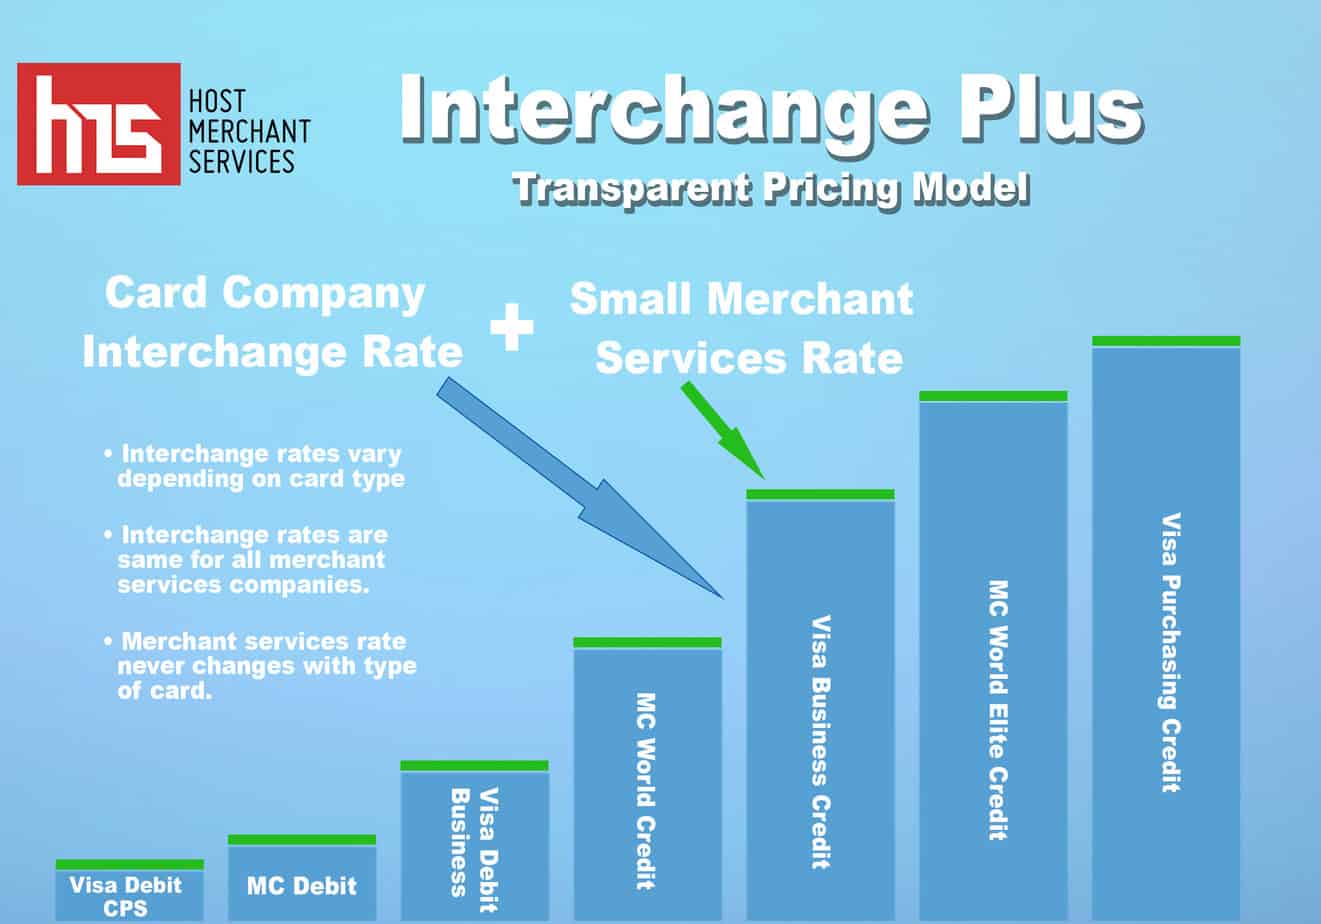
Every debit and credit card has a pre-set interchange rate that the merchant account provider pays to the issuing bank. This is the interchange rate. Debit cards have the lowest interchange rates while high-end rewards cards have the highest rates. Rates can also be lower if the credit card is dipped or swiped on a credit card machine compared to online or keyed sales.

There are hundreds of interchange fees that are comprised of a percentage fee of the volume of the sale and a flat fee per transaction.

How Interchange Plus Pricing Works
Interchange plus pricing is the most beneficial for merchants due to its simplicity and transparency. With this pricing model, merchants pay the actual interchange fee “plus” an additional markup. The “plus” is the amount that exceeds the interchange costs and it covers expenses for the merchant account provider. The markup may be a per-transaction fee or a percentage.Interchange plus pricing infographic

A common alternative to interchange plus pricing is a tiered pricing system, which turns the hundreds of interchange rates into just three tiers: qualified, mid-qualified, and non-qualified. The processor determines which transactions fall into which categories based on criteria like whether a credit card machine is used and whether the transaction was processed same-day.

With tiered pricing, you can never tell which percentage of the processing fee goes tot he credit card association and issuing bank and how much goes to the merchant account provider. This pricing model makes it very easy to hide interchange fees so the processing company can charge a higher markup.

Why Cost Plus Pricing Makes Sense
Tiered and flat-rate pricing models make it easy to overcharge merchants because you never know how much you are paying over interchange. Interchange plus pricing shows you the actual interchange costs for every transaction to see precisely what you are paying over interchange. The cost plus model encourages competition and reasonable markups to save you money on payment processing. While payment processors can still charge whatever they want as a markup, you can easily compare merchant accounts to find the service with the lowest effective rate.

Protection from skimmers banner 1

Protect Your Business from Credit Card Skimmers

Protection from Credit Card Skimmers

Protect Your Business from Credit Card Skimmers

Each year, companies sign on to take advantage of merchant services offered for credit card processing. Skimmers are quickly becoming a threat to unsuspecting customers as companies rely more heavily than ever on point of sale services for their businesses. As a merchant, you want to protect your customer from all potential forms of credit card scams.

Continue reading →

mobile-credit-card-processing

How Mobile Credit Card Processing Effects Small Business [2023 Update]

Gone are the days where businesses must rely solely on traditional terminal solutions to manage customer payments. Now business has more options than ever to complete customer transactions. Small businesses leverage advancements in payment processing to move about flexibly serving their customers. Credit card processing has changed the way the small business community handles transactions.

These services also cut down on costs in removing the need for paper invoices. Paper invoices cost businesses, contributing to a significant amount of overhead. The paper invoices also add to a company’s carbon footprint. If a paperless invoice is received and subsequently rejected by the recipient, the company adds time to the invoicing process when they issue a correction. Tracking the status of an invoice can be very cumbersome for the typical business, especially when they grow in volume. Conducting payments on site allows the SMB the advantage of eliminating the paper invoice altogether. Companies can go from hundreds of invoices to none.

Mobile Credit Card Processing Effects

mobile payment processing helps business

Employees are paid more quickly with credit card processing purchases. Shortening the payment cycle is something the SMB community has always been inclined to improve. Having to send an invoice online or offline, and then waiting for the recipient to make the payment within a specified amount of time lengthens the cycle to 20 or more days. Equipped with a mobile swiper, the customer can be invoiced and handle payment right on the spot. This means that employees are paid sooner.

Companies can manage invoices from practically anywhere. This means that the business has the freedom to expand their business to new locations and areas. Companies no longer have to do business exclusively in their immediate areas with flexible credit card processing options. Brick-and-mortar businesses are often required to conduct business in close proximity to their locations.

Greater accuracy is also an advantage in using newer merchant services to include mobile swiper technology. Errors could take months to identify. They can even go undetected if audits aren’t routinely conducted. Fewer people involved in managing the invoicing process reduces the likelihood of clerical errors. When a payment can be handled right then and there on the spot, an error could be addressed simultaneously.

Thanks to the advancement in merchant services, SMB representatives can conduct business anywhere with improved efficiency. Businesses can open and close work orders more easily. They can offer flexible payment options that are more convenient for their customers.

eBay to Discontinue PayPal as Main Processor

After 15 years, the eBay-PayPal partnership is coming to an end. The e-commerce giant has announced that it will replace the payment processing company it purchased in 2002 for $1.5 billion with Adyen (commonly misspelled as Ayden). The news caused eBay’s shares to rise to a record high while its long-time partner took a hit.

Adyen (or Ayden) is a smaller start-up formed in the Netherlands. This online credit card processing company offers backend payment services for businesses that include payment processing and credit card machines. With it offers point-of-sale credit card machines, online transactions are at the heart of the Dutch company, which already works with tech giants like Netflix and Uber. The company was last valued at $2.3 billion and there have been rumors that it will go public.

PayPal, on the other hand, is one of the world’s most well known and most established credit card processing companies, although it has faced growing competition in recent years. eBay’s ownership of the company ended in 2015. After the spinoff, the processing company was valued at $50 billion — a figure that is now more than $100 billion.

So why has the e-commerce giant made such a move to end this partnership? The company’s strategy is transitioning to full payment intermediation. It plans to integrate the Dutch company’s payment processing for lower costs and greater control for the company’s merchants.

With the new partnership, eBay merchants will have a central view of their information through the company’s merchant services. They will also be able to track and manage all customer interactions and transactions with greater ease. The company says the move will reduce costs for sellers.

Customers will not interact directly with Adyen’s system. With the new merchant services, customers can pay in 150 different currencies with more than 200 unique payment options. Buyers will no longer get directed to a third-party payment system to complete a purchase.

Most payments on the e-commerce giant will be processed by the new merchant services provider by 2021. Customers can still use the existing system until 2023. The shift will begin gradually in North America this year.

PayPal shares may be down on the move as the e-commerce giant is a big part of the payment processor’s business, but these transactions have not been growing as fast as other areas of the processor’s business. The e-commerce website accounts for about 13% of all payments handled by the processor in the fourth quarter, a decline from 16% last year.

Network Security banner 1

Importance of Network Security – The OnePlus Credit Card Hack

PCI compliance Network Security

As a merchant, network security should be a top concern when it comes to credit card processing. The most vulnerable place for credit card data is on the merchant side of the transaction before it’s sent to the payment processor. This is why PCI compliance is important to ensure the security of a merchant’s payment processing system. While some businesses view PCI compliance as an expensive and unnecessary step, the rise of data breaches and the fines and negative publicity that come with them should be noted.

The latest credit card processing breach to hit the news is the OnePlus breach. According to smartphone maker OnePlus, it discovered fraudulent charges were appearing on customers’ credit cards. After shutting down payment processing on its website and beginning an investigation, OnePlus revealed that the credit card information of up to 40,000 people was stolen since November 2017.

The breach occurred when an entity gained access to one of OnePlus’s servers and inserted a script to capture credit card information as it was typed into a payment form on the OnePlus website. The payment processor for OnePlus was originally blamed, but the investigation showed that the payment processing occurred as it should and the breach occurred on the merchant side of the transaction.

This breach underscores just how important PCI compliance is for merchant services with rules that apply to merchants, processors, card issuers, and any entity that handles payment information. PCI compliance comes in many forms depending on the types of credit card transactions your business processes. There are even guidelines that apply specifically to a credit card machine used for in-person transactions. For example, a credit card machine or any other piece of equipment cannot store sensitive information and equipment must be kept updated.

Remember: every PCI requirement is in place because a breach could be prevented with this control, even requirements that may seem unnecessary or overboard.

At Host Merchant Services, we always ensure our customers are PCI compliant. This is done for the safety of our merchants as well as their clients. Following this standard can protect card data from thieves, keep sensitive information secure, and avoid expensive data breaches.

Blog Call To Action 1 2 1

Screen Shot 2018 01 23 at 11.46.24 AM

What Mobile-First Shopping Will Mean for the Retail Industry in 2018

Online ordering mobile first marketing

When considering the trends that have been shaping the retail industry over the last few years, it is easy to infer that 2018 will be the year of mobile first shopping. Online retail giants such as Amazon have noticed that shoppers are not quite ready to completely abandon the brick-and-mortar model; however, they expect to be able to use a combination of mobile apps and online ordering along with more sophisticated physical experiences and interactions.

online ordering for retail

Two major Amazon developments in 2017 illustrate how the e-commerce leader plans to change the rules of mobile first shopping game: the acquisition of the Whole Foods supermarket chain and the testing of the Amazon Go neighborhood convenience stores. It is clear that the company is looking to expand its physical presence beyond the Fulfillment by Amazon (FBA) centers across the United States. This is what Amazon is thinking about: shoppers who use smartphone apps during their lunch break at work will prefer to pick up their purchases at Whole Foods or Amazon Go stores on their way home.

In Florida, supermarket chain Publix has perfected its online ordering and delivery options to include the option of shoppers arriving to pick up their groceries; this gives them an opportunity to make a purchase they may have forgotten to include in their smartphone order. Something else that Publix executives have realized is that online shoppers engage in window shopping at their stores; this means that they enjoy getting acquainted with the products during their visit so that they know what to order online in the future.

Needless to say, the shift towards the new mobile-first retail paradigm will require merchants to give shoppers plenty of payment options. In 2018, the diversity of mobile payments providers will continue, which means that store owners should look for merchant processors that can handle as many options as possible. Google recently announced that it would merge Android Pay with the Google Wallet, and Apple is rolling out a new option called Apple Pay Cash. Venmo and PayPal will continue to develop their systems with the hope of increasing their market share. Various cryptocurrencies are marketing their respective blockchains in an effort to gain acceptance. All in all, 2018 will be a competitive year in terms of electronic payments format, and the possibility of a mobile wallet standard being set this year is very unlikely.

In the end, 2018 will be an exciting year for the retail industry, particularly for brick-and-mortar store owners who properly leverage their physical and mobile presences for the benefit of shoppers.

Blog Call To Action 1 2 1

HMS Logo Red Structured Data 1

Visa Ends Signature Requirements for Chip Cards, Google Pay, Apple Pay, Samsung Pay

The End of Signature Requirements 1

Beginning in April, Visa will no longer require signatures for contactless payments and EMV chip cards. This means North American users of Samsung Pay, Google Pay (previously Android Pay and Google Wallet), and Apple Pay will be able to complete transactions with a touch of their device to the contactless credit card machine.

The signature requirement was once a common method to ensure a transaction was genuine. Depending on the credit card issuer, a signature was required for a transaction exceeding $25 or $50 to confirm the transaction was authentic. Despite the requirement, some vendors were already skipping signature validation.

Credit card issuers cite better security technology as a reason to abandon the method. EMV chip cards have been required in the United States since 2015, generating unique codes with every transaction for a lower risk of fraud. Contactless payments also use one-time codes for each transaction.
Blog Call To Action 1 2 1
EMV chip technology has become the standard in secure credit card processing. Fraud in the credit card processing industry has declined 66% in the U.S. since EMV chip cards were launched just two years ago. In 2016, while the launch of chip payment processing was underway, Visa reported that fraudulent transactions dropped 18% among merchants who began processing chip-enabled cards and rose 11% among merchants who had not yet adopted chip technology.

Visa isn’t the first credit card issuer to end its signature requirement. Mastercard started the trend in October, followed by Discover in December. American Express has also announced it will end the signature requirement on purchases globally effective next April.

All four issuers will drop signature requirements beginning in April in Canada and the U.S. American Express is eliminating signature requirements globally while Discover will eliminate the method in the Caribbean and Mexico. Visa has only waived the signature requirement for merchants who have upgraded to a chip-enabled credit card machine or contactless payment processing. The signature requirement will be optional as retailers can choose to require a signature.

Google Pay banner 1

Android Pay and Google Wallet Merge Creating Google Pay

android pay and google wallet merge to create google payAndroid Pay is no more. On January 8, Google announced that it will combine Google Wallet and Android Pay under a single brand called Google Pay. This move will merge all of the ways to send payments and make purchases with Google into a single product.
Prior to this merge, Google’s payment system was a bit confusing. Android Pay was used to complete transactions in checkout lines while Google Wallet was for sending money to friends or by using the Chrome autofill feature to complete online purchases. Combining the services offers a more consistent experience for consumers shopping online, in-store, and through mobile apps.

The new system makes it easier for consumers to use saved payment information for a faster checkout. Google Pay will appear online, in-store, and across other Google products in the coming weeks. Right now, it’s available on Fandango, Airbnb, and a handful of other websites and apps.

This news comes as Google pushes to make its payment system available everywhere. In fall 2017, Google announced it would speed up the online checkout process when Google is used as a mobile wallet.

For business owners, the change will be simple: the name “Google Pay” will appear when a customer uses their phone at the checkout, purchases something online, or sends money for services. While this is largely just a functional change, it’s overdue. The separation of the services was arbitrary and led to confusion for consumers. Apple’s system with Apple Pay and Apple Pay Cash has always been straightforward in comparison.

Blog Call To Action 1 2 1