Author Archives: hostmerchantservices

Key Tech Trends And Stories To Keep An Eye On In 2024

Key Tech Trends And Stories To Keep An Eye On In 2024

As we are in 2024, it’s clear that technology’s rapid evolution won’t be slowing down. The advances that made 2023 a standout year, like machine intelligence and blending the digital with the real world, will keep transforming our lives.

One key focus for the upcoming year will be balancing innovation with environmental responsibility. The goal isn’t just to advance technologically and minimize and even reverse environmental harm. From advancements like foldable phones to integrating AI into software and AR & VR, 2024 promises even more excitement. Here are some of the major tech trends to watch in 2024.

Summary: Key Tech Trends
  • Generative AI’s Rise: Generative AI, epitomized by tools like ChatGPT, is moving beyond the realm of specialized applications to become a staple in everyday tools. Its integration into search engines and office software signals its growing importance in enhancing efficiency and productivity.
  • Foldable Phones: The mobile tech arena is poised for a significant shift with the mainstream adoption of foldable phones. As prices become more accessible, these innovative devices are expected to dominate smartphone lineups, offering users both novelty and functionality.
  • AR & VR: While companies like Apple are betting big on mixed-reality headsets, the mass adoption of AR and VR technologies remains a challenge. Despite advancements, factors like high costs and limited content will likely delay their integration into daily life.
  • Self-Driving Cars: Self-driving cars’ trajectory is marked by optimism and hurdles. Although advancements in Level 3 driver assistance technology are promising, the widespread rollout of fully autonomous vehicles may face delays due to regulatory, technological, and public trust issues.

Generative AI Will Continue To Captivate Attention
Generative AI Will Continue To Captivate Attention

In 2023, generative AI became a household name. Now, in 2024, will see its true value. For many, the idea of artificial intelligence might be daunting, conjuring fears of job loss or other concerns. But its benefits are becoming clearer as generative AI becomes a regular part of tools we use, like search engines and office software.

Think of it as having a super-smart assistant available all the time. When used right, it boosts our efficiency and helps us work better and faster. Here are some AI-centric techs  you can expect in 2024:

AI-Powered PCs

This year, tech companies started discussing the concept of the AI PC. Essentially, these are laptops equipped with a special kind of processor called a neural processing unit, or NPU. This NPU works alongside the regular CPU and GPU to manage AI tasks.

While chipmakers had thought about adding NPUs for a while, the buzz around generative AI, especially after the debut of ChatGPT, pushed the idea forward. This buzz made companies see AI as something that doesn’t just rely on cloud computing.

The future success of these AI PCs depends greatly on having great apps that users will love. Big names like Intel, AMD, Qualcomm, and Nvidia are gearing up for what looks like a major showdown in 2024. They’ve all revealed their plans, but the real game-changer will be how well they put them into action.

AI Smartphones

Google recently introduced a new advanced language model named Gemini. This model understands language, has visual and auditory capabilities, and improves learning skills. What’s interesting is Google has designed a version to work right inside their Pixel 8 Pro phones. Instead of relying on cloud servers, this model runs on a specialized chip within the device. This move sets Google on a promising path for 2024.

On another front, Apple is gearing up to roll out similar AI features. They’re expected to unveil these in the spring and launch them for iPhones by the fall. Apple’s CEO, Tim Cook, highlighted how they already use AI in features like Live Voicemail and fall detection. He also hinted at Apple’s efforts to enhance Siri using their generative AI technology.

Foldable Phones – The Next Big Trend In Mobile Tech
Foldable Phones – The Next Big Trend in Mobile Tech

As we roll into 2024, foldable phones are gearing up to become the new normal. With prices expected to become more affordable soon, more people are likely to hop on the foldable phone bandwagon. In 2022, only a few brands dipped their toes into the foldable phone pool. Fast forward to 2023, and these unique devices started making up a bigger chunk of smartphone lineups. In 2024, nearly every brand is expected to offer a foldable option, and the early adopters are looking to grab a bigger slice of the market pie.

But the innovation doesn’t stop there. Rollable screens teased us in some concept phones, hinting at what’s to come. Motorola might steal the spotlight with its upcoming ‘bendable phone.’ It features a plastic OLED screen known as FHD+pOLED, which will come in a 6.9-inch display that can flex into a U shape and even double as a smartwatch.

AR And VR At The Front Of Tech
AR And VR At The Front Of Tech

In the middle of the year, Apple revealed its much-anticipated mixed-reality headset, the Vision Pro, set to launch in 2024. CEO Tim Cook talked about a shift into “spatial computing,” merging our real world with digital data. Priced at $3,499, the Vision Pro is packed with cutting-edge tech, benefiting from Apple’s years of research in various fields like sensors and displays.

However, it’s worth noting that virtual reality headsets, including those from Meta, have been around for a while. Even with Meta’s CEO, Mark Zuckerberg, betting on mixed reality, these gadgets haven’t taken off with the masses. Recent sales figures for such devices have been lukewarm at best.

So, while there’s excitement around Apple’s upcoming release and Meta’s new Quest 3, challenges like steep pricing, limited content, and complexity mean it might be a while before mixed reality becomes a part of our daily lives.

Self-Driving Cars Will Boost Again In 2024?
Self-Driving Cars Will Boost Again In 2024?

The world of self-driving cars often swings between extreme pessimism and optimism. Elon Musk of Tesla frequently predicts rapid advancements, which don’t always pan out. Meanwhile, Cruise, a self-driving taxi company, faced setbacks, including losing its license in California and public trust after mishandling an accident.

Some critics say the whole idea of driverless cars has been a flop. Even Cruise’s new leader, Mo Elshenawy, acknowledges they’re going through a tough phase with less funding. But stepping back, it’s clear the reality of self-driving cars is more nuanced as we head into 2024.

Looking at the passenger cars segment, a noteworthy advancement, pending regulatory approval, is the broader availability of Level 3 driver assistance technology packages. Mercedes has already introduced this on specific models in Germany, California, and Nevada. Level 3, per the Society of Automotive Engineers, enables highly automated “hands-off, eyes-off” driving, with other automakers like BMW and Polestar gearing up to offer it.

Major players such as BMW, Ford, Honda, Mercedes, Toyota, and Tesla are actively working on advanced driver assistance technologies, a precursor to fully self-driving vehicles.

However, there’s a growing acknowledgment that the timeline for the widespread rollout of fully autonomous vehicles might be more extended than initially anticipated. Predictions claiming imminent arrival are becoming less common.

A pivotal development in the autonomous truck sector could be a substantial increase in driverless, heavy-duty, long-haul vehicle testing. Kodiak, for instance, has outlined plans for driverless trials in 2024.

Conclusion

In 2024, technology continues relentlessly, blending innovation with environmental responsibility. Generative AI, like AI-powered PCs, takes center stage, promising efficiency gains. Foldable phones and advancements in AR and VR hint at a seamless digital-real world integration. While self-driving cars show promise, challenges remain, underscoring that true autonomy may be further down the road. As we navigate these trends, it’s evident that the tech landscape is vibrant and promising, yet still evolving.
Google Pay Pilots BNPL Service With Zip In The First Quarter Of 2024

Google Pay Pilots BNPL Service With Zip In The First Quarter Of 2024

The retail world is changing, thanks to Buy Now, Pay Later (BNPL) services like Affirm and Zip. These options let shoppers buy items and pay later, making shopping easier. Now, Google Pay pilots BNPL with Zip in the current quarter of 2024. Google Pay is teaming up with Affirm and Zip to add BNPL directly into Google Pay. More people are picking BNPL, especially during holiday shopping. This partnership aims to make paying more straightforward and enhance the shopping experience for customers.
In this latest move, now Google Pay users can pay in installments for online transactions in the US. The collaboration allows Android users to utilize Google Pay at checkout on select merchant apps and websites to opt for Zip or Affirm as their payment method. Affirm plans to launch its BNPL feature on Google Pay in the first quarter of the upcoming year, while Zip is set to conduct a test integration in January.

Key Takeaways
  • Google Pay Enters the BNPL Arena: Google Pay is integrating with BNPL services like Zip and Affirm, allowing users to pay for purchases in installments. This move signifies Google’s intent to provide more payment options and enhance the user experience, particularly on Android devices.
  • Merchant Revenue Boost: Collaborating with established BNPL services offers merchants a potential revenue increase. Affirm has reported a 60% surge in average order values with its services, indicating that such partnerships could be lucrative for businesses.
  • Strategic Expansion Plans: Google Pay’s initial trial phase aims to broaden its reach by including more merchants and additional BNPL services. The company is aligning its offerings with user preferences and market trends, ensuring a seamless integration into the broader retail landscape.
  • BNPL Market Growth: The Buy Now, Pay Later sector is witnessing exponential growth, with projections indicating a staggering increase by 2024. This surge, fueled by changing consumer behaviors and financial challenges, presents a significant opportunity for retailers and payment platforms alike.

Google Pay Pilots BNPL With Zip And Affirm As BNPL Move Gets Momentum

Starting in the first quarter of 2024, Google Pay users on Android will have the option to use Zip and Affirm’s “Buy Now, Pay Later” services when shopping at certain online stores. This new feature lets shoppers divide their payments into smaller, manageable chunks. For example, if someone picks Zip, they can review the terms and conditions and then follow a simple process to finish their purchase. After getting approval, they can use Zip’s pay-over-four-month plan for items priced at $35 or more.

Google Pay is testing out BNPL features for the first time in a small trial, with plans for a broader launch a few months down the line. Drew Olson, the Senior Director of Google Pay, mentioned that teaming up with these payment service providers offers users more ways to pay and gives businesses an extra way to boost their sales.

During the trial phase in January, when shoppers click the Google Pay online checkout button on certain merchants’ Android apps, a promotional banner will appear on Google’s home screen, informing them about the availability of the Zip BNPL option. If the user decides to change their payment method, they’ll see a list of BNPL providers with additional details about their offerings. Opting for Zip, users can review terms and conditions before completing the purchase through a few simple steps. Once approved, customers can conveniently spread out their payments for purchases.

Olson further explained that they’re collaborating with established BNPL services that already have a broad presence in the market. These services are familiar to merchants who are already using Google Pay. He emphasized that this collaboration allows them to expand payment choices for users without needing a direct link to BNPL providers.

Providing such options, Olson pointed out, can boost a merchant’s revenue. Affirm has observed that merchants using its services see a 60% increase in average order values compared to other payment methods. For BNPL providers, partnering with Google Pay means reaching more users who may explore BNPL options with different merchants down the line.

Affirm

Olson highlighted that this approach aligns well with the seamless Google Pay experience that users are already accustomed to. Olson mentioned that as they move past the initial testing phase in the first quarter of the upcoming year, Google plans to expand by including more merchants, additional BNPL services, and exploring new business sectors for the full launch.

Google’s move to work with two BNPL providers isn’t surprising, considering Amazon teamed up with Apple Pay Later and Affirm for last year’s Black Friday event. Google Pay might be testing the waters to see which option users prefer, but they’re probably aiming to attract a broader audience familiar with either Zip or Affirm.

It’s interesting to see Google keeping a close eye on its rivals. Apple introduced Apple Pay Later in October, and Amazon joined forces with Affirm. With Google Pay stepping into the BNPL scene, we can expect a surge in its popularity in 2024, especially as people manage their post-holiday budgets amid rising living costs.

The Growth Of BNPL Is Evident And Stronger Than Ever!

The 2019 pandemic worsened existing financial challenges, leading to more missed payments and reduced credit card usage in the US This decline created space for new payment methods like BNPL to step in. BNPL services offer an alternative to traditional credit cards. They let consumers buy items and pay for them in set installments, often without extra interest or hidden charges.

In 2019, the BNPL market in the US was valued at a few billion dollars. However, it’s predicted to skyrocket, growing by an impressive 1,200% by 2024. This rapid rise of BNPL presents a clear opportunity for retailers aiming to stay competitive—they just need to seize it.

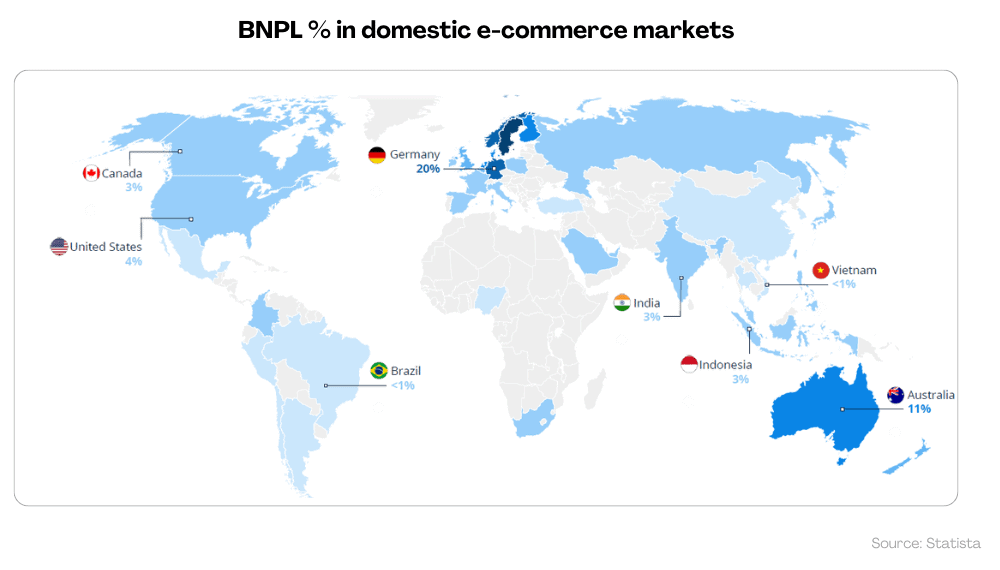
domestic market of bnpl

Plus, the recent adoption of big-name BNPL services further boosted its existence. Apple is introducing its own BNPL service with Apple Pay Later. Plus, during the Black Friday sale last year, Amazon partnered with Affirm and Apple Pay to offer BNPL to its customers on a large scale. According to recent data from June 2023, about 360 million people globally were using BNPL services. With this industry booming, experts predict it could be worth a staggering $3.27 trillion by the year 2030.

About Google Pay

Google Pay serves as a digital wallet that lets you handle various transactions right from your phone. You can send money to friends, pay bills for utilities like electricity and phone services, and even recharge your mobile. Available on both iOS and Android, this app-based platform has evolved over the years. Starting as Google Wallet in 2011, it underwent several name changes like Tez and Android Pay before settling as Google Pay in 2018. With Google Pay, you can shop online, manage bills, and make in-store purchases all in one place.

About Google Pay

Today, Google Pay stands out as a leading choice for mobile payments, making up 26% of online transactions last year. With over 150 million users in 42 countries, it’s a go-to option for people who want a simple and efficient way to handle their payments with just a tap or swipe.

About Zip

Zip is a tech company from Sydney, Australia, founded in 2013 by Niamh Mc Enaney, Peter Gray, and Larry Diamond. Specializing in digital retail finance, Zip helps consumers and small to medium businesses in countries like New Zealand, Australia, the US, and Canada. They offer “Buy Now, Pay Later” options both online and in stores, along with other financial services. Originally called ZipMoney Limited, the company switched to its current name, Zip Co Limited, in 2017. Zip offers clear and adaptable payment choices, empowering customers to manage their money wisely while aiding businesses in their growth. Committed to ethical lending, Zip operates as a regulated credit provider.

Google Pay Pilots BNPL With Zip And Affirm As BNPL Move Gets Momentum

The company offers a range of financial services. For consumers, they provide flexible credit lines through Zip Money and Zip Pay, as well as installment plans through platforms like Spotii, QuadPay, PayFlex, and Twisto. They also extend loans to small and medium businesses through Zip Business. While Zip’s success is closely linked to the BNPL sector, many of its services, such as QuadPay and Zip Pay, don’t charge interest on unpaid amounts. A significant portion of Zip’s revenue comes from customers, primarily through account fees and interest. On the other hand, their installment services earn money by charging merchants, compensating for the risk of non-payment, and encouraging more frequent transactions from consumers.

About Affirm

Affirm, a fintech services company, specializes in offering installment loans to consumers right at the POS. Driven by a mission to create transparent financial products, Affirm aims to empower consumers and enhance their lives. The company envisions transforming the banking industry, making it more accountable and accessible. Affirm provides an alternative to traditional credit cards, allowing shoppers to make purchases at the point of sale and opt for straightforward monthly payments.

In contrast to payment methods with hidden costs and compounding interest, Affirm ensures transparency by showing customers the exact monthly payments upfront, without surprises or additional fees. With partnerships spanning over 2,000 merchants, Affirm offers shoppers the convenience of using its services at checkout across various sectors, including renowned brands in retail, travel, home furnishings, electronics, personal fitness, beauty, and apparel.

Conclusion

The integration of BNPL services into Google Pay marks a significant shift in the payment landscape, responding to the growing consumer demand for flexible payment options. As Google Pay collaborates with BNPL giants like Affirm and Zip, it not only enhances the shopping experience for users but also provides businesses with an avenue to increase sales.

This strategic move by Google Pay reflects the broader trend in the retail sector, where BNPL services are gaining momentum, especially in a post-pandemic world characterized by changing financial behaviors. With the BNPL market poised for exponential growth, retailers and payment platforms must adapt and innovate to meet evolving consumer preferences, ensuring a seamless and inclusive shopping experience for all.

Adobe And Figma End The $20 Billion Merger Due To Regulatory Roadblocks

Adobe And Figma End The $20 Billion Merger Due To Regulatory Roadblocks

Adobe has decided to cancel its planned acquisition of design software company Figma for $20 billion. The reason cited is the difficulty in getting approval from both the EU and the United Kingdom. The UK’s CMA (Competition and Markets Authority) had previously indicated that a significant part of Figma would need to be sold off, making the acquisition less appealing.
Last month, the European Commission had also expressed concerns about the deal. Additionally, company representatives had discussions with US officials in an attempt to salvage the agreement. This proposed acquisition, announced in September 2022, faced challenges due to increasing regulatory scrutiny over large tech companies acquiring potential competitors.

Key Takeaways
  • Regulatory Scrutiny Halts Transformational Deal: Adobe’s $20 billion purchase of Figma was halted primarily due to regulatory challenges from the EU and the UK. Both countries raised concerns about potential anti-competitive effects, leading Adobe to abandon the deal.
  • Gap Between Corporate and Regulatory Views: The cancellation underscores a significant divergence between corporate ambitions and regulatory oversight. While Adobe and Figma saw the merger as a means to enhance collaboration, regulators perceived it as a threat to competition and innovation in the design software market.
  • Financial Implications and Market Reactions: Figma stands to benefit from a $1 billion termination fee, reinforcing its financial stability and potential for future growth, including a speculated IPO. Conversely, Adobe’s stock saw a modest rise post-announcement, indicating investor optimism despite the failed acquisition.
  • Antitrust Regulators Score a Win: The collapse of the Adobe-Figma deal adds to a string of victories for antitrust regulators, who have been vigilant in preserving competition and innovation. The decision aligns with a broader trend of increased scrutiny over large tech mergers, signaling a proactive approach to maintain market diversity.

Figma’s CEO Expresses Regret Over Collapse of $20 Billion Deal with Adobe

Adobe has decided to cancel its planned $20 billion purchase of Figma, a design collaboration platform. The reason given is the challenges in securing approval from regulatory bodies in both Europe and the UK. This decision halts what was expected to be a transformative acquisition in the software industry.

While Adobe and Figma viewed the deal as a step toward enhancing collaborative creativity, regulators in multiple countries viewed it differently. To Figma’s CEO, Dylan Field, this highlighted a significant gap between corporate and regulatory perspectives on competition.

The collapse of this deal adds to a series of wins for antitrust regulators. Regulators raised concerns about Adobe’s dominant position in the design software industry when they opposed the acquisition of Figma. Buying Figma, which has gained popularity surpassing Adobe’s XD, made regulators anxious about potential stifled innovation if Figma couldn’t grow on its own.

Designers echoed these concerns after the merger announcement in September 2022. Despite these concerns, Adobe defended its position during the investigations. Authorities suggested that Adobe should divest significant source code, assets, and engineering resources to ensure fair competition. Given this growing pressure, Adobe found it challenging to finalize the deal while securing all desired Figma assets or maintaining its app offerings amid antitrust concerns.

Figma's CEO Expresses Regret Over Collapse of $20 Billion Deal with Adobe

Image source: Figma

Reports suggest that Adobe had not offered “satisfactory solutions” to address these concerns, leading to the deal’s end. In a joint statement, the companies acknowledged that they couldn’t find a feasible way to secure the required regulatory approvals in the EU and the UK. Consequently, due to the deal’s cancellation, Adobe is obligated must give a reverse terminating fee to Figma, which is $1 billion.

In a recent statement, Shantanu Narayen, CEO of Adobe, mentioned that although Adobe and Figma have differing views on regulatory decisions, both companies have chosen to pursue their goals separately. Despite their initial vision to collaborate on shaping the future of productivity and creativity, each company remains confident in its ability to seize significant market opportunities. Both Adobe and Figma remain committed to their mission of revolutionizing the digital experience for everyone.

In a separate statement, Rao contended that Adobe and Figma weren’t direct competitors at the moment. He pointed out that Adobe XD, which could be seen as Adobe’s closest offering to Figma, had struggled to gain traction recently. Rao emphasized that Adobe believed there was little customer overlap between the two companies. Furthermore, he stated that neither competitors nor customers had raised any significant concerns about the proposed acquisition.

On the other hand, In an official announcement, Dylan Field, the CEO and co-founder of Figma, states that both Figma and Adobe have mutually decided to call off their planned acquisition. Despite investing countless hours with global regulators to explain the distinctions between their businesses and the markets they cater to, they couldn’t envision a route to gaining regulatory approval.

Dylan further stated that when they announced this agreement 15 months ago, they aimed to enhance what Adobe and Figma could offer their respective user communities. Although they’re moving forward independently now, both companies remain enthusiastic about exploring future collaboration opportunities for their users.

Understanding The Reason Behind Regulatory Scrutiny

Margrethe Vestager, the Executive Vice-President overseeing competition policy, noted that both Adobe and Figma are prominent players in the software industry. They currently vie for market share in interactive product design software, essential for creating mobile apps, websites, and various digital offerings. Vestager also pointed out the potential for Figma to become a direct competitor to Adobe in photo and graphic editing tools, which are widely used for image creation and modification.

Understanding The Reason Behind Regulatory Scrutiny

Image source: Adobe

Both companies stand out for their innovation and market success. Figma leads the way in interactive design software, while Adobe dominates the field of photo and graphic editing with its renowned Illustrator and Photoshop programs. If the acquisition had gone through, it would have effectively eliminated existing and potential future competition between them. Vestager’s team found that this would likely result in higher costs, diminished quality, or fewer choices for consumers. The focus isn’t just on present-day competition but also on preserving opportunities for innovation and rivalry in the future.

The collapse of the Adobe-Figma deal adds to a series of wins for antitrust regulators. Both the European Commission and the UK’s CMA were gearing up to challenge the acquisition formally. Meanwhile, the U.S. Justice Department has been considering its stance on the matter after discussions with both companies.

In a separate development, the European Union’s antitrust body has raised objections to Amazon’s proposed $1.7 billion acquisition of iRobot, known for its Roomba vacuums. On a different note, Microsoft successfully finalized its $68.7 billion purchase of game company Activision by making some adjustments to the deal, satisfying UK regulatory requirements.

Adobe’s Missed Merger with Figma: A Silver Lining for Most Stakeholders Involved?

While the failed Adobe-Figma deal might disappoint some private investors hoping for a successful exit, the situation has its silver linings for the key players involved. Figma isn’t walking away empty-handed; they’ll receive a hefty $1 billion termination fee. This financial boost is noteworthy, especially considering Figma’s recent growth and financial health.

Over the past year, the company has expanded its workforce significantly and is projected to increase its annual revenue by 40%, surpassing $600 million. Moreover, Figma has maintained a positive cash flow. This crucial factor could make it an attractive option for an initial public offering (IPO) in the coming years, which they are said to be considering around 2025.

Upon hearing the news, Adobe’s stock went up by 1.8%, indicating that investors view this outcome positively. Remember, when the acquisition was first announced in September 2022 at a high valuation, many were skeptical. This Figma deal was initially viewed as a strategic move for “the future of work.”

However, concerns about the hefty price and potential profit margins caused Adobe’s market value to drop by over $30 billion. Even those who supported the deal now see a silver lining in its failure. After all, Adobe’s XD, which was intended to compete with Figma, wasn’t a major focus for the company to begin with.

Lastly, let’s consider the regulators who opposed the Adobe-Figma deal. They’ve faced criticism in the past for not scrutinizing mergers enough, leading to the elimination of potential rivals in the market. This deal was seen in a similar light to Facebook’s acquisition of Instagram in 2012. The regulators’ concerns also influenced their actions against Microsoft’s purchase of Activision Blizzard and Meta’s buyout of the virtual reality firm Within.

For instance, Facebook once assured the European Commission it wouldn’t combine user data from its services, but later did so, resulting in a hefty fine. By halting the Adobe-Figma deal, regulators might have redeemed themselves somewhat. With Figma continuing to operate independently, there’s hope it could become the strong competitor to Adobe that the regulators wanted to preserve.

About Adobe

About Adobe

Adobe, based in San Jose, California, is a renowned American software firm specializing in multimedia and creative tools. Established in 1982 by John Warnock and Charles Geschke, the company’s name is inspired by Adobe Creek.

In its early days, Adobe focused on digital fonts before venturing into consumer software in the 1980s. Today, Adobe stands as a global frontrunner in digital marketing and media solutions. The company’s suite of tools empowers users to craft innovative digital content, distribute it across various platforms, and refine their strategies for optimal results. Simply put, Adobe assists businesses in creating, managing, and maximizing content across diverse channels and devices.

About Figma

Figma, headquartered in San Francisco, is a collaborative design platform tailored for teams working on product development. Built for seamless online use, Figma streamlines the design process, enabling teams to create, review, and finalize designs more efficiently. Whether the aim is to centralize design tools, enhance visibility, or facilitate teamwork across different time zones, Figma enhances creative workflows and ensures everyone stays aligned.

Trusted by industry leaders like Slack, Microsoft, and Airbnb, Figma has been reshaping the landscape of design by making it more inclusive and accessible to all since its inception in 2012.

Conclusion

The termination of the proposed $20 billion merger between Adobe and Figma due to regulatory hurdles signifies a complex interplay between corporate ambitions and regulatory oversight. While both companies had envisioned a partnership that could redefine the future of design software, the regulatory channel prioritized maintaining a fair and competitive market.

Figma emerges with a $1 billion termination fee, strengthening its financial position and paving the way for potential future efforts, including a speculated IPO. Adobe’s stock market response indicates investor optimism despite the missed opportunity, reflecting a belief in the company’s resilience and adaptability. As the design software industry continues to grow, the failed merger serves as an important reminder of the complex balance between innovation, competition, and regulatory scrutiny.

Frequently Asked Questions

  1. Q: What is a Figma used for?

    Figma is a versatile design tool primarily used for web-based online projects. While it shares similarities with other vector editing software like Adobe XD and Sketch, Figma stands out for its emphasis on collaboration, ease of use, and web-focused workflows. Here are some key areas where Figma proves beneficial:u003cbru003eMobile application and Website Design: Figma provides essential tools like color changes, text manipulation, hovering, image adjustments, animation, and scrolling for creating attractive and intuitive interfaces for both websites and mobile applications.u003cbru003ePrototyping: With Figma, transitioning your designs into interactive prototypes is straightforward, simplifying the process of user testing.u003cbru003eBranding and Logo Designing: Though Figma shines in UI/UX design, it’s also adept at handling branding tasks, including the creation of color schemes, typography, and logos guidelines.u003cbru003eBrainstorming: Figma’s collaborative features allow teams to collaborate in real-time, whether they’re wireframing a new project or brainstorming innovative ideas.

  2. Q: Is Figma actually free?

    Yes! You can use Figma for free.u003cbru003eFigma operates on a freemium model, allowing users to access its core features at no cost. However, this free version limits you to just three projects, encompassing both Figma and FigJam, within your account.u003cbru003eFor those seeking additional benefits such as unlimited projects, version history tracking, or the ability to conduct audio conversations, upgrading to one of Figma’s paid plans—Professional, Organization, or Enterprise—is necessary.

  3. Q: Is Figma similar to Canva?

    Canva and Figma stand out as leading design tools. Both offer robust design capabilities, with Canva being more beginner-friendly, whereas Figma is suitable for more complex tasks and better suited for professionals. In short, their unique features make each better suited for certain tasks.u003cbru003eCanva and Figma serve distinct purposes in the design field. For instance, Canva focuses on raster graphics, making it ideal for crafting visuals for social media. In contrast, Figma is tailored for vector graphics, specifically for designing user interfaces and workflows. While Canva offers a wider range of features for various applications, Figma excels as a specialized tool for UX/UI design tasks.

  4. Q: Why is Figma so popular?

    If you’re using Figma, you can bypass the need for other conventional design tools. Figma’s features, such as easy sharing with team members and seamless synchronization, eliminate the hassle of juggling multiple versions across different formats—all within one integrated platform.

  5. Q: What are the cons of using Figma?

    Here are a few limitations of Figma:u003cbru003eIt doesn’t handle PSD imports or 3D graphics creation.u003cbru003eIt may take time to load intricate or sizable designs.u003cbru003eSome features and keyboard shortcuts found in other design tools are missing.u003cbru003eInternet access is essential for its functionality.u003cbru003eThe free version offers limited project security and subpar export quality.

  6. Q: What do designers think of Figma?

    Figma earns high praise from leading designers for its user-friendly interface, teamwork capabilities, and wide range of tools. Its feature that lets several users collaborate on a design simultaneously, along with instant feedback options, has made it a popular choice among designers.

  7. Q: Is it easy to learn Figma?

    It typically takes about two weeks to grasp the fundamentals of Figma, a tool for creating and testing user interfaces. However, the learning duration might differ based on your prior knowledge and expertise. If you’re familiar with tools like Sketch or Affinity Designer, you could get the hang of Figma in roughly a week or even less.

  8. Q: Who owns Figma now?

    Figma Inc. is based in San Francisco, California, and was established in 2012 by Evan Wallace and Dylan Field, who currently serves as the CEO. The company remains privately owned and not listed on any stock exchange. Although Adobe intended to acquire Figma for $20 billion, recently, the deal fell through because of regulatory issues.

  9. Q: What is the best alternative to Figma?

    Here are some other options to consider instead of Figma:u003cbru003eSketch: Ideal for Mac users, it’s a vector design tool.u003cbru003eInVision: Great for collaboration and getting feedback during the prototyping phase.u003cbru003eAdobe XD: Available for both Windows and Mac, it’s used for design and prototyping.u003cbru003eLunacy: Specifically designed for Windows, it can also edit Sketch files.u003cbru003eAkira: A free design tool tailored for Linux users.

Walmart BNPL by Affirm

Walmart Introduces Affirm’s Buy Now, Pay Later Option at Self-Checkout

Walmart is stepping up its game by adding a new payment choice at self-checkout stations in over 4,500 stores across the US. Now, shoppers can use Walmart BNPL provided by Affirm, a service known for its clear and flexible payment plans that let you buy now and pay later.

Affirm’s payment options come with different interest rates, from 0% up to 30%, based on your credit and where you are shopping. You can pick from various repayment schedules, like paying in monthly installments over three, six, or twelve months. This setup is great for folks who want to manage their spending without worrying about hidden fees or penalties for late payments.
Shopping with Affirm at Walmart is incredibly easy. Once you’ve finished scanning your items at the self-checkout, simply choose Affirm as your payment option. Then, just head over to the app or website, provide some information, and make a decision on your payment plan. Once you’ve been approved, scan the barcode that’s generated. You’re all set! It’s a process that enhances your Walmart shopping experience.

Key Takeaways
  • Walmart Expands Payment Options: With Affirm now available at self-checkout stations in over 4,500 Walmart stores, shoppers have a flexible way to manage their purchases. This move underscores Walmart’s commitment to enhancing the customer experience and catering to diverse payment preferences.
  • Affirm’s Growing Influence: The collaboration with Walmart amplifies Affirm’s presence in the retail landscape. As the company partners with more major retailers like Amazon and Target, it solidifies its position as a leading ‘Buy Now, Pay Later’ service, appealing to a significant portion of American consumers.
  • Consumer Demand for BNPL: The rise of Buy Now, Pay Later services reflects a growing consumer preference for flexible payment options. Affirm’s recent study underscores this trend, revealing that a majority of Americans value the ability to use BNPL services, emphasizing its importance in today’s retail environment.
  • Evolution of BNPL Services: The Buy Now, Pay Later market is expanding rapidly, with projections indicating substantial growth in the coming years. As businesses and consumers alike recognize the benefits of BNPL, it’s clear that this payment model is reshaping the retail landscape, offering a convenient and accessible alternative to traditional payment methods.
Walmart And Affirm Team Up For Flexible Payment Options

Walmart BNPL – Team Up With Affirm For Flexible Payment Options

If you’re getting ready for holiday shopping, there’s some good news for you. Now, at over 4,500 self-checkout Walmart stores, you have the option to pay for your purchases in installments with the BNPL option. Thanks to Walmart’s expanded partnership with Affirm, you can spread out your payments in four to six parts. Pay monthly whether you’re shopping online using the app or visiting Walmart Vision and Auto Centers.

After this collaboration was announced, Affirm’s stock received a boost. This not only helps Affirm expand its customer base but also strengthens its relationship with Walmart. Do you remember back in 2019 when Walmart started offering affirmed pay-over-time options in 4,000 Supercenters across the United States? Well, this new development takes that partnership to heights. You can buy pretty much anything you’d find at Walmart, from clothes and gadgets to toys and more.

Pat Suh, the Senior Vice President of Revenue at Affirm, highlighted some interesting findings. A recent study by Affirm showed that a significant 54% of Americans want the option to use BNPL services when they’re checking out at stores. Even more striking, a whopping 76% of shoppers said they might delay or skip buying altogether if Affirm wasn’t available.

Affirm showed that a significant 54% of Americans want the option to use BNPL

With this in mind, Affirm’s extended partnership with Walmart is no surprise. By offering their straightforward ‘Pay Later’ options at Walmart’s self-checkout stations across the United States, Affirm aims to empower even more shoppers. This move is smart and introduced at the right time, especially with the holiday season around the corner, helping people manage their budgets better while still enjoying their shopping.

If you opt to use Affirm at a self-checkout kiosk, simply open the Affirm app or go to Affirm’s Buy In-Store, Pay Later page on your smartphone. Enter the total amount for your desired items, which should be within the range of $144 to $4,000.

Next, select a pay-over-time plan that suits you, ranging from three to 24 months. Proceed to complete your checkout at the kiosk. Upon approval, you’ll receive a unique barcode. Simply scan this barcode at the self-checkout kiosk to finalize your purchase.

Affirm Focusing On Expanding Partnerships With Leading Retailers In Major Spree

In recent years, Affirm has broadened its reach by offering its buy now, pay later services through collaborations with major retailers. In August 2021, Amazon partnered with Affirm to provide installment payment services for select purchases exceeding $50. Shortly thereafter, Target joined the fray, incorporating both Affirm and Sezzle installment payment options for its customers, enabling Affirm usage for purchases totaling $100 or more.

As Affirm continues to build its network of retail partners, the company is not only focusing on its predominant online presence but is also making strides in attracting customers in physical stores. In October last year, Affirm’s CFO, Michael Linford, highlighted the introduction of the Affirm card. This move aligns with Affirm’s strategy to expand its influence in brick-and-mortar sales.

The Rise and Growth of Buy Now, Pay Later Services

Affirm Focusing On Expanding Partnerships With Leading Retailers In Major Spree

The BNPL trend has come a long way since gaining popularity in 2020. Now, these services are not only gaining traction but also becoming profitable. Experts predict that by 2026, BNPL could make up about a quarter of all online shopping transactions worldwide. That’s a big deal! And by 2023, it is expected to be valued at more than $70 billion in the North American market alone.

So, what’s driving this boom? BNPL services let you split big purchases into smaller, more manageable payments. Plus, some plans offer zero interest, making it even more appealing for consumers. It’s no wonder people are loving the flexibility these services offer.

But it’s not just consumers jumping on the BNPL bandwagon. Businesses are also seeing the benefits, of using these services for everything from day-to-day expenses to major investments. And it’s not just about retail anymore; BNPL options are expanding into areas like healthcare and even grocery shopping. With both traditional banks and new fintech companies entering the scene, the BNPL market is heating up. It’s clear that this payment option is not just a passing trend—it’s here to stay.

About Walmart

Walmart, Inc. is a major player in both wholesale and retail sectors, known for providing a wide range of products and services at consistently low prices. The company operates through three main business units: Walmart International, Walmart US, and Sam’s Club.

Under the Walmart US umbrella, you’ll find familiar brands like Walmart, Walmart, and Walmart Neighborhood Market, along with their online platform walmart.com. The Walmart International division oversees various retail formats such as supermarkets, supercenters, and warehouse clubs, but primarily outside the US. Meanwhile, Sam’s Club focuses on membership-based warehouse stores. Founded in 1945 by Samuel M. Walton and James L. Walton, the company has its headquarters in Bentonville, AR.

About Affirm

Founded in 2012, Affirm Holdings, Inc. is a US-based financial tech company making waves in the “buy now, pay later” (BNPL) section. With a robust presence, Affirm serves millions of consumers and partners with over 200,000 merchants. The company provides flexible payment options for both online and in-person shopping. Whether it’s through an online payment link, a virtual card, or a physical card, Affirm offers multiple avenues for customers to manage their purchases. On the business side, Affirm earns revenue by charging interest to shoppers and service fees to merchants.

When it comes to assessing loans, Affirm takes a comprehensive approach. They consider traditional credit scores, delve into other relevant financial data, and even harness the power of machine learning to make informed decisions.

Conclusion

Walmart’s introduction of Affirm’s BNPL option at self-checkout stations marks a significant step in enhancing the shopping experience for consumers. This partnership not only amplifies Affirm’s presence but also underscores the growing demand for flexible payment solutions.

As the BNPL trend continues to gain momentum, both consumers and businesses stand to benefit from its convenience and adaptability. With Affirm’s extended reach across major retailers and the broader retail landscape embracing this payment model, it’s evident that Buy Now, Pay Later is evolving from a trend to a mainstream financial tool, reshaping the future of commerce.

Online Retailer Zulily Shutting Down Its Operations

Online Retailer Zulily Shutting Down Its Operations, To Liquidate Assets

Online retailer Zulily shutting down its operations to liquidate assets was a surprise to many. Zulily’s shutting down led to the layoffs of numerous employees after attempts to turn the business around fell short.

Founded in 2010 by Mark Vadon and Darrell Cavens in Seattle, the platform has attracted millions of daily visitors looking for unique finds for clothing, home decor, toys, and gifts, all at discounted prices, it announced on its website that it’s working to fulfill all current orders and aims to complete this within the next two weeks. For orders that can’t be fulfilled, Zulily is focused on providing refunds. They’ve also provided a contact for customers who haven’t received their orders or refunds yet.

Key Takeaways
  • Closure and Job Losses: Zulily, a once-prominent online retailer, is shutting down its operations. This decision has led to the loss of over 800 jobs across three states: 292 in Seattle, 273 in Nevada, and 274 at its fulfillment center in Lockbourne.
  • Asset Liquidation: The company is in the process of selling off its remaining stock to settle its debts. Douglas Wilson Cos., a San Diego-based firm, will oversee the liquidation process to maximize returns for Zulily’s creditors.
  • Legal Action Against Amazon: Zulily has filed a lawsuit against Amazon, accusing the tech giant of unfair business practices. Specifically, Zulily alleges that Amazon pressured suppliers to offer less favorable terms to Zulily, thereby undermining its ability to compete effectively.
  • Community Impact: Zulily, which was once a significant presence in Seattle’s tech community, has faced challenges in recent years. The closure impacts employees and creditors and raises questions about the future of smaller e-commerce platforms in a market dominated by giants like Amazon.
Zulily Shutting Down

Image source: Zulily

Zulily Shutting Down, Causing Over 800 Job Cuts

Zulily, the online retail platform, has announced its closure, surprising both its customers and employees. Based in Seattle, the company stated on its website that it’s working to fulfill existing orders and aims to address any outstanding issues, including refunds, on January 22. They’ve also provided a contact for customers with concerns about their orders or refunds.

Once a standout in e-commerce, Zulily is now in the process of selling off its stock to settle debts as it prepares to close its doors. The company began winding down its operations recently after a 13-year stint that once captivated the tech world. However, it struggled to keep up with giants like Amazon and other online shopping platforms. Just before announcing its final sale, Zulily let go of over 800 staff members, with 292 positions in Seattle, 273 in Nevada, and another 274 jobs at its fulfillment center in Lockbourne.

In a statement on its website, Zulily confirmed it’s moving forward with a structured closure. The company has initiated an Assignment for the Benefit of Creditors (ABC), handing over the liquidation process to a third-party trustee. Douglas Wilson Cos., a firm from San Diego, will oversee the winding down and sale of Zulily’s assets, aiming to get the best outcomes for the company’s creditors. It’s worth noting that Douglas Wilson Companies is overseeing the process for Zulily.

Ryan C. Baker, Douglas Wilson Companies’ vice president, emphasized that choosing to wind down Zulily wasn’t taken lightly. Due to the tough business competition, Zulily faced and its financial challenges, immediate action was deemed necessary.

In another statement, Ryan highlighted their aim to handle the Zulily situation efficiently while ensuring the best outcomes for the company’s creditors. Baker mentioned that they’ve assembled a skilled team to manage claims and promptly respond to any queries or worries from both Zulily’s customers and creditors. Understanding the challenges these situations bring, they’re dedicated to being responsive and dependable in their role as the Assignee.

Once a notable presence in Seattle’s tech community, Zulily even sponsored the Seattle Sounders in 2019. Lately, the company gained attention for its vigorous advertising on social media.

Zulily’s move toward liquidation resulted in numerous job cuts across various states this past year. In a significant development last May, Regent, a private equity firm, acquired Zulily from its previous owner, Qurate Retail Group, known for QVC and HSN. This acquisition led to Zulily being separated from QVC, Inc.’s financial arrangements, with an outstanding debt of around $80 million settled by Qurate Retail at the time of sale.

Qurate Retail Group

Image source: Qurate Retail Group

Is Amazon The Reason Behind Zulily’s Shutdown?

Zulily’s closure follows the recent shutdown of Jane.com. Both struggled to compete with well-funded rivals like Amazon, Shein, and Temu. Just this month, Zulily filed a lawsuit against Amazon, alleging unfair business practices.

Ryan pointed out that the situation unfolded because Zulily had few options left.

Zulily has filed a lawsuit against Amazon, claiming the e-commerce giant used unfair tactics to undermine its business. Specifically, Zulily alleges that Amazon pushed sellers away from Zulily and restricted Zulily’s ability to offer competitive prices. These claims align with the FTC’s broader antitrust lawsuit against Amazon earlier.

The lawsuit alleges that Zulily’s suppliers felt pressured by Amazon’s pricing demands. Suppliers had to raise Zulily’s prices to match Amazon’s rates or stop doing business with Zulily altogether. Within just a year, about half of the suppliers selling on Amazon and Zulily chose to end their association with Zulily due to this pressure.

Zulily argues that its business model is straightforward – it buys products wholesale and sells them to consumers without extra charges. In contrast, Amazon operates a marketplace where retailers sell directly to consumers and pay additional fees for using the platform.

Amazon has refuted these claims from both Zulily and the FTC.

Wilson, from the legal firm handling the case, mentioned they’re reviewing the lawsuit and are committed to keeping it active. He emphasized that dropping the lawsuit isn’t on the table right now.

When Did Things Start To Tumble For Zulily?

Founded in 2010 by Mark Vadon and Darrell Cavens, who previously worked at the online jewelry store Blue Nile, Zulily saw rapid growth. By 2013, the company had attracted 12.6 million active customers and generated $331 million in revenue, a staggering increase of nearly 700% since its inception.

The company went public in 2013 with an initial valuation of $2.6 billion. By 2014, Zulily’s market worth climbed to $7 billion, backed by annual sales of $1 billion. Zulily expanded its workforce at the Nevada location, reaching around 1,000 employees, with plans to add another 600. That same year, the company revealed intentions to launch a new distribution center in Bethlehem, Pennsylvania.

Zulily’s growth momentum began to slow, and In a significant move in 2015, Liberty Interactive-QVC, later known as Qurate, acquired Zulily for an estimated $2.4 billion. Over time, challenges persisted, leading to the closure of its Pennsylvania facility and the unfortunate layoffs of approximately 500 employees in 2022.

Fast forward to 2023, the ownership of Zulily shifted to Regent, a private equity firm.

So, How Can You Reach The Team For Any Refunds Or Your Orders?

Zulily has established a dedicated team to assist customers, vendors, and other concerned parties. You can reach the Zulily ABC hotline at 8882025829, or for international callers, dial (+1) 7472886406. For more details and support, visit https://omniagentsolutions.com/ZulilyABC.

image 34

Image source: Omni

Customers can email [email protected], while vendors and other interested parties can reach out to [email protected].

Conclusion

Zulily’s decision to cease operations and liquidate assets underscores mid-sized e-commerce platforms’ challenges in a fiercely competitive market dominated by giants like Amazon. Founded with promise and rapid growth, Zulily’s journey reflects the volatile nature of the online retail landscape.

The closure, affecting over 800 employees and countless customers, also highlights the ripple effects of such business decisions on communities and stakeholders. As the company navigates its liquidation process and legal battles, it is a cautionary tale about the complexities and uncertainties inherent in the e-commerce sector. For those impacted, Zulily has provided dedicated channels for support and inquiries, aiming to mitigate the fallout from its closure.

Salesforce Acquires Spiff

Salesforce Acquires Spiff With Focus To Expand Its SPM Offering

Salesforce, known for its cloud software, is set to buy Spiff, a company specializing in sales commission tools. This move strengthens Salesforce’s sales offerings, giving users a more robust platform. Established in 2017, Spiff has been a game-changer in automating sales commissions. Spiff offers a user-friendly interface that simplifies the process for businesses to set up automated sales compensation plans. Salesforce acquires Spiff with a focus on expanding its SPM offering in the market.

These plans adjust automatically when team members meet their agreed-upon goals. With built-in compatibility for popular enterprise ERP and CRM systems, Spiff can manage complex commission setups. This includes various conditions that might activate payments. Sales reps also benefit from real-time visibility into their potential earnings.

They’ve helped businesses set up fair and clear commission plans that boost sales team morale and performance. Now, joining forces with Salesforce, Spiff aims to grow even more, bringing added value to Salesforce’s customers. However, The financial terms of the agreement were not publicly disclosed.

Key Takeaways
  • Strategic Enhancement of Sales Performance Management (SPM): Salesforce’s acquisition of Spiff is a deliberate move to strengthen its Sales Performance Management offerings. By integrating Spiff’s specialized tools for automating sales commissions, Salesforce aims to provide users with a more comprehensive and efficient platform for managing sales strategies and enhancing business growth.
  • Simplified Compensation Planning: Spiff’s user-friendly interface and capabilities in automated commission calculations offer businesses a simplified approach to setting up and managing complex sales compensation plans. This acquisition promises to bring this ease of use to Salesforce’s Sales Cloud users, enabling them to design fair and transparent commission structures with minimal hassle.
  • Collaboration and Insights for Revenue Growth: The acquisition aligns with Salesforce’s goal to foster better collaboration between sales, finance, and other departments. With Spiff’s integration, Chief Revenue Officers and teams can expect improved insights into revenue drivers and more effective management of incentive plans, ultimately driving sales performance and growth.
  • Continuation of Innovation and Flexibility: Spiff’s ongoing commitment to innovation, highlighted by its recent funding rounds and introduction of new features like Spiff Designer, indicates a forward-thinking approach. As part of Salesforce, Spiff’s adaptable and low-code solutions are expected to further enhance Salesforce’s offerings, allowing businesses to tailor the platform to their unique needs more effectively.
image 27

Image source: Spiff

Salesforce Acquires Spiff In An Undisclosed Deal To Boost ICM And SPM Solutions

Salesforce, a leading enterprise software company, has revealed its intention to purchase Spiff, a company specializing in innovative ICM software. The financial details of the deal have not been made public.

After the acquisition is finalized, Spiff’s team will become part of Sales Cloud. Their expertise will strengthen Salesforce’s SPM (Sales Performance Management) offerings. This move aims to give Salesforce customers a reliable platform for better visibility, enhanced sales strategies, and accelerated business growth. By integrating Spiff into Salesforce, will also enable Chief Revenue Officers (CROs) to collaborate more effectively with finance and sales teams. This collaboration allows for easier management of intricate incentive plans and provides insights into the key drivers of revenue growth.

Ketan Karkanis, GM at Salesforce, commented that the Spiff bridges the gap between what salespeople desire—clear compensation—and what sales managers seek—integrating compensation planning within CRM to align actions with business goals.

With Spiff, sales reps can see their commission details in real-time, helping them grasp their earnings better. The platform also handles intricate user roles, team setups, approval processes, and document management. Key features include its ability to grow with a business, easy integration options, and detailed analytics, making it straightforward for companies to set up compensation plans.

Sales Cloud

Image source: Sales Cloud

Both Salesforce and Spiff have a longstanding relationship, with over 70% of Spiff’s customers already using Salesforce’s Sales Cloud. When the acquisition is finalized in the starting months of 2025, Spiff’s team will officially become part of Salesforce.

Jeron Paul, CEO of Spiff, expressed enthusiasm about the company’s future and its role in ICM and SPM. He highlighted Spiff’s ongoing commitment to innovation and looks forward to contributing even more within the Salesforce environment.

Spiff is a flexible platform that lets businesses design their ideal pay structures with minimal coding. By adding Spiff to its portfolio, Salesforce enhances Sales Cloud with this adaptable feature. This flexibility makes it easier for users to tailor the platform to their specific needs, unlike older systems that can be rigid and complex.

While Salesforce offers robust tools, setting them up to fit unique business needs can be time-consuming. Customizing workflows or adding specific features often requires extra effort. However, Salesforce is committed to simplifying these tasks. Acquiring Spiff and refining tools like Salesforce Flow Builder are steps in that direction, aiming to make CRM setup more straightforward for users.

image 30

Image source: Salesforce

Based in Salt Lake City, Spiff has raised over $110 million since its inception six years ago. Salesforce’s venture capital arm, Salesforce Venture, has also been an investor. Beyond just investment, Spiff has been accessible on the Salesforce AppExchange for quite some time, indicating a deeper collaboration between the two firms.

Earlier this year…

Spiff announced a successful $50 million Round C Series funding. This round was led by Salesforce Ventures, with contributions from Norwest, Lightspeed, Album, and Kickstart Fund, among others. The funding was raised to help Spiff enhance its sales commission tools and address other intricate finance and sales tasks that traditionally relied on spreadsheets.

Additionally, Spiff also revealed its latest feature, Spiff Designer at the same time. This tool aims to simplify commission automation for finance and revenue teams. By combining the user-friendly nature of spreadsheets with advanced automation capabilities, Spiff Designer allows professionals in finance and sales operations to more efficiently manage and create their commission programs.

Salesforce Strengthens Low-Code Focus with Strategic M&A Acquisitions

Salesforce’s acquisition of Spiff fits into its broader strategy of bringing compatible companies into its fold, especially those focused on low-code solutions. This strategy is clear when you look at Salesforce’s recent acquisitions and where it’s investing.

For instance, in September, Salesforce bought Airkit, a platform that uses low-code to create AI-driven customer service tools. Airkit, based in Redwood City, California, was started by Adam Evans and Stephen Ehikian, who previously sold another startup, RelateIQ, to Salesforce for $390 million. Since its launch in 2017, Airkit received funding from various sources, including Salesforce Ventures. By 2020, they had secured $28 million in initial funding and a total of $68 million over six years. Just like Spiff, Airkit was also part of Salesforce’s AppExchange platform.

About Salesforce

Salesforce offers a cloud-based platform designed to craft meaningful customer experiences. Originating as a Software-as-a-Service (SaaS), Salesforce operates on a multi-tenant architecture, offering advantages like seamless API integration, scalability, and cost-effectiveness. It stands out as a top provider of Customer Relationship Management (CRM) solutions and extends its offerings with an Artificial Intelligence (AI) platform for areas like marketing automation, finance, and human resource management.

Whether for a small business or large corporations, Salesforce streamlines operations by providing employees with a unified customer view across various departments. These capabilities enable businesses to leverage cutting-edge technologies, identify potential customers, and enhance overall customer experiences. Currently listed on the NYSE and a part of the S&P 500 index, Salesforce boasts a market capitalization of $258.69 billion, showcasing its rapid growth in the competitive Cloud Computing landscape.

About Spiff

Spiff stands out as a sales compensation platform, streamlining commission calculations and boosting team motivation for enhanced top-line growth. With its user-friendly interface, real-time insights, and seamless integrations, Spiff empowers finance and sales operations teams to manage intricate incentive compensation plans independently. It brings transparency to sales teams, automating and optimizing commission plans to drive motivation among commissioned representatives. Spiff not only alleviates the challenges of commission management for the finance team but also fosters smoother collaboration between finance and sales, ultimately boosting overall sales performance.

Choose Spiff as your sales compensation software to unlock your team’s full potential. Tailored to help you achieve your goals, whether it’s boosting productivity or refining sales processes, Spiff is the solution you need.

Spiff integration

Image source: Spiff

Conclusion

Salesforce’s acquisition of Spiff marks a significant stride in its strategy to bolster its Sales Performance Management offerings. This strategic move enhances Salesforce’s capabilities by incorporating Spiff’s expertise in automated sales commission tools. With Spiff’s intuitive interface and robust functionalities, Salesforce customers can anticipate more streamlined processes and better visibility into their sales compensation strategies.

As Spiff’s team becomes an integral part of Salesforce’s Sales Cloud, the synergy between the two companies promises to deliver enhanced value, particularly for Chief Revenue Officers aiming for cohesive collaboration across departments. This acquisition not only signifies Salesforce’s commitment to innovation but also underscores its dedication to providing comprehensive solutions that drive business growth and optimize sales performance.

CFOs Are Cautious About Real-Time Payments

CFOs Adopt Cautious Strategy for Leveraging Instant Payments

A significant majority of CFOs want to adopt real-time transaction solutions, also known as instant payments, within the next two years. This indicates a substantial increase compared to the adoption rate, which is less than half.

As of September 1st, The Clearing House (TCH), the operator of the RTP Network that has been operational since 2017, reported that around 150,000 businesses are actively utilizing its network. Additionally, in July, the Federal Reserve introduced its instant payment rail called FedNow.

Despite these advancements, it is worth noting that real-time payments are still in their early stages. These solutions enable transfers of funds between consumers and businesses by allowing them to instantly send and receive funds from their bank or credit union accounts at any time of day or year. This ensures that recipients have access to these funds instantly. But CFOs are cautious about real-time payments, let’s see why.

Key Takeaways:
  • Growing Adoption of Real-Time Transaction Solutions: CFOs are cautious about adopting real-time payments for now but are planning to adopt real-time transaction solutions within the next two years, pointing to an increasing trend in the use of instant payments.
  • Real-Time Payments Enhance Transparency and Cost Efficiency: Real-time payments offer a transparent view of payment information, providing details like the recipient’s name and a thorough breakdown of the invoice. When compared to wire transfers, instant payments are more economical, often resulting in reduced transaction expenses.
  • Anticipated Functionality Enhancements: The inclusion of Request for Payment (RfP) in the RTP networks services and its future integration into FеdNows offerings showcase the expected enhancements in functionality. These improvements aim to provide access to transaction details and improved measures against fraud activities.
  • Improved Cash Flow Management: Real-time payment solutions give businesses control over their payments. This allows for timing and instant confirmation of payments, which helps with managing cash flow and could potentially lead to early payment discounts.

CFOs Are Cautious About Real-Time Payments in a Changing Financial Landscape

In the past, there was a lot of uncertainty when it came to online payments. It was difficult to know for sure if the money reached its intended destination. Now, both parties involved can easily track the payment journey. This is an improvement compared to the ways of delayed settlements and complicated notification processes with traditional ACH and wire payments.

CFOs Are Cautious About Real-Time Payments in a Changing Financial Landscape

The rise of embedded finance has made things much simpler for buyers. They can now order the inventory they need and settle invoices all on one single platform. Payment orchestration platforms offer Account Payable (AP) services that take away the burden from clients and companies dealing with outbound payments.

Real-time transaction solutions offer CFOs the ability to swiftly settle payments with their suppliers, providing the potential for enhanced efficiency. Despite this capability, many CFOs are exercising caution in adopting these systems within their back offices, assessing whether the benefits ultimately surpass the associated costs.

In July, the Federal Reserve introduced FedNow, an instant payment designed to enable businesses and consumers to transfer money immediately. This initiative seeks to broaden access to rapid payments for a larger network of financial institutions and their clientele. Similarly, TCH, a payment network owned by major financial institutions, initiated a comparable payment system back in 2017. Both services enable instantaneous clearing and settling, operating seamlessly 24/7. In contrast, other payment methods may take longer or may not be available 24/7.

One of the key attractions for CFOs regarding real-time payments is the ability to meticulously manage working capital. By leveraging these systems, companies can delay bill payments until the last possible moment, effectively retaining their cash for an extended period. Additionally, real-time payments can furnish finance chiefs with the assurance of precise settlement and clearance timings for their transactions.

But why is there still hesitation among CFOs about using this as a go-to service? Why CFOs Adopt Cautious Strategy for Leveraging Instant Payments?

The reason why CFOs adopt a cautious strategy about real-time payments is that while some may require this type of service based on the industry, not all B2B sectors may require the swiftness promised by FedNow and other similar services (like RTP by TCH), the potential for enterprises to leverage faster payments as a cash management tool is apparent. Some CFOs opt to hold onto their funds until the eleventh hour, still managing to make timely payments. However, altering long-established payment processes can be challenging, and a compelling business case is necessary to justify the transition effort.

Treasurers typically rely on the ACH system (which is also cheaper compared to instant payments) for batched electronic payments, like employee payroll, and traditional wire transfers for significant or crucial transactions.

Yet, neither system operates round the clock.

Digital payment ecosystems offer enhanced security compared to paper-based checks, eliminating the risk of mail losses. This secure environment incentivizes companies to modernize their payment practices. Suppliers increasingly prefer non-check payment methods, compelling buyers to adapt to these evolving preferences like instant payment (even if they have to pay a little extra).

FedNow and RTP Adoption Trends

A recent survey indicated that currently, 3% of treasurers are utilizing the FedNow payment system, with an additional 39% planning to join in the future. The remaining respondents were either uncertain or had no intentions of utilizing FedNow. The survey, encompassing 310 treasury executives, had almost 80% representation from publicly traded and private U.S. companies, with the rest comprising nonprofits and government agencies.

On the other hand, 12% of treasurers reported using TCH’s RTP network, with an additional 20% expressing their intent to adopt it.

Presently, the FedNow service is connected to over 120 banks and credit unions, while the RTP service by TCH is available at 400 financial institutions. It’s worth noting that there are approximately 9,000 banks and credit unions across the United States.

Reasons CFOs Should Consider Instant Payments

Transparent Information and Data

Information and Data within the ACH file typically include the payment amount, recipient details, and some basic particulars. However, the information obtained post-payment is often more restricted, as it relies on the recipient’s initiative to provide feedback through the network, which many suppliers do not consistently do.

Reasons CFOs Should Consider Instant Payments

Consequently, reconciling the payment becomes challenging since the payer may lack comprehensive information on the recipient, the exact payment amount, and the timing of fund reception. In contrast, a real-time payment incorporates crucial elements such as the supplier’s name and detailed invoice information, including an itemized breakdown of expenses. Real-time payments enable the transmission of payments along with this comprehensive data, facilitating seamless confirmation without requiring any additional action from the recipient.

Cost Efficiency

When compared to wire transfers, instant payments offer a significantly lower cost while maintaining, if not improving, the same rapidity. Traditional wire transfer charges generally range from $15 to $30, contingent on the financial institution. Instant or real-time payments, depending on the specific bank, can incur costs ranging from 25 cents to $1.

Similar to the use of commercial or procurement cards, incorporating real-time payments for a portion of back-office expenses can prove beneficial. These payments are not only more cost-effective than wire transfers but also offer a heightened value proposition compared to ACH transactions. 

Anticipating Enhanced Functionality

TCH recently announced the expanded availability of RfP through the RTP network. This enhancement enables businesses to request payments directly. For instance, payroll providers can leverage RfP to prompt corporate customers to fund payroll on the same day as payday, instead of the customary three to four days prior, leading to improved fund management for employers.

Furthermore, FedNow is set to include RfP in its services, along with additional risk management and operational enhancements focused on bolstering fraud prevention capabilities and ensuring streamlined access to account and transaction information. To leverage the benefits of real-time payments, businesses should proactively engage with their financial institution to determine their participation status in the program.

Currently, around 400 financial institutions are active on the RTP network, with community banks and credit unions constituting 90% of RTP participants. FedNow has boarded 108 financial institutions thus far.

Enhanced Control for Cash Flow

RTP provides businesses with the capability to manage the timing of their outgoing payments accurately, ensuring a better grasp of their cash flow, a critical aspect for small and mid-sized enterprises.

Additionally, RTP enables businesses to obtain instant confirmation of each payment’s receipt, facilitating improved cash flow management and the potential to leverage early payment discounts.

Enhanced Control for Cash Flow

Conclusion

The “digital” finance sector is experiencing a notable shift toward the adoption of real-time transaction solutions, as CFOs adopt a cautious strategy for leveraging instant payments within their operations. While the availability and advantages of real-time payments, such as enhanced transparency, cost efficiency, and improved cash flow management, are becoming increasingly evident, some finance leaders remain cautious in fully adopting these systems.

The cautious approach is driven by several factors, including industry-specific requirements, established payment processes, and cost considerations. Despite the benefits of real-time payments, CFOs are carefully evaluating the potential impacts on their current financial landscapes, assessing whether the benefits outweigh the associated costs and complexities of transitioning to these new systems.

As both the Federal Reserve’s FеdNow and TCH’s RTP Network continue to expand their services and functionalities, the potential for enhanced financial control and streamlined payment processes becomes more apparent with more and more people adopting this solution despite the current payment environment where CFOs Are Cautious About Real-Time Payments With the anticipation of additional enhancements and functionalities, businesses arе encouraged to actively engage with their financial institutions to explore the opportunities and benefits of integrating real-time payment solutions into their operations.

Nuvei Partners with American Express to Enable Effortless A2A Payments

Nuvei Partners with American Express to Enable Effortless A2A Payments

Pay with Bank Transfer, a division of American Express, recently revealed that they have chosen Nuvei Corporation, a known fintech company, to be their first authorized acquirer responsible for promoting and delivering the innovative payment method made possible by Open Banking.

As Nuvei Partners with American Express to enable effortless A2A payments, this forward-thinking payment solution allows consumers to effortlessly conduct transactions directly from their banks, eliminating the need to put in the card attributes or undergo additional authentication procedures. PwBt provides vendors with a seamless payment experience that includes instant fund reconciliation and attractive processing charges. Nuvei will actively promote PwBt to both existing and new merchants in the UK, helping them seamlessly integrate the Open Banking approach into their e-commerce platforms.

In the UK, over 7 million users are already benefiting from direct bank account payments facilitated by Open Banking. Early adopters in sectors such as utilities and travel are recognizing the security benefits of PwBt, which makes it an appealing option for one-time high-value payments like holiday bookings as well as for streamlined and immediate bill settlements.

Key Takeaways
  • PwBt Selects Nuvei as First Acquirer for Open Banking Solution: Nuvei Partners with American Express to promote and distribute its innovative Open Banking-powered payment method.
  • Seamless Integration into Nuvei’s Checkout Process: Nuvei offers its customers an effortless way to integrate PwBt into their checkout process. This can be done by utilizing Nuvei’s customizable payment solution, which allows for an overview of all payment data from each customer transaction. Additionally, it simplifies payment operations, making them more efficient and streamlined.
  • Enhanced Benefits for Merchants and Consumers: As Nuvei Partners with American Express, this collaboration aims to provide its merchant partners with efficient and secure payment alternatives, promoting increased conversion rates and reduced cart abandonment. PwBt’s expansion is set to contribute to the broader adoption of Open Banking solutions, fostering trust and comprehension among consumers.
  • Open Banking’s Empowering Potential: Open Banking technology enables individuals to have control over their management and opens up possibilities for innovative payment solutions, like PwBt, which enhances user experience with its security and seamless operation.

Background

In a press release issued in 2019, American Express announced its plan to introduce a real-time financial transaction product for consumers in the UK. This product – PwBt – was designed to allow people to make payments for goods and services. The PwBt service is designed specifically for individuals who have bank accounts, regardless of whether or not they have an American Express card. American Express has partnered with eCommerce merchants from different industries, including well-known names like Hays Travel and Thai Airways.

2 16

Image source: Nuvei

By taking advantage of the opportunities presented by open banking regulations, the PwBt feature enables sellers to receive payments from customers who are connected to leading banks in the UK. Buyers can conveniently check their account balances and make payments online using this service. American Express recognized the potential offered by open banking and got in line to help businesses with a new, efficient, and secure way to accept online payments from their customers.

The whole structure of open banking empowers individuals with greater control over their financial management. The regulations implemented by the EU at the time facilitated the sharing of data from multiple banks, paving the way for innovative payment solutions such as PwBt. This solution recently expanded its way to a Canadian giant as Nuvei Partners with American Express to Enable Effortless A2A Payments.

Nuvei Partners with American Express to Expand PwBt’s Seamless Open Banking-Powered Solutions

PwBt provides a secure method for paying your American Express bill through a direct transfer from your bank account. It’s a user-friendly process that takes just a few simple steps, without the need for any account setup. Additionally, since your bank manages the payment entirely, you benefit from top-tier bank-level security, with none of your payment details stored by American Express.

Nuvei customers will have the opportunity to seamlessly integrate PwBt directly into their online checkout process using their existing link to Nuvei technology. Leveraging Nuvei’s adaptable and full-stack tailor-made payments solution, online businesses can optimize their checkouts and streamline their backend payment operations through a unified connection, facilitating smoother interactions and providing a consolidated picture of all payment data from every customer transaction.

The CEO of Nuvei, Philip Fayer expressed pride in extending the availability of PwBt to their merchant partners, enabling them to meet the increasing customer demand for efficient and secure payment alternatives.

He added that their goal is to facilitate closer connections between their clients and their customers through flexible payment options, regardless of location or preferred payment method. Backed by American Express but accessible to anyone with a bank account, they recognize that PwBt surpasses expectations by providing a secure and seamless service that is inclusive and user-friendly. They are excited to collaborate in extending these advantages to a wider customer base.

3 16

Image source: Nuvei

Holly Coventry, the Vice President, emphasized that in today’s digitally-driven environment, consumers seek straightforward and secure payment solutions. Merchants who understand this trend are experiencing increased conversion rates and reduced instances of cart abandonment.

The Nuvei partnership with American Express will expand the reach of PwBt to more merchants, addressing these concerns and offering additional benefits such as immediate reconciliation and appealing processing fees. This expansion will contribute to the broader adoption of Open Banking solutions, as consumers will gradually build trust and comprehend the advantages with more frequent exposure to this payment option.

All of Nuvei’s partners selling to customers in the UK now have the opportunity to seamlessly integrate (PwBt) instantly. The technology, backed by American Express but accessible to anyone with a UK bank account, enables customers to enjoy the effortless payment process while benefiting from American Express’s robust bank-level security measures.

About American Express

American Express serves as a global service company, providing a diverse array of products and services, including charge and credit card products, expense management solutions, consumer and business travel services, as well as stored value products like traveler’s cheques and other prepaid options. Additionally, the company offers network services, merchant acquisition and processing, servicing and settlement, point-of-sale systems, marketing and information solutions for merchants, and fee-based services, encompassing market and trend analyses, consulting services, fraud prevention, and the development of tailored customer loyalty and rewards programs.

4 15

Image source: American Express

The “Pay with the Bank Transfer” feature by American Express enables consumers to make direct online or in-store payments from their bank accounts. Leveraging the capabilities of open banking, this service provides financial and processing advantages to merchants while offering customers a simple, swift, and secure payment method.

About Nuvei

Nuvei operates as a financial service company, offering clients a range of payment technology solutions. Through Nuvei, businesses can access various payout options, along with banking, card issuing, fraud management, and risk management services. Leveraging Nuvei’s adaptable, expandable, and customizable technology, businesses can embrace next-generation payments, offer diverse payout choices, and tap into banking and card issuance opportunities.

By linking businesses to their customers across more than 200 markets, with localized acquisition in over 47 markets, 634 distinct payment methods, and 150 currencies, Nuvei equips customers and partners with the technology and insights necessary to thrive both locally and globally through a single integration.

Conclusion

The collaboration between Nuvei Corporation and American Express to facilitate seamless Account-to-Account (A2A) payments through the Pay with Bank Transfer (PwBt) solution marks a significant advancement in Open Banking-powered transactions. By leveraging Nuvei’s adaptable technology and American Express’s secure banking features, this partnership aims to provide a user-friendly and secure payment experience for consumers while aiding merchants in streamlining their checkout processes and enhancing transaction efficiency.

With an emphasis on enhancing financial control for individuals and delivering simplified, secure payment solutions for businesses, the integration of Open Banking technology presents an innovative and progressive approach within the fintech industry. As Nuvei actively promotes PwBt to a wider audience of merchants in the UK, the collaboration is expected to further accelerate the adoption of Open Banking solutions, enabling increased consumer trust and understanding of the benefits associated with this cutting-edge payment method.

Block stock surges

Block Stock Surges on Strong Earnings and Upgraded Outlook

Following a robust quarterly performance, Block stock surged on strong earnings and upgraded outlook, with an increase of up to 17% during after-hours trading. The payment company, led by Jack Dorsey, has updated its adjusted profit forecast to show confidence in its ability to withstand the harsh economy’s impact on consumer spending. This positive revision aligns with the performance observed in the sector, which closely reflects consumer spending patterns.

Block now expects to achieve adjusted core earnings ranging from $1.66 billion to $1.68 billion for the year, surpassing their estimate of $1.50 billion. Additionally, the company aims to achieve profitability based on operating income by 2024. Amrita Ahuja, the finance chief, has disclosed plans to reduce the workforce by year’s end as part of a comprehensive cost-saving program implementation.

Block stock

Source: Google Finance

Key Takeaways:
  • Stock Surge Following Upgraded Forecast: Block Stock Surges on Strong Earnings and Upgraded Outlook, with shares climbing as much as 17% in early trading, buoyed by an improved forecast for the entire year’s adjusted EBITDA, signaling investor confidence in the company’s financial health and prospects.
  • Exceeding Financial Expectations: Block has surpassed the expectations set by Wall Street in Q3 2023. Their adjusted earnings per share (EPS) of $0.55 exceeded consensus estimates, resulting in a surge in Block shares price after their impressive earnings beat and increased full-year guidance. This strong performance aligns with their revenue growth trend, as their net revenue has increased by 24%. Moreover, their adjusted EBITDA has significantly surpassed expectations.
  • Strategic Cost-Saving Initiatives: To enhance efficiency and profitability, Block is implementing a cost-saving program that includes measures like downsizing the workforce and automating processes. Their goal is to achieve profitability on an operating income basis by 2024.
  • Robust Growth Across Platforms: Blocks Cash App and Square segments have experienced robust growth year over year. The monthly active accounts for Cash App have seen an increase, while Squares revenue has grown by 12%. This noteworthy growth across platforms further supports Block’s raised earnings expectations and ambitious targets for the future.

Block Stock Surges: Soaring Shares and EBITDA Outshine Estimates With Strong Outlook

Block stock surged, climbing as high as 17% during early trading, following the company’s upward revision of its adjusted EBITDA projection for the year. In the third quarter, Block reported a significant rise in EPS to $0.55 compared to $0.42 in the previous year, surpassing the expected value of $0.47. The company’s net revenue reached $5.62 billion, showing a growth of 24% YOY.

Adjusted EBITDA exceeded expectations at $477.5 million, surpassing the estimated value of $373.8 million, while the total payment volume increased by 10% annually and reached $60.08 billion. Cash App stood out as a competitor with an account activity of $55 million for transactions, marking a 1.9% increase from the previous quarter.

Block gross profit

Source: sec.gov

Additionally, Block revised its adjusted EBITDA projection for the year to be around $1.67 billion. The company expects significant growth in adjusted EBITDA to reach approximately $2.4 billion by 2024. Furthermore, Block announced a stock buyback program of $1 billion.

Ahuja mentioned that they have identified areas where they expect to find cost savings, such as real estate, process improvements through automation, and discretionary spending.

With consumer spending in the US maintaining a generally positive trend, analysts anticipate a rise in sales during the crucial holiday shopping season, supported by retailers offering substantial discounts on various products to attract buyers. Furthermore, Block has now projected a gross profit for 2023 ranging from approximately $7.44 to around $7.46 billion.

22

Source: sec.gov

23

Source: sec.gov

As the Block stock surges on strong earnings, the expectations for 2024 are high, with the company expecting a significant enhancement in adjusted operating income margin compared to 2023. In its shareholder letter, the company stated that its outlook does not consider any additional macroeconomic deterioration that could affect its results.

During the Q3 results, net revenue experienced a 24% YOY growth, escalating from $4.52 billion to around $5.62 billion. Bitcoin revenue surged from $1.76 billion to $2.42 billion YOY. Gross profit increased by 21% compared to the same period last year, rising from $1.57 billion to $1.9 billion.

Block adjusted EBITDA 2023 Q3

Source: sec.gov

Adjusted EBITDA stood at $477 million, in contrast to $327 million in the year prior. Block observed particularly robust growth in its payment platform, Cash App, and its POS options from Square.

Cash App revenue reached $3.58 billion, marking a 34% YOY growth, while Square revenue increased by 12% YOY to $1.98 billion. Jack Dorsey remarked that they have been relatively quiet recently due to their intense focus.

Key Revenue Details

  • Transaction Segment: The company’s transaction revenues reached $1.66 billion, reflecting a 9.3% increase from the previous year. However, this figure was slightly below the expected $1.68 billion.
  • Strong Square Ecosystem: Within the transaction revenues, the robust Square ecosystem contributed $1.54 billion, marking a 10% growth from the prior year.
  • Subscription and Services: Revenues from this category amounted to $1.49 billion, indicating a significant 25.3% surge year over year, surpassing the expected $1.46 billion. The solid performance of the Square ecosystem played a role, contributing $402 million to subscription and service revenues, up 21% from the previous year.
  • Hardware Segment: The company’s business generated $42.3 million in revenues, showing a slight decline of 2.4% from the previous year, missing the projected $45.9 million.
  • Bitcoin: Revenues from the Bitcoin category totaled $2.42 billion, representing a substantial 37.5% increase from the previous year.

These figures demonstrate the company’s varied revenue streams and its continued growth in different segments.

Block’s Q3 Earnings – Balance Sheet And Operation Details

For the third quarter of 2023, the company saw its gross profit increase by 21.1% from last year, reaching $1.898 billion. However, the gross margin saw a slight decrease of 0.9% from the previous year, ending at 33.8%. Breaking it down, the Cash App was a standout, with its gross profit rising to $984 million, which is a 27% boost from the previous year. Similarly, Square’s earnings were up, with a gross profit of $899 million, marking a 15% increase from the year before.

image 19

Source: sec.gov

When we look at the adjusted EBITDA, there’s a notable rise to $477.5 million, which is a 45.9% jump from last year. This is while keeping in mind that the non-GAAP operating expenses also climbed by 14.4%, reaching $1.44 billion.

There’s also good news regarding operating income. It saw a significant climb to $89.8 million, a substantial increase from the $32.2 million reported in the quarter last year. Turning our attention to the balance sheet, as of September 30, 2023, there’s a healthy cash and equivalents balance of $5.1 billion, up from $4.7 billion at the end of June. The short-term investments also saw an uptick, standing at $1.16 billion, compared to $1.12 billion in the previous quarter.

The long-term debt has remained more or less the same, with a slight increase to $4.118 billion from $4.114 billion in the previous quarter.

About Block

Block, Inc. concentrates on building comprehensive ecosystems tailored to specific customer groups. Operating across two primary segments, namely Cash App and Square, the company provides a range of services designed to meet the needs of businesses and individual consumers. Under the Square segment, Block enables businesses or sellers to process card payments, offering a suite of products and services that support their operational growth. This segment combines hardware, financial, and software services, creating user-friendly products and services.

image 20

Image source: Block

On the other hand, the Cash App segment offers a variety of financial tools and services, empowering consumers to effectively manage their finances. With a focus on enhancing financial management, Cash App facilitates money transfers, savings, spending, investments, and receipt management. Additionally, Block’s TIDAL platform serves as a global hub for musicians and their fans, providing engaging content and experiences to foster stronger connections between artists and their followers.

The company also engages in the Bitcoin ecosystem through Spiral, an independent team dedicated to contributing to the open-source development of Bitcoin technology. 

Conclusion

The company’s strategic adjustments to its earnings forecast, coupled with cost-saving measures and a focus on operational profitability, have cemented investor confidence.

The strong growth across both Cash App and Square segments is a testament to the company’s robust business model and its ability to adapt and thrive in a volatile economic environment. As Block continues to diversify its revenue streams and enhance its operational margins, it stands as a compelling example of resilience and forward-thinking in the fintech sector. The upward trajectory in its financials, backed by a comprehensive ecosystem of products and services, positions Block to not only weather potential economic downturns but also to seize new opportunities for growth and innovation.

PayPal New CEO, Alex Chriss: Background

PayPal New CEO, Alex Chriss, Asserts Leadership in First Ever Earnings Call

Unlike many new corporate leaders, PayPal New CEO, Alex Chriss, has not hesitated to make significant directional changes early in his tenure. In the Q3 earnings call. Chriss, who took over as CEO after Dan Schulman on September 27th, emphasized his focus on achieving growth.

This marks a departure from Schulman’s emphasis on PayPal’s checkout service. Initially, this shift caused a decrease in investor confidence and a decline in the company’s stock value.

Key Takeaways:
  • New CEO’s Strategic Shift: Alex Chriss highlighted the importance of focusing on growth and moving away from the checkout service that Dan Schulman previously had priority on. Chriss’s leadership signifies a change in strategy aiming for an effective and growing organization.
  • Resilient Q3 Performance: Despite facing difficulties in the market and experiencing heightened competition, PayPal displayed a strong performance in Q3 of 2023. Some notable achievements during this period include a 15% rise in payment volume, an 8% increase in revenues, and a 20% growth in EPS. Moreover, the company exhibited good operating cash flow and free cash flow throughout this timeframe.
  • Strategic Overhaul: As part of its revamp, PayPal made notable changes to its operations, like divesting its logistics branch, Happy Returns to UPS. The company’s goal is to make operations more efficient and provide experiences for customers by implementing automation and enhancing the checkout process. Moreover, PayPal plans to utilize AI technology to engage consumers and improve its range of business solutions.
  • Financial Overview and Company Profile: PayPal provides an overview of its situation, including information about its cash holdings, investments, and debts. Additionally, the company demonstrates its dedication to rewarding shareholders through stock repurchases. Moreover, PayPal’s mission revolves around stimulating empowerment and focusing more on economic participation through its inclusive digital payment platform that serves millions of active account holders worldwide.
image 15

PayPal Stock Price On 12-18-2023 (11:00 am) ( Source Google Finance)

PayPal New CEO, Alex Chriss: Background

PayPal’s New CEO, Alex Chriss assumed the position of CEO on September 27, replacing Dan Schulman when PayPal was head-on with various challenges in the fintech industry. The company has faced a decrease in its stock value due to decreasing investor interest in fintech companies, tough competition from Apple, and slower growth in its branded checkout business over the past few years.

Given Chriss’s extensive experience at Intuit, he is expected to lead PayPal’s recovery. However, analysts on Wall Street caution that reviving the company might take a long time and extensive efforts.

The year 2023 proved difficult for PayPal, as its stock mostly traded at low levels compared to the long-term average. While this made the stock more affordable, potential investors were still worried about uncertainties in the economy and reduced consumer spending. However, there was a positive market response to the plans of PayPal’s new CEO, Alex Chriss. He aimed to streamline the company’s resources towards its growth priorities to create a leaner, more efficient, and effective organization. Overall, market observers hold a confident view of the stock’s long-term prospects.

Regarding growth, one of the primary hurdles facing the company is intense competition. The market dynamics have significantly changed since PayPal’s separation from eBay approximately eight years ago, with consumers now having alternative options, such as Apple Pay, that provide a fast and convenient checkout experience. The payment systems of Amazon and Google continue to gain traction, posing challenges for PayPal, which heavily relies on e-commerce for revenue generation. It is essential to note that the termination of PayPal’s operating agreement with eBay a few years ago has impeded its growth.

PayPal’s Third Quarter 2023 Earnings Reflect Resilience Amidst Market Challenges

Following a more-than-expected third-quarter report, PayPal experienced a much-needed upturn in its stock value, which had been struggling since its peak in 2021. Despite its position as a leading figure in the payments sector, PayPal has faced challenges in sustaining its growth momentum during the pandemic surge, leading to ongoing struggles in its stock performance.

Speaking about it, Alex Chriss, acknowledged the obstacles ahead, highlighting the competitive pressures from firms like Block (formerly Square) and Stripe, as well as traditional financial service providers such as Fiserv and FIS. To address these challenges and improve financial performance, PayPal aims to streamline certain aspects of its operations. Chriss emphasized the need to address the company’s high-cost structure, which has been impeding its agility and clarity of focus.

On November 1, 2023, PayPal disclosed its third quarter of 2023 earnings, showcasing a robust performance with notable growth in both revenue and EPS. The company’s Overall payment volume reached $387.7 billion, marking a 15% increase and a 13% growth on an FX-neutral basis. Notably, net revenues stood at $7.4 billion, demonstrating an 8% growth and a 9% FX-neutral increase. The GAAP operating income saw a 4% rise, amounting to $1.2 billion, while the operating income (excluding GAAP) showed an 8% increase, reaching $1.6 billion.

image 16

Source: PayPal’s third quarter of 2023 earnings

GAAP EPS was reported at $0.93, compared to $1.15 in the third quarter of 2022, whereas the EPS for non-GAAP showed an impressive 20% growth, totaling $1.30 compared to $1.08 in the prior year. Additionally, the company recorded a significant operating cash flow of $1.3 billion and a free cash flow of $1.1 billion.

PayPal’s Strategic Overhaul – Enhancing Consumer Experience and Streamlining Operations

PayPal recently divested its logistics arm, Happy Returns, to UPS, as part of its strategy to streamline operations and focus on its core payments model. CEO Chriss emphasized the need to address duplication and manual work, intending to invest in automation for improved efficiency.

During his initial month in the role, Chriss engaged with various stakeholders to outline a plan that aims to revolutionize product development and reporting practices. This plan, to be unveiled in the upcoming earnings call, involves a comprehensive overhaul of the consumer experience, centering on a seamless checkout process that adds value to each transaction.

For consumers, PayPal intends to leverage its rich database to power a sophisticated shopping recommendation engine and enhance incentive marketing using AI technology. In the business segment, the company plans to accelerate the advancement of PayPal Complete Payments, an offering tailored for digital merchants. Utilizing consumer data for refining checkout form autofill is also a focus.

PayPal’s New CEO also highlighted the potential of generative AI in fostering meaningful connections between consumers and merchants, ensuring responsible use of this technology. The company anticipates recruiting seasoned professionals to reinforce its talent pool in the upcoming months, recognizing the need for enhanced execution speed in driving growth and delivering on its promising outlook.

Jamie Miller has been appointed as the new CFO of PayPal to aid the company under its new expense management approach led by the new leader, Alex Chriss. Previously serving as the global CFO at EY, Miller brings a wealth of experience from her previous roles at General Electric and Cargill. She takes over from Gabrielle Rabinovitch, who has been serving as acting CFO during the transition period. In Q3, PayPal’s net income saw a 23% decline, settling down to around $1.02 billion YOY, with the company’s Q4 performance falling slightly below expectations till now, as noted by Rabinovitch. 

Expanding Service Offerings to Braintree Customers

In a bid to cater to larger companies associated with Braintree, Chriss intends to broaden the range of services offered. Describing Braintree’s position as a foothold for future growth, Chriss emphasized the company’s commitment to addressing additional customer needs, including fraud management, payouts, chargeback automation, and Forex services.

braintreen by paypal

According to William Blair, the company’s long-term prospects remain substantial, particularly as it has transitioned from a traditional checkout button to a comprehensive E2E solutions platform for both consumers and merchants. While it’s still early, the company’s sharp focus on leveraging its wealth of data for enhanced operational efficiency is encouraging for the future, as management emphasizes its commitment to pursuing profitable growth.

While acknowledging the dedication of PayPal’s current employees, Chriss also expressed the intention to bring in new talent to help achieve his objectives. In the meantime, he is diligently working to gain a comprehensive understanding of the company, with plans to present a more detailed strategy to analysts during the upcoming earnings call in February.

Key Highlights Of Q3 Results 2023

PayPal exhibited a robust performance in the third quarter of 2023, marked by an 8% increase in net revenues, which grew to 9% on an FX-neutral basis. The company saw a 4% rise in GAAP operating earnings, amounting to $1.2 billion, and an 8% increase in operating income (non-GAAP), reaching $1.6 billion. The GAAP EPS was $0.93, down from $1.15 in the third quarter of the prior year, while the EPS for non-GAAP stood at $1.30, demonstrating a 20% growth YOY.

image 17

As of September 30, 2023, PayPal’s cash equivalents and investments amounted to $15.4 billion, with a total debt of $10.6 billion. During the third quarter of 2023, the company bought back approximately 23 million common stocks, delivering $1.4 billion in returns to stockholders.

The company generated $1.3 billion in cash flow from operations and $1.1 billion in free cash flow during the quarter. These figures include a $0.8 billion of adverse impact from European BNPL loans originated as HFS in the period. 

About PayPal

PayPal offers a secure and efficient way to send money, pay and create online invoices, and establish a merchant account. With a core belief in the transformative power of accessible financial services, PayPal is dedicated to democratizing financial opportunities and empowering individuals and businesses to participate and thrive in the global economy. Their inclusive digital payment platform empowers 277 million active account holders to transact with confidence, whether online, through a mobile device, an app, or in person.

Through a blend of innovative technology and strategic partnerships, PayPal continuously develops improved methods for managing and transferring funds, providing users with flexibility and options for sending, receiving, and paying. Operating in over 200 markets globally, the PayPal ecosystem, encompassing Venmo, Xoom, and Braintree, facilitates transactions in more than 100 currencies, allowing users to withdraw funds in 56 currencies and hold balances in their PayPal accounts in 25 currencies. 

Conclusion

PayPal’s New CEO, Alex Chriss, left an indelible mark by charting a clear course for the company’s future. Departing from the previous strategy, Chriss outlined his vision for prioritizing profitable growth, setting the stage for a more efficient and agile organization. Despite market challenges, PayPal’s robust third-quarter performance, including notable increases in overall payment volume and net revenues, showcased the company’s resilience and enduring potential.

Moreover, the strategic overhaul, evidenced by the divestment of Happy Returns and a commitment to streamline operations, underscores Chriss’s dedication to optimizing consumer experiences and refining business offerings through advanced AI technologies. With the appointment of Jamie Miller as CFO, PayPal is poised to fortify its financial management and steer the company’s trajectory toward sustained growth.

As PayPal continues to empower millions of users worldwide through its secure and accessible financial services, Chriss’s leadership, coupled with the company’s continued dedication to innovation and strategic partnerships, bodes well for its continued success and enduring prominence in the global digital payment landscape.