Author Archives: hostmerchantservices

Consumer Agency to Regulate BNPL-Like Credit Cards

Consumer Agency to Regulate BNPL-Like Credit Cards

On the 22nd of April, 2024, the Consumer Financial Protection Bureau (CFPB) issued an interpretive rule. This rule will allow the consumer agency to regulate BNPL providers, similar to those governing traditional credit card issuers. The rule includes digital user accounts that offer credit access, such as loans under the BNPL model.

It states that providers marketing loans as BNPL must follow consumer protection standards outlined in federal law and regulations. This includes rules about billing disputes, product refunds, service cancellations, and disclosure requirements like periodic billing statements. The CFPB introduced this rule to provide clarity on the obligations that market participants with specific business practices must adhere to, considering the diverse loan offerings within the BNPL sector.

Consumer Agency to Regulate BNPL- Key Takeaways
  • Extension of Credit Card Regulations to BNPL Lenders: The Consumer Financial Protection Bureau (CFPB) has issued an interpretive rule that requires Buy Now, Pay Later (BNPL) providers to adhere to consumer protection standards similar to those for credit card issuers. This includes handling disputes, issuing refunds, and providing periodic billing statements.
  • CFPB’s Justification and Market Concerns: The CFPB’s decision is based on the view that BNPL loans function similarly to credit cards in many respects, such as offering credit services and charging merchants transaction fees. The Bureau aims to introduce consistency and clarity to the BNPL market, addressing issues like consumer disputes and the lack of standardized disclosures.
  • Mixed Industry Reactions: BNPL providers have responded differently to the CFPB’s rule. Affirm supports the initiative, emphasizing the need for consistent industry standards. Conversely, Klarna criticizes the approach, arguing that BNPL and credit cards are fundamentally different products and should not be regulated in the same manner.
  • Implementation and Public Feedback: The rule will take effect 60 days after its publication in the Federal Register. The CFPB has opened a comment period until August 1, 2024, to gather public input and refine the regulatory approach to better align with modern financial technologies and consumer credit models.

Background
bnpl infographics

The CFPB started investigating BNPL programs in 2021 due to rapid market growth and concerns over increasing debt and the handling of consumer data.

In 2022, a CFPB market analysis revealed that BNPL usage surged during the pandemic. Five companies issued 180 million loans totaling more than $24 billion in 2021, marking a nearly tenfold increase from 2019. The analysis found that over 13% of BNPL transactions involved returns, with consumers disputing or returning $1.8 billion worth of transactions among the five firms.

The report highlighted issues such as the absence of standardized disclosures and difficulties in dispute resolution. Since the report’s release, the CFPB has engaged in various activities to deepen its understanding of the market. These include identifying common business practices, conducting supervisory examinations, and other forms of market monitoring and investigation.

Last year, the CFPB shared insights on the financial profiles of BNPL borrowers. In March 2024, the CFPB published its Consumer Response Report for 2023, which documented consumer difficulties with merchants over BNPL issues, including not receiving items and problems canceling loans. The CFPB continues to field complaints about refunds and disputed transactions as BNPL products remain popular among various demographic groups.

CFPB Extends Credit Card Protections to BNPL Lenders

Last month, the CFPB announced its intention to apply certain consumer protection rules from the credit card industry to BNPL lenders. This move aims to increase regulation in the rapidly growing BNPL sector. Companies such as Klarna, Afterpay, and Affirm collaborate with retailers to offer finance options for customer purchases, with repayment made in installments. Despite its growth, this sector has not been subject to a comprehensive federal regulatory framework.
Consumer Financial Protection Bureau

Image source

Under a new interpretive rule issued by the CFPB, BNPL lenders must now resolve customer disputes, issue refunds for returned products, and provide periodic billing statements—requirements that align with those mandated for credit card companies under the Truth in Lending Act (TILA).

Rohit Chopra, the Director of the CFPB, stated that consumers should receive the same protections whether they use a BNPL or credit card service, citing established laws and regulations that support this policy.

Rohit further highlighted that consumers who opt for BNPL at checkout are often unsure about receiving refunds for returned products or whether the lender will assist if the product isn’t as promised.

The CFPB believes this initiative will introduce consistency to the market and is set to become effective 60 days after its publication in the Federal Register. Affirm responded positively, stating that the CFPB’s move to promote consistent industry standards is encouraging.

In their statement, Affirm also called on other BNPL providers to fulfill the industry’s commitment to offering a more flexible and transparent payment alternative compared to traditional methods.

However, Klarna expressed concerns, stating it is perplexing that the CFPB overlooks the key differences between credit cards and BNPL services. Klarna argues that regulating BNPL as if it were a credit card—comparing two fundamentally different products—will not address issues related to consumer credit card debt.
what is bnpl

The bureau defended its approach of regulating BNPL (Buy Now, Pay Later) providers in the same manner as credit card companies. It stated that BNPL loans are often used similarly to credit cards for both in-person and online purchases. Additionally, like credit cards, BNPL loans involve credit services and payment processing, and they also result in transaction fees charged to merchants, according to the press release.

A CFPB spokesperson explained that the agency conducted a thorough review of how current laws and regulations pertain to the emerging BNPL lending model. After careful examination, it was concluded that specific elements of the TILA and its implementing regulations are applicable to BNPL loans as they are presently structured.

An “interpretive” law allows an agency to offer the public its initial interpretation of existing laws concerning a specific issue.

Understanding Interpretive Rule

The CFPB recently issued a rule that redefines digital user accounts used for BNPL credit. Under this rule, these accounts are categorized as “creditors” or “card issuers” under Regulation Z subpart B. This includes any account that allows purchasing on credit through non-traditional means such as websites, apps, or browser extensions, aligning them with “credit cards” as described in Regulation Z and TILA. These digital accounts, designed for repeated use, meet the “time to time” usage criteria set out in Regulation Z, even if they do not incorporate the usual credit card fees or interest charges.

BNPL plans, typically arranged as closed-end loans to be paid in up to four installments without additional finance charges, must now provide consumer protections similar to those of traditional credit cards. These protections include:

  • Resolving disputes initiated by consumers and halting payments while disputes are resolved;
  • Issuing credits and processing refunds when consumers return goods or cancel services;
  • Sending regular billing statements akin to those provided with standard credit cards.

The rule requires BNPL providers to follow subpart B, which includes regulations on cardholder liability and the solicitation of credit cards, among other rules. While BNPL products do not fall under “open-end credit” definitions, the new rule mandates that BNPL services manage disputes, process returns, and cancellations, and provide transparent billing statements, similar to traditional credit card companies.

However, BNPL providers are not held to some of the regulations affecting credit card companies, such as caps on penalty fees or assessments of a consumer’s payment capacity.

The CFPB has opened a comment period for public input on this interpretive rule until August 1, 2024, aiming to adjust regulatory practices to better suit modern financial technologies and evolving consumer credit models.

Conclusion

Most major BNPL companies already adhere to protections similar to credit card protections, yet the new rule aims to standardize these across the industry, a CFPB official explained to journalists. The rule targets the commonly used “pay in four” installment plans but won’t enforce all credit card regulations, such as evaluating a consumer’s repayment capacity.

The CFPB believes that applying these consumer protection standards will ensure greater consistency and fairness in the BNPL sector, ultimately benefiting consumers by providing clearer guidelines and enhancing trust in these financial products. The new rule is expected to take effect 60 days after its publication, with the public comment period open until August 1, 2024.

A Look Behind the Bankruptcy and Consequences

What Happened to Synapse? Synapse Bankruptcy Freezes Customer Funds

Life comes with its share of costs—rent, mortgage, groceries, gas, and leisure activities all add up. However, what impact does losing access to one’s finances have? Currently, this is the situation for numerous Americans. Thousands of personal and business bank accounts have been frozen for weeks due to an ongoing conflict between the fintech startup Synapse and its banking partners over disputed customer balance amounts.

So what happened to Synapse? Let us analyze and understand Synapse’s bankruptcy and its effect on customers.

What Happened to Synapse? Key Takeaways of Synapse’s Bankruptcy
  • Frozen Accounts Affecting 200,000 Users: Synapse Financial Technologies’ bankruptcy has left over 200,000 customers unable to access their funds due to ongoing disputes with banking partners.
  • Judicial Intervention: A US Bankruptcy Court Judge appointed an independent Chapter 11 trustee to manage Synapse, aiming to restore access to customer funds, although the timeline remains uncertain.
  • Operational and Legal Issues: Synapse’s collapse followed a series of operational failures, management disputes, and legal conflicts with key partners like Mercury and Evolve Bank, leading to widespread service disruptions.
  • Regulatory and Consumer Impact: The situation underscores the vulnerabilities in fintech operations, prompting calls for increased regulatory oversight to protect consumers and ensure the stability of fintech services.
image 12

Image source

Synapse Financial Technologies’ Collapse Leaves 200,000 Fintech Users Without Funds

In the wake of Synapse Financial Technologies’ collapse, more than 200,000 fintech clients have lost access to their money. Since last year, disagreements over disputed customer balance numbers have arisen with many partners for Synapse, an Andreessen Horowitz-funded business that serves as a middleman between consumer-facing fintech brands and banks backed by the FDIC.

Judge Martin R. Barash of the US Bankruptcy Court (Central District of California) agreed during a recent hearing to hand control of Synapse over to an independent Chapter 11 trustee, removing the incumbent management.

Barash emphasized that his main concern is to restore consumer access to their funds, although he did not specify how soon this might occur. Previously, he attempted but failed to involve federal banking regulators to help resolve the issue. “Getting end consumers their money is the most critical thing right now,” he said, expressing the urgency of the situation. Additionally, he expressed how extremely upsetting it bothered him to hear from people who are struggling to pay for their homes or buy food.

Synapse Financial Technologies' Collapse Leaves 200,000 Fintech Users Without Funds

Michael Gottfried, an attorney representing Yotta Technologies, one of the affected fintechs, described the situation as a “house on fire,” underscoring the severity of the crisis for those cut off from their money.

The conflict escalated in April when Synapse filed for bankruptcy after losing several key partners. On May 11, Synapse disabled access to a critical technology system used by lenders to manage transactions and account details. Consequently, users of multiple fintech services have been left without access to their money.

Evolve stated in a release last week that Synapse’s shutdown has “unnecessarily put end users at risk by impeding our ability to verify transactions, confirm user balances, and adhere to legal requirements.” As a bank, Evolve is obligated to ensure all customer deposits are precisely accounted for, a process that could be time-consuming.

Despite the freeze on customer deposits, Evolve confirmed it remains financially stable. Other institutions partnered with San Francisco-based Synapse include Tennessee’s Lineage Bank and Yotta, a savings rewards company that offers prizes to incentivize customers to save.

The impact of Synapse’s operational issues might expand. According to court documents, Synapse estimated it had about 100 customer relationships affecting approximately ten million Americans before declaring bankruptcy. However, banking regulators argue this estimate is significantly inflated, expecting the number of affected individuals to be in the thousands or tens of thousands.

Synapse’s creditors were advocating in court for the bankruptcy to be converted to Chapter 7, which would have resulted in the company’s liquidation. During court proceedings, representatives for Synapse’s customers expressed concern that liquidating the company could further exacerbate the disruptions to accessing funds.

How US banking regulators might influence the situation arising from Synapse’s collapse is still being determined. Synapse is not a bank, so its regulation does not fall under the Federal Reserve or the Federal Deposit Insurance Corporation (FDIC). Additionally, since no banks associated with Synapse have failed, there is no basis for FDIC deposit insurance coverage.

The Consumer Financial Protection Bureau (CFPB), which holds law enforcement powers, might investigate Synapse’s operations and its effects on consumers.

Both traditional bankers and consumer advocates have often criticized the business model of fintech companies, which operate similarly to banks but without regulatory safeguards, as customer funds are held somewhere else.

A Look Behind the Bankruptcy and Consequences

Synapse, founded in 2014, pioneered the “banking-as-a-service” (BaaS) industry. For startups, obtaining the necessary charters and permissions and developing systems to accept deposits, grant loans, and issue debit cards is relatively inexpensive and time-consuming. In 2022, Synapse made the Inc. 5000 list of Fastest Growing Private Companies, ranking in the top 100 Financial Services companies. With 200 employees, the company served 18 million end-users, a 64% increase from the previous year, handled $91 million in transactions annually, an 82% increase, and processed $76 billion in transaction volume, up 43% from the previous year.

Despite its rapid growth, Synapse has yet to achieve profitability, and there are ongoing concerns about its aggressive management style dating back to 2020. The CEO, Pathak, an expatriate from India, was known for his impulsive decisions to dismiss engineers for not working quickly enough. Engineers reported issues with faulty code and disorganized customer databases, leading some neobanks to sever ties with Synapse due to these operational problems.

In the summer of 2022, Evolve, a bank established a century ago in Tennessee, decided to end its sponsorship of Synapse and withheld a $17 million payment to cover a $14 million discrepancy in one of the FBO accounts. The separation process has been protracted and remains unresolved, attributed to Synapse’s difficulties in reconciling account ledgers—an essential banking function typically not complicated by discrepancies and suspicious circumstances.

At the same time, Synapse faced a significant issue with its largest client, Mercury, a fintech company providing bank accounts to small businesses and holding $3 billion in deposits. Mercury claimed that Synapse had underpaid them in “rebates” that should have increased with the rising federal funds rate. This dispute led to ongoing legal action, with Mercury alleging in one lawsuit that Synapse was insolvent and requesting that its assets be frozen to ensure funds would be available should Mercury win the case.

Additionally, Mercury chose to bypass Synapse by forming a direct partnership with Evolve Bank. This move, which circumvented the need for Synapse’s involvement, posed a threat to the banking-as-a-service (BaaS) business model. The combination of public insolvency accusations and this strategic shift contributed to a severe crisis for Synapse.

Synapse had been seeking a buyer for several months before striking a deal with TabaPay, a provider of financial services to fintech companies. To facilitate this transaction, Synapse filed for Chapter 11 bankruptcy reorganization, with TabaPay agreeing to purchase Synapse’s assets for $9.7 million—a sum considerably lower than the venture capital funding Synapse had previously received.

Initially, the plan under Chapter 11 was for Synapse to sell its operational assets to TabaPay, which would have absorbed many of Synapse’s approximately 100 employees and taken over client services.

However, this deal ultimately collapsed. On May 11th, Evolve Bank & Trust, an Arkansas-based bank partner of Synapse, suspended individual consumers’ access to their accounts and debit cards. Evolve stated it was unable to access necessary records at Synapse to verify account balances.

Despite the challenges and reduced staff, Synapse continued to play a crucial role in managing substantial customer funds. During court proceedings, another sponsor bank, Lineage, reported that Synapse managed funds for the benefit of others (FBO) accounts with assets valued between $60 million and $80 million. This did not include the assets held in the Evolve FBO and other bank relations. Liquidating Synapse involves disentangling these complex banking relationships. The overseeing bankruptcy judge, Martin Barash, described the situation as a “hot mess.”

Following TabaPay’s withdrawal from the acquisition, Lineage, which was under a federal consent order for its dealings with fintechs, ceased processing payments for clients of Synapse. Some clients, like Juno, transitioned to Evolve. Concurrently, on May 11, the Synapse dashboard that Evolve used to manage customer accounts malfunctioned. This led to a sudden halt in access to fintech app accounts, with all direct deposits and transactions being returned to the senders.

What Should the Affected Parties Do?

If you’ve been affected and need to file a complaint, contact the FDIC by phone at 1-877-275-3342 or online.

If you want to provide input on fintech regulations, contact the Consumer Financial Protection Bureau by phone or online.

About Synapse

What Happened to Synapse?

Image source

Synapse Financial Technologies Inc. operates as a banking-as-a-service (BaaS) platform, specializing in creating banking software solutions. The company provides an array of API products across payment, deposit, lending, investment, and finance sectors, enabling clients to develop and launch their banking products.

Synapse aims to simplify the process for users to create and implement financial applications, often referred to as the “AWS of banking.” Their offerings encompass a range of products, including lending, credit services, wealth management, online payment processing, embedded finance, and card solutions.

Conclusion

The collapse of Synapse Financial Technologies has significantly disrupted the lives of over 200,000 users who have lost access to their funds. Amidst ongoing bankruptcy proceedings and disputes with banking partners, the company’s operational failures have left many struggling to meet basic financial needs. The appointment of a Chapter 11 trustee aims to address these issues, yet the timeline for restoring access to customer funds remains uncertain.

As the situation evolves, affected parties should stay informed and consider reaching out to regulatory bodies like the FDIC and the CFPB for assistance and to voice concerns about fintech regulations. This case highlights the vulnerabilities in fintech operations and the critical need for robust regulatory oversight to protect consumers.

Mastercard Crypto Credential Goes Live, Adds New Partners

Mastercard Crypto Credential Goes Live, Adds New Partners

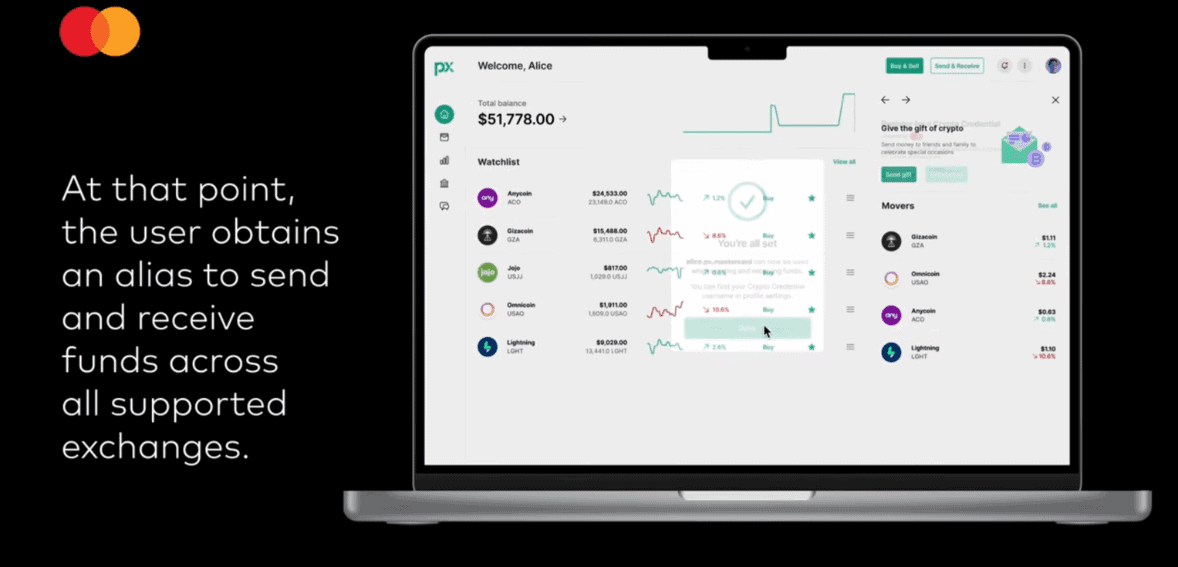
Mastercard has reached a new milestone in its cryptocurrency initiatives. Its Crypto Credential offering, introduced at Consensus 2023, is now operational. With their Mastercard Crypto Credential aliases, users of cryptocurrency exchanges can send and receive cryptocurrency, saving them time by eliminating the need for a complex alphanumeric address.

Mastercard Crypto Credentials make verifying how customers and organizations interact on blockchain networks more accessible. Users no longer need to use the more complicated blockchain addresses to complete transactions; instead, they can use simpler identifiers.

The Mercado, Lirium, and Bit2Me exchanges have activated live transaction capability. This enables secure and straightforward blockchain transactions in European and Latin American markets.

Key Takeaways
  • Simplified P2P Transactions: Mastercard’s Crypto Credential pilot program enables easier peer-to-peer cryptocurrency transactions using simplified aliases, eliminating the need for complex blockchain addresses.
  • Enhanced Security and Compatibility Checks: The program verifies the recipient’s alias and wallet support for the specific digital asset and blockchain before completing transactions, preventing potential fund loss.
  • Global Reach and Partnerships: The service is available in 13 countries across Latin America and Europe, facilitated through partnerships with several crypto exchanges, including Mercado, Lirium, and Bit2Me.
  • Future Expansion and Regulatory Compliance: Mastercard plans to expand the program to include NFTs and blockchain ticketing while ensuring compliance with regulatory standards to enhance transparency and security in blockchain transactions.
Mastercard Crypto Credential Goes Live

Mastercard Introduces Crypto Credential for Simplified P2P Transactions

Mastercard began its Crypto Credential pilot program on May 29, 2024, to streamline peer-to-peer (P2P) bitcoin transactions. Now that the application is up and running, users can transfer and receive cryptocurrency using simpler aliases instead of complicated blockchain addresses.

When a transfer is started, the Mastercard Crypto Credential ensures that the recipient’s wallet offers the particular blockchain and verifies the legitimacy of the recipient’s alias. If the recipient’s wallet does not support the asset or blockchain, the transaction is stopped, and the sender is notified, thereby averting potential fund loss.

Mastercard has enabled this service in partnership with several crypto exchanges, including Mercado, Lirium, and Bit2Me, to facilitate secure blockchain transactions between Latin America and Europe. This service is available to users in 13 countries, allowing them to conduct cross-border and domestic transfers across various blockchains and currencies. Countries include:

  • Uruguay
  • Switzerland
  • Spain
  • Portugal,
  • Mexico
  • Guatemala
  • France
  • Chile
  • Brazil,
  • Peru
  • Paraguay
  • Panama
  • Argentina

Walter Pimenta, Mastercard’s Executive VP of Product and Engineering for the Caribbean and Latin America, stated that Mastercard remains committed to enhancing its standards, partnerships, and technology to deliver simple, secure, and safe payment solutions.

Mastercard Crypto Credential Goes Live, Adds New Partners

He underlined the need to enable verifiable and reliable interactions across different public blockchain networks in light of the growing interest in blockchain and digital assets in Latin America and worldwide. Pimenta was excited to work with a vibrant collection of partners to further the development of the Mastercard Crypto Credential.

Mastercard elaborated that adding new partners like Foxbit and integrating with Lulubit through Lirium extends the scope of its pilot program, offering wider access to consumers. It is poised to expand its applications to include non-fungible tokens (NFTs) and blockchain ticketing, depending on market demand and regulatory compliance. Mastercard highlights that this initiative represents a major advancement in utilizing blockchain technology for mainstream financial transactions, focusing on safety and ease of use.

Talking about it, Ricardo Dantas, CEO of Foxbit Group, stated that collaborating with a leader like Mastercard strengthens their dedication to meeting market demands. They aim to provide solutions that enhance the user experience in the rapidly evolving cryptocurrency sector.

This collaboration significantly enhances their presence in the crypto market. Their joint efforts, which include partnering with Mastercard Crypto Credential and launching the Foxbit Card, align seamlessly with their mission to increase the accessibility and usability of crypto, giving their customers more options to control and optimize their digital finances.

Mastercard Crypto Credential also aims to authenticate interactions between consumers and businesses on blockchain networks. It ensures that users adhere to specific verification standards and verifies that the recipient’s wallet can accept the transferred asset. The service simplifies the process for consumers by automatically determining which assets or blockchains the recipient supports through metadata exchange. This is intended to increase trust and reliability in transactions.

tractions on Mastercard Crypto Credential

All image source: Youtube

Furthermore, it facilitates the exchange of Travel Rule information for cross-border transactions, meeting regulatory requirements that enhance transparency and help prevent illegal activities.

Mastercard’s initiative reflects a broader trend among traditional financial institutions to integrate blockchain technology and cryptocurrencies into their offerings. For instance, Visa is investigating methods to facilitate Ethereum gas fee payments through its cards, utilizing the ERC-4337 standard and a specialized smart contract known as “paymaster” to manage off-chain gas fee payments.

The launch of Mastercard Crypto Credential marks a significant development in digital finance. Mastercard fosters broader adoption of cryptocurrencies by streamlining blockchain transactions and offering a secure, user-friendly platform.

About MasterCard

Mastercard Inc. (Mastercard) is a payment and technology company that authorizes, clears, and settles payment transactions. It provides a variety of payment solutions, including debit, credit, commercial, and prepaid cards; real-time account-based payments; digital payments; and transaction services for both cross-border and domestic transactions. Additionally, it offers payment system security.

Mastercard also delivers value-added services like rewards and loyalty programs and advisory services, including analytics, implementation, and consulting. The company serves financial institutions, individuals, businesses, digital partners, governments, merchants, and other organizations across the Middle East, Americas, Europe, Africa, and Asia-Pacific. Mastercard is based in New York, US.

Conclusion

Mastercard’s launch of the Crypto Credential pilot program marks a significant advancement in digital finance. This initiative streamlines cryptocurrency transactions using simplified aliases instead of complex blockchain addresses. It enhances transaction security and user experience and prevents potential fund loss by verifying wallet compatibility before transfers. The service supports cross-border and domestic transfers, operating in 13 countries with partners like Mercado and Bit2Me.

Mastercard is working with new partners and has plans to expand into NFTs and blockchain ticketing. This shows their commitment to integrating blockchain technology into mainstream financial transactions. By ensuring safe, simple, and secure interactions, Mastercard is helping to drive broader adoption of cryptocurrencies and strengthen its position as a leader in the evolving digital finance landscape.

Visa Pay-by-Bank Services for the US

Visa Pay-by-Bank Services for the US

With technological advancements and the implementation of instant bank payment systems, pay-by-bank or paying directly from bank accounts could become as prevalent as using debit or credit cards in the US. This method is already widespread across Europe and many other regions.

Merchants benefit from reduced fees if they encourage customers to switch from credit cards to bank payments. Many consumers are already comfortable using direct bank payments for transactions like bill payments, and new technologies are enhancing this experience. However, paying by bank is less common in retail and eCommerce shopping. Nonetheless, recent technological improvements are minimizing obstacles and making it more practical. In a significant move, Visa, a leading card network, is now gearing up to introduce pay-by-bank services in the US.

Key Takeaways
  • Visa Introduces Pay-by-Bank Services in the US: Visa is expanding beyond traditional card services to offer direct bank-to-bank payment options, aiming to complement its existing debit, prepaid, and credit card offerings.
  • Reduced Fees for Merchants: Merchants could benefit from lower transaction fees by encouraging customers to use direct bank payments instead of credit cards, especially for bill payments, subscriptions, and loan repayments.
  • Success in Europe with Tink: Visa’s pay-by-bank model has seen significant adoption in Europe, driven by Tink, a payment platform owned by Visa. Tink’s partnerships and the growing trend towards open banking have facilitated this success.
  • Improved Efficiency and Security Over ACH: Visa’s pay-by-bank services aim to surpass ACH transactions in terms of quality, addressing issues like fraud and processing delays and offering a more efficient and secure payment method for large, infrequent transactions.

Visa Expands Beyond Cards with New Pay-by-Bank Services

Visa Expands Beyond Cards with New Pay-by-Bank Services

Visa has traditionally focused on its card services. Still, the company is now expanding to offer other types of money transfer services, aiming to complement its existing debit, prepaid, and credit card offerings.

The pay-by-bank model facilitates direct payments from a consumer’s bank account to a business’s bank account, eliminating the need for a credit or debit card. These transactions can cover any purchase but are commonly used for bills, subscriptions, and loan repayments.

In Europe, the adoption of such services has grown, highlighted by the success of Tink, a payment platform owned by Visa. Tink has introduced its pay-by-bank method through partnerships with several companies, signaling a strong move towards open banking, a system that allows more direct transactions between banks and businesses without intermediaries.

Although these developments could pose a competitive challenge to Visa’s traditional card business, the company is integrating these new services into its portfolio. The upcoming introduction of pay-by-bank services in the US aligns with the Consumer Financial Protection Bureau’s (CFPB) push towards a regulatory framework that supports more open banking services. This indicates a significant shift in how financial transactions could be conducted in the future.

Jack Forestell, Visa’s inaugural Chief Product and Strategy Officer, stated that the company has been diligently setting up the necessary infrastructure for launching its pay-by-bank service. This groundwork includes establishing connections with banks and forming agreements with banks and processors to ensure robust capabilities for customer authentication and linking. He mentioned that Visa has signed on some pilot customers and is now prepared to launch the pay-by-bank service.

A2A payment

Visa’s established reliability and security will be incorporated into the new pay-by-bank services, according to Forestell. He described the service as a straightforward digital process that customers will encounter in specific scenarios. Sellers will offer the option to pay via bank, powered by Visa. Users will simply click a button, authenticate with their bank, and the payment will be processed, he explained during the conference. Forestell noted that these services are likely to be used in areas where account-to-account transactions are common, particularly for large payments.

Forestell also highlighted certain areas where these services are useful—such as rent, loan payments, healthcare, life insurance, education, and long-term care. These are typically larger, infrequent payments. Although there is some use of cards in these sectors, the adoption rate remains relatively low.

Typically, such payments are conducted through ACH transactions, which have increased. However, Forestell believes that Visa’s pay-by-bank services could surpass ACH in quality.

Forestell pointed out that ACH transactions are problematic and inefficient, often due to issues with fraud and delays in processing. These delays disrupt the payment process, and he argues that Visa could overcome these challenges by offering a method that is both more efficient and secure. He suggests that these improvements could lead to higher transaction volumes and enhance the services provided by financial and commercial partners.

In Europe, Visa’s pay-by-bank services have experienced significant growth, especially following the acquisition of Tink. Over the last two years, payment initiation volumes have significantly risen. Furthermore, Tink has partnered with companies like Splitwise, Payop, and TransferGo to extend the use of pay-by-bank services.

About Visa

Update on Visa MasterCard Settlement

Visa is a multinational payments technology corporation that facilitates the use of digital currency in place of conventional cash and cheques by tying together customers, companies, banks, and governments in more than 200 countries and territories. With the ability to process over 24,000 transactions per second, the company’s sophisticated processing network is renowned for its dependability, convenience, and security, which includes safeguarding against consumer fraud and ensuring merchant payments.

Although Visa does not provide credit, issue cards, or set rates and fees for customers, its technology innovations allow financial partners to offer a range of payment choices, such as credit, debit, and prepaid cards. Customers now have more payment options thanks to these advancements.

Governments worldwide are switching to digital currencies to reduce overhead costs and increase efficiency when distributing rewards and making purchases. Visa is making it easier for people to use digital currency and mobile technologies for financial management, online shopping, international transfers, and access to basic financial services by extending the reach of electronic payments beyond big cities to rural, unbanked areas. This expansion facilitates everyday financial operations and boosts economic growth.

Conclusion

Visa’s move to introduce pay-by-bank services in the US represents a significant evolution in payment options, aligning with technological advancements and consumer preferences. This new service is set to reduce transaction fees for merchants and enhance security and efficiency compared to traditional ACH transactions.

Building on its successful European model through Tink, Visa is poised to leverage its existing infrastructure and reliability to expand these services domestically. As Visa integrates these direct bank payment methods into its portfolio, it underscores a shift towards more direct, efficient, and secure financial transactions, potentially transforming the payment landscape in the US.

1 3

TicketMaster Data Breach: Hack Affects Over a Half Billion Users

Over 500 million customers have been impacted by a significant Ticketmaster data breach after a cyber-attack targeted the website. Reports indicate that hackers have accessed customers’ names, phone numbers, and addresses globally, totaling 1.3 TB of stolen data. The group responsible, known as TheShinyHunters, is reportedly asking for a $500,000 ransom in exchange for the stolen database.

Key Takeaways
  • Massive Data Compromise: Over 560 million TicketMaster customers’ personal information, including names, phone numbers, addresses, order histories, and partial payment data, was stolen and is being sold by the ShinyHunters hacking group.
  • High Ransom Demand: The ShinyHunters are attempting to sell the 1.3 TB of stolen data for $500,000 on the dark web forum Breach Forums.
  • Ongoing Investigations: The Australian Department of Home Affairs and the FBI are collaborating with Ticketmaster to investigate the breach, with suspicions that the attack may have involved accessing a cloud-hosting service called Snowflake.
  • Security Concerns and Legal Context: This breach adds to Ticketmaster’s history of security issues and comes amid a legal challenge from the US Department of Justice and 29 states accusing Ticketmaster of monopolizing ticket sales and suppressing competition.

Massive Data Breach by ShinyHunters Exposes Over 560 Million TicketMaster Customers

Massive Data Breach by ShinyHunters Exposes Over 560 Million TicketMaster Customers

Yet another breach has been announced by a hacking group. A hacker group known as ShinyHunters has taken responsibility for a data theft incident that compromised the personal information of over 560 million TicketMaster customers. This group is allegedly selling this 1.3 TB of data on a well-known hacking forum, Breach Forum. The hacking incident and resulting data leak occurred alongside the relaunch of BreachForums. This dark website facilitates the buying and selling stolen materials and information that can be used to conduct hacks.

The group is trying to sell the data for a one-time fee of $500,000 (£400,000) to any interested buyer. If you’ve ever used Ticketmaster, the following details could currently be at risk of being sold to malicious entities by the ShinyHunters:

  • Name
  • Phone number
  • Address
  • Order history and purchase specifics
  • Email address
  • Partial payment data, including the last four digits of your credit card number and the card’s expiration date

With such data, hackers have ample opportunity to cause significant problems. Given the large number of affected individuals—over 500 million—a skilled hacker has numerous potential targets for extracting payment information and possibly accessing bank accounts.

This data breach might be the largest in terms of the sheer volume of affected individuals and the extensive data compromised. The Australian Department of Home Affairs reportedly collaborates with Ticketmaster to investigate the breach. Additionally, the FBI is said to have offered its help to Australian officials.

The specifics of how ShinyHunters executed its attack remain unknown. However, there are indications that the attacks may have targeted a cloud-hosting service known as Snowflake, which led to this major leak.

However, denying the news, Snowflake reported in its blog update that there is no indication the incident was due to any vulnerabilities, misconfigurations, or security breaches of its platform. Nevertheless, they did verify that a threat actor gained access to demo accounts using the credentials of a former employee. These accounts contained no sensitive data.

Ticketmaster has previously faced similar issues with online security breaches, including bad actors using bots to manipulate ticket sales and purchase tickets for resale. In 2021, Ticketmaster faced a $10 million fine for illegally accessing data from Songkick, a competitor. Employees of Ticketmaster had obtained login details and accessed SongKick’s computer systems without authorization. The ticketing company reported last January that cyber-attacks driven by bots disrupted sales for Taylor Swift concerts.

Talking about the hacking group, it’s not their first attack; ShinyHunters was responsible for a 2020 data breach at Mashable. They accessed a database linked to a defunct feature that enabled users to log into Mashable with their social media accounts. The breach compromised data such as email addresses but did not include passwords or financial information.

ShinyHunters also claims to have contacted Ticketmaster regarding the breach but says they have not received a response.

This announcement is part of a broader context where Ticketmaster is facing a legal challenge from the US Department of Justice and 29 states, accusing it of monopolizing ticket sales and suppressing competition.

Steps to Take If You’re Worried About the Ticketmaster Data Breach

3 5

Organizations that manage personal information must adhere to strict legal standards to prevent unauthorized access to this data.

If you’re a Ticketmaster customer and have been alerted that your data may have been compromised, it’s crucial to understand your rights. Also, if you suspect your data might be at risk and Ticketmaster hasn’t contacted you, you should contact them immediately to address your concerns.

The incident with Ticketmaster demonstrates the risks associated with data breaches, including the possibility of your information being sold on the dark web or used maliciously. It’s vital to remain vigilant for signs of phishing attempts designed to steal more personal information.

To protect yourself, there are several proactive steps you can undertake, including:

  • Please be sure to monitor any credit card accounts linked to Ticketmaster for unusual activity, as these accounts are at a higher risk of being compromised. Also, keep an eye out for any unauthorized transactions. For added security, you might want to request a new credit card number from your issuer.
  • It’s important to update your Ticketmaster account settings by changing the password and enabling two-factor authentication. Additionally, it’s a good idea to set up two-factor authentication for your email account in order to protect your Ticketmaster account and other personal information from scammers.
  • You should also think about enrolling in continuous credit monitoring. This type of service will notify you immediately if there are any attempts to open new accounts in your name. For example, WalletHub provides free around-the-clock monitoring of your TransUnion credit report.
  • Keep an eye on your tickets for upcoming events. Tickets can be quite valuable and are frequently resold online. Check your Ticketmaster account and email for any unexpected ticket transfer notifications.
  • Avoid unsolicited requests for personal information. Unexpected phone calls and emails asking for your personal data may increase. Remember, don’t provide any information if you didn’t initiate the contact.
  • Choose to freeze your credit rather than setting a fraud alert. Freezing your credit reports with Equifax, Experian, and TransUnion prevents fraudulent borrowing. A freeze restricts access to your credit reports, stopping new loans or credit lines from being opened in your name. In contrast, a fraud alert provides less protection.

About TicketMaster

About TicketMaster

Image source

Ticketmaster is a leading ticket distribution company in the United States, specializing in selling tickets for a wide range of live entertainment events, including sports, concerts, family shows, theater, and more. The company operates on a large scale, selling tickets through about 3,300 retail outlets worldwide, 19 telephone call centers, and its website, ticketmaster.com. It serves over 10,000 clients, including venues, artists, and promoters.

In addition to its main operations, Ticketmaster manages TicketWeb, a site that caters to independent venues, and ReserveAmerica, which handles campsite reservations in North America. It also operates several regional ticketing service companies. Ticketmaster is a subsidiary of IAC/InterActiveCorp, owned by media entrepreneur Barry Diller.

Conclusion

The Ticketmaster data breach has affected over 560 million users, exposing personal information and posing significant security risks. The hacking group ShinyHunters is attempting to sell the stolen data, including sensitive customer details, for $500,000. Investigations by the Australian Department of Home Affairs and the FBI are ongoing, highlighting the need for strong cybersecurity measures.

Ticketmaster’s history of security issues and legal challenges further emphasizes the importance of safeguarding customer data. Users should take proactive steps to protect their personal information and remain vigilant against potential data misuse.

PayTech’s RCKT Mobile POS

BNPL Continues to Grow: 25% of Consumers Report Usage

Companies like Affirm, Klarna, Afterpay, and Sezzle have made BNPL increasingly popular, particularly among shoppers looking for more flexibility in paying for purchases. Here is an in-depth analysis of why BNPL continues to grow and surpass more conventional credit card usage to become the second most popular credit payment option, with 25% usage among American customers.

BNPL plans allow shoppers to split the cost of their order into smaller, interest-free installments. Many customers find this payment option appealing since it helps them manage their money better. The fact that these buy now pay later loans do not appear on your credit reports has nothing but fueled the ongoing attraction towards them.

Key Takeaways – Why BNPL Continues to Grow
  • Increasing Usage of BNPL Services: Buy Now Pay Later (BNPL) services are gaining popularity, with 25% of Americans using them in the past year. This trend is especially notable among younger generations and parents, who prefer the flexibility of splitting payments into smaller, interest-free installments.
  • Demographic Preferences: Younger consumers and parents are the primary users of BNPL services. For instance, 40% of Gen Z and 37% of parents with minor children reported using BNPL, compared to lower usage rates among older generations and those without minor children.
  • Upcoming Federal Regulations: Starting in May 2024, BNPL services will be subject to the same federal regulations as credit cards. These regulations aim to provide better consumer protection by addressing merchant disputes, refunds offered, payments suspended during investigations, and disclosure of fees.
  • Economic Context and Credit Card Debt: The rise in BNPL usage comes amidst high levels of credit card debt in the US. With total credit card debt at $1.115 trillion in early 2024 and many cardholders carrying month-to-month balances, consumers seek alternative payment options like BNPL to manage their finances.
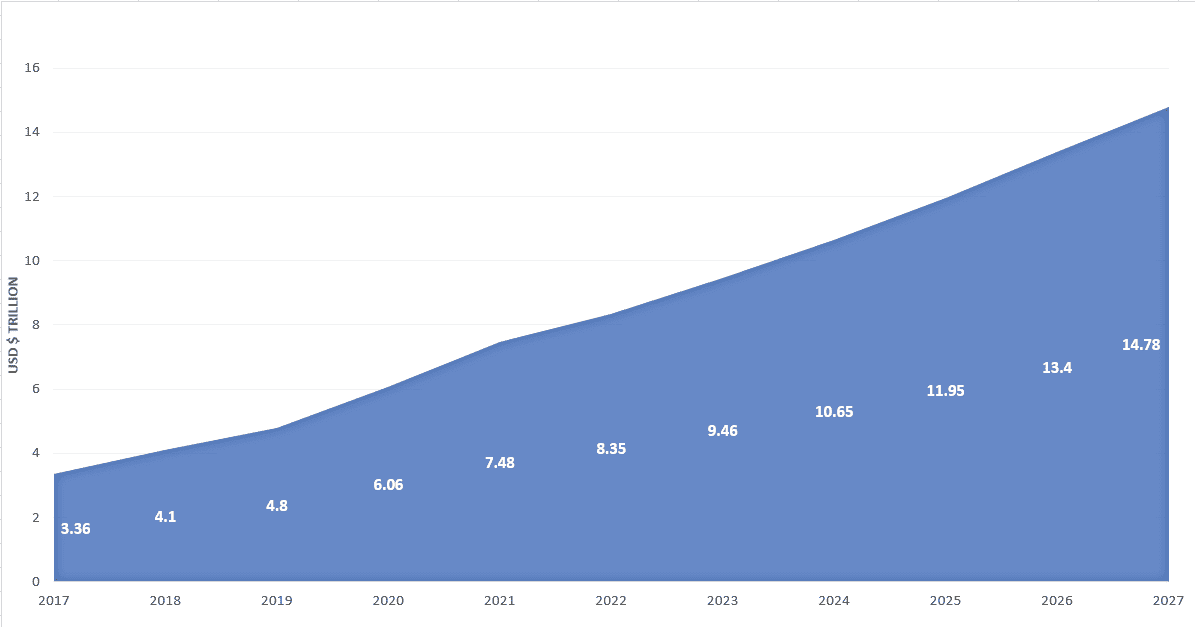
infographics of global bnpl growth year on year

Source: Statista – Global transaction value of buy now, pay later (BNPL) in e-commerce from 2019 to 2021, with forecasts from 2022 to 2026

Growing Popularity and Use of Buy Now, Pay Later (BNPL) Services

Buy Now Pay Later (BNPL) services are relatively new to the credit market, and their popularity is growing quickly. BNPL allows consumers to split a purchase into several smaller installments, usually over four or six months. The application process is quick and easy without requiring a credit check. This is a key benefit for people with poor or no credit. BNPL lenders typically don’t charge interest; they earn money by charging merchants 3% to 6% of the purchase price.

A recent NerdWallet report showed that 25% of Americans used Buy Now Pay Later in the past year, with younger generations and parents being the most frequent users. Meanwhile, 66% of respondents used credit cards during the same period. NerdWallet surveyed 2,061 US adults in early April.

Sara Rathner from NerdWallet agreed that it has unquestionably gained popularity. She explained that BNPL programs often bypass the need for a credit check or application process, simplifying how consumers can start using them.

Further breaking down this, 25% of consumer groups and 37% of parents with minor children reported using BNPL services over the past year, in contrast to 20% of individuals without minor children. Among different age groups, 40% of Gen Z (ages 18-27) and 36% of millennials (ages 28-43) have utilized BNPL services during this period, compared to 20% of Gen X (ages 44-59) and 12% of baby boomers (ages 60-78).

BNPL and Gen Zers infographics about bnpl

Source: Forbes

In the last year, 8% of Americans resorted to BNPL options to cover essential expenses, including groceries and personal care products. Unlike credit cards, which often provide cash back or other rewards, BNPL services usually do not offer these advantages.

Rathner mentioned that as the prices of necessary goods continue to rise, Buy Now Pay Later has become a popular method for covering these expenses. Although this form of credit has been crucial for many, anticipated changes to the payment terms are expected soon.

New Federal Regulations Will Make BNPL More “Consumer-First”

According to the Consumer Financial Protection Bureau’s (CFPB) announcement last month, BNPL companies will be forced to abide by federal regulations covering the use of credit cards in the US beginning in May 2024. Buy Now Pay Later customers will soon have the same federal protections as credit card users.

Under the new legislation, Buy Now Pay Later firms—dominated by fintech businesses like Affirm and Klarna—must investigate merchant disputes, offer refunds for returned goods or canceled services, suspend payments while ongoing, and disclose fees on bills.

Many analysts find that this change is beneficial to consumers. It is a positive step towards providing better protection for consumers who use BNPL services, which have gained significant popularity in recent years. By aligning BNPL firms with the same standards as credit card companies, the CFPB aims to ensure that consumers feel secure and well-informed when using these services.

Klarna also stated in response to the CFPB’s announcement. In it, Klarna indicated that the company already provides its users with the protections mentioned by the CFPB.

Sebastian Siemiatkowski, the CEO and co-founder of Klarna, commented that there may be value in instituting some degree of regulation around the buy-now-pay-later industry. However, he noted that such regulation should be considered in the context of whether these products are ultimately in the best interest of consumers, as compared to traditional credit cards.

New Federal Regulations Will Make BNPL More “Consumer-First”

Credit Card Debt Trends and Challenges in the US in 2024

In the first quarter of 2024, Americans’ total credit card debt amounted to $1.115 trillion, as the Federal Reserve Bank of New York reported. This is a decrease from $1.129 trillion in the final quarter of 2023, which was the highest since the New York Fed began tracking this data in 1999. It’s unlikely that this downward trend will continue throughout the year, considering that over 44% of credit card holders carry balances month to month, a trend that many experts find concerning.

Reducing this debt is challenging. Delinquencies have gone up to their highest level since 2011, and 8% of cardholders surveyed have been in debt for a year or longer. Despite this, the industry views these figures as a retrieval of pre-pandemic norms. Lenders had anticipated an increase in delinquencies, which were kept unusually low during the COVID-19 pandemic by federal stimulus payments. Nonetheless, the issue persists at the individual level.

Credit Card Debt Trends and Challenges in the US in 2024

Low-income households, parents with minor children, and younger consumers are experiencing the most significant financial strain. Approximately 38% of cardholders earning $100,000 annually or more carry a balance, compared to 56% of those earning $50,000 or less.

Parents of minor children are also more likely to have incurred late fees over the past year, with 61% reporting such fees compared to 28% of adults without children. As changes to Buy Now Pay Later (BNPL) arrangements are anticipated shortly, consumers must understand the terms of such financing options fully.

Rathner emphasized the importance of being informed about one’s rights before making any financial commitments.

Conclusion

The popularity of Buy Now Pay Later (BNPL) services continues to rise, offering consumers an alternative to traditional credit cards. With 25% of Americans using Buy Now Pay Later, particularly among younger generations and parents, this payment method has become a significant part of the credit landscape. However, with new federal regulations set to take effect in May 2024, Buy Now Pay Later services will soon have to provide the same consumer protections as credit cards. This regulatory shift aims to enhance transparency and security for users.

As consumer credit evolves, individuals must stay informed about the terms and implications of their payment choices to manage their finances effectively.

1 27

How Can AI Help Improve SEO for Your Website

There was a time when SEO professionals could fill their content with keywords and quickly ascend to the first page of search results. Thankfully, those days are behind us. As search engine algorithms continue to evolve, so do technological advancements. Artificial intelligence (AI) is increasingly prominent in search engine results pages (SERPs). So, how can AI help improve SEO for your website?

Google’s algorithm is continuously improving, and so is consumer discernment. Therefore, you have the power to create content that not only appeals to search engines but also engages audiences. This involves thorough topic and keyword research, analyzing audience data, and crafting content that is both captivating and capable of ranking well.

The good news is that SEO is becoming less monotonous, thanks to the addition of AI tools. The SEO AI sector is rapidly advancing, and your competitors are likely already integrating these innovative tools.

What Is Artificial Intelligence?

What Is Artificial Intelligence?

Artificial intelligence (AI) involves creating computer systems that can perform tasks traditionally requiring human intellect, such as decision-making, pattern recognition, and speech understanding. AI is a broad term that covers various technologies, including machine learning, natural language processing (NLP), and deep learning.

While “AI” is a common term for these technologies, there is some debate about whether they truly constitute artificial intelligence. Some experts suggest that what is often termed AI today is actually sophisticated machine learning, which they consider merely an initial step toward real AI.

Despite philosophical debates about the existence of “true” intelligent machines, the term AI is generally used today to describe technologies powered by machine learning, such as ChatGPT and computer vision. These technologies allow machines to undertake tasks traditionally done by humans, such as generating text or analyzing data.

In the business world, AI has shown that it can increase revenue. More and more businesses are using AI, with a 25% increase in its use each year. It is being used in more parts of businesses than before. Companies that use AI say they make more money in the areas where they use it, and 44% say they spend less because of AI.

Understanding AI SEO

Understanding AI SEO

AI has seamlessly integrated into many aspects of daily life, from fitness and food to shopping and travel, and it is similarly transforming SEO. AI-driven SEO utilizes tools to scrutinize keywords and website performance, guiding strategies to enhance search rankings. AI assesses data, compares competitor pages, and recommends elevating a brand’s online presence.

For instance, Google’s AI-powered RankBrain and BERT (Bidirectional Encoder Representations from Transformers) algorithms are fundamental in shaping search results and optimizing them to be more relevant and accurate. This capability also enables the creation of effective SEO strategies through comprehensive data analysis and interpretation.

Plus, AI assists marketers in identifying emerging keywords and topics, understanding consumer purchasing trends, and efficiently targeting markets.

How Can AI Help Improve SEO for Your Website?

How Can AI Help Improve SEO for Your Website?

AI can help SEO your website in several direct and indirect ways. With AI-powered tools at your back, these tasks will be streamlined and help you be at your best SEO game:

  1. Content Creation

In 2024, creating compelling and high-ranking content will be easier than ever, thanks to advancements in generative AI. This technology involves algorithms capable of producing new content across various digital formats and relies on extensive data training. With minimal input from users, these algorithms can generate fresh content automatically.

AI suggests relevant topics, optimizes headlines, and drafts initial content versions. It evaluates high-performing content across the web to suggest effective strategies that enhance your content’s visibility and ranking.

Prominent examples of generative AI include ChatGPT, Jasper AI, and Writesonic, which are instrumental in refining content to suit different stages of your marketing funnel. The focus of content creation has shifted from merely producing quantity to generating quality content that is genuinely useful to the audience. AI plays a crucial role in achieving this goal by ensuring the relevance and value of the content produced.

  1. Keyword Research

Keyword research can be a tedious and time-consuming process, but AI tools have significantly simplified it by offering features like analysis assistants. These tools evaluate anchor text usage, keyword variations, and semantic search terms, making it easier to:

  • Gain a deeper understanding of your audience.
  • Identify search terms frequently used by your target audience.
  • Increase relevant organic traffic to your website.
  • Customize your content strategy to meet your audience’s needs.

AI-powered tools streamline the three critical phases of keyword research—discovery, analysis, and implementation—by quickly processing vast data sets.

These advanced keyword research tools help pinpoint the most effective keywords for your site by providing rapid insights into keyword relevance, search intent, and competitive dynamics.

Platforms like Semrush enhance keyword research by allowing you to identify keyword opportunities, analyze competitors’ keywords, and compile keyword lists swiftly. Another innovative tool, Twinword Ideas, leverages AI to track search trends and deliver the most effective keywords, reducing the need to sift through extensive keyword lists manually. This AI-driven approach ensures a more targeted and relevant selection of keywords for your strategy.

  1. Content Optimization

Content optimization involves enhancing your current material to maximize its potential for achieving specific goals, such as obtaining high rankings in search engine results pages (SERPs) to attract relevant organic traffic.

It can be frustrating when you have invested significant effort in creating numerous blog posts related to your product, but the traffic levels are stagnant.

One approach could be manually investigating why specific articles aren’t performing well by analyzing Google Analytics data and reviewing your distribution strategies. You might then attempt to improve the content yourself.

Alternatively, you could utilize an AI tool that precisely identifies ways to enhance the quality of your content.

For example, Surfer SEO is a data-driven application that provides insights and analyses to help optimize web content for better search engine visibility. It suggests improvements in natural language processing, content length, keyword density, backlinks, and other crucial on-page elements. Another tool, MarketMuse, leverages AI to support content creators, marketers, and SEO experts in developing high-quality, topic-relevant content.

MarketMuse analyzes the content landscape for specific topics, identifies gaps, and provides actionable recommendations for enhancement. It offers guidance on keyword incorporation, content structuring, and competitive analysis to optimize content effectively.

  1. Voice Search

As internet usage transitioned from desktops to mobile devices, a similar shift is now happening toward voice searches. AI-powered speech recognition technologies utilize NLP to effortlessly convert spoken language into text, thereby reaching a broader audience that might have been inaccessible otherwise.

Consider the way you search for a recipe using traditional text search compared to voice assistants like Siri or Alexa. You might type “orange chicken recipe” into Google, whereas younger users may simply tell their iPhones, “Hey Siri, how to make orange chicken.” These slight variations in phrasing gradually shift search terms from “recipe of orange chicken” to “How can I make orange chicken at home?” As voice-activated searches become more common, voice SEO (VSEO) is becoming an essential element of SEO that can no longer be overlooked.

Voice-to-text and dictation tools are increasingly popular as accessibility options for those who are unable to type. Integrating AI-driven voice search into your SEO strategy can place you ahead of competitors who may still be hesitant to adopt this technology.

For instance, tools like Long Tail Pro are instrumental in identifying long-tail keywords, which are specific phrases with higher conversion rates than shorter, more generic keywords.

Schema markup, or Schema.org, enhances how search engine bots comprehend your content by defining your website’s semantic vocabulary. Voice search is inherently conversational, using AI and NLP principles to better interpret and respond to user inquiries.

AI-enhanced content creation tools like Grammarly can help produce more engaging, conversational content by suggesting tone adjustments and identifying complex passages.

  1. Web Development and Design

Developers frequently employ AI tools to aid in software coding, enabling them to produce high-quality products more efficiently. For instance, Google Vision has assisted developers with image labeling, enhancing the accuracy of Google Image search results by associating textual descriptions with photos and objects.

Even novice web designers can benefit from AI-driven website builders. These tools help integrate keywords into image descriptions, meta descriptions, and other behind-the-scenes content. Platforms like Wix have integrated AI into their editing tools, offering automatic content optimization. This allows users to maximize the value of their existing content effortlessly.

  1. Backlink Analysis

Consistent analysis of backlinks is crucial for enhancing this important ranking factor. How? by identifying potential new, high-quality link sources in your competitors’ backlink profiles.

This process would require extensive online searches for sites linking back to your brand and those of competitors. However, employing AI-powered analytics tools for backlinks or link-building tools can streamline this labor-intensive task.

Utilizing AI for detailed competitive backlink analysis enables businesses to understand their competitors’ backlink strategies deeply. AI-powered tools can reveal competitors’ tactics, pinpoint deficiencies in your link profile, and provide valuable insights to guide more effective and strategic link-building initiatives.

  1. Website UX

User experience (UX) is increasingly central to search engine optimization (SEO), emphasized by Google’s announcement that from 2021 onwards, page experience will be a major ranking factor. Page experience refers to a group of signals that gauge a user’s satisfaction when interacting with a web page, focusing on the content’s value and the overall user experience it provides. This means web pages that fail to deliver a positive UX are less likely to rank well.

In this context, the role of artificial intelligence (AI) is significant. AI helps search engines emulate human-like judgment to assess whether a web page will likely offer a good user experience based on factors like relevance, authority, structure, ease of navigation, loading speed, and mobile compatibility. Suppose a website can offer a personalized and enjoyable user experience. In that case, it increases the time spent on the site and the likelihood of the content being shared, signaling to search engines that the content is valuable and should be ranked higher in search engine results pages (SERPs).

Conclusion

AI has revolutionized SEO by streamlining processes and providing deeper insights into content creation, keyword research, optimization, voice search, web development, and backlink analysis. The advancements in AI tools allow marketers to generate high-quality content, identify effective keywords, enhance on-page elements, and adapt to new search behaviors like voice search.

By leveraging AI, businesses can stay competitive and ensure their SEO strategies are both efficient and effective. As AI continues to evolve, incorporating these technologies into your SEO efforts is crucial for maintaining and improving your website’s search engine rankings.

Frequently Asked Questions

How does AI enhance keyword research and content creation for SEO?

AI streamlines SEO by automating tasks like keyword research and content creation. Tools like Frase and RankIQ analyze large amounts of data quickly, suggest related keywords, and help craft SEO-optimized content, ensuring it meets your audience’s needs.

Can AI improve the speed and performance of my website?

Yes, AI can improve your website’s technical performance. AI algorithms optimize image sizes, manage site code for faster loading times, and predict site downtimes, leading to a smoother user experience and better SEO rankings.

How does AI help with link building and meta-tag optimization?

AI tools like Alli AI automate meta tag generation and link building by analyzing large databases to recommend potential link partners. This saves time and optimizes your website’s SEO elements more effectively.

What role does AI play in voice search optimization?

AI helps tailor content for voice search by making it more conversational and aligned with common voice queries. Tools like Frase can generate content that addresses specific questions and phrases used in voice searches, improving your ranking in these searches.

Top Marketing Books Every Business Owner Should Read

Top Marketing Books Every Business Owner Should Read

Many experts argue that becoming a leader in marketing within your industry depends on creating exceptional and memorable content. Others stress the importance of using data to succeed. A few believe focusing on customer experience is the key to achieving marketing excellence. Each perspective holds some truth. However, your goal is to determine the best combination of these approaches to propel your business forward.

This may seem daunting, but it is entirely achievable if you invest time collecting insights and deciding which strategies to implement. You can start this week by exploring one or more of the recommended marketing books. Each book presents a unique take on marketing and communication in today’s landscape. Remember to take notes as you read—your next breakthrough idea might be a page-turn.

What Are the Best Marketing Books for Business Owners

The top marketing books cover essential topics like consumer behavior, advertising, copywriting, sales, pricing, and branding. These books offer insights into what drives consumer purchases, how to connect with potential customers, and how to generate excitement about your product.

If you’re new to marketing, starting with the basics is wise. The first ten books on the list provided should cover these fundamental areas. As you gain more experience in your marketing career, you should strive to excel in a specific marketing domain—whether it’s SEO, content marketing, advertising, email marketing, or social media.

Being a marketing generalist is valuable, but excelling in an area that particularly interests you can make you more attractive to employers. Now, let’s dive into some of the top marketing books:

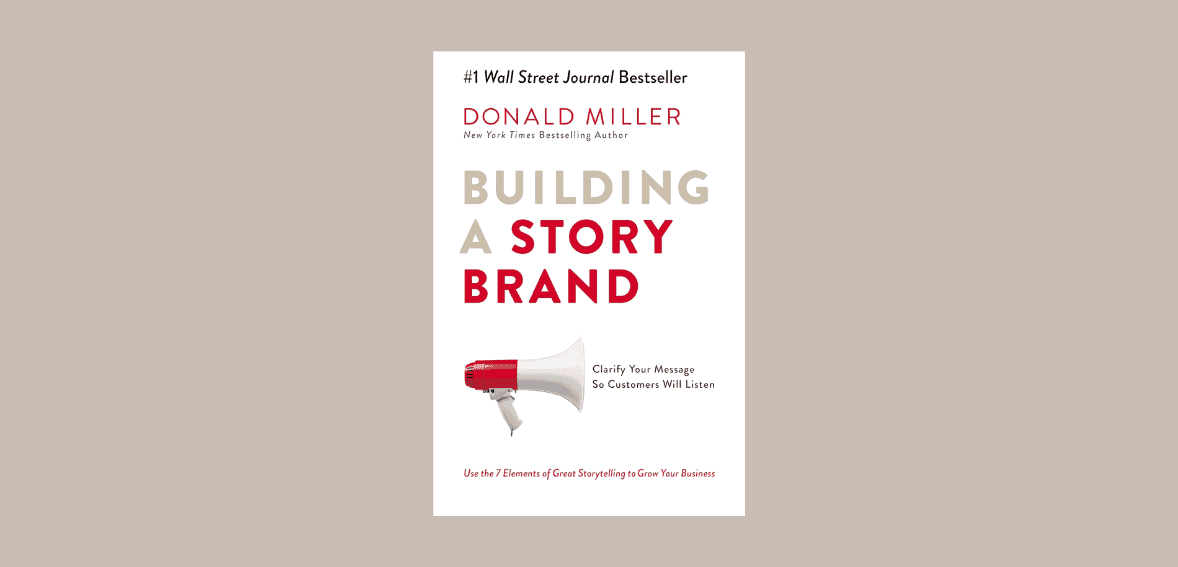
1. Building a StoryBrand: Clarify Your Message so Customers Will Listen

~Donald Miller
Building a StoryBrand: Clarify Your Message so Customers Will Listen

Building a StoryBrand uses timeless storytelling elements to refine brand messaging. Often, marketers bombard potential customers with unnecessary or irrelevant details instead of addressing what the customer actually cares about.

Consider this scenario from Miller’s book: “Imagine your customer is a hitchhiker. You stop to offer a ride, and his only concern is where you’re headed. Instead, as he approaches, you start sharing your mission statement, recounting how your grandfather constructed this car, or raving about your 1980s alternative music playlist. Your passenger isn’t interested in these details.”

The essence of StoryBrand is crafting clear and engaging stories in which the customer is the protagonist or “hero,” and the brand acts as the “guide” to assist them in navigating challenges and reaching their aspirations.

Whether you’re marketing a garage band or a political figure, “Building a StoryBrand” will revolutionize how you communicate your identity, activities, and the distinct value you bring.

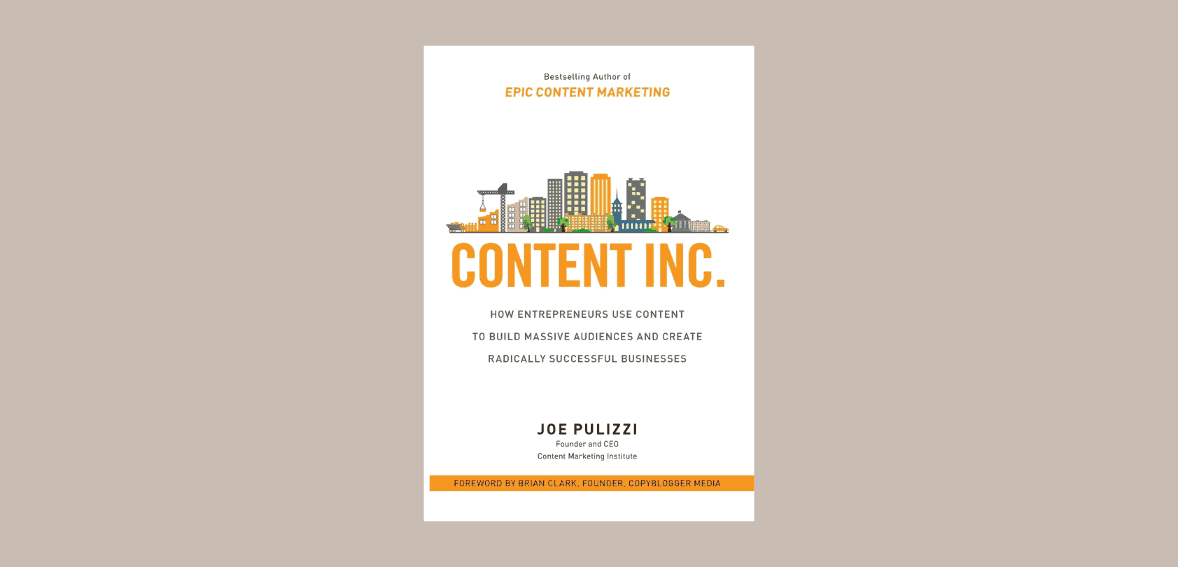
2. Content Inc.: How Entrepreneurs Use Content to Build Massive Audiences and Create Radically Successful Businesses

~Joe Pulizzi
Content Inc.: How Entrepreneurs Use Content to Build Massive Audiences and Create Radically Successful Businesses

Content Inc. offers valuable guidance for new entrepreneurs aiming to cultivate an online target audience. The book outlines effective strategies for creating a business model that attracts future buyers and devises successful SEO tactics.

Additionally, it serves as a resource for entrepreneurs aspiring to become significant industry figures by navigating the online business landscape. Marketing professionals in larger corporations seeking to drive change will also find this book beneficial.

Content Inc. presents practical techniques for building a substantial target audience through content marketing. It is well-organized, and the methods are straightforward to implement.

This book is ideal for startup entrepreneurs who aim to attract new customers, craft impactful content marketing, and offer products that meet their audience’s needs. It provides a roadmap for establishing a base of future buyers before moving on to sales.

3. Renegade Marketing: 12 Steps to Building Unbeatable B2B Brands

~Drew Neisser
Renegade Marketing: 12 Steps to Building Unbeatable B2B Brands

Drew Neisser’s Renegade Marketing offers a groundbreaking approach to marketing. It urges brands to forge genuine customer relationships by embracing risk and innovation. This shift from conventional marketing strategies aims to boost brand growth and customer loyalty.

Drew Neisser, a seasoned strategist and author, brings extensive firsthand experience from his time in business-to-business marketing, including work with major brands like IBM and various start-ups and midsize companies. Through interviews with over four hundred leading marketing professionals, Neisser identified CATS as the traits of successful marketers:

  • Courage,
  • Artistry,
  • Thoughtfulness,
  • Scientific approach.

These traits underpin the strategic framework presented in Renegade Marketing. Neisser has developed a twelve-step formula that dramatically streamlines B2B marketing efforts and helps companies establish a dominant presence in their market.

4. Epic Content Marketing: How to Tell a Different Story, Break through the Clutter, and Win More Customers by Marketing Less

~Joe Pulizzi
Epic Content Marketing: How to Tell a Different Story, Break through the Clutter, and Win More Customers by Marketing Less

Another hit by Pulizzi, Epic Content Marketing, outlines structured approaches and success stories that illustrate how to convert potential customers into actual customers, encouraging them to act while maintaining a respectful approach.
This insightful book highlights how major corporations like Coca-Cola, LEGO, and John Deere have boosted their sales. It acts as a manual for creating and distributing specialized content that attracts and retains customers, ultimately leading to increased profits and growth.

This compelling marketing book introduces a novel concept: it advocates viewing content as part of an overarching series rather than standalone pieces. By developing a sequence of connected content it helps establish a clear, coherent narrative that enhances the impact and effectiveness of the content.

5. Positioning: The Battle for Your Mind

~Al Ries and Jack Trout
Positioning: The Battle for Your Mind

Positioning is celebrated as a seminal work in marketing literature, introducing an innovative method for connecting with an audience overwhelmed by media. The book explores how to craft a distinctive “position” in the minds of potential customers, a strategy that accounts for a company’s strengths and its competitors’ characteristics.

As the pioneering text on communicating with a media-saturated and skeptical public, “Positioning” presents a transformative strategy for establishing a brand’s place in a consumer’s mind, acknowledging both the company’s and its rivals’ strengths and weaknesses.

The book highlights critical principles: the power of clear and simple messaging; the difficulties of altering a brand’s position once established; positioning is defined by the perception it creates in the consumer’s mind rather than the product’s tangible qualities; the role of consistent repetition in reinforcing a brand’s market position; and the necessity of distinguishing a brand through a unique selling proposition (USP).

6. Influence: The Psychology of Persuasion

~Robert B. Cialdini
Influence: The Psychology of Persuasion

Influence, a definitive text on persuasion, unravels the psychology behind why people agree to requests and how to harness this knowledge effectively. Authored by Dr. Robert Cialdini, a leading authority in the fields of influence and persuasion, this book distills thirty-five years of comprehensive, evidence-supported research and a three-year intensive study on behavioral change into a widely praised guide.

In this book, Cialdini delves into the reasons people consent and presents ethical methods for utilizing these insights in both professional and personal settings.

He outlines six key principles crucial for crafting compelling marketing materials. With engaging narratives and practical examples, he simplifies these intricate marketing ideas, making them accessible to a broad audience. The principles laid out in “Influence” are designed to catalyze significant personal transformation and contribute to your overall success. Applying these principles to print campaigns enables marketers to create impactful content that connects with viewers and prompts them to act.

7. Scientific Advertising

~Claude C. Hopkins
Scientific Advertising

Scientific Advertising, published in 1923, is a seminal work in advertising authored by Claude C. Hopkins, recognized as the pioneer of modern advertising methods. This book remains incredibly relevant over a century after its release, proving essential for marketers at any career level.

This title is celebrated for being the first to document critical marketing strategies such as split testing, loyalty programs, and coupon-based tracking. It provides a comprehensive guide to refining advertising efforts through systematic testing and analysis.

The book addresses various advertising topics, from formulating advertising laws to specific tactics like mail-order advertising, crafting effective headlines, understanding consumer psychology, strategic planning, budget management, and exploring advanced topics like negative advertising and testing advertising campaigns.

8. 10x Marketing Formula: Your Blueprint for Creating Competition-Free Content That Stands Out and Gets Results

~Garrett Moon
10x Marketing Formula: Your Blueprint for Creating Competition-Free Content That Stands Out and Gets Results

For inbound and content marketing enthusiasts, the “10x Marketing Formula” is a must-read. This innovative approach comes straight from the insights of Garrett Moon, co-founder of Co-Schedule. Consider exploring an introductory post on the subject to get a feel for the book’s strategies. The premise is simple yet profound: instead of relying on incremental gains, successful marketing strategies often hinge on bold, transformative leaps that can significantly elevate your results.

The book delves into crafting, evaluating, and refining a marketing strategy that is not only predictable but also ambitious. It emphasizes the importance of making daring moves—though they might not always succeed, their success can be transformative for your business.

Much of the book highlights content marketing, a top strategy for scaling SaaS businesses. Moon has rigorously tested these strategies on the CoSchedule blog and extensively addresses social media marketing.

If you’re devising a digital marketing strategy for a SaaS business, this book is a critical read. Despite not always appearing on “best marketing books” lists, its value is undeniable and worth your attention.

9. Hooked: How to Build Habit-Forming Products

~Nir Eyal
Hooked: How to Build Habit-Forming Products

Why do certain products become immensely popular while others fail? What drives our habitual engagement with some products? Is there a recognizable pattern to how technologies become addictive? Nir Eyal addresses these inquiries by introducing the Hook Model—a four-step method ingrained in many successful companies’ offerings to promote consumer behavior subtly.

“Hooked” draws on Eyal’s extensive consulting, research, and hands-on experience. He crafted this book as the practical guide he wished he had during his days as a startup founder, providing not just theories but concrete strategies for creating superior products. This book is tailored for designers, marketers, product managers, startup founders, and anyone interested in how products shape our actions.

The book outlines the Hook Model, which includes four crucial stages: Action, Trigger, Investment, and Variable Reward. Eyal thoroughly explores each component, employing examples from well-known companies like Facebook, Twitter (now X), and Pinterest to show how they engineer products that users continually engage with. He also integrates findings from psychology and behavioral economics to bolster his points, making “Hooked” both actionable and thoroughly researched.

10. Pink Goldfish: Defy Normal, Exploit Imperfection, and Captivate Your Customers

~David J. Rendall and Stan Phelps
Pink Goldfish: Defy Normal, Exploit Imperfection, and Captivate Your Customers

In an overcrowded market, it’s tough for companies to stand out, and genuine differentiation is becoming scarcer. “Pink Goldfish” offers a fresh, seven-part framework based on over 200 case studies for gaining a competitive advantage by leveraging, rather than correcting, imperfections.

The problem with many organizations is that they are simply boring. Even the best products can falter if marketed in a lackluster way. “Pink Goldfish” proposes a seven-step path to distinctiveness, emphasizing the importance of being different.

Embrace the unique aspects of your business and amplify them in a way that’s compelling to customers. This book will change how you view your flaws and can serve as a vital resource for marketing teams looking to foster creativity and break away from the norm. If you’re seeking a guide to inspire innovative thinking within your team, “Pink Goldfish” is the book for you.

11. How Not to Suck at Marketing

~Jeff Perkins
How Not to Suck at Marketing

Clear, straightforward, and enjoyable to read. Whether you’re beginning your marketing career or eyeing executive or C-suite roles, you’ll discover plenty of straightforward advice and insights gained from real-world experience. Marketing as a discipline is expanding in both scope and significance, and Jeff effectively combines strategic marketing insights with actionable advice to excel (i.e., avoid failing).

“How Not to Suck at Marketing” hones in on vital skills needed by today’s marketers. While digital tools provide instant feedback, successful marketing plays a long game. This book guides you through crafting your marketing strategies and advancing your career with practical advice.

Reading “How Not to Suck at Marketing” will equip you to create effective campaigns, inspire your team, and enhance your marketing prowess. It’s time to stop doubting your marketing abilities and start progressing towards becoming a seasoned professional.

12. The Hype Handbook: 12 Indispensable Success Secrets from the World’s Greatest Propagandists, Self-Promoters, Cult Leaders, Mischief Makers, and Boundary Breakers

~Michael F. Schein
The Hype Handbook: 12 Indispensable Success Secrets from the World’s Greatest Propagandists, Self-Promoters, Cult Leaders, Mischief Makers, and Boundary Breakers

With “Hype,” you can harness the power of hype to captivate your audience without overwhelming them. In “The Hype Handbook,” Michael Schein surrounds the strategies used by history’s greatest hype-builders, dissecting their promotional prowess and offering insights into leveraging basic psychology for your own endeavors.

You will learn how shameless propaganda can be used to achieve positive outcomes in social and personal contexts. Influencers have long understood the potency of hype, but mastering the art of hype is essential in today’s world, where persuasion and propaganda hold unprecedented sway.

Michael F. Schein guides you through generating and harnessing hype for noble purposes, whether it’s fostering genuine business success, aiding others, or instigating positive societal change. Learn to identify and implement the twelve key hype-producing strategies outlined in the book to infuse your endeavors with excitement and engagement, regardless of your background or resources.

“The Hype Handbook” equips you with the knowledge and techniques to effectively wield the tools of persuasion, empowering you to achieve personal and professional triumphs.

Conclusion

Mastering marketing involves blending various approaches to create a strategy that drives your business forward. By exploring the recommended books, you can gain valuable insights into content creation, data utilization, customer experience, and more. Each book offers a unique perspective on essential marketing principles, helping you understand and connect with your audience effectively.

Whether you’re new to the field or looking to specialize, these resources provide the knowledge and tools needed to excel in the competitive landscape of modern marketing. Start reading today and discover the ideas that could transform your marketing efforts and lead to significant business growth.

eCommerce ERP : Top 6 Market Leaders

Strategies to Master Your Marketing Funnel

As a business owner or marketer, you know that customers can discover your business through various channels such as advertisements, word of mouth, and digital marketing. But did you know that developing strategies to convert these initial contacts into loyal customers can be challenging? Understanding your customers and mapping out their interactions with your business becomes crucial. This is the key to developing an effective marketing funnel strategy.

By understanding your customers, the marketing funnel becomes a more valuable tool, empowering you to make informed decisions to enhance their experience throughout their journey. In this article, we will discuss the different stages of the marketing funnel and how to construct one. We will also provide you with actionable tactics that can be applied at each stage to optimize engagement and conversion. So, get ready to take your marketing strategies to the next level!

What Is a Marketing Funnel?

What Is a Marketing Funnel?

The marketing funnel serves as a model for visualizing the journey of converting leads into customers from a marketing and sales perspective. The concept likens this process to a funnel, where marketers initially cast a wide net to attract as many leads as possible, then gradually nurture them through the buying process, narrowing the field at each funnel stage.

Ideally, this model would resemble a cylinder, where every lead becomes a customer. However, marketers must make the funnel as cylindrical as possible by maximizing lead conversion. AIDA (Awareness, Interest, Desire, Action) is one of the most common models, but it’s not the only one. Here’s a breakdown of the AIDA model:

  • Awareness – This stage occurs when an individual learns about your brand, product, or service.
  • Interest – At this point, an individual shows interest in your offer.
  • Desire – Also referred to as “Consideration,” this is when an individual evaluates your product or service closely.
  • Action – This final stage, often called “Conversion,” happens when an individual decides to become a customer.
AIDA

Image source: Wikipedia

Different models may have varying numbers of stages, each with distinct names and specific actions taken by both the business and the consumer. The section below will present an overview of the most common and relevant stages, actions, and terms associated with the marketing funnel.

Why Is the Marketing Funnel Important?

The customer journey is a complex progression through the marketing funnel. People might move back and forth between stages, linger in one stage, or behave unpredictably. It would be unfeasible for any marketing team to account for every possible variation in customer behavior.

As such, the marketing funnel provides a simplified customer journey model, offering businesses a framework to refine their marketing strategies. It ensures that marketing efforts are applied effectively at each funnel stage.

Certain stages of your marketing funnel might be overlooked without such a structured approach, leading to gaps where potential customers are lost—often called a “leaky” funnel. For instance, your website might attract significant traffic, but there’s a clear issue if visitors aren’t signing up for your email list. The marketing funnel highlights such problems, guiding you toward solutions.

Here are some advantages of implementing a marketing funnel for your business:

  • Enhance analytics tracking: A marketing funnel facilitates the monitoring and analysis of analytics, allowing you to identify which stages of the customer journey are most effective at driving conversions and which areas need improvement.
  • Simplify the customer journey: By clearly outlining the steps in the customer journey, you make it easier for customers or prospects to take the desired actions.
  • Refine your marketing strategy: With distinct stages defined in your marketing funnel, you can pinpoint and implement adjustments to enhance your overall marketing approach.

Different Marketing Funnel Stages

Different Marketing Funnel Stages

You can break down a marketing funnel into any number of stages you see fit, but typically, most marketers adhere to three key stages:

  • Top of the Funnel (TOFU): Awareness

At this initial stage, the funnel is at its widest, handling the largest volume of leads. Your objective here is to maximize outreach and attract as many people as possible. Offers in inbound marketing at this stage should be free, easily accessible, and primarily educational, such as blog posts, videos, and eBooks.

  • Middle of the Funnel (MOFU): Consideration

In this phase, the funnel narrows as you begin to sift through the initial influx of leads, weeding out those less aligned with your target. The goal is to engage prospects more deeply by providing targeted content that educates them about your offer.

At this stage, a visitor transitions into a potential customer once they seriously consider your proposition. Common MOFU activities include promoting webinars and encouraging the download of case studies, eBooks, whitepapers, and research reports.

  • Bottom of the Funnel (BOFU): Conversion

This final stage of your funnel targets your most qualified leads. Here, you present conversion opportunities that will likely be attractive to them. This stage must be the most persuasive for your online marketing funnel to succeed.

The number of leads decreases at the bottom of the marketing funnel, but their conversion likelihood increases. Approach these leads as if they are on the verge of making a purchase. Common BOFU activities include offering live demos, product trials, vendor comparison charts, and customer testimonials.

Creating a Marketing Funnel: Strategies to Maximize the Results

Creating a Marketing Funnel: Strategies to Maximize the Results

To establish an effective marketing funnel, start by developing a landing page. This initial contact point introduces potential customers to your business. Your landing page should clearly outline your product or service and highlight its benefits to make a strong impression on visitors. Ensure the content here is engaging and convincingly communicates the value of your offering.

Next, collect email addresses from visitors and offer something valuable in return, like a white paper, templates, free access to exclusive content, or discounts and coupons. After acquiring a prospect’s contact information, it’s crucial to maintain communication and provide content tailored to their needs, helping to address any potential objections.

When the nurturing phase has set the stage, move to close the sale. To seal the deal, you can offer incentives such as discount codes, free trials, or product demos. Continue to engage with the customer post-purchase to educate them further about your offerings and strengthen your relationship. Regular interaction fosters customer loyalty.

Finally, constantly refine and improve your marketing funnel. Always be on the lookout for enhancements that can optimize the process.

Here’s how to craft a marketing funnel, customizable to fit your specific needs:

1. Focus on Your Customers

With limited resources, it’s crucial for your team to avoid wasting time and money on digital marketing efforts aimed at individuals who have no interest in your products.

Being customer-centric means truly understanding your customers and forming emotional connections with them. This involves acquiring accurate customer insights and delivering the right information and experiences at the opportune moments.

  • Seek opportunities to craft valuable customer experiences.
  • Leverage customer data to comprehend purchasing behavior, interests, and engagement levels.
  • A customer-centric company designs processes that enhance customer support and enrich experiences throughout their purchase journey.
  • Utilize customer lifetime value metrics to categorize customers according to their behavior.

2. Define Your Goals

As eager as you might be to dive into your digital marketing efforts, it’s important to pace yourself. Begin by gaining a deep understanding of your audience. The next crucial step in your marketing funnel strategy is to clarify what your business aims to achieve.

Converting customers is challenging without clear objectives because they may not understand what you ask them. Setting specific goals at the outset of your digital marketing journey is essential.

Consider your marketing funnel in three segments, from top to bottom, and set objectives for each phase:

  • Top of the Funnel: Aim to increase website traffic.
  • Middle of the Funnel: Focus on enhancing engagement rates.
  • Bottom of the Funnel: Work on improving conversion rates.

While it’s tempting to aim for success in all areas, it’s more effective to select a specific goal for each marketing activity and develop a detailed plan—for instance, targeting a 20% increase in sales by year-end.

3. Implementing Effective Media Strategies at Each Stage

It’s essential to customize your marketing strategies for each specific stage of the funnel. Different parts of the funnel—top, middle, and bottom—require tailored approaches to propel prospects to the next level.

At the top of the funnel, the goal is to maximize reach and brand awareness. Large companies might use television ads, while startups often use cost-effective social media campaigns. As potential customers show interest, it’s crucial to maintain visibility on review sites and search engines during the middle stage of their decision-making process. In the lower funnel, digital retargeting ads and email follow-ups are pivotal to encouraging site engagement.

However, converting sales is just the beginning. Encouraging repeat purchases through email promotions and customer loyalty programs is key. Additionally, motivating customers to leave positive reviews and share their enthusiasm for your brand on social media helps transform them into brand ambassadors. Leveraging positive word-of-mouth is a cost-effective way to acquire new customers compared to expensive top-of-funnel advertising.

4. Create Captivating Content

Your goal is to generate excitement about your brand and products. Consider why customers should be interested in your company and how your products address their needs. These insights will guide your content strategy for this phase.

Also, conduct competitor research. Examine their landing pages, social media presence, and blog posts to understand how they attract prospects. Analyze these elements to identify successful strategies and opportunities for improvement.

Use social listening tools to monitor your competitors’ social media activities. Pay attention to the type of content they post, the engagement levels they achieve, and their overall strategy. Draw inspiration from these findings to enhance your own content strategy. Remember, having a plan is just the start—you also need to know how to capture attention and spark interest.

5. Cultivating Interest and Desire

The AIDA model we discussed above distinguishes between “interest” and “desire,” but practically, they often merge into a single concept.

The key to sparking both interest and desire lies in crafting compelling content. To attract and engage potential customers effectively, ensure your marketing materials deeply resonate with their needs and provide distinct solutions. Start by capturing their attention with educational content such as in-depth blog posts, webinars, or instructional videos that inform them about your offerings. Boost engagement by using reviews and testimonials for social proof and to foster trust. Additionally, employ content targeted with specific middle-of-funnel keywords to position your brand as the ideal solution to their problems.

Once interest is piqued, cultivate it into a robust desire for your products or services. Use powerful storytelling to create a more profound connection, illustrating “before and after” scenarios or customer success stories to demonstrate the clear benefits of your offerings. Clarify your unique selling proposition to differentiate your product from competitors using comparison guides or detailed case studies. Further, enhance the desire to purchase by providing personalized experiences based on the customer’s previous interactions with your brand, making them feel uniquely valued.

6. Capture Leads

Develop strategies to gather contact information from leads, such as email addresses or phone numbers, using techniques like the “give and take” approach. For example, offering gated content in exchange for their details can facilitate further engagement.

Employing effective calls to action (CTAs) throughout your channels is also an excellent method.

When using a call to action (CTA), it’s essential to experiment with different CTAs to see which yields the best results. Consider your audience’s position in the sales funnel when choosing a CTA, and remember to test different wording, colors, and placements to maximize conversion rates.

You can also send them straightforward, actionable emails highlighting how your products or services can resolve their issues. Consider offering additional incentives such as free trials, demo videos, competitor comparison guides, and product samples to nurture leads into becoming paying customers.

7. Maintain Customer Loyalty

Effective marketing goes beyond just attracting customers; it’s equally important to keep them. Acquiring new customers can be up to five times more expensive than retaining current ones, making customer retention a crucial skill to develop.

Plus, your existing customers are about 50% more likely to try your new products, providing an excellent opportunity for you to test different retention strategies. For instance, you might reinforce the value of your product to loyal customers or inform them about new updates and features.

Here are some key strategies to keep those valuable loyal customers engaged:

  • Upselling: Engage with customers post-purchase by offering a similar product at a discount. This communicates that you value their business and can boost your revenue.
  • Encourage User-Generated Content: After a purchase, ask customers via email to share a photo and review of their product. Reward those who do with a discount code for their next purchase. This strategy generates fresh content for your marketing, drives return visits to your site and enhances customer loyalty.
  • Implement a Loyalty Program: Encourage customers to return by offering rewards for repeated purchases. For example, Girlfriend Collective, an apparel brand, has a loyalty program that offers benefits like free shipping and early access to sales based on a customer’s lifetime spend.

8. Monitor and Optimize

It’s crucial to monitor key metrics in any marketing campaign. These include customer engagement, conversion rates, click-through rates, brand awareness, marketing qualified leads, sales qualified leads, and cost per lead. Regularly tracking these metrics allows you to identify successful strategies and areas that need improvement.

Utilize the data and insights you gather to refine your marketing funnel. This might involve adding new content, altering the focus of existing content, or adjusting your automation triggers to achieve optimal results.

Conclusion

Mastering your marketing funnel involves understanding your customers and strategically guiding them from awareness to conversion. By recognizing the different stages—Awareness, Consideration, and Conversion—you can create targeted content and employ specific tactics to engage and nurture leads.

This approach helps convert leads into customers, retains them, and builds loyalty. Regularly analyzing key metrics and optimizing your strategies ensures that your marketing funnel remains effective. By focusing on customer needs and continuously refining your approach, you can maximize the potential of your marketing efforts and achieve sustainable business growth.

Frequently Asked Questions

  1. What are the essential stages of a marketing funnel?

    A marketing funnel includes awareness (learning about your product), interest (seeking more information), desire (wanting your product), and action (making a purchase). After purchase, focus on retention to turn customers into repeat buyers and advocates.

  2. How can I effectively attract customers at the top of the marketing funnel?

    Attract customers at the top of the funnel by creating educational and informative content. Use SEO-optimized blog posts, social media content, and informational videos. Offering free resources like ebooks or webinars can also draw in potential customers.

  3. What strategies work best to convert leads in the middle of the funnel?

    To convert leads in the middle of the funnel, deepen their engagement with targeted email marketing, free trials, and detailed product demos. Personalized content, such as tailored emails and targeted offers, can help move leads closer to purchasing.

  4. How can I improve conversion rates at the bottom of the funnel?

    Strong call-to-actions, customer testimonials, and detailed comparison guides can improve conversion rates at the bottom of the funnel. Your content should also address last-minute objections and streamline the purchasing process to make it easy for customers.

How to Create a Wikipedia Page for Your Business

How to Create a Wikipedia Page for Your Business

Wikipedia is a well-known online resource frequently visited by many to gain information as an information repository. Despite its reputation for sometimes harboring inaccuracies, it remains a valuable platform for readership. In December 2023, it attracted approximately 4.3 billion global visitors. The significant traffic presents substantial business opportunities, which prompts organizations to consider establishing a Wikipedia page for their company. Today, we will explore creating a Wikipedia page for your business through a few simple steps.

Wikipedia Page

What Is Wikipedia?

Wikipedia is a free online encyclopedia that anyone can edit. It was developed collaboratively by a community of users known as Wikipedians. The platform allows registered and unregistered users to modify content, although article creation requires registration. The term “wiki” refers to the server technology that facilitates web content editing directly through a browser.

Co-founded by Jimmy Wales and Larry Sanger in January 2001, Wikipedia began as a supplementary project for Nupedia, a more traditional encyclopedia. Wikipedia quickly expanded, surpassing its predecessor in breadth and depth.

Although Wikipedia operates without overt corporate funding, which might suggest a neutral stance, the open-editing nature allows for personal biases and misinformation to seep into articles. Despite efforts by administrators to verify and cite accurate sources, not all inaccuracies are caught. This has led to caution against using Wikipedia as a definitive source in academic and professional contexts due to potential reliability issues.

How Can Your Business Benefit from Wikipedia?

How Can Your Business Benefit from Wikipedia?

Other than the fact that Wikipedia is a completely free source of marketing, here are some other ways how your business can benefit from it:

  • Control Over Your Brand Narrative:

Creating and managing a Wikipedia page for your business allows you to shape the narrative surrounding your brand. You can portray your business in a favorable light, showcasing its achievements and providing a detailed account of its history and offerings.

Working with a reputation management company can help ensure that your Wikipedia page’s content is compelling and accurate.

  • Building Trust:

Trust is a critical factor in any business’s success. A presence on Wikipedia can enhance your brand’s credibility with your audience.

Although Wikipedia is not always suitable for scholarly purposes, it is regarded as a relatively trustworthy source for general information. Featuring your business on Wikipedia signals to customers and stakeholders that your brand is reputable.

  • Search Engine Visibility:

Wikipedia pages often appear near the top of search engine results on platforms like Google, enhancing the online presence of your business. By collaborating with a reputation management firm, you can optimize your Wikipedia page for search engines to ensure it ranks highly for pertinent keywords.

  • Value of Backlinks:

Backlinks from Wikipedia are highly advantageous for businesses, enhancing a website’s credibility, visibility, and organic traffic. As the fifth-most visited website globally with a domain authority score of 100—the highest achievable—links from Wikipedia are highly esteemed and can elevate your site’s reputation.

You should look for relevant Wikipedia articles that contain broken links or lack citations and offer links from your website to address these gaps. Strategically placing relevant links can not only secure valuable backlinks but also increase traffic to your site.

Opportunity for Organic Brand Awareness:

As previously mentioned, Wikipedia ranks highly in Google search results, often appearing as a primary source of information. Consequently, a Wikipedia page about your brand typically appears at the forefront of relevant searches and may even be featured in the Google Knowledge Graph panel at the top-right corner of search pages.

This visibility provides current and prospective customers, as well as potential investors, with easy access to well-structured and credible information about your brand. This exposure is often more influential and convincing than sponsored ad links to your website.

8 Easy Steps to Create a Wikipedia Page in 2024

Before you begin creating a Wikipedia page for your business, it’s crucial to ensure that your business meets Wikipedia’s notability criteria.

Wikipedia requires that organizations or products be notable, which means there must be verifiable evidence that they have been recognized by reliable sources that are independent of the organization or product itself.

To be eligible for a Wikipedia page, your business needs to be substantiated by substantial, independent, and credible sources. Once you have established that your business qualifies, you can proceed with the following steps:

Step 1: Create an Account

image 11

Before you begin creating pages, having a registered account on Wikipedia is essential. This is advisable as it prevents your IP address from being publicly visible in the edit history. If Wikipedia detects any inappropriate edits from an unregistered user, they might block the associated IP address.

A registered account not only adds to your credibility but also helps build trust with the website, which is crucial for the sustainability of your page. With an account, you gain access to a personal user page where you can post a brief biography and photos and a talk page that allows you to interact with other Wikipedia users.

To create an account, visit the Wikipedia homepage and click on “Create account” at the top right corner. Fill in the required fields with your username and password, then click “Create your account” to complete the registration process.

Step 2. Contribute to Existing Pages

The next step would typically involve creating your new page using Wikipedia’s Article for Creation (AfC) submission template. This template simplifies the formatting and submission process. However, due to manual reviews, each submission has a three-month waiting period.

An effective way to expedite this process is to establish yourself as a credible contributor by actively editing existing articles. This helps you become an autoconfirmed user and demonstrates your familiarity with Wikipedia’s editing standards and practices. Gaining a reputation as a knowledgeable and trustworthy contributor is crucial for the eventual acceptance of your page.

Starting by editing existing articles is advisable. This approach allows you to showcase your reliability and expertise, facilitating your promotion to an autoconfirmed user. This status grants you the ability to edit pages without immediate review or approval.

Typically, user accounts on the English Wikipedia that are at least four days old and have made a minimum of 10 edits (including any that have been deleted) achieve autoconfirmed status. Engaging with existing pages before submitting your company page can be highly advantageous, as it often eliminates the lengthy wait for manual review of new articles.

Therefore, take your time and contribute thoughtfully to the Wikipedia community. Once you attain the necessary status, you can create your company page.

Contribute to Existing Pages

Step 3. Research

Thorough research is important before you start writing your Wikipedia page. Begin by exploring existing Wikipedia content related to your brand and industry. Use the search feature on Wikipedia to look up relevant industry keywords, your competitors, and your brand name to see if there are existing pages where your brand could be mentioned.

Then, gather a list of references, including publications, articles, and mentions of your brand, as these will be necessary to cite as sources on your page. Also, examine the pages of your competitors for valuable insights. They include details such as the brand’s history, product lineup, founding date, revenue figures, service areas, and trademarks. This information will help you structure your page.

If a page about your brand already exists, consider enhancing it with additional information. Use the search bar to navigate and find any related content that might influence your page creation or updates.

Step 4. Create an Outline

After collecting sufficient information about your company, begin structuring the outline for your text. Start by providing a basic introduction, which should include a history of your company and an overview of the products or services offered.

Organize your information into clear, manageable sections. These should be easily navigable through a table of contents on every site page.

Proceed to elaborate on your products or services in greater detail. Ensure your descriptions are thorough and informative, maintaining a neutral and objective tone. Remember, a Wikipedia page is intended for information, not promotion. Lastly, ensure that reliable sources can support all content on your Wikipedia page. Avoid including any information that cannot be substantiated with citations.

Step 5. Draft Your Page

When creating your Wikipedia page, using a style that differs from standard blogs or articles is crucial. Reflect on the Wikipedia pages you have read and aim to replicate their structure by following fundamental principles:

  • Neutrality: Maintain a neutral tone throughout your page, focusing on factual information rather than emotional expressions.
  • Simplicity: Use clear, straightforward sentences and avoid complex jargon to make your content accessible.
  • Originality: Interpret and rephrase information from your sources instead of copying it directly, maintaining the uniqueness of your content.
  • Verifiability: Support all your claims with citations from reliable sources, demonstrating the credibility of your information.
  • Objectivity: Avoid biased language and promotional content to ensure the text remains unbiased and factual.

Taking these steps seriously is crucial, as promotional content and lack of notability are common reasons for rejection. Review your draft with an unbiased third person (your employee may also have a biased view) for a fresh perspective and further refinement.

Step 6. Create Your Page

After writing your page and having it reviewed, proceed to Wikipedia’s “Writing an article” section. You will find a blue button labeled “Article wizard: an easy way to create articles.”

You will then be taken to Wikipedia’s Article Wizard. Here, you can start building your page immediately by clicking “Next” or practicing editing in Wikipedia’s sandbox first.

Click on “Next.”

You can include as much detail as you deem necessary. Remember, using citations is critical to the credibility of your page. Citations help establish trust in the information you present, so ensure you use reliable sources to substantiate your claims.

Step 7: Submit Your Page

Once you have completed all the necessary steps, you are ready to submit your company’s Wikipedia page. After submission, you must wait for Wikipedia’s review process.

This process can take several months and may require multiple attempts before successful completion. A volunteer reviewer will examine your draft and decide whether to move it to the main article space. If the article requires further improvements, you will receive feedback on how to enhance it. Keep in mind that reviews may take time since all Wikipedia editors are volunteers.

Step 8: Maintaining Your Wikipedia Page

Publishing your page is just the beginning. To ensure your page remains relevant and accurate, update it as your company progresses.

Again, anyone can edit Wikipedia pages. While the site generally ensures that edits are appropriate, some inaccuracies can slip through, particularly for smaller businesses.

Make it a habit to check your Wikipedia page every few months to ensure its accuracy and add any new mentions or publications. This will help keep Wikipedia reliable and ensure your brand is presented accurately and positively.

Conclusion

Creating a Wikipedia page for your business offers valuable opportunities to enhance your online presence, build trust, and increase visibility in search engine results. By following the steps outlined, from ensuring notability to maintaining the page, you can effectively establish and manage your brand’s narrative on this influential platform.

Regular updates and active participation in the Wikipedia community are essential to keeping your page accurate and relevant. Although the process may be time-consuming, the potential benefits, such as improved search engine rankings and increased credibility, make it a worthwhile investment for your business.

Frequently Asked Questions

  1. How do I start the process of creating a Wikipedia page for my business?

    First, create a Wikipedia user account by visiting the Wikipedia homepage and following the instructions. To get more editing privileges, aim to become an u0022autoconfirmed useru0022 by making several edits and having an account for a few days.

  2. What are the key guidelines I should follow when creating a Wikipedia page for my business?

    Ensure your business meets Wikipedia’s notability guidelines by having significant coverage in reliable, independent sources. All information must be verifiable and properly cited. Use neutral language and follow Wikipedia’s style and citation guidelines.

  3. How do I submit and get my Wikipedia page approved?

    Submit your drafted page through Wikipedia’s u0022Article Wizard,u0022 which helps ensure your draft meets standards. Your submission will then undergo a review process, which can take a few weeks to several months.

  4. What should I do after my Wikipedia page is published?

    Keep your page accurate and up-to-date with new business developments. Engage with the Wikipedia community by responding to comments and suggestions on the talk pages to maintain credibility and factual accuracy.