Block Inc

Buy Now, Pay Later Meets Digital Banking as Block Expands Afterpay and Cash App Pay

Think about the last thing you bought online. There’s a good chance you didn’t pay all at once. Maybe you split it into four. Maybe you tapped a balance instead of a credit card. That small shift at checkout is now a multibillion-dollar habit. And one company is moving fast to own both ends of it.

Block Inc, the company that owns Cash App, Square, and Afterpay, is integrating its payment solutions. This creates a unified, expanding network that gives Afterpay and Cash App Pay merchants access to tens of millions of customers. This illustrates the direction of payment solutions in retail. Buy now, pay later is moving out of the periphery and is integrating with the banking ecosystem.

Here’s what Block is building, why merchants keep signing up, and what it all means for shoppers and small business owners in 2026.

What Block Inc Just Did
AfterPay

Image Source

In March 2025, Cash App integrated Afterpay’s pay-over-time solutions to hundreds of thousands of partner merchants. Cash App Afterpay, which comes with a new checkout logo, represents a unified branding effort of the two companies. Starting with Pay-in-4, the traditional four-part (interest-free) installment split, Cash App users can use this feature on their Cash App. The Pay Monthly feature, which allows for longer payment terms for large purchases, is coming next.

Block’s acquisition of Afterpay makes considerable sense. There are approximately 57 million Cash App users each month. Afterpay provides flexible payment options and partnerships with retailers for installment purchases. Cash App and Afterpay together form a significant alternative payments network in the U.S. Afterpay co-founder and Block’s head of global sales, Nick Molnar, explained that this allows merchants to access a much larger market, while consumers can access modern payment options beyond traditional credit systems.

From 2023 to 2026, the list of merchants using Cash App continued to expand, with the addition of companies such as Instacart, Fubo, and Lime, as well as many other retail and apparel brands. The pitch to sellers is that Afterpay and Cash App Pay meet different shopper needs. By offering both, sellers can meet consumers’ needs at more stages of the buying journey. This phrasing is thanks to Tanuj Parikh, who leads revenue for Afterpay and Cash App. For more information about the newly added partners, check out PYMNTS’ latest coverage of the merchant expansion.

From a Transfer App to Your Main Bank
Buy now pay later

This is where buy now, pay later merges with digital banking. Cash App has provided consumers the ability to quickly transfer cash to settle a dinner bill or send rent to a roommate. Block aims much higher. According to analysts, the internal objective is “banking primacy” — being the account into which your salary is deposited.

The data indicate improvement. Block capped the most recent quarter with 9.7 million Primary Banking Actives, up 18% from last year. A Cash App account becomes a Primary Banking Active when it receives a direct deposit or an account holder engages in at least $500 worth of monthly transactions across the Cash App ecosystem, including Cash App Card, Cash App Pay, and Afterpay. Under that definition, spending through Cash App’s buy now, pay later (BNPL) service can be enough to count you as a Primary Banking Active.

Layered on top of a foundation already bolstered by a real bank, Block’s offerings include Cash App Green, a younger-skewing status program with a much lower average member age (34 years) compared to a median age above 50 for traditional U.S. banking customers. Other offerings include managed accounts for children, teenage savings accounts, a Bitcoin Lightning network, and peer-to-peer stablecoin transfers planned for 2026. Block co-founder and CEO Jack Dorsey envisions a future Cash App that serves as a financial “protector,” proactively tracking and alerting customers to risks posed by incoming and outgoing transactions.

Sitting below is a chartered financial institution. Square Financial Services is Block’s industrial bank that facilitates much of its lending. And lending is on the rise. In the most recent quarter, consumer lending origination volume grew 82% year over year. Additionally, Cash App Borrow, a product that offers short-term loans, grew an impressive 175% year over year. Afterpay’s post-purchase lending is said to be surpassing the early trajectory of Block’s lending product.

FIGURE 1 — THE BLOCK MONEY STACK

LayerWhat happensWhy it matters to Block
Send & receive (P2P)The original Cash App habitBrings users in and builds daily trust
Spend & splitCash App Pay + Afterpay at checkoutPay now, or pay in 4 / pay monthly
BankDeposits, card, savings, Cash App GreenTurns users into Primary Banking Actives
LendBorrow + Afterpay creditThe highest-margin layer of the stack

Each layer down the stack is more valuable to Block. BNPL is the bridge from spending into banking and credit.

Why Merchants Keep Signing On
Why Merchants Keep Signing On

Integrating a payment button onto a retail platform can be burdensome. So why are merchants integrating Afterpay and Cash App Pay at such an accelerated rate? The simple answer is reach and conversion. Cash App users are more likely to complete a purchase because they trust Cash App as a payment method. Moreover, Cash App Pay serves as a familiar payment method. In addition, Cash App Pay, paired with BNPL (Buy Now, Pay Later), has a significant and established impact on cart behavior.

The 2026 wave brought a mix of categories, from grocery delivery to eyewear to sportswear. The spread matters. It shows BNPL moving past fashion into everyday spending. The table below groups some of the recently added partners by sector.

TABLE 1 — SELECTED MERCHANTS ADDED TO THE AFTERPAY / CASH APP PAY NETWORK (2025–2026)

CategoryExample merchantsWhy it matters
Everyday & deliveryInstacart, LimeBNPL stretches into groceries and mobility, not just splurges
Streaming & mediaFuboSubscriptions and services join the installment world
Eyewear & accessoriesGlassesUSA, JaxxonMid-ticket items that benefit from a split-pay nudge
Apparel & lifestyleMonday Swimwear, WeWoreWhat, Kat The LabelThe fashion core where Afterpay first grew up
Sports & audioRally House, Shokz, REDVANLYHigher average order values, ideal for Pay Monthly
Family & milestonesNanit, Herff JonesPlanned, larger purchases that suit installments

Every new logo expands the network in both directions. An increase in merchants means more places for Cash App users to spend their money. An increase in users means a larger potential customer base for the next merchant. That flywheel is the entire goal.

Buy Now Pay Later Retail 2026: The Demand Is Real

None of this would matter if shoppers weren’t asking for it. But they are requesting it. Among younger generations who generally distrust traditional credit, the trend toward buy now, pay later retail has become a permanent fixture as a new payment method.

By 2026, approximately 50% of adults in the U.S. have tried some form of buy now pay later (BNPL). The trend is also evident in holiday spending, where shoppers spent $20 billion on BNPL during the 2025 holiday season, up 9.8% from the previous year. Electronics and furniture are among the leading categories. The figures below summarize the headline numbers with some supporting information.

FIGURE 2 — BNPL RETAIL 2026, BY THE NUMBERS

~50%of U.S. adults have used buy now, pay later at least once
20–30%typical lift in checkout conversion when BNPL is offered
15–40%reported rise in average order value with BNPL
~40%of BNPL sales can come from shoppers new to the retailer
$20.0BU.S. BNPL spend over the 2025 holiday season (+9.8% YoY)
96M+projected U.S. BNPL users in 2026

Figures aggregated from industry research; ranges reflect variations across providers and categories.

The takeaway for retailers is blunt. Offering installments tends to boost conversion, increase basket size, and attract first-time buyers. For a full breakdown of usage and category data, Capital One Shopping’s BNPL research is a useful reference point.

How Cash App Pay Checkout Actually Works

It is beneficial to differentiate between the two tools, as they serve different functions. The term people search—Cash App Pay Checkout—generally means the payment is done in full from the Cash App balance, while Afterpay refers to the pay-over-time service. Block now provides them together, so merchants can serve both types of shoppers in a single integration.

At the online checkout, Cash App Pay allows shoppers to select a payment option, after which the payment is confirmed in the app or by scanning a code, and funds are cleared from Cash App or a linked source. Afterpay, on the other hand, lets the shopper split the cost into four interest-free installments or opt for the Pay Monthly plan to spread a larger purchase over several months. In both cases, the merchant is paid upfront. These payment services offer a user-friendly comparison at first glance.

TABLE 2 — CASH APP PAY VS. AFTERPAY AT CHECKOUT

FeatureCash App PayAfterpay
What it doesPay in full, instantlySplit into installments
Best forQuick, lower-friction mobile paymentsMid- to higher-ticket purchases
Shopper costNo installment planInterest-free Pay-in-4; fees can apply to Pay Monthly or late payments
Merchant payoutReceives funds for the salePaid up front; Afterpay carries repayment risk
Core appealSpeed and Cash App familiarityAffordability and bigger baskets

Offering both is the selling point. A shopper who balks at paying $180 at once might happily split it. Another just wants to tap and go. Covering both reduces the moment of hesitation that kills online sales.

Should Small Businesses Offer BNPL?

This is a practical consideration for owners reading the news. Should small businesses offer BNPL in 2026? The truth is: it depends on your margins, average order values, and your demographics. BNPL is not free for the business. Providers charge a fee for each transaction, often a percentage plus a fixed amount, which is usually higher than traditional card rates. The expense is charged for the conversion lift.

For some stores, the decision is simple. If you sell items in the $75-$500 range to younger shoppers, then the option to pay in installments can turn a browser into a buyer and lift the average order value. Small to medium enterprises (SMEs) generally see higher cart conversion rates. For tight-margin, low-value, or older-customer businesses, the fee may outweigh the benefit. The table presents the trade-offs.

TABLE 3 — THE MERCHANT TRADE-OFF ON BNPL

UpsideCost or caveat
Higher checkout conversion, fewer abandoned cartsPer-transaction fees usually exceed standard card rates
Larger average order valuesReturns can be higher in some categories like fashion
Access to younger, BNPL-first shoppersAdds another payment flow to manage and reconcile
You get paid up front; the provider carries repayment riskReliance on a third party’s brand and policies
Network reach (e.g., Cash App’s user base)Customer support and disputes may route through the provider

A reasonable approach is to test rather than commit blindly. Turn it on, watch your conversion and return rates for a quarter, and compare the fee against the incremental revenue. If the lift is real for your store, keep it. If not, the fee is just a cost. Treat BNPL like any other channel: measure it.

The Catch: Debt, Defaults, and Regulators

When spending and lending occur in the same app, buying and borrowing become indistinct. While this is beneficial to Block’s revenue, it poses financial risks to consumers and to the company’s loan book.

The data shows the early warning signs. Buy Now, Pay Later (BNPL) plans show low default rates, but a significant number of consumers miss payments at least once. This is frequently reported to be between 30% and 40% in surveys. It is also common for consumers to have multiple BNPL loans, making payment oversight difficult. This is referred to as “loan stacking.”

This has not gone unnoticed by regulators. In the U.S., the Consumer Financial Protection Bureau has been particularly focused on BNPL plans and their relationship with traditional credit cards. As this market segment develops, new regulations could bring increased transparency and new consumer rights, especially regarding payment disputes. For Block, focusing on lending to gig workers and those with inconsistent incomes raises significant concerns. What will be the impact on loss rates when the economy experiences a downturn? There is significant financial incentive to pursue this lending. The credit risk is the financial cost.

What This Means Going Forward

With a broader view, Block’s strategy is easy to understand. Each payment creates a loop. Cash App customers will not only be paying customers but also be incentivized to continue spending and engage in recurring transactions through Cash App. Block’s Cash App strategy is to keep customers on the ‘Cash App’ loop by offering features and controlling the lending margin.

For users, the incentive to use the Pay in 4 feature is its improved ease of use. This feature does come with risk, as it may drive users to a negative financial position. The appropriate way to use Pay-in-4 is to treat it as a loan, which may be necessary to discourage users from spending beyond their financial limits.

For small business owners, the decision to use the Pay-in-4 feature is much more clear-cut. Pay-in-4 can drive growth for your small business, assuming your product and consumer base are a good fit. However, Pay-in-4 can also add an unnecessary layer of expense to your business. You should evaluate the Pay-in-4 feature based on your own business metrics, rather than on what Block says in its marketing.

Either way, the direction is set. Buy now, pay later and digital banking are merging into one experience, and Block is determined to be the company that owns it. The checkout button you tap in 2026 may turn out to be a bank in disguise. You can follow the source announcements directly through Block’s investor newsroom.

Frequently Asked Questions

  1. What is the difference between Cash App Pay and Afterpay?

    You can now make full payments directly from your Cash App balance with Cash App Pay. Afterpay allows customers to make partial payments via interest-free installments, as well as via the Pay Monthly plan. Block now offers both services so that retailers can cater to your purchasing preferences, whether you want to pay in full immediately or prefer to pay in installments.

  2. Which merchants accept Afterpay and Cash App Pay?

    The network connects millions of merchants. Recent additions include Instacart, Fubo, Lime, GlassesUSA, Shokz, Rally House, Monday Swimwear, Nanit, among others. The list continues to expand as Block enhances its commerce suite offerings.

  3. Should a small business offer BNPL in 2026?

    Younger shoppers are likely to respond better to this solution, and it can increase order value and improve conversion for mid-ticket items. Unfortunately, it is likely that this solution will be more costly than it benefits your store. Providers charge high, per-transaction fees which often exceed card rates. You will need to run a test, measure the performance lift relative to the fees, and keep the solution only if the numbers work for your store.

  4. Is buy now, pay later risky for shoppers?

    Although default rates are low, many users have reported missed payments, and loan stacking is prevalent. BNPL is still a form of lending. Only use this for splittable purchases you are comfortable paying in full, and be mindful of the number of active plans.
Fifth Third

Fifth Third is closing 81 branches. Here’s the business-customer checklist.

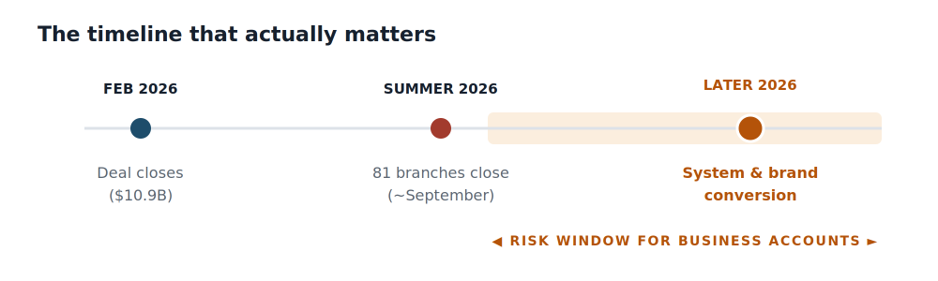
On June 3, 2026, branch-closure filings with the Office of the Comptroller of the Currency surfaced — first reported by Banking Dive — confirming that Fifth Third will shut 81 branches this summer as it digests Comerica. The $10.9 billion all-stock acquisition closed in February 2026, creating the ninth-largest bank in the country with roughly $294 billion in assets. CEO Tim Spence has framed the deal around about $850 million in targeted cost savings — and branch consolidation is where a good chunk of that math gets done.

The bank’s public framing is reassuring and mostly accurate: it is consolidating overlapping locations, and most branches being closed have another Fifth Third within a mile. That answers a consumer’s question — where do I deposit a check now? It does not answer a business owner’s question: whether payroll runs and vendor payments clear without interruption when two banks’ systems are stitched into one. For a small business, the branch closing is the headline; the account conversion behind it is the event that can actually cost you money.

What’s closing, and when

Fifth Third branch closure

The closures are heavily concentrated in Michigan, where the two banks’ footprints overlapped most. Per the OCC filings reported by Banking Dive and the Detroit News, the 75 Michigan closures break down to 55 former Comerica branches and 20 existing Fifth Third sites, with the remaining six spread across Florida (four), California (one), and Texas (one).

Source: OCC branch-action filings, via Banking Dive & the Detroit News (June 2026).

DETAILFIGURE
Total branches closing81
Originally Comerica locations59
In Michigan (55 ex-Comerica + 20 Fifth Third)75
Florida / California / Texas4 / 1 / 1
Closures with another Fifth Third within a mileMost
Branch closuresThis summer (reported ~September)
Full system & brand conversionLater this year

Despite the layoffs, Fifth Third’s Michigan net position continues to grow as it incorporates Comerica’s network alongside its own. The bank plans to have 227 financial centers across 39 Michigan counties post-acquisition, with 116 in the five-county Metro Detroit area and 19 in the City of Detroit.

Fifth Third Bank claims its acquisition will provide the City of Detroit with the largest available banking network. While the claim itself is positive, the optimism is tempered by the fact that there will be branch closures during the summer (most are expected to close during September) and the systems and brand conversion will not happen until “later this year.”

Some predict the conversion of customers to Fifth Third Bank to happen the weekend of Labor Day. Nonetheless, the time between “my branch closed” and “my bank accounts closed” will be useful for business owners.

Why this conversion carries more risk than a routine one

Why this conversion carries more risk than a routine one

Most account conversions are standard, but there are two reasons this account conversion deserves special consideration. First, when you take the integration of Comerica’s commercial banking division into Fifth Third’s Division, this has become one of the more significant regional bank conversions in recent years. If you’re talking about the size of the job, that’s the area where you will find exceptions. Second, and of greater interest to the business customer, the back office handling the migration is also being closed on the same schedule.

Fifth Third has submitted a state WARN notice announcing the permanent layoff of 502 workers at Comerica’s former Great Lakes Campus in Farmington Hills. The layoffs will occur in phases from July to November of 2026. These layoffs will follow those at Comerica’s Texas locations, bringing the total to over 740 employees. The layoffs won’t stop your payroll from running on their own.

The subtler risk is that the staff who best understand Comerica’s commercial accounts are among those leaving — on the same schedule as the migration itself. The most logical and safest approach would be to build your own safety net rather than to assume the bank’s safety net will be adequate.

The conversion window is the real risk — not the branch distance

“Another branch within a mile” is a geographic term. A business doesn’t run on geography; it runs on the account identity to which everything is wired. When Comerica accounts migrate onto Fifth Third’s systems during the conversion later this year, the pieces that depend on that identity are the ones that can break. Here is the chain that must survive the cutover, roughly ordered by the damage a failure would cause.

Routing and account numbers

Changes to your account numbers will have a ripple effect on your transactions. Write to your bank and ask if the account and routing numbers for your former Comerica bank account will change. Be aware that some Comerica bank accounts were reassigned while others were retained. The answer to your inquiry will tell you how much of this list will pertain to you.

ACH origination — the file that pays everyone

If your business originates ACH payments — vendor disbursements, tax payments, customer debits — those origination files reference your originating account and routing. A single stale field, such as the immediate origin or the company/batch header, can bounce an entire batch, and ACH returns can take days to surface. Once you have the new credentials, send a small test file before you push a full payroll or vendor run through it.

Payroll batches and recurring debits

While it is true that no area of accounting can be allowed to make mistakes, payroll is the most critical to get right. Whether payroll is processed in-house or through an external provider, the funding account that is provided must match the converted account.

If payroll is processed by a third party, be it Gusto, ADP, or Paychex, the funding account must be updated in the third party’s portal, not the bank’s. A pre-note must be confirmed to clear prior to the next scheduled pay date. The same principle applies to recurring debits and to autopay setups that are initiated by the customer.

Bill pay payees and merchant settlement

Be prepared to re-enter payees, as saved bill-pay payees do not always migrate correctly. On the card side, your processor makes settlements to a deposit account using the routing and account numbers. If these change and no one addresses them, a day or two of card batches may remain unsettled. If your processor is the bank, a conversion may involve card-processing re-boarding, new terminals, and a new gateway, with card-on-file tokens re-vaulted.

image

The branch closing is the visible event. The conversion is the quiet one — and it’s where ACH, payroll, and settlement instructions are most exposed.

Cash-heavy businesses: the logistics question

Cash-heavy businesses

If you run cash, a branch closure isn’t just an inconvenience — it changes your deposit logistics. A location that closes this summer may have been your deposit drop, and the replacement may not sit on your route.

Three factors influence what a bank should do. The first factor is distance. If your closest branch is 20 minutes away, daily deposit runs take staff time and increase the likelihood that cash sits on-site overnight. The second factor is volume. Once you’re depositing more than a few thousand dollars per day, an intelligent safe that provisionally credits your account, or a remote deposit capture for checks, generally reduces the trips to the bank.

The final factor is the quote for the armored pickup. A route that may have worked for your bank’s location in the past may not work for your bank’s location in the present, as transport companies quote based on stop frequency and distance. Get a quote before the branch closes, rather than after, so that you won’t have to consider the quote during the time the branch is closed.

The checklist: 10 things to verify before conversion day

Once you have a conversion date, run this list against your accounts. The goal is simple: when the systems flip, nothing that touches money should reference stale account information.

#VERIFYWHY IT MATTERS
1Routing & account numbers post-conversionThe detail everything else depends on
2ACH origination ID & settlement accountStops rejected vendor/tax batches
3Payroll funding accountThe one you cannot afford to miss
4Recurring debits you originateSubscriptions and customer autopay
5Autopay / bill-pay payeesSaved payees may not migrate cleanly
6Merchant deposit & settlement instructionsWhere card deposits actually land
7Wire instructions shared with customersUpdate before they send to old details
8Online/mobile banking & entitlementsUser roles and approvals can reset
9Account signers & authorized usersRe-confirm who can move money
10Statements, tax docs & payment historyDownload before access changes

A simple conversion-week game plan

The checklist tells you what to verify; this tells you when to do it. Treat the conversion date as a hard deadline and work backward from it.

60 days out:  Have the conversion date confirmed in writing. Inquire if the account and routing numbers will change. Establish a backup operating account at another financial institution. Export the statements, tax documents, and payment history.

30 days out:  Your payroll provider, processor, and key vendor funding accounts need to be updated. Autopay and bill-pay payees need to be re-entered. A test ACH file and a small test card batch should be sent using the new details.

Conversion week:  When possible, run payroll a day early. Maintain more operating cash on hand than normal to account for any settlement delay. Ensure you have a point of contact at the bank (i.e., a name, not a 1-800 number).

The week after:  Reconcile the first full ACH cycle, the first payroll, and the first week of card settlements line by line before you trust the new setup.

The bigger picture: consolidation is the trend, not the exception

Fifth Third asserts that its net pitch yields a positive outcome for its customers after branch conversion. They claim that after conversion, Fifth Third clients and former Comerica clients in Michigan will gain access to approximately 42% and 60% more branches, respectively. Fifth Third also claims that they will offer the most extensive banking network in Detroit. However, looking at the big picture, this offer reflects the industry as a whole.

According to TheStreet, 178 bank branches shuttered during the first months of 2026, and over 10,000 branches closed after 2019. In the last 10 years, the Federal Reserve recorded a 19% reduction of bank branches in the United States. The trend of consolidation continues with regional mergers. This spring, layoffs from PNC’s merger with FirstBank impacted Colorado.

This merger is no different. Comerica was founded in Detroit in 1849. It wasn’t until 2007 that Comerica moved its headquarters to Dallas. By late 2026 or early 2027, Comerica will merge with Fifth Third (which will also include the naming rights to Detroit’s Comerica Park), thus significantly changing the face of banking in Detroit. In reaching this decision, Fifth Third has erased nearly two centuries of Detroit banking by focusing on integrating Comerica into its operations and eliminating the city’s largest banking presence.

The practical lesson isn’t “panic about your branch.” It’s that a closure notice is a re-shop moment — for banking and for processing. (We made a similar case after the CFPB’s Bilt reimbursement order: when the rails shift under you, it’s worth checking who you’re actually tied to.) The owners who come through a conversion unbothered are usually the ones who used it as a prompt to ask whether their current setup is still the best one.

What doesn’t have to move when your bank does

Here’s the section that is missed by most owners in the mad rush: your payments stack doesn’t need to be at the mercy of your bank’s merger calendar. If merchant services are with an independent provider (not a bank), your processing, ACH, and settlement logic remain safe during a bank switch — just reassign the deposit account.

Although simple, this principle increases your flexibility and reduces a bank’s monopoly. With an independent processor, you can settle money at any bank of your choosing. If a bank changes, you change a single field at the processor. Keep your card tokens with a vault provider, and a bank merger/transfer will prevent forced re-entry of your customers’ cards. This principle demonstrates why your bank is not the problem. Your bank is not your single point of failure.

COMPONENTIF IT’S TIED TO THE BANKIF IT’S PORTABLE
Card processing & settlementRe-papered with the bankStays — repoint deposit acct
ACH originationRe-onboard, new originator IDStays — same provider rails
Recurring billing / tokensAt risk of re-vaultingStays — tokens preserved
Reporting & reconciliationNew portal, new exportsStays — same dashboard

That portability is the whole argument for keeping merchant services separate from the deposit relationship — and for understanding the faster-payment rails (FedNow, RTP) that increasingly move money independent of any single branch. When the bank consolidates, the payments stack shouldn’t have to.

Frequently Asked Questions

  1. Is my money safe during the conversion?

    Yes — deposits remain FDIC-insured throughout, up to applicable limits. The risk here isn’t your balance; it’s the timing of transactions that depend on account details lining up after the cutover.

  2. Will my account and routing numbers change?

    They may. Some former Comerica accounts could be reassigned while others carry over. Ask the bank directly, in writing — the answer drives most of the checklist above.

  3. When exactly is the conversion?

    The bank says “later this year,” with branch closures landing this summer (reported around September). Some coverage points to a Labor Day conversion. Don’t rely on the public language — get your specific date confirmed in writing.

  4. Do I have to stay with Fifth Third?

    No. A closure notice is a natural time to compare banking and merchant services options. If you do switch, sequence it so it doesn’t collide with the conversion itself.

No-Show

How Studios Charge No-Show and Late-Cancel Fees Without Losing Members

You may have a cancellation policy written somewhere on your waiver or buried in the membership agreement. But if you’re being honest, you enforce it maybe once every five. The other four, it’s just not worth the hassle.

The front desk doesn’t want to be confronted for the no-show. With your software, charging by hand is a 5-step process. In the back of your mind, you’re worried members will just cancel their membership over a $15 fee.

As a result, the mat remains empty, the waitlisted member who wanted to use it doesn’t get to use it, and you bear the expense. Again.

Now, this is a thing that always irks me, but studios that charge regular fees simply don’t lose members because of them. What they lose is their members who were never going to remain.

The True Expense of a No Show

The True Expense of a No Show

A no-show is generally a minor inconvenience to most studio owners. It’s not. It’s a triple hit.

There’s the empty seat first of all. Two students did not bother to cancel for a class with 18 students, so there are 16 students in the class. Second, and this is the one that hurts, there were probably some people on the wait list for those two who didn’t get the chance because they seemed to be taken at the last minute. Thirdly, you’re still paying your teacher anyway.

Simulate numbers for a studio of 200 people who don’t attend classes 15% of the time, for 30 classes per week. This is about 90 blank spots in a week. At only $12 per spot, a conservatively estimated walkout cost is more than $1,000 per week.

The science of what actually works to change behavior is quite simple. Reminder texts alone? They’re somewhat helpful; they may be able to reduce your no-show rate by 5–8%. Fees alone? Bigger impact. Combine them? You’ll notice the true difference when both are in place, sometimes 30-40% less no-show for studios that have both.

Determining the Correct Amounts

That’s where a lot of studios go wrong. They set fees that are either too small to be consequential ($5 for a no-show at a $25 class) or too high to be acceptable, and they get complaints.

There are a few points to consider:

Late cancellations should always be fewer than no-shows. The whole idea is to reinforce the desired behavior — in this case, cancel and get you a chance to fill the seat. When these two fees are identical, there is no reason to cancel!

When it comes to late fees, it’s easier to find something in the $10–$15 range that works for most boutique studios. No-shows are generally $5-$10 more expensive. Class pack forfeiture is even more effective, as it makes it real for the member not to have a credit.

Your cancellation window is also important. For studios with members booking the night prior (e.g., early-morning yoga classes), a 12-hour window is better. For special courses, where the weeks are booked up weeks early, a 24-hour time frame seems more appropriate. Before making a decision, consider your actual booking history; most booking websites will provide you with your booking history.

The Consent Language That Protects You

The Consent Language That Protects You

If you charge a card on file without the proper authorization language, then you will lose a chargeback dispute. The member claims that they did not approve the charge, the bank agrees, and you have to pay the charge plus an additional $25 chargeback fee.

Your waiver/membership contract should contain two clauses: first, it must state what the fees are for; second, it must authorize you to charge the card on file when the fees apply.

E.g. “Member authorizes [Studio Name] to charge the card on file for cancellation and no-show fees, in the amounts set out in the membership terms, on the same basis as their regular membership charges, until the card on file is changed or the membership ends.”

That doesn’t count as legal advice (consult a real law firm if you have any important questions), but the important parts are the “explicit authorization” and the mention of the policy being something that they have acknowledged.

The Grace Ladder

A good policy is never enough, because charging any first-time offender, no matter what is happening, is bad for retention. People have emergencies. Phones die. Life happens.

Create a grace system, and write it down. 1st absenteeism in a 90-day period? The fee is automatically waived, and a friendly reminder is sent. Second offense? Fee applies. Third and beyond? Fees apply, regardless of the reason.

The advantage of automating it is that it eliminates the human judgment call and, therefore, the awkwardness. The system charges them, not you. If someone has genuinely forgotten, it doesn’t leave them feeling penalized; if they have done it more regularly, they are always charged.

Strategies for Making the Charge Automatic

Strategies for Making the Charge Automatic

Studios with a policy in place don’t have to manually charge cards in the morning. They have their software programmed to do that for them, after a predetermined time period following class.

The flow is as follows: At the end of class, the system will compare who is registered with who has checked in. Those who are registered but fail to check in and do not cancel in time are flagged. The fee is charged automatically a couple of hours later. The member is notified of the reason.

No phone call. No embarrassing conversation at the front desk when they enter the building. It’s simply a straightforward notification.

The Announcement and What to Say

Announcing a fee policy you’ve never had before is the most dreaded aspect of being a studio owner. It’s not a big deal, but it’s direct communication.

An email that gets results:

From October 8, 2026 we will be enforcing a cancellation policy for late cancels & no shows; we know most of you are very good about cancelling and this is primarily for those of you that have reserved and others are waiting to occupy the space. As always, life happens, and we deal with genuine emergencies with common sense. Thanks for being part of [Studio Name].

Short. Non-accusatory. Matter-of-fact. You’re not hurting your members; you’re ensuring the experience for all of them.

Conclusion

Check your existing waiver and member agreement for the language regarding card authorization. If not clearly mentioned, correct it first.

Afterward, you set your fee rates, establish your windows, configure your grace ladder, and enable auto-charging in your booking software. This process can take hours to set up, and the results are apparent in the first month of the implementation.

We keep our gym and studio payment articles together in Fitness and Gym Payment Resources; see it for more on no-show and late-cancel fees.

Bypass Credit Card Fees

How Pay-by-Bank Is Helping Gyms Bypass Credit Card Fees

No one starts a gym business because they find payment statements fascinating.

We go into this field because we believe in fitness, the social atmosphere, and maybe even helping build something worthwhile in our communities where none had existed previously. Payment processing is an afterthought for most of us; just another hoop to jump through until we can focus on getting the gym up and running. Which, conveniently enough, is exactly what Visa and Mastercard want. Most gym owners overlook the pay-by-bank facility, which lets them bypass credit card fees and save a lot of money.

The majority of gym owners know that credit card fees are around 2 percent, but they do not realize how quickly they eat into their revenue streams. Consider a business earning $30,000 per month in membership fees. Given that the vast majority of those members use their credit cards for payment, that entrepreneur is most likely losing $600 to $1,000 each month on credit card fees alone, even before meeting utility bills and salaries – $7,000 to $12,000 annually. For what? In effect, for giving Visa the opportunity to meddle in the financial transaction between you and your own paying customer.

It seems there is a much better system. In fact, Pay-by-bank has been here all along; the thing is, no one ever forced owners to examine it before now.

It Was Right Here All Along: The Problem with ACH

The Problem with ACH

ACH is the Automated Clearing House system. It processes funds transfers between accounts. That’s how your direct deposit goes through, and how your electricity bill payment works too. ACH has been silently transferring funds since the seventies. The fitness business has been using it for years now; however, it was quite a tedious task back then. An individual would fill out a form with their routing number; the gym would batch these debits manually on a monthly basis, and sometimes it went wrong.

All these concerns about ACH were completely valid at the time. It took forever to verify accounts. It took days just to validate an account number by submitting micro-deposits. Billing mistakes would become apparent far too late in that process. It really did seem like a step backward compared to the immediate satisfaction of swiping a card.

Yet many entrepreneurs are still thinking with a very old mindset. Times have changed.

Bank verification tools, such as those embedded directly in today’s gym management systems, can verify a person’s account information within seconds. The customer won’t even need to find the routing number; all they need to do is access their bank through a simple interface that works much like Venmo or Cash App. In addition, due to Same-Day ACH, the settlement time has been dramatically shortened. While it used to take a prohibitive three to five days to settle payments, this delay is now so minimal that it makes no significant difference compared to card payments.

What the Figures Actually Mean

Let’s get down to some cold hard facts, as this is where the theory will either stand its ground or fall apart.

Credit card interchange rates range from 1.5% to 2.5% for most consumer credit cards. But rewards credit cards (usually used by wealthier consumers) are closer to 2.5%. Add in the premium travel credit card, and you may be looking at a rate of more than 2.7%. After you account for the markup your processing service applies, you will be paying between 2% and 3.5%.

ACH is only a fraction of the cost. You’ll most likely be paying somewhere between $0.25–$1.00 for each transaction based on your situation, or even just a very small percentage that stops way below the cost of credit card interchange fees.

Here’s a quick calculation: For your average $50 per month subscription price, even your expensive $0.75 ACH processing fee still pales in comparison to the $1.25–$1.75 you might be losing per credit card transaction. On an annual basis, with 800 members billed monthly, this would result in an additional $5,000–$8,000 per year.

And this does not even take into consideration the horror that is chargebacks. One of your members disputes a charge because they did not realize they had joined, or because they simply did not wish to pay this month, and all of a sudden you owe the reversal amount plus a $25 penalty. Even though ACH disputes exist, they follow completely different rules. The valid grounds are narrow — a customer can generally only dispute an ACH debit as unauthorized, as a revoked authorization, or for an incorrect amount or date — so the “chargeback reflex” that credit card companies have cultivated does not apply here. There is a trade-off worth knowing, though: a consumer has up to 60 days to file, and unlike a card chargeback, you cannot contest an ACH reversal through the banking system. If the member’s bank honors the return, the funds are pulled, and you settle it directly with the member. In practice, that means far fewer disputes, but the ones you do get are resolved member-to-member rather than by fighting the bank.

Bypass Credit Card Fees With Pay-by-Bank: Why Gyms Are Uniquely Suited for This

Pay-by-Bank

Well, not every kind of business lends itself to making payments through banks. For example, you can’t really expect someone at a coffee shop that does $6 sales at a busy counter to make their transaction as quick as possible.

But with a gym membership, everything’s turned around almost 180 degrees.

This process, in essence, is ongoing. The customer subscribes to the gym service, establishes the payment instrument once, and is automatically charged each month. The minor inconvenience of establishing the ACH transaction occurs only once, when signing up for the gym. This cannot be compared to the expiration of a credit card every few years, which causes the charge to fail, triggers an automated notification, and finally leads to an embarrassing discussion at the reception counter to gather new information. A bank account never expires; it stays open unless closed by the customer.

This is another place where ticket sizes will come into play. Monthly membership costs could range from $30 to $100, with coaching and CrossFit gyms potentially costing $150–$200. With such low numbers, taking percentages doesn’t look like the best strategy. That’s why flat-rate payments via ACH become incredibly appealing if your ticket size exceeds $40.

The Member Pushback Problem

Of course, no discussion on this topic would be complete without addressing the obvious concern: How willing will members really be to sign up for this service?

It’s a legitimate concern for sure. Any change to billing strategies can result in complaints from some members. However, most owners tend to overestimate their concerns. Remember, most people use autopay for things like car insurance and utilities.

With the right approach, many will even prefer it. No credit card information is in play, so a breach at some unknown retailer can’t compromise the card they would have used to pay their gym membership. It’s an easier, straight-to-the-point payment method.

While it may appear that you’re giving up the profits by offering even a small discount, when considering the bigger picture compared to what the credit card companies are charging you, you’ll most likely still come out ahead. As for new customers? Simply make ACH the default selection on your iPad or website signup form, and there’s little doubt they’ll choose it.

How the Setup Actually Works

How the Setup Actually Works

In practice, it’s not rocket science, although you will have to find a processor that actually prioritizes payment processing for banks instead of treating it like an afterthought.

Here are three components that ensure this is a smooth process:

  1. Digital authorization embedded within your digital waiver/consent process.
  2. Instant bank authentication to prevent members from having to think about their routing numbers.
  3. Intelligent reporting to know about failed payments immediately without searching through Excel.

Fortunately, most systems designed today have native support for this capability. What’s key is that your merchant provider understands how to price this type of recurring high-volume business. Take, for example, Host Merchant Services, which offers an ACH/eCheck program specialized for gyms. Pricing is based on recurring volume rather than single-time invoice transactions, which is important because gyms handle hundreds of monthly transactions rather than just a few corporate accounts.

Facing the Facts About Failures

It’s only fair to note that ACH is not a miracle cure. Things go wrong with ACH, just like cards.

A credit card transaction will either go through immediately or be declined straight away. You will be able to tell right away whether or not the card is maxed out. ACH payments take one or two days before the bank sends a return code that could indicate either insufficient funds or an account that has been closed.

However, this doesn’t mean you cannot overcome this obstacle; it simply means you need to put measures in place to ensure it doesn’t happen. For example, your software needs to include logic that immediately sends your members a secure URL so they can update their banking information.

Conclusion

A definite change is occurring in the payment methods for ongoing services. Slowly but surely, the USA is heading towards implementing the same type of account-to-account architecture as the Europeans have had in place for years, with improvements such as the Federal Reserve’s FedNow rail and Same-Day ACH functionality.

Card payments will not disappear overnight, nor do they need to. Card payments make perfect sense for one-off retail purchases or instant point-of-sale payments. However, for a consistent and repeatable payment from someone who has been training with you for two years? Handing over any value in that relationship to the cards doesn’t seem right anymore.

Gyms with razor-thin margins and high-volume operations would see huge benefits from earning a little more profit. That’s because they don’t have to start a fresh marketing campaign or sell any more merchandise to earn additional money. All they are doing is saving money that is theirs.

Related reading on pay-by-bank for gyms: Fitness and Gym Payment Resources.

Hypercard

American Express Acquires Hypercard: AI Expense Management Goes Mainstream

In the second quarter of the financial year of 2026, Amex made headlines with a historic acquisition. American Express acquired Hypercard. This is not your average tech buyout; it was a strategic move and a milestone in merchant payments worldwide. To understand the depth of this acquisition, you must understand the advent of agentic AI and autonomous finance in the payment landscape. Agentic AI is a type of artificial intelligence software that specializes in certain tasks.

AI, in general, possesses broad intelligence. However, agentic AI, as the name suggests, is an agent; it specializes in a specific field and is highly optimized to autonomously execute multi-step tasks, such as reading receipts, coding, and filing. On the other hand, autonomous finance is a connected topic. It refers to the automation of finance through technologies such as artificial intelligence, which operates silently in the background without requiring human intervention.

Hypercard was a startup founded in 2022. It was backed by revolutionary thought leaders of the modern tech industry, such as Sam Altman. The acquisition of Hypercard by American Express signals a strategic shift towards embedding AI technology across merchant payments and banking systems worldwide. Legacy software simply digitized the billing and the financial aspects of any business. It did not offer any actionable insight within the software that could be used to self-optimize the system and prevent any losses. However, AI can analyze historical data and make accurate predictions about the future. This results in a shift in the SaaS industry towards AI-based services that can make smarter decisions and more accurate predictions.

It also marks an end to reactive finance. Instead of employees analyzing and reporting on quarterly reports and then taking action on them, AI can analyze past data and make statistically better decisions. This acquisition fits a broader trend in which large financial institutions are acquiring AI fintechs to control the entire B2B spend lifecycle.

The Broken State of Legacy Expense Management

Legacy Expense Management

The current system has multiple points of failure. Month-end close is one of the most agonizing accounting processes finance teams go through each month. They have to verify, categorize, and reconcile all company spending before closing the books. Reconciliation refers to the act of matching the ledger records with the bank account statements to cross-reference and match payments to different accounts. Amex saw this gap in the finance industry; they suffered from it too. To reduce the workload and burden on staff and streamline financial bookkeeping, American Express acquired Hypercard.

Legacy systems such as Concur or Expensify only moved the manual burden from paper to a screen; they did not eliminate manual data entry; rather, they just shifted the medium. In other words, this was mere digitization of the account books. Traditional expense reporting relies on employees. It is highly subjective, depending on the work employees send, their ability to meet deadlines, and whether they actually remember to file expense reports every week. This creates a manual lag. This lag often results in error reporting and finance reconciliation getting delayed.

Legacy tools have another disadvantage — they work on reactive mechanics. They flag a discrepancy or a violation after the money has already been spent. This forces the finance teams into the awkward position of reporting the loss and taking accountability for it. On the other hand, modern AI systems have completely changed the game. They focus on any pattern that could possibly result in a loss and flag it prematurely. This creates an environment for preventive financial management that mitigates losses and fosters a better financial ecosystem.

Controllers have to spend a disproportionate amount of their time chasing receipts from employees. This often creates manual follow-ups that stall the accounting cycle and create friction, often resulting in lags. Also, human data entry is prone to errors, so there is no guarantee of the report’s outcome.

What is “Agentic” Expense Management?

“Agentic” Expense Management

At the heart of this acquisition sits agentic expense management. Generative AI is an all-purpose AI that can answer a wide variety of questions for you. It is most commonly used by everyday consumers for tasks such as searching the internet. However, agentic AI is a niche type of AI that specializes in autonomously making complex decisions within a particular field. For example, an agent that can categorize, consolidate, and reconcile financial data of a company.

With agentic AI, we often hear the term “deterministic workflows” associated with it. These are processes that follow strict, unchanging rules, such as accounting principles. These rules must be followed by the AI agent, unlike the “creative” freedom of a text generator, making its outcome more predictable.

Agentic AI goes beyond chatbots; it is not just a general-purpose chatbot but a specialized digital worker. It can log into systems, extract data, map it to rules, and route it for approval without human prompting. An AI agent can perform multi-step execution. It receives a receipt, uses optical character recognition to read it, matches it to corporate statements, checks it against policies, and then assigns it an appropriate accounting code.

Agentic systems can also understand the user’s context. For example, it knows if the employee is a VP with a $500 dinner allowance or a normal employee with a $50 allowance. When the AI agent encounters a receipt that appears to be an exception, it can autonomously route it to a human supervisor for manual confirmation and interpretation. As finance teams correct the agent’s output, it continuously saves the feedback. An AI agent can continually learn from human user feedback and update its categorization models. This means that the system gets smarter as it encounters more data.

Hypercard: The Tech Behind The Acquisition

Hypercard was founded in 2022 by Marc Baghadjian and Nikolas Ioannou. When it started, its core focus was autonomous workflows, which earned it substantial backing from heavyweights such as Sam Altman, OpenAI’s CEO, who validated its AI architecture.

Native AI architecture refers to software built around artificial intelligence from the start, rather than an older software platform that integrates AI features to stay relevant in the market. In 2024, Amex discovered Hypercard, and their first collaboration was made. Together, they launched the “Hypercard Rewards American Express card”, which served as a live in-market stress test for Hypercard.

Hypercard’s value lies not just in its slick interface; its real value lies in the backend automation it provides for back-office admin tasks. Its AI engine is specifically designed to handle rigid, high-stakes data requirements of corporate finance. With an agile partner platform, these deliverables get amplified in value. An Agile Partner Platform (APP) is an integration framework by Amex. It allows third-party tech companies to build services directly on top of Amex’s card data.

Hyper’s focus was on developing effortless finance. However, their ultimate goal wasn’t just to develop an expense tracker for corporate giants; it was to build an FP&A (Financial Planning & Analysis) agent capable of forecasting financial outcomes. The key applications were forecasting and a corporate travel-planning agent, which would give Amex a roadmap for future AI products.

On top of that, Amex also acquired a specialized engineering team that knows exactly how to build and deploy AI tools that don’t break under stress. This was effectively an acqui-hire.

Why Amex Bought Hyper: Merging Payments with Autonomous Workflows

Why Amex Bought Hyper

Amex had a closed-loop payment network. This means that Amex acts as both the card issuer and the payment processor, which gives it direct access to far richer transaction data than open networks do. Amex does not want to limit itself to just facilitating payments. Its ultimate aim is to own the end-to-end corporate finance lifecycle, from initiating payments to balancing the books. They want to manage what happens before and after the swipe, making it harder for companies to switch from Amex to a competitor. It wants to become an embedded finance solution. Embedded finance means the integration of financial services, such as accounting software, directly into a non-financial or primary interface, such as credit cards.

Since Amex operates a closed-loop network, it has access to more granular transaction data than Visa and Mastercard. Feeding this data directly into Hyper’s AI makes automated categorization significantly more accurate. The Hyper deal substantiates this ascent toward dominance in the finance field. It builds directly on Amex’s 2025 acquisition of “Center”, which is expense management software, proving that Amex is systematically assembling an all-in-one corporate finance platform to launch later in 2026.

This acquisition is also aimed at fending off fintechs. B2B fintechs such as Brex and Ramp built their entire businesses by offering software attached to corporate cards. Amex is buying Hyper to beat these agile startups at their own game.

Impact on Controllers and CFOs: Accelerating the Month-End Close

Continuous close is an accounting concept in which books are updated and reconciled in real time rather than compiled at the end of the month. To prevent the burden of updating massive batches, companies often use automated software. On the other hand, accrual is an accounting method in which expenses are recorded when they are incurred. This is not necessarily restricted to when cash leaves the bank and requires accurate visibility into outstanding spending.

AI agents can process expenses as they occur. This means that connecting them to the CFO’s dashboard could update accounts in real time. On the other hand, controllers get their time back. They no longer have to act as debt collectors chasing receipts, because the AI has already sent out the prompts and communication.

Lastly, since the data is carefully categorized, the financial models and budget forecasts are often really accurate.

Conclusion

The Amex-Hypercard deal indicates a shift in the payment landscape. It represents the moment when expense management shifted from a reactive, manual software category to a proactive, invisible feature of the payment network itself. Agentic AI not only saves money; it buys back thousands of hours of human time capital. Within five years, manually filling out account books will become obsolete, making AI reconciliation a survival necessity.

Frequently Asked Questions

  1. What did Amex acquire through Hypercard?

    It acquired an agentic expense management software company, gaining its team of AI experts and proprietary tech stack to automate back-end finance.

  2. Will AI expense management replace accountants?

    No, but it will fundamentally change their jobs. AI handles the rote, manual data entry and basic reconciliation, allowing controllers and accountants to focus on strategic analysis, cash flow forecasting, and edge-case exceptions.

  3. What happens if the AI categorizes an expense incorrectly?

    If an expense is wrongly categorized, it will be passed to the human supervisor for confirmation. This will be a rare case, as AI can categorize quite efficiently, and the human in the loop would ensure a high level of accuracy.

  4. Why are credit card networks buying software companies?

    Credit card companies are acquiring software companies to establish closed-loop networks that control the entire financial cycle for corporates. This is an effort to remain relevant in a market where payment processing is becoming increasingly commoditized.

  5. How does the AI handle company spending policies?

    When an expense occurs, the AI cross-references the transaction against those rules in real-time, instantly approving compliant spending and flagging violations.

Talon.One Acquisition

Adyen’s $876M Talon.One Deal — What It Signals For Embedded Loyalty + Payments

Recently, we saw a drastic shift in Adyen’s strategy. Will this erase the boundary between “paying for an item” and “deciding its price”?

Organic building is a corporate strategy for developing software entirely in-house from scratch, rather than buying technology from external companies. For years, Adyen relied on organic growth as its foundational growth strategy, building an impressive brand presence. This $876M merger marks a major shift — a massive, uncharacteristic pivot that signals a high sense of urgency.

The Talon.One acquisition has fundamentally merged the checkout and promotional processes, ensuring that the act of paying and the calculation of personalized discounts are now monopolized. Traditionally, shoppers had to calculate their final prices before initiating a payment. This meant they had to leave the checkout page to search for discounts and promo codes, creating significant friction.

By embedding Talon.One, the user can access discount codes directly, meaning Adyen has provided direct access to dynamic pricing in its checkout forms, so customers now don’t have to leave the checkout page at all.

Why Payments and Loyalty Can No Longer Live in Silos

Payments and Loyalty

Separating your CRM software from your payment processor creates data fragmentation. API Integration tax refers to the financial and operational cost merchants pay to connect disparate software systems, such as CRMs and accounting software, so they can communicate with one another. Software disconnect is a big disadvantage.

The “Silo Problem” is faced by every merchant that stores loyalty points in their CRM but has no real-time sync between the CRM and the payment software. This forces them to build fragile technical bridges that fail most of the time. These disparate systems often fail to synchronize in real time, creating additional work for admin staff. It also introduces human error and time delay into the process, resulting in a clunky customer experience.

The API integration tax forces millions of dollars out of merchants’ pockets every year for enterprise-grade solutions, just to make a basic discount mechanism function properly. The payment processor represents the ultimate source of truth, as it is the firsthand observer of payment success or failure, making it the most reliable trigger for updating a customer’s loyalty tier. Combining these systems actively prevents discount fraud, as the latency between customer tier update and promo code availability is eliminated.

The Mechanics of Real-Time Decisioning at Checkout

Real-Time Decisioning at Checkout

Real-time decisioning refers to an automated rule engine that analyzes live data and makes decisions in real time, following the constraints of the given rules. Let us break down the technical process of Adyen and Talon.One’s discount rules during a transaction.

The primary advantage of real-time decisioning is the elimination of latency. Latency is the delay between the user taking an action, such as clicking “Pay”, and the system responding. Low latency is the key to preventing checkout timeouts. The system functions as an intermediary rule engine that intercepts the shopping basket data. It checks the user’s ID against the Talon.One’s database, and overwrites the final price before routing the request to the acquiring bank.

This process is important because legacy setups require the e-commerce websites to calculate all discounts before forwarding the final total to the payment gateway. This means that once the payment gateway has accepted the payment, the amount cannot be changed. On the other hand, Talon.One allows dynamic pricing for the user.

Unified Commerce: Bridging the Gap Between Online and In-Store Identity

Unified commerce refers to a centralized backend platform that handles all customer interactions, payments, and data across physical stores and online channels. On the other hand, identity resolution is the technical process of linking different data points, such as a credit card and an email address, to a single master customer file.

Unified commerce solves the problem of forgetting a customer, where a brand treats a highly loyal shopper like a complete stranger when they walk into the physical store for the first time. This usually happens because the payment processor is not connected to the front-desk CRM. Adyen uses actual payment credentials such as 16-digit credit card numbers or Apple Pay tokens as the primary customer identifier. This helps the brand identify the customer the minute they tap their card on the physical cash register.

This frictionless recognition is important because relying on physical loyalty cards or phone numbers slows checkout times, creating bottlenecks that lead customers to skip checkout. By connecting Talon.One and the Adyen POS terminal, the system can instantly recognize and cross-reference a tapped card, calculate available points, and prompt the cashier with a highly personalized offer.

The Agentic Commerce Angle: Why AI Bots need Machine-Readable Loyalty

Agentic Commerce

Agentic commerce and AI buyers require structured data to function efficiently. Agentic commerce is the future of e-commerce, in which AI software agents research, negotiate, and autonomously initiate purchases on behalf of human users. On the other hand, machine-readable pricing refers to pricing and discount rules structured strictly in code rather than text, which allows AI systems to instantly calculate the final cost via API.

Agentic commerce shifts purchasing power from human-dependent systems towards AI systems capable of making their own decisions. In this model, the merchant provides machine-readable pricing and eligibility logic, which allows an AI system to instantly understand and calculate the exact final cost. This is crucial because if an AI agent cannot dynamically access and verify a merchant’s loyalty discounts via API, it will likely purchase from a competitor whose standard public price appears lower, costing the merchant a guaranteed sale.

Adyen and Talon.One have solved this barrier by baking complex decisioning rules directly into the transaction layer. It empowers the merchant’s system to present the exact, personalized price to the AI agent in a short span of time.

Talon.One Acquisition: Moving From Basket Totals to Item-Specific Pricing

Stock Keeping Unit (SKU) refers to a unique alphanumeric barcode or identifier for a specific product and its variants. Basket-level data looks at the total spend. On the other hand, SKU-level data looks at the specific items bought. SKU-level data processing allows the payment engine to analyze exactly which items are in the shopping cart, rather than just the total amount. This allows the merchants to design precise promotional strategies.

This level of detailed visibility matters because applying static discounts to your products destroys overall profit margins; however, applying dynamic discounts requires distinct technical capabilities. With Talon.One‘s engine integrated into their workflow, a merchant can apply heavy discounts instantly based on the customer’s purchase history. This helps them charge full price for highly anticipated new arrivals sitting in the exact same basket.

The system can execute highly complex conditionals, such as granting triple loyalty points only if the basket contains a specific promoted SKU, directly within the payment gateway. This type of direct access to item-specific data at checkout helps merchants optimize inventory allocation in real time, thereby driving sales volume towards overstocked warehouse items without a broad devaluation of their prices.

Shifting From Payment Processor to Transaction Optimizer

Commoditization occurs when a service becomes so common and standardized that companies can compete only on price and distribution. Pure payment processing is rapidly becoming commoditized. This means that infrastructure companies like Adyen must offer advanced software layers that differentiate them from competitors.

Transaction optimizers are platforms that change the economic outcomes of a sale. They don’t just process payments; they maximize merchant revenue through multiple strategies. By acquiring Talon.One, Adyen shifted its identity from being just a payment processor to a transaction optimizer.

This is crucial because enterprise merchants view payment processing as an unavoidable cost center to be minimized, whereas they view loyalty and conversion tools as revenue generators that justify premium investment. The combined integration enables Adyen to directly influence Customer Lifetime Value (CLV), ensuring the frictionless payment experience actively encourages repeat purchases.

Margin Control vs. Conversion

Margin leakage refers to the unintentional loss of profit caused by overlapping discounts, poor promotional structure, or system exploitation. On the other hand, dynamic offers are promotions and prices that change in real-time based on user behavior, inventory levels, or purchase history. Dynamic offers solve cart problems efficiently. They give hesitant buyers the exact personalized incentive they need to check out. However, if left unchecked by strict financial guardrails, they can cause catastrophic margin leakage.

Financial governance is important because real-time automated incentives execute instantly. Talon.One’s infrastructure provides strict governance over these policies. They prevent coupon stacking, which ensures that a clever customer cannot combine a “first-time buyer” code with a “clearance sale” discount.

Strategic Implications for the Wider Fintech Ecosystem

Fintech ecosystems are interconnected networks of financial technology companies that compete aggressively for enterprise merchant businesses. Adyen’s acquisition forces major competitors, such as Stripe and PayPal, to reevaluate whether their value-added services are sufficiently integrated to genuinely compete with a unified, native loyalty engine.

On the other hand, Value-Added Services (VAS) refer to extra software features built on top of the core product to increase stickiness. Adyen’s competitive shift will change the payment landscape for enterprises. While other competitors will be left competing in commoditized payment processing, Adyen is capitalizing on the single feature enterprises are willing to pay a premium for.

The market is likely to see an aggressive M&A race in the fintech space – major payment processors will be hunting for enterprise clients. For merchants, this means the competition will offer multiple high-value options at affordable prices.

Conclusion

An embedded loyalty stack is a technology setup where loyalty and rewards are built directly into the core commerce and payment flow. On the other hand, data hygiene refers to the practice of ensuring customer databases are clean, accurate, and free of duplicates. Merchants must adopt data hygiene practices to ensure seamless transitions and avoid subsequent software failures caused by bad data.

The customer identity is converging rapidly towards real-time decisioning and payment processing in a single motion. Adyen’s uncharacteristic decision indicates the urgency in the consumer market. Merchants that adopt the new strategies will see sustained growth in the future.

Transitioning to embedded loyalty stacks is necessary to ensure modern consumers are satisfied with the shopping experience. Companies should mitigate risk by migrating basic point-earning rules to the new payment layer before attempting to launch complex, SKU-level dynamic pricing or agentic commerce integrations.

Frequently Asked Questions

  1. What does Talon. One do?

    It is an API first enterprise loyalty and promotion engine. It allows merchants to create, manage, and execute complex promotional and loyalty rules in real time.

  2. How does real-time decisioning impact cart abandonment?

    Real-time decisioning reduces cart abandonment. It means that prices change dynamically during checkout, without the customer having to leave the checkout page.

  3. What is embedded loyalty?

    Embedded loyalty integrates reward systems directly into payment gateways and POS terminals. It ensures that paying automatically redeems stored rewards without ever leaving the checkout page.

  4. How does this affect physical retail stores?

    It enables true unified commerce by using a customer’s payment card or digital wallet as their loyalty identifier.

  5. Will this change how merchants manage their profit margins?

    Yes, by changing loyalty rules, finance teams can gain absolute control over promotional budgets. This means overspending on loyalty is prevented, and profit margins do not bleed.

Agentic Checkout

Stripe + Google Bring Agentic Checkout to Gemini — What Merchants Must Now Understand

With a shift in customer mindset, checkouts are now shifting from merchant websites to AI interfaces, such as Google Gemini. Stripe recently partnered with Google to bring agentic checkout to Gemini; this partnership will be a catalyst that’ll change the retail industry forever.

Agentic checkout is a process in which an AI assistant completes a purchase on the user’s behalf, skipping the hassle of navigating a merchant’s website and checkout interface. The technology that facilitates agentic checkout is known as checkout orchestration. This technology coordinates processes such as product discovery, inventory checking, and payment execution invisibly in the background.

The traditional e-commerce funnel involved a customer landing on the merchant’s website, searching for a desired product, and then proceeding to checkout. This forced users to leave their current digital context. With the partnership between Stripe and Google, the aim is to embed the checkout directly within Google’s AI Search feature and Gemini app. This partnership is crucial for merchants because it takes the massive consumer reach of Google, via Gemini and Universal Cart, and combines it with the extensive payment infrastructure of Stripe.

The significance of this partnership for merchants is unparalleled. It will fundamentally change how products are discovered and sold, turning AI models into new storefronts.

What “Agentic Commerce” Actually Means

What “Agentic Commerce” Actually Means

Agentic commerce has been a buzzword in the market for a long time. Agentic commerce mainly comprises two key components: AI agents and autonomous economic actors. AI agents are software programs that make decisions and take actions based on constraints provided by their human users. Autonomous economic actors are digital bots that have the authority and technical capability to spend money. You must have realized by now that agentic commerce can be simply understood as AI agents buying merchandise online.

Early AI models, such as ChatGPT, Claude, and Gemini, functioned only as chatbots. They were advisors who could scour the internet for you and recommend the best products. However, these chatbots possessed neither the authority nor the technical capabilities to spend money and make purchases.

Agentic commerce elevates them from mere AI chatbots to autonomous economic actors by enabling them to make purchases and spend money online. This ability shifts the entire e-commerce landscape from being a search-driven marketplace to a search-optimized store. The products that best align with the agentic constraints will be purchased, while poorly optimized merchant sites will see a decline in sales revenue.

Payments are no longer a one-off event; they are distributed over specific time periods as constraints. A great example of this is Gemini’s ability to spend a set amount of money per week, such as $50 on coffee beans. To bring agentic checkouts to the masses, the AI needs to be able to catalog all the products available online, and this is the exact problem Stripe and Google are solving together.

What Stripe + Google are Actually Enabling

Stripe + Google Bring Agentic Checkout to Gemini

The partnership between Google and Stripe is based on two specific technologies: Stripe’s Agentic Commerce Suite and Google’s Universal Cart. The Agentic Commerce Suite is a Stripe toolset that enables merchants to make their product catalogs and payment systems accessible to AI systems. On the other hand, Google’s Universal Cart is a new cross-platform shopping cart that lives inside Gemini, Search, and YouTube. It tracks items and executes purchases via AI. It is clear how these systems will complement each other — one will serve as a universal catalog for every product on the internet, while the other will serve as the cash register for that product.

Google will provide the consumer surface via the Universal Cart, which will allow shoppers to add items to an intelligent cart while chatting with Gemini or browsing YouTube. Stripe, on the other hand, will provide the financial plumbing by allowing the merchant to list products and accept secure, machine-initiated payments through a single integration.

Through the Universal Commerce Protocol (UCP), Gemini can read a merchant’s Stripe-hosted product catalog in real-time. This allows the transaction to happen speedily. Even though the complete ecosystem rests inside Google itself, the brand that sells the product still owns the revenue, liability, and customer data. This partnership means that fragmentation will be eliminated; single, cohesive catalogs will be uploaded to Stripe, read by Universal Cart, and transactions initiated, all without the user ever leaving their digital context.

How Agentic Checkout Works: Step-by-Step Flow

How Agentic Checkout Works

Agentic checkouts depend on two technologies: machine-readable data and webhooks. As the name indicates, machine-readable data refers to product information such as price, size, or stock availability, formatted specifically to be read by an AI software. Webhooks are automated messages sent from one app to another when an event occurs. It is a complex web concept. For now, you can understand it as the payment gateway telling the AI that the payment succeeded.

Now, let us see the steps involved in agentic checkout:

Step 1: Discovery and Syncing

For the product to be accessible to the AI, it must first be listed. The merchant connects their product catalog to Stripe, which formats the data into structures the AI can parse.

Step 2: User Intent

The real process starts here. The buyer tells Gemini what they want to buy. Gemini then verifies the inventory and availability in real time.

Step 3: Authentication & Guardrails

After the user’s intent is verified, Gemini will check whether the user is actually authorized to spend the required amount. This usually happens via Google’s Agent Payments Protocol (AP2).

Step 4: Token Exchange

In agentic payments, the credit card is not passed repeatedly because it poses security risks. Instead, one-time, unique tokens are generated for every payment to ensure that codes aren’t reused.

Step 5: Machine Confirmation

The merchant’s payment system will process the token. Upon successful payment, a webhook will be sent by the payment processor, notifying the AI that the payment has been completed.

Why This Changes Checkout Ownership and Customer Relationships

Checkout ownership refers to the control a merchant has over the visual interface of the checkout page on their website. For decades, checkout ownership had been a differentiating factor among merchant websites, influencing conversion and abandonment rates. A better checkout page meant lower cart abandonment. With features such as mobile optimization and guest checkouts, merchants were able to compete and increase website traffic. Agentic checkout strips away the website UI, giving all merchants a level playing field for the checkout interface.

Brands still retain the “Merchant of Record” role, but they lose the ability to design custom checkout workflows; Stripe’s generic payment flow becomes the uniform payment processor for everyone. The merchant loses the ability to personalize the checkout experience, recommend new products, implement pop-ups, and visualize cross-sellers, shifting the checkout process to a plain-text format.

This also causes a shift in brand loyalty. The customer will not attribute the instant checkout and the fast transaction to the brand; instead, they will associate it with Gemini. However, this also has an advantage — by surrendering the burden of visual checkout, merchants gain access to buyers at moments of high intent and catch sales they otherwise risk losing.

Payment Infrastructures Behind the Scenes: Tokens, API, and Stored Credentials

The AI agent must obtain bank credentials to proceed with checkout. For this, it uses tokenization and virtual cards to securely store and transmit card data. Tokenization refers to the process of replacing sensitive credit card numbers with a randomized string of characters that is useless if stolen by a hacker. On the other hand, virtual cards, also known as shared payment tokens, are temporary payment methods issued specifically for a single transaction or for an AI agent. These tokens expire immediately after use, rendering them useless for preventing fraudulent transactions in the future.

Giving an AI agent your credit card details is a security risk. To prevent any security catastrophe, the AI agent relies on tokenized, stored credentials to proceed with transactions. When Gemini decides on a transaction, it requests a shared payment token or a virtual card from Stripe. This is then used as a temporary token to process the payment.

Merchants must upgrade from old-style checkout forms to API-based payment forms, which enable agents to process transactions automatically, reducing human friction. Newer technologies, such as Stripe Radar, have evolved to distinguish fraudulent “bots” from genuine, intent-based agentic transactions.

Benefits for Merchants: Conversion, Speed, and Automation

There are two main benefits of agentic checkouts: frictionless conversions and distributed commerce. The ultimate aim is to remove every possible barrier between the moment of intent and checkout completion. Barriers could be clicks, form fields, or any lack of optimization that delays the checkout process. Distributed commerce refers to selling your products across multiple platforms and interfaces, rather than just your main website.

The immediate benefit of agentic checkout workflows is reduced cart abandonment. The AI can remember passwords, addresses, and other personal information for the consumer; this reduces friction from repeatedly entering address fields and passwords, lowering form abandonment rates. On the other hand, merchants can access consumers where they already spend most of their time. This eliminates the need for the customer to visit the brand’s website and allows them to purchase the products they want directly from the interface they’re using, such as Gemini, Search, or YouTube.

Agentic checkout also enables complex, multi-vendor problem-solving, allowing the customer to compare prices and secure the best deal without having to scour multiple websites. For smaller merchants, it allows them to be bundled with larger AI-driven purchases.

Conclusion

One-click checkout adoption boosts conversion rates by 20% to 30%. By utilizing Stripe’s Agentic Commerce Suite and Google’s Universal Cart, merchants can future-proof their business. This ensures that your catalogs are ready for next-gen AI-based purchases and capture customers beyond dedicated websites.

The partnership between Stripe and Google will redefine how e-commerce is implemented; merchants will now be able to compete with major brands without having to implement expensive website optimizations. With the new agentic checkout features, the commerce industry will be changed for both merchants and consumers in the future.

Frequently Asked Questions

  1. What is agentic commerce?

    Agentic commerce refers to commerce in which AI agents are given the authority and technical capability to make purchases without human intervention. This is being implemented by Google Gemini and OpenAI’s ChatGPT.

  2. How are Stripe and Google working together on this?

    Stripe is pairing its Agentic Commerce Suite, which can convert merchant catalogs into machine-readable data, with Google’s Universal Cart, enabling seamless commerce through interfaces like Gemini, Google Search, and YouTube.

  3. Does the merchant still get consumer data?

    Yes, even though the transaction is completed through Stripe + Google, the brand remains the Merchant of Record. This means the merchant retains all revenue, liabilities, and access to customer data.

  4. How does AI pay without risking my credit card information?

    AI agents use tokenization and shared payment tokens to securely process transactions. They are one-time, unique transaction codes generated by the system that cannot be reused; this prevents card data from being stolen or used in fraudulent transactions.

  5. Will AI agents deplete my inventory with fake purchases?

    Modern fraud systems, like Stripe Radar, are being updated to distinguish between authenticated AI agents and fake bots. This prevents fake purchases from being made by your account.

FedNow and RTP

Newtek Bank Turns on FedNow + RTP: What 24/7 Instant Payments Mean for SMBs

Traditional banks shut shop on Saturdays, Sundays, and public holidays. This is an inherent hurdle to merchants that operate 24/7; they are forced to manage their cash flow and payment batches around these holidays. Most merchants have their transactions processed by a method called batch processing. Batch processing is a method in which transactions are grouped and processed in a single batch.

SMBs have always relied on Automated Clearing House (ACH) for payment processing. However, increasing customer expectations, such as 24/7 online ordering and services, force the business to cover operational costs with out-of-pocket expenses.

Having money trapped in processing is the biggest bottleneck for a business. They have to rely on operational reserves to meet the rent and weekly payroll. Newtek Bank’s decision to integrate FedNow and RTP comes at a time when SMBs are suffering from operational delays caused by batch processing.

By adopting instant payments, SMBs can ensure that operational cash reserves are replenished reliably, preventing them from going bankrupt due to day-to-day expenses.

FedNow and RTP: Understanding the Instant Payments Landscape

Instant Payments Landscape

FedNow and RTP are the two biggest payment rails in the United States. RTP, introduced by the Clearing House, is a private, real-time payment network launched in 2017. It is owned by a consortium of some of the largest banks in the United States. On the other hand, FedNow is a real-time payment network launched in 2023 by the Federal Reserve. It was designed to make instant payments accessible to thousands of smaller regional banks across the United States.

To understand the impact of these two entities on the payment system, we first have to understand how payments actually work. There are two distinct processes involved in a payment, i.e., authorization and capture of funds. Consumer apps, such as Venmo or Zelle, authorize payments instantly, but the funds are captured over time. The fund settlement is not instant. On the other hand, FedNow and RTP authorize and capture funds simultaneously. This means the funds are credited to the merchant’s account instantly.

Till now, FedNow and RTP were not interoperable. Interoperability is the ability of two systems to communicate directly with one another. RTP was the first entity in the United States to establish instant settlement of funds. This marked a milestone in the banking system for merchants. However, small merchants often feel priced out or are hesitant to join private networks run by competing banks. To achieve widespread inclusion, the Federal Reserve launched FedNow in 2023, with the main aim of connecting small regional banks to the instant fund settlement ecosystem.

What Does 24/7/365 Settlement Actually Mean?

24/7/365 Settlement

Settlement is the final step in a financial transaction, in which the funds are irrevocably transferred from the sender’s account to the receiver’s account. In traditional wire transfers, payment settles instantly. Now you might wonder, if payments can already be settled instantly, why do we require a completely different payment network?

Although wire transfers are settled instantly, they are limited to Federal operating hours, i.e., they typically close at 06:00 PM EST. Moreover, wire transfers are not processed on Federal holidays. This creates a hurdle for businesses because they have to operate every day. Payments being blocked on certain days and after specific hours every day means the merchant has to schedule their payment-processing requests precisely, which is often not possible due to the highly unpredictable nature of income.

These guardrails provide all-time, instant fund settlement. 24/7/365 settlement means funds will be settled instantly, regardless of whether they are filed on a public holiday or outside business hours. For the receiver, these funds are considered “good funds.” Good funds are money that has fully cleared and is immediately available for the recipient to withdraw, spend, or invest without risk of a bounced transfer.

Why Newtek Bank’s Dual Adoption is a Catalyst for SMBs

You know by now that FedNow and RTP are the two major fund settlement methods for merchants. Newtek Bank’s strategy of integrating these two payment networks is a dual-rail strategy that combines the two major payment rails available to merchants.

A dual-rail strategy is a bank’s decision to integrate and support both the RTP and FedNow networks simultaneously. Since most banking networks and merchants rely on either FedNow or RTP, Newtek Bank’s strategy is to cater to every merchant, regardless of their choice. This makes it extremely powerful in the payment space.

Newtek Bank ensures that any SMB client can reach their full potential by removing restrictions on payment methods. Merchants can now accept payments via FedNow or RTP, which offers unlimited opportunities. But this also means that Newtek Bank holds the opportunity to monopolize the payment game in their favor.

Smart payment routing ensures payments reach the receiver’s bank via the correct instant rail, without hurdles. This positions Newtek Bank as the ultimate operational partner that SMBs adopt to gain an edge over competitors.

Cash Flow velocity: How Instant Liquidity Transforms Working Capital

Instant Liquidity

Cash flow velocity is the speed at which money moves into, through, and out of a business. Old banking systems force merchants to slow the velocity of cash flow. Businesses have to hold cash reserves for 3 to 5 days before incoming payments are even settled into the merchant’s account, and even use that money.

Float is the time between when a payment is initiated and when it is actually settled in the recipient’s account. You can simply understand it as the time between the customer initiates the payment and when you are actually able to spend the money. On the other hand, a key concept for merchants is liquidity. It is the amount of money readily available for the merchant to spend.

Instant payments drastically reduce your float time, which means that funds flow faster into your bank account, and you do not have to wait for fund settlement to meet operational expenses. An increase in liquidity means that the merchant is not forced to take out credit lines to meet their day-to-day operational expenses. While businesses previously used float to their advantage to delay payments, merchants today demand faster, instant settlement of funds.

B2B Vendor Payments and Just-in-Time Funding Strategies

Traditionally, merchants had to schedule and plan their payment processing strategies so that ACH payments and fund settlements were completed by the time the payment was expected. But with FedNow and RTP, merchants can release payments as needed, since funds settle instantly.

This strategy is called Just-in-Time (JIT) funding. It is a strategy in which a business holds onto its cash reserves until the exact moment a bill is due, rather than paying the dues in advance, anticipating their clearance on the expected dates. The newer payment guardrails also reduce the Days Payable Outstanding (DPO). DPO refers to a financial metric that indicates how long a company takes to pay its invoices from trade creditors.

Instant payments allow merchants to take advantage of early-bird discounts while paying vendors. They no longer have to worry about banks closing on weekends or public holidays. Since both FedNow and RTP rely on the ISO 20022 data, the merchant can obtain a unique invoice number to cross-reference every payment they receive, preventing confusion.

Payroll, Gig Workers, and Emergency Disbursements

Instant payments also have human and HR benefits which are particularly useful in the gig economy. Earned Wage Access (EWA) is a benefit that allows employees to access a portion of their accrued wages before the traditional payday. Businesses need to finalize and fund their payroll accounts 3 to 5 days before payday. This was important to ensure the payment aligned with ACH processing times.

On the other hand, disbursements refer to payments made by a business to individuals, such as payroll, expense reimbursements, or insurance claims. Instant payments allow companies to hold payroll until Friday, since funds can be settled at any time. This gives merchants more flexibility and breathing room, allowing them to extend operational liquidity for a few more days each week. For businesses relying on gig workers, the ability to offer immediate payouts is a competitive advantage.

Irrevocable Transactions and New Fraud Risks

These instant transactions are irrevocable, as we defined earlier. Irrevocable transactions are payments that, once set, cannot be canceled, reversed, or recalled by the sender’s bank. This is crucial because it requires meticulous review of the receiver before initiating the payment, because the merchant has no immediate remedy. On the other hand, Authorized Push Payment (APP) fraud is a scam where a criminal tricks a legitimate business employee into voluntarily sending an instant payment to a fraudulent account. Since these payments are irrevocable, the funds once initiated for the transaction can no longer be recovered.

The greatest advantage of instant payments is speed. However, speed is also the biggest risk associated with instant payments. Since funds are settled in seconds, there is very little margin of error. Transactions on the FedNow and RTP networks are permanent and irrevocable. If a business has sent money through this payment network, there is little to no way for them to recover if it results in a loss.

This irrevocability of transactions, as a characteristic of instant payments, has led to a rise in APP fraud. The scammer hacks vendor email accounts and requests payment from the merchant into a separate bank account via instant-settlement payment rails. Since the business has technically authorized the payment, even though it was made under false pretenses, the bank is generally not liable to reimburse the lost funds. This leaves SMBs to deal with risks alone; they must absorb all losses from fraudulent transactions.

Conclusion

FedNow and RTP have successfully eliminated the gap in the payment processing landscape. With Newtek Bank offering combined payment rails, it has successfully captured SMBs and their payment infrastructure. Instant payments shift banking from a delayed administrative process into a real-time strategic advantage. Businesses that adapt early will out-maneuver competitors who are still waiting for checks to clear.

Frequently Asked Questions

  1. What is the difference between FedNow and RTP?

    RTP is the older instant payment settlement institution established and operated by big, private banking institutions. On the other hand, FedNow was launched in 2023 by the Federal Reserve to provide wider access to the instant payment settlement infrastructure for smaller banks.

  2. Are instant payments the same as wire transfers?

    No. Both forms of payment settle funds instantly, but wire transfers have a big disadvantage: they are not processed on weekends and federal holidays.

  3. Can I cancel a FedNow or RTP payment if I make a mistake?

    No, the transactions made through instant payment settlement infrastructure, such as FedNow and RTP, are strictly irrevocable. Once initiated, these transactions cannot be reversed or recovered.

  4. Is Zelle considered an instant payment like FedNow?

    No. Zelle is a consumer application that updates instantly, but the actual settlement of funds between the banks still happens via delayed ACH batch processing.

  5. Do I need new software to send instant payments?

    Yes, you need software compliant with the ISO 20022 standard, the common platform for both FedNow and RTP, to process instant fund settlement through these payment rails.

Agentic Commerce

American Express Pushes for Shared Agentic Commerce Standards: What It Means for Merchants

E-commerce is shifting from human customers to automated, machine-based agent buyers. This disruption in the e-commerce industry calls for a complete restructuring of policies on fraud, checkout, and liability models that merchants rely on. Machine customers are AI programs authorized by the user that can autonomously search, negotiate, and execute purchases without human intervention. On the other hand, agentic commerce refers to an ecosystem where AI agents interact directly with merchant APIs and payment networks to complete shopping workflows.

Traditional e-commerce checkout flows are designed to block automated AI agents. They require humans at every phase, from visually appealing checkout interfaces to multi-factor authentication. With the steady rise of agentic commerce, the rules of legitimacy in online purchases need a complete overhaul.

Machine customers strip away the need for visual branding; the entire process from wanting a product to paying for it relies on a high-intent moment when the customer communicates to the AI agent that they want to purchase something. This means that merchants must shift their focus from optimizing websites for visual appeal to optimizing them for machine-readability.

Checkout policies are designed to flag automated, high-speed purchasing behavior as “malicious” bot activity. Such merchants currently risk losing a major share of customers purchasing via agentic commerce. To solve this, American Express recently launched the Agentic Commerce Experiences (ACE) Developer Kit in April 2026. It established the first major closed-loop framework that allows AI agents to prove their identity and human intent.

What Is Agentic Commerce, and Why Is Traditional Checkout Breaking?

Why Is Traditional Checkout Breaking

Agentic commerce can be simply understood as AI agents searching, navigating, and making purchases on behalf of a human user. Legacy checkout refers to a standard web-based shopping cart. It relies on UI navigation, cookies, manual typing, and human-in-the-loop fraud checks. In agentic commerce, the human user gives their AI agent a budget and a goal, and the AI executes the entire transaction from discovery to checkout across merchant APIs. This happens via delegated authentication. Delegated authentication is the process by which a human legally and securely transfers purchasing power to their AI agent.

Traditional fraud prevention relies on behavioral biometrics, such as typing speed and mouse patterns. When AI agents interact with these legacy checkout interfaces, these systems flag them as “malicious bots” because they act instantly and lack human behavioral patterns. CAPTCHA and active 3D Secure challenges completely block agentic transactions because they require a human to identify pictures or enter one-time passwords, stalling an autonomous workflow.

This technology speeds up the checkout process. However, it creates fragmentation across multiple sessions. This is because AI agents do not rely on cookies or site settings; they constantly jump between API calls, making it difficult for the merchant to track the customer journey using traditional market analytics. Also, merchants are forced to build custom API bridges for different AI agents, such as ChatGPT or Gemini. This creates an unsustainable engineering burden on the merchant’s infrastructure. Moreover, these bridges break repeatedly every time the AI model updates.

The ACE Developer Kit by Amex: Standardizing the Agent Checkout

In April 2026, Amex released its ACE Developer Kit, aimed at resolving the false flagging of authorized AI agents on human-designed merchant checkout interfaces. The Amex ACE Developer Kit is a suite of five integrated services built by American Express. With its ability to verify AI agents, validate human intent, and process autonomous payments securely, it can change the landscape of agentic commerce forever.

The Amex ACE Developer Kit provides a closed-loop network for e-commerce. This means the payment system, i.e., Amex, single-handedly operates the whole ecosystem. It acts as the card issuer, the payment network, and the acquirer, which grants full visibility into both the consumer and merchant sides of a transaction. It functions as different entities, such as Agent Registration, Payment Credentials, and Cart Context.

Agent Registration ensures that only verified, secure AI agents can access payment networks, protecting merchants from malicious bots attempting mass fraud. You can think of Agent Registration as a digital bouncer that verifies an AI agent before allowing it to proceed with the transaction. On the other hand, Payment Credentials is meant to allow cardholders to securely link their Amex cards to their AI agents. This establishes a trusted billing relationship without handing raw sensitive information, such as credit card numbers, to third-party developers.

Cart Context is a digital guardrail that prevents the AI agent from purchasing irrelevant products. It allows the AI agent and merchant to share and lock the basket details before proceeding with the transaction, ensuring the agent is purchasing exactly what the human user wanted. Since Amex is a closed-loop network, it can easily verify the human’s request to initiate the transaction and handle errors on the merchant’s side, allowing the AI agent to proceed.

Intent Intelligence: Proving the Human Actually Wanted to Buy

Proving the Human Actually Wanted to Buy

The biggest problem with agentic commerce is proving the human intent behind an AI agent’s actions when the human is not actively involved in the process. AI agents can “hallucinate”, which could lead to fake transactions. Merchants can cryptographically prove that a human actually authorized a purchase, which solves the biggest risk in agentic commerce.

Intent intelligence refers to the process of capturing, structuring, and cryptographically locking the specific boundaries, such as budget, item, and timeframe, that a human gave the AI agent prior to initiating the purchase. The human intent is verified by a “Proof of Intent Token”. It is a digital receipt that is generated at the start of a request that proves the exact parameters the human user defined for the AI agent to operate within.

Intent intelligence is the technology that translates the human’s commands into a curated set of parameters for the AI agent to understand. For example, if a human commands the AI agent to buy roasted arabica coffee beans, intent intelligence will convert this into a list of constraints, such as budget < $50, specification = arabica, weight = 250 grams. Proof of Intent tokens are generated as soon as the human commands the AI agent to buy something. It allows the payment network to create a locked, verifiable contract that prevents the AI from deviating and buying something unexpected.

During the authorization process, the merchant’s system verifies the items in the cart against the Proof of Intent token, ensuring that the AI did not hallucinate and purchased only the items the human user requested. The structured intent serves as a dispute resolution mechanism. The cryptographic token is the merchant’s defense against a customer claiming not to have ordered the items.

Network Tokenization: Keeping Credentials Safe from Autonomous Bots

Keeping Credentials Safe from Autonomous Bots

Network tokenization is the process of replacing the sensitive 16-digit credit card number with a unique, encrypted token that is transmitted over the network. It securely transfers payment data, applies specific constraints, and prevents information theft if the network is ever breached. Scoped payment credentials are tokens that are artificially limited in time, by merchant, or by monetary value. This prevents token misuse if it is stolen or the AI goes rogue.

Giving the AI agent your credit card number is a huge security risk. Having such sensitive information flow over the network without human supervision could result in financial catastrophes. To prevent this, the 16-digit number is converted to encrypted codes or tokens by a process known as network tokenization. These tokens are single-use, meaning even if the AI’s memory is breached by hackers, the transaction cannot be repeated.

Scoped credentials allow the human user to set specific constraints on the AI agent, such as spending limits. It physically prevents the AI from exceeding the authorized limit, removing the burden of validating the consumer’s budget from the merchant. It also acts as a fallback mechanism if the AI goes rogue or is breached by hackers, by limiting the losses. Network tokens are updated automatically when a card expires or is replaced. This benefits the merchant by ensuring a continuous transaction flow from the consumer, without the burden of handling declines and account updater services.

The Liability Shift: Amex Agent Purchase Protection and Chargebacks

Agent Purchase Protection is an Amex policy introduced earlier this year. It protects cardholders from charges that result from errors made by AI agents, provided that the agent was registered and the intent was authenticated. It is an industry-level safety net; the first line of defense against hallucinations and false purchases made by the AI agent. This explicitly shifts the liability of hallucinations away from both consumers and merchants.

In earlier policy, if an AI made a “hallucinated” purchase, the customer would file a chargeback. This would hit the merchant’s operational reserves, withdrawing the transacted amount and an additional chargeback fee. Under the new Amex framework, if the merchant validates the transaction against the provided Proof of Intent token, they are shielded from the liability of losses arising from “agentic errors.” With the new policy, Amex has forced developers and AI companies to implement stricter checks to verify intent, as payment networks will likely revoke permissions if too many errors occur.

Moving Beyond Fragments: The Push for Interoperability

While Amex has built a closed-loop network, the broader implementation of agentic commerce requires open standards for other AI companies and banks to prevent a monopoly. Interoperability refers to the ability of different AI agents, payment networks, and merchant APIs to communicate with each other. An important policy that helps implement a universal code is the Agent Payments Protocol (AP2). AP2 is an open protocol that standardizes the exchange of structured data queries among AI agents. It is driven heavily by Google and supported by Amex.

It is not realistic for a merchant to maintain separate, proprietary checkout integrations for different AI agents and banks. This would result in fragmentation and an unsustainable burden on the merchant’s digital infrastructure. The AP2 acts as a universal translator, allowing any AI agent, bank network, and merchant API to communicate seamlessly.

Amex is actively contributing to open standards. This is because Amex is aware that the ACE Developer Kit’s wide adoption is only possible if it expands into the broader agentic commerce market.

Conclusion

Agentic commerce is shifting e-commerce from visually appealing workflows to heavily optimized machine-readable query transfers. Amex’s ACE Developer Kit and AP2 are setting industry benchmarks for security and optimization in agentic commerce. Merchants who optimize their APIs for broader agentic implementation will see sustained growth and revenue inflows in the emerging field of agentic commerce.

Frequently Asked Questions

  1. What are Amex agentic commerce standards?

    They are a set of rules and developer tools created by Amex to securely authenticate agentic transactions, verify human intent, and execute autonomous payments originating from legitimate sources.

  2. How does the Amex ACE Developer Kit work?

    The ACE Developer Kit is a suite of five different tools developed by Amex. These tools allow Amex to build a closed-loop network that serves as both a payment network and the developer infrastructure behind a transaction for both the consumer and merchant sides.

  3. How do merchants stop blocking legitimate AI shoppers?

    Merchants must update their legacy fraud systems to stop relying on human behavioral metrics and instead use cryptographic authentication to whitelist registered, secure AI agents.

  4. What is a Proof of Intent Token?

    It is a cryptographic receipt generated before the AI agent initiates a transaction with the merchant API. It serves as a reference to verify that the purchase made by the AI agent matches the product requested by the human user.

  5. How do AI agents actually browse a merchant’s store?

    AI agents entirely skip the merchant’s website and interact with merchant catalogs via APIs. To rank higher, the merchants must optimize their catalogs for AI readability.

Rental Software Costs

Booqable vs EZRentOut vs Point of Rental: Real Cost For Small Fleets

Choosing a rental software solely on the basis of the monthly subscription price is a grave mistake. Software as a Service pricing refers to a subscription-based model in which you rent software for a monthly fee. Most business owners make the mistake of choosing software solely based on advertised prices, without fully considering the total monthly cost of using it.

The rental software costs for most solutions available in the market is almost always different from the sticker prices advertised by software companies. The total cost of ownership (TCO) of software is the actual amount a business pays for it at the end of the month.

Payment processing fees contribute significantly to software costs. Software that costs a fixed, low monthly subscription may end up costing twice or three times the base price at the end of the month when processing costs are added.

The need to buy rental software is that it enables you to streamline your operations, helping you get paid faster, prevent slot clashes, and eliminate manual labor in data entry. Small fleets require software to survive. This is because they lack backup options if things go awry. Thinner profit margins with small fleets mean that every software failure impacts their operational reserves.

In this article, we will explore the three most popular rental management software — Booqable, EZRentOut, and Point of Rental. This will allow us to see which software is the best for managing a small fleet.

Why Rental Software Costs Impact Profit More Than You Think

Why Rental Software Costs Impact Profit

Fleet utilization rate is defined as the percentage of equipment that has been rented out of the total equipment in your inventory. This gives you an insight into the health of the business. A higher utilization rate means better cash flow.

You should understand that equipment must be rented out to generate ROI. Having software that cannot track availability efficiently results in more idle time for equipment in the inventory. Cheap software does not completely automate data entry. The staff has to manually enter customer details from the website into the software, which introduces scope for error and causes delays.

Software also tracks equipment maintenance. Repairing and servicing equipment before it breaks down completely saves time and money. Routine maintenance alerts prevent catastrophic breakdowns, preventing immediate revenue loss.

For most businesses, the checkout page is where most customers abandon. Software provides a clean interface and reduces friction in payment processing, making the checkout process easier for the customer. It also saves staff and admin time by eliminating the need to chase invoices or delayed payments. Automating the booking process prevents double booking, ensuring customer trust and satisfaction.

A Quick Overview of Booqable, EZRentOut, and Point of Rental

E-commerce native stores are online storefronts built with a focus on the customer-facing interface. Booqable is heavily focused on the customer-facing experience and online storefronts. You can understand Booqable as the Shopify for rental businesses. Booqable makes websites very attractive and primarily caters to event, camera, and bike rentals — basically, Booqable is used for rentals that need to display an online aesthetic to secure bookings.

EZRentOut is a platform based on heavy-duty tracking. It is used by businesses that need heavy asset tracking. It primarily caters to B2B businesses, such as tool, AV, and heavy machinery companies. It is used to track depreciation, GPS location, and maintenance logs. EZRentOut is built for organizations that take asset tracking more seriously than a pretty-looking customer interface.

For businesses that need more robust and scalable systems to manage their rental inventory, Point of Rental is the ideal choice. It is deeply rooted in complex rental logistics. With a design built to manage complex dispatch routing, job costing, and multi-location inventories, it caters to the needs of industry giants.

To summarize, Booqable is built for speed and aesthetics. On the other hand, EZRentOut is built for asset accountability, while Point of Rental is built for industry giants requiring deep tracking.

Pricing Models: Subscriptions, Per-User Fees, Add-Ons, and Transaction Costs

Pricing Models Explained 1

Software companies use multiple pricing models to generate revenue. Per-user licensing is a pricing model in which monthly fees are capped at a set number of users, and adding more users requires an additional payment. A payment gateway fee is the percentage-based charge that payment gateways levy on every credit card payment made by the customer.

Base subscriptions are the pre-defined plans offered by the software company for a set sticker price. Often, these plans impose usage limits on the company, such as the number of users or vehicles that can be tracked using the software.

The per-user pricing model is the most expensive in the long term. Rental companies buy software based on the advertised low sticker price. The final bill at the end of the month can rapidly inflate if your staff increases, such as warehouse staff, delivery staff, and counter clerks, who all need to have access to the software.

Certain features, such as API integrations, are often locked behind paywalls. These can inflate your bill significantly because most software companies offer features such as marketing, automated GPS tracking, and fleet maintenance tracking as add-ons — they carry extra charges for every feature that the rental company needs.

Transaction and processing fees are another major percentage charged on every transaction. Some software allows rental businesses to integrate with third-party payment gateways, but some only allow white-label payment processors. The rates on these gateways vary widely and must be taken into account when calculating total costs.

While lower-tier SaaS products allow you to migrate data to their platform for free, some higher-tier software providers charge a mandatory fee as an onboarding fee.

Real Cost Breakdown for Small Fleets

Booqable: Real Cost Breakdown for Small Fleets

Website integration is the ability to embed the rental software into the rental business’s pre-existing website, so customers never leave your branded site to complete a booking. On the other hand, API access refers to a digital bridge between software platforms and native business websites that facilitates operations, such as sending sales data directly to a custom CRM.

Booqable offers multiple plans for different phases of a rental business, including Start, Grow, and Scale.

The “Start” Plan starts at $29 per month. It is an entry-level tier that allows a cheap entry point for businesses to use the software. It offers basic inventory and a booking page, but it is strictly limited to small operations that do not need advanced custom features, such as website integration or multiple staff accounts.

The “Grow” Plan is offered at $69 per month and includes the realistic features most rental businesses require. It offers custom website integration and 5 additional user accounts, making it highly effective for small teams.

Lastly, the “Scale” plan, offered at $149 per month, is the ultimate option for easy scaling. With features such as multi-location support, API access, and 10 extra users, it allows scaling within an affordable software budget.

Booqable is very affordable; however, it lacks some advanced features, such as deep account integrations, and requires higher tiers for basic logistics, which businesses outgrow easily.

EZRentOut: A Slightly Heavy Alternative to Booqable

EZRentOut offers certain newer features, such as sub-renting and cycle billing. Sub-renting refers to the practice of renting equipment from a third-party competitor to fulfill a customer’s order when your own inventory is fully booked. On the other hand, cycle billing is the practice of automatically billing a customer on a recurring basis, such as every 28 days, for a long-term rental, rather than a single upfront charge.

The “Essential” plan by EZRentOut starts at $59 per month and is the entry-level plan offered for small businesses. It offers basic bookings and B2B customer management, but it is just a sticker price. For features such as credit card payments and customer portals, the business has to pay extra charges to the company. On the other hand, the “Growth” plan, at $399 per month, represents a massive price jump. In this tier, the software becomes fully functional, unlocking features such as online credit card payments, a rental webstore, and custom reports.

On the other hand, EZRentOut offers a “Premium” plan at $499 per month. This premium tier unlocks crucial B2B features such as QuickBooks integration, sub-renting, work orders, and cycle billing.

There is also a custom Enterprise tier from EZRentOut that includes multi-site support, custom roles, and advanced GPS tracking. This tier requires contacting the sales team, which means costs will scale for large operations.

Point of Rental: The Enterprise Grade Solution for Rental Businesses

There is a fundamental difference between on-premise and cloud deployment. Cloud deployment uses cloud-based services that run over the internet and are subscription-based. On the other hand, on-premise software is installed directly on your company’s local servers. On-premise offers total control, but requires the business to hire an entire IT department to manage the servers.

Point of Rental does not display any public pricing plans. They offer customized, quote-based plans for every rental business, tailored strictly to deployment type, industry, and volume. Dispatch and logistics are complex processes of scheduling trucks, calculating load weights, and optimizing routes for heavy equipment.
Point of Rental offers included value with their pricing — businesses often get volume-based discounts on pricing plans. While the starting price is generally higher, it is justified by premium capabilities such as ERP-grade workflows. Point of Rental offers businesses to build bespoke websites with deep customized features that align with customer experience and brand identity.
With their 40+ years of experience in the rental management space, their support teams and workflows are highly capable of solving every query that arises in your business. Their teams actually understand the business, resulting in thousands of dollars in savings from costly downtime.

Conclusion

Software must not be seen as an operational overhead, but it also should not be seen as a full-time employee for your business. In reality, software is a smart assistant that assists in business optimization and growth.

Booqable is the easiest, simplest, and lightest software for businesses just starting out. On the other hand, EZRentOut is a great option for small rental businesses that need software to streamline day-to-day operations and offer certain advanced features. For enterprise-grade rentals, Point of Rental is the ideal choice, as these businesses can leverage their transaction volume to secure discounted rates. Choosing the right software helps you streamline daily operations and sustain your business’s growth without reckless spending or relying on guesswork.

Frequently Asked Questions

  1. Is Booqable good for heavy equipment rentals?

    No. While Booqable is lightweight and easy to set up, it is not suited for heavy equipment rentals.

  2. Does EZRentOut integrate with QuickBooks?

    Yes, the higher tiers of EZRentOut allow you to integrate the software with QuickBooks, so you can manage your accounts and CRM in one place.

  3. Why doesn’t Point of Rental show prices publicly?

    Point of Rental builds highly customized, ERP-grade systems for every client they serve. That is why they do not have standard pricing tiers, as pricing depends heavily on the client’s requirements and the volume they process.

  4. Can I use Booqable if I already have a WordPress site?

    Yes. Booqable is specifically designed to embed its booking engine seamlessly into existing websites, including WordPress and Squarespace, via simple integration codes.

  5. Which software is best for managing long-term, recurring rentals?

    Based on our review, EZRentOut and Point of Rental are the ideal software for managing long-term, recurring rentals because of features such as sub-renting and cycle billing.