Qlarifi

BNPL Evolution: Socure’s Qlarifi Acquisition Aims to Make Buy Now Pay Later Safer

The buy now, pay later (BNPL) boom is entering a new phase of maturity – and with that, growth comes a pressing need for better credit risk and fraud prevention infrastructure. BNPL has quickly grown into one of the fastest-scaling consumer credit products globally, now accounting for nearly 6% of U.S. e-commerce spending and expected to surpass $700 billion in global transaction value by 2028. Yet this rapid rise has exposed gaps in the financial system.

Many BNPL loans go unreported to traditional credit bureaus, leaving lenders blind to a consumer’s overall BNPL debt burden. BNPL obligations often become “phantom debt” hidden from view, leading consumers to overextend themselves beyond what other lenders or credit reports reveal. Socure’s recent acquisition of Qlarifi aims to create the industry’s first unified platform for BNPL credit scoring, identity verification, and fraud prevention.

The Rapid Rise of BNPL and Its Growing Pains
Rise of BNPL

BNPL services – which let shoppers split purchases into interest-free installments – have exploded in popularity in recent years. Consumers have flocked to BNPL for its convenience and zero-interest appeal, driving more than 20% annual growth in BNPL usage in markets like the U.S. By some estimates, BNPL already makes up nearly one in every sixteen online retail transactions in the U.S., and global BNPL spending is on pace to top $700 billion by 2028.

However, BNPL’s breakneck growth has come with significant growing pains. Unlike traditional credit products, BNPL plans are typically not fully captured in consumers’ credit reports or FICO scores. In fact, many BNPL providers have no obligation to report these short-term installment loans to credit bureaus, and until recently, most chose not to. This lack of reporting means a shopper could rack up multiple BNPL debts with different services, yet each lender sees only its own slice of the picture.

Other creditors – and even the consumers themselves – may not realize the true extent of their obligations until bills come due. Because most BNPL loans aren’t reported to bureaus, they can become “phantom debt” that flies under the radar. The result is a heightened risk of overextension: some buyers end up borrowing more than they can realistically repay by taking on many small installment plans across various apps.

Another consequence of BNPL’s light oversight is first-party fraud. With minimal credit checks and quick online approvals, BNPL has been vulnerable to abuse by malicious actors or indebted consumers. First-party fraud refers to instances in which the buyer commits fraud – for example, obtaining goods via BNPL with no intention of paying, or using multiple identities to circumvent limits. BNPL providers have reported that loan stacking (opening numerous BNPL loans concurrently across different platforms) and deliberate defaults have led to mounting losses in some cases.

Merchants, too, can face higher fraud-related chargebacks under BNPL if these risks aren’t managed. All of this has raised alarms because BNPL’s traditional selling point was that default rates were low, but cracks begin to show when the economy or consumer finances tighten.

Crucially, legacy credit infrastructure has not kept up with the BNPL phenomenon. Conventional credit scoring and reporting systems were never designed for the high-frequency, small-dollar, instantaneous lending decisions that BNPL entails. Credit bureaus have struggled to ingest and interpret the flurry of micro-loans and BNPL transactions, which often use different data formats and shorter durations than typical loans.

As a result, the underlying infrastructure to support responsible BNPL lending has lagged behind its popularity. Lenders lack real-time visibility into a borrower’s aggregate BNPL exposure across providers, and positive BNPL repayment history doesn’t easily translate into credit-building for consumers. Recognizing these shortcomings, regulators and consumer advocates have put pressure on the industry to improve oversight. Regulators in multiple countries have signaled that BNPL firms must implement stronger credit checks, clearer disclosures, and data-sharing practices to prevent consumer harm.

In the U.S., for example, regulators have clarified that many BNPL loans fall under existing credit card rules, meaning providers must offer dispute rights and other protections akin to those in traditional credit. In the U.K. and elsewhere, authorities are exploring new rules to ensure lenders assess affordability and report BNPL loans in some fashion.

Socure’s Vision: Marrying Identity Verification with Credit Risk Data
Identity Verification

Socure is a leading digital identity verification and fraud prevention company that has made its name helping financial institutions confirm who their customers are in real time. Founded in 2012 and based in New York, Socure provides an AI-driven platform that leverages machine learning and massive data (online and offline) to verify identities with high accuracy. It helps banks, fintechs, and online merchants automatically approve legitimate customers quickly while flagging identity thieves or suspicious applicants.

The company’s Socure ID+ product and its Identity Graph engine analyze thousands of data points to assess whether an identity is real and whether the person behind a transaction is who they claim to be. Socure has over 2,000 clients, including top banks, card issuers, and fintech firms, making it a major player in the fraud prevention and KYC (Know Your Customer) space.

In recent years, Socure has expanded its mission beyond verifying identities at account opening. It’s pushing into broader “risk decisioning” – essentially using data and AI to make automated judgments about fraud risk and creditworthiness. Socure’s platform, which includes a risk-decision engine called RiskOS, is part of this evolution.

Socure acquired the AI risk decisioning startup Effectiv in 2024, signaling its intent to expand into credit risk and compliance decision-making. The ultimate goal for Socure is to become a full-stack decisioning platform that spans identity verification, fraud prevention, anti-money-laundering checks, and credit underwriting.

Against this backdrop, the BNPL sector presented a natural next frontier for Socure. BNPL providers were facing identity-related fraud (such as synthetic identities or repeat offenders using multiple accounts), and they were facing credit risk issues (like loan stacking and overextended borrowers) – a combination of problems that straddles Socure’s expertise in fraud detection and the broader domain of credit risk analytics.

Socure’s founder and CEO, Johnny Ayers, has said that BNPL has outgrown legacy systems that were never built to support innovative lending products. He emphasizes that lenders need real-time visibility to lower fraud and credit risk, while regulators are calling for greater transparency. Socure saw an opportunity to bring BNPL into the modern risk management fold by uniting identity and credit data into a single solution.

Qlarifi – A BNPL-Focused Credit Database Built by Industry Insiders
BNPL-Focused Credit Database

To address BNPL’s unique challenges, a specialized approach was needed – and that’s where Qlarifi comes in. Qlarifi is a fintech startup (founded in 2023 and based in the UK) that built one of the first real-time BNPL consumer credit databases. Notably, Qlarifi was founded by veterans from BNPL giants Klarna and Zip, people deeply familiar with the inner workings and pain points of the buy-now-pay-later model. Having witnessed how borrowers could juggle multiple BNPL plans across different providers, the Qlarifi team set out to create a consolidated view of BNPL usage that any lender could tap into.

Qlarifi serves as a central repository of BNPL repayment behavior. It aggregates data on consumers’ BNPL transactions and outstanding installment plans across participating BNPL services. By tracking a shopper’s BNPL activity in real time (across many providers), Qlarifi can provide an underwriting risk score or report that reflects that person’s total BNPL exposure and payment history. Say a customer has four active BNPL loans across various apps, a lender checking Qlarifi’s database would see the combined debt and whether the customer has been paying on schedule. This information would traditionally not be visible to any single BNPL provider or to credit bureaus in a timely manner.

According to the company, Qlarifi was designed to give BNPL lenders the insight needed to safely expand services for trusted customers while pinpointing high-risk behavior such as loan stacking and fraud. It helps answer questions like: Is this applicant trying to take out more BNPL loans than they can handle? Has this person defaulted on other BNPL plans recently? Is someone opening multiple BNPL accounts under slightly different identities?

By flagging these scenarios, Qlarifi’s data enables lenders to make more informed underwriting decisions and avoid extending credit to overextended or risky borrowers. It also helps protect consumers from themselves – preventing well-meaning shoppers from accidentally overextending by hopping between BNPL services to get more credit.

Qlarifi’s approach essentially fills the void of a “BNPL credit bureau.” In fact, industry observers have called it the first serious attempt at a purpose-built credit bureau tailored to BNPL’s small-ticket, instant loans. By mid-2025, Qlarifi had launched its platform (after raising a £1.4 million pre-seed round) and was already piloting it with several BNPL providers in Europe. Those pilot programs demonstrated the efficacy of sharing BNPL repayment data among lenders: participating providers could spot when a user had multiple buy-now-pay-later plans and could adjust their lending decisions accordingly.

Early results indicated that such data sharing can indeed reduce default rates and fraud incidents. As Qlarifi co-founder and CEO Alex Naughton explained, the company was created to address a clear pain point: the absence of infrastructure that prevents consumers from overextending themselves across multiple BNPL providers.

The First Unified BNPL Credit & Fraud Platform: Why the Socure–Qlarifi Deal Matters
Socure–Qlarifi Deal

In December 2025, Socure announced it had acquired Qlarifi for an undisclosed sum, with the goal of creating a unified system that combines identity verification, fraud detection, and BNPL credit scoring. It’s a combination that could redefine risk management for BNPL providers.

At a high level, it will tie Qlarifi’s real-time BNPL repayment data directly into Socure’s Identity Graph and RiskOS decisioning engine. This means when a consumer applies for a pay-later plan at checkout, the lender can (with one integrated service call) simultaneously:

  • Verify the customer’s identity – Confirming they are a real person and not a fraudster or banned user, by using Socure’s AI-based identity verification and device/behavioral analytics.
  • Check the customer’s BNPL credit exposure – Query Qlarifi’s database to view the person’s current outstanding BNPL loans, recent BNPL repayment history, and any risk flags (e.g., multiple active loans or past delinquencies).
  • Assess fraud and credit risk in real time – Using Socure’s RiskOS, the combined data is analyzed to produce an instant decision or score. Good customers with manageable BNPL debt and a verified identity can be approved in seconds. Risky profiles – say, someone who already has several unpaid BNPL plans or whose identity mismatches known records – can be flagged or declined just as fast.

This unified approach addresses the blind spots that existed when identity and credit data were siloed. Previously, a BNPL lender might verify an applicant’s identity but still have no clue how many other BNPL debts they had. Or conversely, a lender might use rudimentary credit checks but not catch if the identity itself was manipulated.

Now, by linking identity and BNPL-specific credit signals, the lender gets a holistic risk view of the applicant across the BNPL ecosystem.

According to Socure, this combined platform can have a dramatic impact on fraud and losses. By spotting issues such as loan stacking, overextension, and first-party fraud across providers in real time, the system is expected to significantly reduce bad debt. In fact, Socure claims that integrating Qlarifi’s data will allow BNPL lenders and merchants to reduce first-party fraud losses by up to 70%. It suggests that a large portion of current BNPL fraud losses stems from borrowers exploiting the lack of cross-platform visibility.

If true, a 70% reduction would not only save providers money, but also deter would-be fraudsters once they realize this networked visibility exists. Importantly, it’s not just about fraud: the unified system should also reduce credit losses (defaults) by preventing over-lending to consumers who already have multiple outstanding plans. For consumers, this could translate to fewer instances of getting approved for more installments than they can juggle, thereby avoiding financial distress.

Another benefit is speed and cost. BNPL is all about instant decisions at the point of sale – any risk management solution for this space must operate in milliseconds. Socure’s API-driven platform is built for real-time checks, and Qlarifi’s data is updated in real time as well. The vision is that, even with an extra layer of cross-provider credit checks, BNPL apps won’t sacrifice their quick, seamless user experience. Lenders can say “yes” to good customers faster and with more confidence because fewer manual reviews and less uncertainty are involved.

Meanwhile, truly risky applicants can be screened out before a loan is ever approved, rather than the lender discovering issues after the fact. Socure also noted that by automating these checks and using a consortium model (many lenders contributing data), the platform can reduce the operational costs of credit scoring and fraud detection for BNPL providers. Smaller or newer BNPL players, who might not have sophisticated in-house risk analytics, can essentially plug into Socure-Qlarifi’s “risk brain” to get instant fraud screening and credit insights for applicants.

From an industry perspective, the Socure-Qlarifi deal signals a shift towards collective risk management. It’s creating something akin to a BNPL credit bureau + fraud consortium in one. Each lender that joins the platform contributes data (with appropriate privacy safeguards) and, in return, gains a fuller picture of consumer risk across the network. This kind of shared intelligence is common in areas like credit cards (credit bureaus) and bank fraud (shared blacklists, fraud consortiums), but it’s new to BNPL.

Trusted BNPL users who always pay on time might benefit, as their positive history will be visible, potentially earning them access to larger purchase approvals or better terms over time. Meanwhile, the serial BNPL abusers will find it harder to game the system since all providers they apply to will see the same red flags.

Toward a More Responsible BNPL Future

Responsible BNPL is gaining attention as scrutiny of the sector increases. The idea is simple: a product built on easy, fast credit now needs controls similar to traditional lending to remain viable. The Socure–Qlarifi initiative supports this shift by adding shared visibility across BNPL providers, helping prevent consumers from taking on excessive debt while meeting regulator and consumer advocate expectations.

For consumers, this means stronger protection and clearer limits. Lenders can see existing BNPL obligations and missed payments before approving new plans, reducing the risk of debt piling up across multiple providers. It also creates a path for people with little or no credit history to build a positive record through responsible BNPL use.

Regulators also benefit from improved transparency. A unified view of BNPL exposure allows clearer reporting on borrower behavior, defaults, and overall risk, addressing long-standing concerns about hidden aggregate debt. This proactive approach may help BNPL avoid the reputational issues faced by other high-risk credit products.

BNPL providers gain commercially as well. Better risk controls reduce fraud and losses, which is critical in a low-margin model. Shared infrastructure also simplifies compliance and lowers the cost of meeting tighter credit standards, making responsible BNPL easier to offer at scale. Together, these changes point to a more mature phase for the industry, where BNPL operates as a regulated, integrated part of consumer credit rather than a standalone alternative.

Conclusion

The acquisition of Qlarifi by Socure signals a shift in the BNPL industryis evolution. After a long period of rapid expansion, BNPL providers are now facing the obligations that come with operating at scale as lenders. By pairing Qlarifi’s BNPL-focused credit data with Socure’s identity verification and fraud prevention technology, the combined platform points toward a higher bar for risk management and accountability. Lenders gain clearer insight into a borrower’s overall obligations and repayment behavior, supporting more disciplined credit decisions. At the same time, consumers benefit from added safeguards against taking on debt they cannot afford and from clearer pathways to building credit through responsible BNPL use.

The deal also helps close a trust gap that has drawn attention from regulators. It demonstrates that fintech innovation can extend beyond user experience to include the underlying systems that support transparency and risk controls. This moment may come to be seen as when BNPL matured, moving away from fragmented data and unchecked growth toward shared infrastructure and stronger oversight. If Socure’s Qlarifi-based solution delivers measurable reductions in fraud and defaults, it could serve as a benchmark for the rest of the market. Other providers may follow with similar partnerships, and regulators may gain greater confidence in BNPL’s role within the broader financial system.

Frequently Asked Questions

Who are Socure and Qlarifi?

Socure provides digital identity verification and fraud prevention for banks and fintechs. Qlarifi is a BNPL-focused startup that analyzes a shopper’s buy-now-pay-later activity to assess credit risk and repayment behavior.

Why did Socure acquire Qlarifi?

The acquisition fills a gap in BNPL risk management by combining identity verification with BNPL-specific credit insights. Together, they help BNPL providers assess both who the customer is and whether they can responsibly take on another installment plan.

How does the combined platform reduce BNPL fraud and defaults?

It checks identity, reviews BNPL repayment history, and flags overextension in real time. Providers can then approve, limit, or decline transactions based on a fuller risk picture, reducing first-party fraud and missed payments.

What does this mean for consumers using BNPL?

Approvals may include slightly stronger checks, especially for users with many active BNPL plans. Responsible customers should see little change, while overextended users may face limits that help prevent debt buildup.

Is this part of a broader shift in the BNPL industry?

Yes. BNPL is moving toward more responsible lending with better underwriting, increased reporting, and regulatory readiness. The deal reflects a push for sustainability as the sector matures.
Fifth Third Commercial Card

Big Bank + Fintech: Fifth Third Taps Brex to Power New AI-Driven Commercial Card

Fifth Third Bank has partnered with Brex to launch a new commercial card that gives the bank’s commercial banking clients direct access to Brex’s intelligent finance platform. Through the Fifth Third Commercial Card powered by Brex, clients can issue corporate cards, automate expense management, enable real-time payments, and leverage AI-powered agents to reduce manual review while strengthening spend control, the companies announced in a December 9th 2025, press release.

Built on Brex Embedded payments infrastructure, the card will become Fifth Third’s default commercial card solution for its commercial banking clients.

Key Takeaways
  • By making the Brex-powered card the default solution for commercial clients, Fifth Third is shifting a foundational banking function onto an external platform rather than running it as a standalone in-house product.
  • The value proposition centers on reducing manual finance work, expense review, reconciliation, and controls. By embedding automation directly into spend workflows, rather than layering reporting tools on top of traditional cards.
  • Access to a meaningful share of U.S. commercial banking clients through Fifth Third gives Brex a faster path to adoption than selling company by company, while keeping the bank as the primary client relationship.
  • Instead of rebuilding legacy card and payables systems internally, Fifth Third is relying on embedded fintech infrastructure. It shows a model that other regional and national banks may follow to stay competitive.

Fifth Third Commercial Card with Brex Signals a Shift in How Banks Deliver Corporate Card Programs

Fifth Third Commercial Card

Corporate card programs are becoming less about the plastic and more about the operating system behind spend. Fifth Third Bank’s new partnership with Brex is a clear example of that shift. On December 9, 2025, the two companies announced the Fifth Third Commercial Card powered by Brex, giving Fifth Third’s commercial banking clients access to Brex’s finance platform for card issuance, expense workflows, and payments.

For many mid-market and enterprise finance teams, the pain points are familiar – employees spend across dozens of categories and geographies, receipts arrive late (or not at all), approvals happen over email, and month-end reconciliation becomes a recurring scramble. Traditional card programs often deliver basic reporting, but they can fall short on automated policy enforcement, real-time controls, and clean data flowing into accounting systems. Fifth Third’s approach here is to offer a card program coupled with tooling that aims to reduce the manual work that typically sits around business spend.

The practical change for Fifth Third commercial clients is that they can issue corporate cards, automate expense management, and make real-time payments within the Brex platform, alongside AI agents designed to reduce manual review and help enforce spending controls. Rather than treating expense review as a fully after-the-fact process, the intent is to address common issues earlier in the workflow through tighter rules, faster categorization, and automated approval routing.

The partnership is also meaningful from a product architecture standpoint. The new offering is built on Brex Embedded payments infrastructure and is expected to become the default commercial card solution for Fifth Third’s commercial banking clients. That signals a broader industry trend: banks increasingly rely on fintech partners to modernize commercial card and payables capabilities without undertaking multi-year rebuilds of legacy platforms.

Tim Spence, Chairman, CEO, and President of Fifth Third Bank, said the partnership reflects a shift in what businesses need from financial platforms: not just payment processing, but tools that support operational efficiency and growth. He noted that combining Fifth Third’s banking capabilities with Brex’s AI-based technology is intended to simplify complex workflows, improve control and visibility, and help companies scale more effectively, including across global operations.

Pedro Franceschi, CEO of Brex, said Fifth Third shares Brex’s view that businesses increasingly expect financial tools to be proactive and intelligent, not purely transactional. He added that the partnership expands Brex’s reach to a meaningful portion of the U.S. commercial banking market and enables broader delivery of automated, AI-enabled finance capabilities. Together, the companies aim to provide commercial teams with faster processing, more consistent expense management, and tighter integration with the bank relationship clients already rely on.

In day-to-day terms, organizations evaluating a program like this should focus less on the headline “AI” and more on what it changes operationally. The value typically shows up in a few places:

  • Fewer hours spent chasing receipts, coding expenses, and correcting submissions
  • Clearer policy controls at the point of spend (limits, merchant restrictions, approval routing)
  • Faster month-end close due to cleaner, more complete transaction data
  • Better visibility for finance leaders into spend patterns and anomalies as they happen

There are also second-order effects worth paying attention to. When expenses are categorized consistently and matched to documentation earlier, finance teams can spend more time on analysis and forecasting rather than transactional clean-up. And when rules are enforced systematically, compliance becomes less dependent on individual reviewers remembering policy details under time pressure.

It’s also notable that Fifth Third’s corporate card program, which had been operated in-house, will be powered by Brex under this arrangement. This is an important reminder that partnerships like this are not just product launches; they can represent a foundational shift in how a bank runs a core commercial offering.

Bridgit Chayt, Head of Commercial Payments at Fifth Third, said the partnership brings together Fifth Third’s banking capabilities and Brex’s AI-enabled technology to streamline commercial finance operations. She emphasized that the combined platform is designed to automate routine workflows, improve real-time visibility into spending, and reduce manual work that often slows finance teams. The goal is to give businesses faster insight, stronger controls, and tools that can support growth across regions, allowing teams to spend more time on decision-making rather than reconciliation.

Art Levy, Chief Business Officer at Brex, said the partnership expands access to Brex’s AI-native finance tools for a broader set of commercial businesses. He noted that features such as automated spend controls, real-time reporting, and AI-assisted receipt capture and accounting are intended to reduce administrative effort and help finance teams close books more quickly. Together, the companies aim to support tens of thousands of businesses with more efficient, reliable spend and expense management connected to an established banking relationship.

For clients, the right questions now are pragmatic.

How well does the workflow integrate with current accounting and ERP tools?

What approval structures can be mapped directly into the platform without workarounds?

What data controls and audit trails are available, especially if AI-driven automation is part of the review process?

And what will change for employees submitting expenses on day one?

About Fifth Third

About Fifth Third

Fifth Third Bancorp is a U.S.-based financial services company headquartered in Cincinnati, Ohio, providing a broad range of banking solutions to consumers, businesses, and government clients through its branch network and digital channels. The bank’s capabilities span retail and commercial banking, lending, treasury and cash management, payments, commercial card programs, and wealth and asset management, with a focus on supporting middle-market and larger enterprises through financing, liquidity management, and operational banking services.

Fifth Third is a regulated U.S. bank publicly traded under the ticker FITB, combining core banking services with continued investment in technology and partnerships to enhance the customer experience and modernize commercial finance.

About Brex

About Brex

Brex is a U.S.-based financial technology company founded in 2017 that provides corporate cards and software to help businesses manage spending, expenses, and payments. Its platform typically includes tools for issuing cards, automating expense reporting and approvals, managing bills and reimbursements, and connecting spend data to accounting workflows, with additional capabilities such as travel and cash management products offered through partner institutions.

Brex operates as a fintech (not a bank) and is used by a range of companies looking to reduce manual finance work, improve real-time visibility into spend, and strengthen controls across teams and locations.

Conclusion

Taken together, Fifth Third’s partnership with Brex reflects where commercial cards are headed: spend management as an integrated finance function, not a standalone payment method.

For organizations that feel stuck between legacy card programs and piecemeal expense tools, this embedded model offers a path to consolidate controls, simplify operations, and improve financial visibility without asking the finance team to work harder just to keep up.

Frequently Asked Questions

  1. What are Fifth Third and Brex doing together?

    Fifth Third is launching a new commercial credit card program powered by Brex’s technology. The card will be Fifth Third–branded but run on Brex’s card issuance and spend management platform.

  2. What new capabilities will Fifth Third’s business clients get?

    Clients will gain virtual cards, real-time spend controls, and built-in expense management with automated receipt matching and categorization. Finance teams can track spending instantly and streamline close and reporting.

  3. Why did Fifth Third partner with Brex instead of building in-house?

    Partnering lets Fifth Third deliver a modern solution much faster than building from scratch. Brex already has proven technology, while Fifth Third brings scale, trust, and banking relationships.

  4. What does this partnership mean for Brex?

    It gives Brex access to a large base of traditional commercial banking clients and validates its embedded finance strategy. Brex expands distribution while earning revenue behind the scenes.

  5. Is this part of a larger banking trend?

    Yes. More banks are partnering with fintechs to quickly modernize their products. This deal reflects a broader shift toward bank–fintech collaboration and embedded financial technology.

NMI Business Capital

Embedded Lending Takes Off: Inside NMI’s New “Business Capital” for Merchants

In recent years, embedded finance – the integration of financial services into non‐financial software – has exploded. Platforms that serve small businesses now routinely bake in loans, payments, banking, and insurance tools. This trend is putting SMBs at the forefront of the financial landscape by giving merchants instant access to credit as part of their day-to-day operations.

Small merchants prefer one-stop solutions rather than juggling banks, money apps, and spreadsheets. In fact, a study finds that 88% of U.S. small businesses report regular cash flow disruptions. With so many Main Street firms living hand-to-mouth, offering loans directly in the software they already use is a powerful idea.

Many small merchants could benefit from built-in financing offers like the NMI Business Capital, right in the software they use to manage sales and payments.

Why NMI’s Move Matters

NMI

Image source

NMI – a leading provider of embedded payments infrastructure (often white‑labelled by banks, ISOs, and software platforms) – has now stepped into lending with its NMI Business Capital program. Launched in late 2025, Business Capital lets NMI’s partners (banks, ISOs, SaaS providers, payment facilitators, etc.) embed pre‑approved working‑capital loans into their merchant portals.

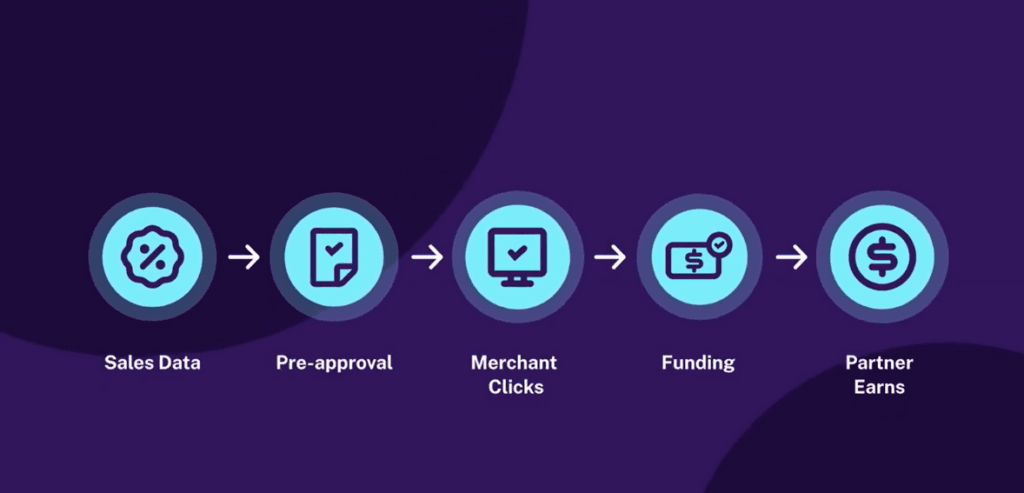
A merchant logging into their NMI-powered dashboard will see a simple loan offer based on their recent sales. The key promise is speed and simplicity, with no lengthy applications or credit checks to bog down the process.

By integrating funding into the existing payments portal, NMI aims to let merchants close their financing gap without switching systems. As NMI Chief Growth Officer Peter Galvin explains, with 88% of small businesses reporting ongoing cash flow disruptions, access to funding is more important than ever. Embedded funding within the platforms merchants already use removes much of the friction and administrative burden associated with traditional lending. Instead of forcing a merchant to leave the platform and hunt for a bank loan (which could take weeks), Business Capital surfaces an offer automatically as part of their daily routine. The merchant clicks “Accept,” and funds arrive in 1–2 business days.

NMI’s approach means partners do almost no extra work or take on any additional risk. The lending engine – powered by fintech partner Parafin and backed by Celtic Bank – handles underwriting, compliance, and servicing. The partner (whether it’s an ISO, a bank, or a SaaS provider) simply toggles the feature on in their NMI portal.

The platform even provides analytics on adoption and loan performance. In return, partners earn a share of each loan’s fixed fee – creating a new revenue stream without added cost or complexity.

How NMI Business Capital Works

How NMI Business Capital Works

Image source

NMI Business Capital is built directly into the NMI Merchant Portal, the interface merchants already use to review transactions, settlements, and reports. When the feature is active, the portal runs a brief eligibility check on a scheduled basis or whenever requested. If a merchant qualifies, a tailored funding offer appears, such as “Borrow up to $10,000 today.” The offer is powered by Parafin’s lending platform, which reviews historical processing data and risk signals without pulling personal credit. The merchant can accept or decline with a single click. After acceptance, funds are usually deposited into the merchant’s bank account within one to two business days.

Repayment is automatic and straightforward. Each day, a fixed percentage of the merchant’s card sales is applied to the outstanding balance, similar to Square’s financing programs. Because payments adjust with sales volume, merchants repay more during strong periods and less during slower ones, which helps manage cash flow.

Pricing is simple and transparent. There is a single upfront fee based on the loan amount, with no compounding interest, late fees, or added charges. The total repayment amount is set at the start, while daily payments vary based on revenue.

For partners, a key advantage is that all loans are issued by Celtic Bank. This keeps the product fully regulated and FDIC-backed without requiring the partner to act as a lender or manage credit decisions. NMI handles the on-platform experience, while Parafin operates behind the scenes. To partners, it functions as another software feature; to merchants, it feels like funding that is part of their existing payment system.

Key Facts of NMI Business Capital

Key Facts of NMI Business Capital
  • Quick, pre-approved offers: NMI’s partners can show instant loan offers based on the merchant’s sales history. No lengthy credit checks or paperwork.
  • Fast funding: Once accepted, funds arrive in 1–2 business days.
  • Flat-fee pricing: A single, up-front fee (charged at closing) replaces traditional interest. NMI stresses that there is no compounding interest, hidden charges, or late fees.
  • Automatic repayment: Daily sales flows handle repayments. A fixed % of each day’s card receipts is swept into the loan until the loan is paid off.
  • No risk or work for partners: Loans are underwritten and serviced entirely by Parafin/Celtic Bank; partners simply toggle on the feature.
  • Embedded into portals: The loan interface appears inside the merchant’s existing dashboard – no separate apps. NMI calls it “funding built right into the platforms merchants already use”.

These features reflect best practices from earlier embedded lending programs. In fact, platforms like Stripe, Square (Block), Shopify, Toast, etc. have long used exactly this model: they offer merchant cash advances or term loans repaid via daily sales.

The infrastructure is proven – payment processors see the sales, and they simply divert a percentage to recoup the advance. NMI is now giving that capability to any ISO or software provider connected to its platform.

Benefits for Merchants and Partners

Benefits for Merchants and Partners

For merchants, the biggest advantage is access and speed. Many small businesses have been reluctant or slow to seek bank financing – often because of paperwork, long approval times, and inflexible terms. Embedding a loan offer in their day‑to‑day system changes the game. A merchant doesn’t have to stop operations to fill out forms; instead, a small business owner can tap a button during end-of-day reconciliation and see an instant decision.

This “one-click capital” approach happens right when cash flow is being reviewed – a moment when merchants are most open to funding. And because the repayment flexes with sales, businesses are not overburdened during slow periods.

Plus, the transparent fee structure avoids many pitfalls of payday-style loans. Merchants know upfront exactly how much they will pay (the fee), and there are no surprises. The absence of compounding interest and late penalties further protects business owners from runaway debt in case of delays. In sum, Business Capital aims to keep financing fast, fair, and frictionless for the end customer.

For platform partners (ISOs, PayFacs, vertical SaaS companies, etc.), Business Capital is a value-add with little downside. It deepens the merchant relationship: a platform that provides both payments and capital becomes harder to leave.

The revenue comes from sharing the fixed fee on each loan. Unlike card processing fees (which largely cover costs), loan fees are nearly pure profit for the partner, boosting margins. One industry analyst even points out that integrated merchant financing can triple pay‑fac gross margins while cutting churn – if done seamlessly.

Crucially, partners incur no lending risk. All underwriting and compliance is outsourced to Parafin/Celtic. NMI’s platform merely channels the loan – it never holds the debt. The partner doesn’t need to expand its balance sheet or navigate banking regulations. This “no-lift” model is an attractive alternative to traditional co-branded loans, where an ISO might need to conduct manual reviews or assume liability. With Business Capital, the platform’s IT team integrates once, and lending is done.

Embedded lending meets merchants where they need it. According to a survey, 88% of U.S. SMBs regularly experience cash flow disruptions. Having financing offers built into the payments interface helps stabilize those swings.

How This Fits the Broader Trend

NMI’s entry into embedded lending is part of a larger industry shift. Major payment companies have been layering credit onto their platforms for years. Square (Block) pioneered this in 2014 with Square Loans, and has since advanced tens of billions in small-business funding. Shopify Capital (launched in 2016) likewise funds merchant advances using its payment and e-commerce data. Stripe Capital (for Stripe’s sellers) and PayPal Working Capital are other examples. These programs all share the same DNA: underwriting based on transaction data and repayment via revenue share.

What’s notable is that embedded lending is still in early innings. The addressable market for embedded lending could be $48 billion in annual revenue, of which only a small fraction has been captured so far. SMBs themselves want it – nearly 70% say they’d prefer their software or payments provider to offer loans. Yet historically, many banks and fintechs have failed to deliver fast, seamless products. NMI’s new program reflects the recognition that the future of SMB finance lives inside the apps they already trust.

By partnering with Parafin, NMI is effectively turning its entire reseller network into a lending channel. Those merchants might now get a loan offer while reviewing yesterday’s sales, just as easily as they could see yesterday’s deposits.

In the short term, NMI’s Business Capital may primarily benefit its existing customers (ISOs and SaaS vendors who already use NMI). But the long-term implication is broader: it signals that payment gateways are no longer just pass-through utilities. They’re becoming full-featured commerce platforms. And by embedding lending, they’re offering SMBs a one-stop shop for both selling and growing.

Conclusion

NMI’s Business Capital underscores how pervasive embedded finance has become in the SMB ecosystem. By letting merchants get quick loans with no extra forms or credit checks, directly in the same portal where they view sales, NMI aims to alleviate the very cash-flow worries that plague small businesses.

At the same time, it lets payment software providers unlock a new revenue source, without taking on lending headaches. This win‑win comes at a time when 88% of merchants could use it most. In short, funding is finally being woven into the commerce fabric, meeting merchants exactly when and where they need it.

Frequently Asked Questions

  1. What is NMI Business Capital?

    NMI Business Capital is an embedded financing feature within the NMI platform that enables payment providers to offer pre-approved working capital to their merchants. Offers are based on processing history and appear directly in the merchant dashboard.

  2. How do merchants receive and repay the funding?

    Merchants accept a pre-approved offer online and typically receive funds within a day. Repayment occurs automatically as a small percentage of daily card sales until a fixed total is repaid.

  3. Who provides the capital and assumes the risk?

    NMI does not lend the money itself. The funding and credit risk are handled by a lending partner, while NMI enables the experience and repayment through its payments platform.

  4. Why is embedded financing helpful for small businesses?

    It provides fast access to cash with minimal paperwork and flexible repayment tied to sales volume. This makes it easier for merchants to manage cash flow without traditional loan hurdles.

  5. How does this compare to Square Capital or Stripe Capital?

    The structure is similar, but NMI makes this model available to many payment providers and ISVs. It allows them to offer Square- or Stripe-style funding without building their own lending programs.

Stablecoin Adoption

Wall Street Warms to Stablecoins: Why “Stablecoin Adoption Is Exploding”

Stablecoins are digital tokens pegged 1:1 to stable assets (typically fiat currencies such as the US dollar), combining blockchain speed with predictable value. Once mainly a tool for crypto traders, stablecoins are now broadening into mainstream finance. Companies are adopting them for corporate payments, payroll, and treasury operations to achieve 24/7, real-time settlement that traditional banking (with its daytime-only clocks) cannot match.

This trend is so pronounced that Alchemy co-founder Joe Lau says stablecoin adoption is literally “exploding” – driven by banks, fintechs, and payment firms pushing beyond the old USDT/USDC exchange era.

Key Takeaways

  • Stablecoins are moving fast out of crypto exchanges into corporate wallets and payment networks, enabling 24/7 global settlement and frictionless transfers.
  • In response, banks are rolling out deposit tokens (bank-issued stablecoin-like dollars) as a regulated alternative, offering many of the same benefits under existing banking rules.
  • Experts predict a dual system. “Open” stablecoins will handle peer-to-peer and cross-border transfers, while bank-issued tokens will circulate within bank ecosystems – at least until scale and technology drive them together.

24/7 Settlement and Business Use Cases

24x7 Settlement

Modern blockchain rails allow money to move instantly across networks, unlike traditional payment systems. Traditional payment rails settle only during banking hours and can take days for cross-border transfers. Stablecoins change that by enabling digital-native, round-the-clock settlement. Firms like Stripe and Visa are already building on this promise: Stripe acquired a stablecoin startup (Bridge) in early 2025, and card networks have created infrastructure for stablecoin-funded cards.

Multinational corporates and fintechs are increasingly using stablecoins for 24/7 cross-border payments and treasury operations. In practice, this means a global company can move dollars between offices or pay vendors anywhere at any time – even overnight or on weekends. Instant transfers and lower fees with blockchain-based dollars, instead of slow wires and multi-day settlements of legacy systems.

Joe Lau emphasizes that stablecoins enable money to move at the speed of the internet while maintaining banking-level safety. As traditional banks lag (wires and batch payments), forward-looking companies are integrating stablecoin rails into their operations. Some payroll and treasury platforms now offer stablecoin payouts for faster global payroll, and payment processors are pilot-testing stablecoin use. This corporate demand is a key driver behind the “exploding” adoption – companies chase digital-native settlement as a strategic capability.

Banks and Tokenized Deposits: A Regulated Alternative

Banks and Tokenized Deposits

Banks are developing similar blockchain-based systems (e.g., JPM Coin) to digitize traditional deposits. Banks themselves are not standing by. JPMorgan, HSBC, and others are issuing their own digital deposit tokens on blockchains. JPMorgan’s recently launched JPM Coin is one early example: it represents dollar deposits at the bank, letting institutional clients send US dollars via blockchain 24/7.

In fact, JPMorgan said JPM Coin transactions can settle in seconds on a public blockchain (Coinbase’s Base network) instead of days. Similarly, HSBC is expanding its tokenized deposit service (already live in HK, Singapore, and the UK) to new markets; HSBC’s payments head notes that it lets clients send money in seconds and at all hours.

These bank-issued tokens (often called tokenized deposits or deposit tokens) are one-for-one backed by actual cash on the bank’s balance sheet. Unlike crypto stablecoins (which are issued by private firms and held off the bank’s books), tokenized deposits remain fully regulated “on-balance-sheet” money.

Tokenized deposits give banks all the benefits of stablecoins – low fees, fast settlement – while operating under existing regulatory and insurance frameworks. The funds backing the token remain in the bank, so it doesn’t weaken the bank’s deposit base or its money multiplier, as converting bank deposits into off-book crypto could.

Two Tracks to the Future: Stablecoins vs. Bank Tokens

Industry leaders foresee a dual-rail system in the near term. On one track are open stablecoins (like USDC, USDT, and future digital dollars) that can move between any two parties on public blockchains. On the other track are bank deposit tokens, which operate within a bank’s own ecosystem or a permissioned network. JPM Coin moves money between JPMorgan clients, but (right now) cannot pay a vendor banking elsewhere.

Alchemy’s Joe Lau describes stablecoins as a more “open-ended” layer, while deposit tokens are more “closed-loop”. He predicts that, for now, these systems complement each other. Corporations and fintechs may favor bank tokens for one-stop banking and payments integration, while others use stablecoins to pay anyone, anywhere.

Citi’s research agrees: stablecoins, tokenized deposits, CBDCs, and other digital monies will co-exist, each finding its niche. In fact, Citi forecasts that bank “tokens” could ultimately surpass stablecoins in transaction volume by 2030, reflecting corporate preference for trusted, familiar bank-issued money.

Experts predict that over time, open stablecoin rails and bank-based token rails will gradually merge or interoperate. Over time, the lines between them may blur. Lau notes banks are already talking about expanding their token networks (e.g. for other digital assets), while stablecoin issuers are exploring ways to become more bank-like (for example, by adopting more flexible reserve strategies).

As both approaches scale, competition and innovation will lead to compatibility. As the two converge, money becomes both fully compliant and instantly accessible. This could mean future stablecoins that carry banking guarantees, or bank tokens that connect to public networks – eventually creating a unified, internet-age dollar system.

Stablecoin Adoption: Market Growth and Wall Street Forecasts

Wall Street Forecasts

The growth numbers underline this boom. Morgan Stanley data show total stablecoin circulation hit about $300 billion in September 2025 – a ~75% jump from a year earlier. Although still small relative to global money, this rapid expansion in a single year is striking. And Wall Street is projecting much more to come.

Citi’s research arm recently raised its 2030 stablecoin issuance forecast to about $1.9 trillion in a base-case scenario (up from $1.6T) and $4.0T in an upside case. (Those figures assume stablecoin usage continues to broaden far beyond crypto trading.) Morgan Stanley even suggests the market “could exceed $2 trillion by 2028,” driven by new use cases across commerce and B2B finance.

These forecasts stem from real signals: hundreds of new stablecoins are launching (including from fintechs like PayPal and Robinhood), and big companies are actively integrating them. For example, Stripe’s acquisition of a stablecoin provider (early 2025) underscores growing mainstream confidence. Meanwhile, credit card giants Visa and Mastercard are building stablecoin-friendly rails. Even retail and industrial firms (Wal-Mart, Amazon) are reportedly exploring tokenized dollars to cut payment friction.

Investors and banks see stablecoins as strategic infrastructure. In early 2025, the total stablecoin supply was roughly $280B (up from $200B at the start of the year), reflecting explosive demand. For perspective, that issuance pace implies billions of dollars in new stablecoins per month, mostly to support real-world transactions. All told, markets and institutions are bracing for stablecoins to become a major pool of money – potentially even greater than today’s commercial money markets and bank deposits.

The Regulatory Backdrop

Part of the reason for this surge is growing regulatory clarity, at least in the US. For years, the lack of clear rules held back banks and big corporations from using crypto rails. That has changed. In the US, Congress and regulators passed the GENIUS Act (July 2025), establishing the first federal stablecoin framework.

This law requires stablecoins to maintain 100% backing in liquid assets (such as cash or Treasuries) and to disclose their reserves monthly, among other consumer protections. By aligning state and federal standards and building trust, these rules make it easier for mainstream players to issue and use stablecoins.

Similarly, tokenized deposits benefit from existing banking laws (FDIC insurance, capital rules) because the tokens are literally backed by regulated bank deposits. Regulatory safety is a big selling point for institutions: they can achieve many of the speed gains of crypto without leaving the legal banking framework. Tokenized deposits let banks “modernize the dollar” without rewriting the banking system. As regulation catches up, traditional finance (neobanks, fintechs, large payment networks) is testing how stablecoins and deposit tokens can be integrated into their products.

Conclusion

Stablecoins have grown from niche crypto tokens into tools that promise to reshape finance. They offer “internet-time” money – always on, programmable, and global – precisely what modern businesses demand. Banks have responded by tokenizing their own dollars, leading to a two-track system of private stablecoins and bank-issued tokens. While both are nascent today, experts foresee them blending over time into a new digital money stack.

With a base already of $300+ billion and forecasts in the trillions, stablecoins are rapidly moving from the fringes into core financial plumbing. For US businesses and banks, this means the dollar could soon flow through blockchain rails around the clock – combining the safety of bank money with the speed of the internet.

Frequently Asked Questions

  1. What are stablecoins, in simple terms?

    Stablecoins are digital currencies designed to maintain stable value, typically pegged to the U.S. dollar. They offer fast, digital, 24/7 transfers without the price swings seen in cryptocurrencies like Bitcoin.

  2. Why is stablecoin usage growing so quickly?

    Stablecoins settle transactions in minutes, anytime, unlike bank transfers that take days and follow business hours. This speed, lower cost, and growing regulatory clarity are driving adoption by fintechs, companies, and financial institutions.

  3. What are tokenized deposits, and how are they different from stablecoins?

    Tokenized deposits are digital versions of bank deposits issued and controlled by banks, typically used within closed networks. Stablecoins are usually issued by non-banks and run on public blockchains, allowing anyone with a wallet to use them.

  4. Why do experts expect stablecoins and bank deposit tokens to coexist?

    They serve different needs. Stablecoins work well in open, global ecosystems, while tokenized deposits appeal to banks and enterprises that want blockchain speed within a regulated environment.

  5. Are major banks and financial firms actually using stablecoins?

    Yes. Firms like JPMorgan, Visa, Mastercard, and others are already testing or using stablecoins and deposit tokens for settlements, cross-border payments, and internal transfers, signaling growing mainstream adoption.

PaymentIQ

Worldline Sheds a Unit: Why Selling PaymentIQ Fits Its “Focus” Strategy

Worldline, a French payment processing giant, is slimming down its business portfolio as part of a new “focus” strategy. In December 2025, Worldline announced plans to divest its PaymentIQ platform, a payment orchestration gateway, to Sweden’s Incore Invest for roughly €160 million.

PaymentIQ helps online merchants connect to numerous payment providers through a single integration and has been especially popular in the digital gaming and iGaming sectors as a multi-acquirer payment gateway.

What Is PaymentIQ? A Payment Orchestration Platform

PaymentIQ is a payment orchestration platform that allows merchants to route transactions through hundreds of different payment providers via a single API connection. It serves as a hub that connects businesses with over 260 banks, acquirers, and alternative payment methods worldwide. This enables online companies to offer more flexible checkout options and higher payment success rates by automatically routing payments to the best provider based on factors such as cost and likelihood of success.

Secure payment processing with orchestration features for merchants.

Image source

PaymentIQ can auto-route transactions, provide built-in fraud screening, and support a wide array of payment methods (from credit cards and e-wallets to bank transfers and crypto) – all through a single integration.

Originally built by a Swedish firm called DevCode, PaymentIQ was designed with the needs of iGaming and online gaming operators in mind. It became known for handling complex payment flows for online casinos, sports betting platforms, and gaming marketplaces, where merchants often need to manage dozens of payment options across multiple countries. The platform was acquired by Bambora (a Nordic payments company) in 2017, then absorbed into Ingenico and, through subsequent mergers, into Worldline.

In Worldline’s portfolio, PaymentIQ functioned as a niche SaaS product enabling international merchants (especially in high-growth digital sectors) to expand payment acceptance without heavy IT development. Its value proposition was clear: simplify payments for merchants by offering “one-stop” connectivity to global payment networks, thereby boosting conversion and efficiency in online sales.

Despite its strong technology and a growing user base, PaymentIQ remained a relatively small piece of Worldline’s sprawling business. It generates about €50 million in annual revenue (2024), with an impressive €40 million in EBITDA and €30 million in free cash flow. This makes it a profitable unit – but in context, Worldline’s overall revenue was €4.6 billion in 2024, so PaymentIQ represents just around 1% of the total.

The service also operates largely outside Worldline’s core geographic and client focus (which is mainly mainstream European retailers and banks). These factors set the stage for Worldline to consider divesting PaymentIQ under its new strategic plan.

Worldline’s “North Star” Transformation and Focus Strategy

Worldline’s “North Star” Transformation

In 2025, Worldline’s leadership (under new CEO Pierre-Antoine Vacheron) launched a major turnaround initiative called “North Star 2030.” This strategy is a roadmap to refocus the company on its core payment services and to simplify operations after years of expansion. Worldline had grown into a broad entity through numerous acquisitions (including Ingenico in 2020 and various bank-owned payment processors), leaving it with a complex product portfolio and regional businesses.

The North Star plan aims to streamline this “Frankenstein’s monster” of acquired systems into a more unified, efficient company. In practice, that means concentrating on businesses that align with Worldline’s strengths and have synergies with each other – primarily, payment processing and merchant acquiring in Europe – while exiting peripheral or non-core activities.

Worldline explicitly framed the PaymentIQ sale in this context. The company stated that divesting PaymentIQ is a step in its strategic refocus on core European payment activities and part of the simplification journey under the North Star transformation plan. By “simplification,” Worldline means reducing complexity within its organization so that management can focus on core payments offerings (such as card acquiring for merchants, online payments, and processing for banks) without the distraction of running unrelated units.

PaymentIQ, while successful, does not strongly “generate synergies” with its other segments and sits outside the group’s revised risk and strategy framework. PaymentIQ’s business – serving global online merchants and especially gaming companies – is somewhat tangential to Worldline’s main mission of being the European partner of choice for merchants and financial institutions. North Star 2030 calls for Worldline to slim down and double down: shed non-core businesses and double down on its primary payments franchise.

Another facet of North Star is improving Worldline’s financial resilience and investor confidence. After some weaker performance in recent years (and even a compliance controversy in 2025), the firm is in turnaround mode. Management has been cutting costs, tightening risk controls, and raising fresh capital to strengthen the balance sheet.

The PaymentIQ divestment neatly fits into this playbook: it frees up capital and frees Worldline from a niche venture that, while profitable, might require additional investment to scale globally – resources better used in Worldline’s core areas. In fact, Worldline launched a €500 million equity raise alongside these divestitures, bolstered by anchor investments from major French banks, to fund its transformation and reduce debt.

Why Selling PaymentIQ Makes Strategic Sense

Selling PaymentIQ

Given that backdrop, it becomes clear why Worldline chose to sell PaymentIQ now. PaymentIQ is a strong product, but not core to Worldline’s integrated payments ecosystem. Worldline’s core business centers on payment acquiring (processing card payments for merchants), payment processing for banks, and related value-added services, predominantly in Europe. PaymentIQ, by contrast, is a vendor-agnostic gateway that integrates with other payment processors (including Worldline’s competitors) to meet merchants’ needs.

Its specialization in online gaming/gambling payments also means higher regulatory complexity and risk – something Worldline has become more sensitive about managing under its “reframed risk framework”. By exiting PaymentIQ, Worldline can avoid those distractions and risks and focus management attention on products and regions where it has a clear competitive edge.

Another reason is portfolio streamlining. Through acquisitions over the years, Worldline has amassed businesses ranging from payment terminal manufacturing to e-ticketing services. The North Star strategy identified several non-core pieces; PaymentIQ was one of the last to be carved out. Offloading it simplifies Worldline’s organization: fewer product lines to oversee, a leaner technology stack to integrate, and a clearer identity as a pure-play payments provider. Worldline stated that the transaction will streamline operations, improve resource utilization, and enable management to focus more closely on its core payment activities.

The proceeds (cash) will strengthen the group’s financial profile and allow capital to be redeployed toward core activities – for example, upgrading their payments platforms or funding growth in key European markets.

Financially, the timing was favorable. PaymentIQ has been growing quickly (its revenue jumped 36% in 2024), but it’s still small relative to Worldline. Selling it for ~€160 million in cash provides an immediate cash boost. To put it in perspective, €160m is about 4 times PaymentIQ’s annual EBITDA – a reasonable valuation for a niche B2B software unit. Worldline likely judged that this cash could earn a better return if invested in its core business or used to pay down debt, rather than holding onto a 50m-revenue adjunct.

Plus, since PaymentIQ’s contribution was under 2% of earnings, divesting it doesn’t hurt Worldline’s overall earnings power significantly (and Worldline can potentially still partner with PaymentIQ as an independent vendor if needed). The company has projected only a ~€50m revenue impact from removing PaymentIQ, which they believe will be offset by growth and cost savings elsewhere.

Recent Divestments Boost Financial Flexibility

The PaymentIQ sale is part of a series of divestments Worldline has undertaken as part of its overhaul. In about six months, Worldline has divested four business units, raising over half a billion euros in cash proceeds. These include:

  • Mobility & e-Transactional Services (MTS) – A division providing digital ticketing, transit, and e-government services – was sold to Magellan Partners Group in July 2025.
  • North American Operations – Worldline’s merchant services business in the U.S. and Canada (known as Bambora North America) – sold to Shift4 Payments in October 2025. (This exit meant Worldline pulled out of the U.S. market entirely, underscoring its focus on Europe.)
  • Electronic Data Management (EDM) Unit – A regulatory compliance data service (formerly Cetrel Securities in Luxembourg) – sold to SIX Group (the Swiss financial infrastructure firm) in November 2025.
  • PaymentIQ Orchestration Platform – Now being sold to Incore Invest (announced December 2025, expected closing Q1 2026).

Total expected proceeds from these divestments are in the range of €510–560 million, which will significantly bolster Worldline’s balance sheet. In fact, the first three sales (MTS, North America, EDM) were reported to generate about €350–400m, and the PaymentIQ deal adds another ~€160m.

This influx of cash, combined with the €500m in new equity that Worldline is raising, provides the company with ample financial flexibility to weather current challenges and invest in its core businesses. Worldline can use these funds to reduce debt, fund its technology integration (converging platforms), and pursue targeted growth projects in its mainline merchant services division.

Equally important, by divesting these units, Worldline has reduced its cost base and future capital expenditure needs. For example, the MTS division and EDM services likely require ongoing R&D or regulatory compliance that fall outside Worldline’s payments expertise. Removing them improves Worldline’s profitability metrics and simplifies its organizational structure.

All of this is aimed at helping Worldline achieve the turnaround targets under North Star 2030, which include restoring organic revenue growth (~4% annually by 2027+) and boosting free cash flow to the hundreds of millions. The company’s management specifically highlighted that these divestitures enhance strategic flexibility and allow reallocation of capital to core activities, exactly what one would expect in a focus strategy.

Sharpening Focus on European Payments & Acquiring

With non-core pieces divested, Worldline is pivoting back to its core mission: being Europe’s leading payment partner for merchants and banks. The company’s vision is to become the “European partner of choice” for payment services. In practical terms, this means Worldline will focus on its merchant-acquiring business across Europe, its online payment gateways for retailers, and its processing services for financial institutions (including issuing and ATM services).

Worldline has a strong footprint in countries such as France, Germany, Belgium, the Nordics, and beyond, serving millions of merchants, from small businesses to large enterprises. By focusing on these markets, Worldline can leverage its local expertise, wide acceptance network, and scale advantages – traits that are crucial in the highly competitive payments industry.

The divestment of North American operations was a clear signal of this geographic focus. Competing in the U.S. against entrenched local processors was an uphill battle; instead, Worldline chose to double down on Europe, where it has home-field advantage. Likewise, selling a specialized global platform like PaymentIQ indicates that Worldline will focus on its own integrated payment platforms rather than third-party orchestration tools.

Worldline is investing in unifying its myriad systems (including those from the Ingenico acquisition and others) into a single, modern infrastructure that can handle in-store, online, and cross-border payments seamlessly. This should help Worldline innovate faster (for instance, launching new payment methods or AI-driven fraud tools across its network) and provide a more consistent experience to merchants. Essentially, a more focused Worldline can become more agile and customer-centric, unburdened by sidelines.

Focusing on core payments also positions Worldline to better compete with specialized rivals such as Adyen, Stripe, and Nexi. These competitors often tout the simplicity and singular focus of their platforms. Worldline, through North Star initiatives, is aiming to achieve a similar level of cohesion by consolidating its APIs and services into a single set across its offerings. By 2030, Worldline envisions a unified architecture supporting everything from point-of-sale transactions to e-commerce to account-to-account payments on a common backbone.

A streamlined product suite and organization will likely improve Worldline’s ability to innovate and respond to market needs (e.g., by supporting instant payments or digital wallets EU-wide), thereby strengthening its competitive position in Europe. The sale of non-core units, such as PaymentIQ, is a means to that end, allowing Worldline’s management to focus squarely on its European payments empire.

Industry Trend: Streamlining and Carve-Outs in Payments

Worldline’s portfolio pruning is part of a broader trend in the payments and fintech industry: big players are refocusing on their core strengths, while investors are acquiring the carved-out niche businesses. In recent years, several financial technology conglomerates have realized that “bigger” isn’t always “better” when it means operating across too many disparate areas. For example, in 2023, FIS (a U.S.-based fintech giant) chose to spin off and sell a majority stake in its merchant payments arm, Worldpay, to a private equity firm, effectively reversing a prior expansion and refocusing on its core banking software business.

Similarly, Fiserv offloaded non-core units (like a loan servicing segment) to concentrate on payments and fintech solutions for banks. These moves echo a common theme: large fintech companies streamline operations to improve efficiency, address investor concerns, and zero in on markets where they have a competitive edge.

Worldline’s strategy fits this narrative. After a decade of aggressive acquisitions (which made it a top-three payment processor in Europe), the company hit growing pains – from integration challenges to a slumping stock price – prompting a “back to basics” approach. By selling off side businesses, Worldline can avoid being a jack-of-all-trades and instead strive to be the master of its core domain (payments).

This trend acknowledges that the payments sector is rapidly evolving; focused specialists often outperform conglomerates that are too spread thin. Investors have rewarded companies that demonstrate a clear focus and penalized those with complex, sprawling structures.

On the flip side of these divestitures, there is another trend: specialized investment firms eagerly buying up these carved-out units. In PaymentIQ’s case, Incore Invest – a Swedish investment firm – saw an opportunity to acquire a high-growth platform and nurture it as an independent business.

We’ve seen private equity and niche investors do similarly in fintech: for instance, the private equity firm Apollo took over Worldline’s former payment terminals division (Ingenico hardware) to run it as a standalone company, and GTCR (another PE firm) acquired FIS’s Worldpay with plans to invest in its growth. These investors often believe they can unlock value in niche platforms by giving them dedicated focus and funding, away from the constraints of a larger parent company.

For PaymentIQ, being under Incore Invest could mean more tailored attention and resources to expand its orchestration technology. Incore has already indicated it will carve out PaymentIQ (legally known as CoreOrchestration AB) into a standalone business and work closely with the team to strengthen product packaging, sharpen execution, and capture additional growth opportunities.

As a pure-play payment orchestration provider, PaymentIQ might grow faster or serve a broader range of partners than it could within Worldline. The payment orchestration market itself is sizable (estimated at around $3 billion and growing) and highly dynamic. We may see PaymentIQ target not just gaming merchants but any online merchant needing to simplify multi-provider payments – competing with other orchestration specialists on the global stage. Incore’s acquisition reflects confidence that focused growth strategies can unlock the full potential of such niche platforms, which might have been undervalued inside a conglomerate.

Conclusion

Worldline’s decision to sell PaymentIQ for €160 million signals a clear strategic pivot: simplify the group and double down on core payments. By divesting this orchestration unit (and other non-core assets), Worldline is “trimming the fat” to focus on its North Star, delivering payment services at scale across Europe and adjacent markets. The deal strengthens financial flexibility and removes a business that, while strong, sat outside its primary scope, leaving a leaner Worldline better positioned to invest in unified platforms, market expansion, and innovation in merchant acquiring and processing.

For the broader fintech industry, the move reflects a wider trend of major players streamlining to stay competitive as agility and specialization increasingly beat sheer size. PaymentIQ’s carve-out also highlights a healthy investor ecosystem willing to back niche platforms as standalone specialists. Under Incore, PaymentIQ can pursue its mission of connecting merchants to multiple payment providers, while Worldline’s sharper focus could improve execution and rebuild investor confidence, making this a win-win example of fintech recalibrating toward a clearer strategic fit.

Frequently Asked Questions

  1. Why is Worldline selling PaymentIQ?

    Worldline is simplifying its portfolio under its “North Star 2030” focus strategy. PaymentIQ is profitable, but non-core and has limited synergies with Worldline’s main European acquiring and processing business.

  2. What exactly does PaymentIQ do?

    PaymentIQ is a payment orchestration platform that connects merchants with hundreds of payment providers through a single API. It helps route transactions smartly to improve success rates, reduce costs, and expand payment options globally.

  3. Why was PaymentIQ considered “non-core” for Worldline?

    Worldline’s core is a large-scale payments infrastructure for mainstream European merchants and banks. PaymentIQ is a vendor-agnostic gateway with a strong presence in iGaming and is outside Worldline’s main strategic and risk focus.

  4. What does Worldline gain from this sale?

    The ~€160 million sale adds financial flexibility and reduces operational complexity. It also frees management time and capital to invest in unified platforms, European growth, and core product innovation.

  5. What happens to PaymentIQ under Incore Invest?

    PaymentIQ is expected to operate as a focused, standalone specialist with dedicated ownership. Under Incore, it can scale faster, refine its product packaging, and expand beyond its strong gaming base into broader e-commerce use cases.

Paper Checks

Are Paper Checks Finally Going Extinct? Fed Signals a Scaled-Back Check Service

The humble paper check – once a dominant payment method – may be on its last legs. The U.S. Federal Reserve has signaled it may significantly scale back its check-processing services in the near future. In early December 2025, the Fed’s Board of Governors voted 6–1 to seek public input on the future of its check-clearing operations. This move, driven by declining check usage and rising costs, could mark the beginning of the end for check writing.

In this article, we explore the implications of the Fed’s proposal and the broader trend of declining checks. Could this be the final chapter for paper checks? We’ll highlight the stark statistics (check volumes have dropped drastically from a decade ago) and discuss what reduced Fed support could mean – possibly slower clearing times or higher fees for the remaining check users.

The Fed Signals It’s Scaling Back on Checks

Secure online payment check and digital transaction technology illustration.

The Federal Reserve Board’s recent action is a strong signal that the central bank sees paper checks as a fading player in payments. In a December 2025 notice, the Fed sought public input on potentially reducing the availability of check-processing services it provides to banks and credit unions. In essence, the Fed is debating how much longer – and how much further – it should invest in the nation’s check-clearing infrastructure, given that Americans are using checks less and less each year.

To guide the discussion, the Fed outlined several scenarios for its future role in check processing:

  • Maintain but Don’t Upgrade: Stop making major new investments in aging check-processing systems and keep running them as-is. This would avoid big expenditures, but over time, it would degrade the reliability of check clearing (leading to more delays, outages, and errors as equipment ages).
  • Streamline Services: Proactively simplify and scale back check services to cut costs. For example, the Fed could reduce the number of daily check-presentment deadlines, shorten operating hours, or eliminate certain support services (such as certain check adjustment and reconciliation functions). This could save money, but would likely lead to longer clearing times and less convenience for banks and their customers.
  • Wind Down Checks: Go further and substantially wind down Federal Reserve check processing over the coming years. In this scenario, the Fed would eventually cease most check-clearing operations, forcing banks to use private networks or other means to clear the remaining paper checks. This would significantly reduce Fed costs, but it could make check clearing more fragmented and potentially more costly elsewhere.
  • Invest to Sustain (The Opposite Path): Alternatively, the Fed could invest in its check-processing infrastructure to maintain or improve service levels. However, this would require substantial investment. By law, the Fed must recover the costs of its payment services through fees, so the expense of upgrades would likely mean higher fees charged to banks for check clearing, which could trickle down to businesses and consumers.

The Board of the Fed is only seeking information at this stage – no final decision has been made. Any major changes would undergo further review and public comment before implementation.

However, just by floating the possibility of significantly reducing or even winding down its check services, the Fed has sent a clear message: the status quo of nationwide check processing is no longer taken for granted.

Why Is the Fed Considering This Now?

The central bank cites a confluence of factors: steadily declining check usage, rising check fraud, and the high cost of maintaining aging systems. The Federal Reserve Banks currently process millions of checks a day for the industry, but volumes have dropped significantly, raising per-check costs and prompting upgrades for the Fed’s check-processing centers (consolidated into a single center as of 2010, down from 48 in 1979).

Rather than sink more money into a fading payment method, the Fed is weighing whether to scale back and let market forces (and private-sector processors) handle what’s left of paper check traffic.

It’s worth noting that the Fed’s move was not unanimous. Vice Chair for Supervision Michelle Bowman cast the lone dissenting vote, arguing that the inquiry was biased toward prematurely discontinuing Fed check services. Bowman cautioned that checks still play an “integral role” for many consumers and businesses, and that reducing the Fed’s support could harm people who rely on them. She also noted that reducing Fed check services won’t solve the rise in fraud; that problem needs to be addressed regardless.

The Long Decline of Paper Check Usage

Decline of Paper Check Usage

To understand why the Fed is considering pulling back, look at the numbers. At the turn of the 21st century, Americans wrote over 40 billion checks per year – by far the most used non-cash payment method at that time. Fast forward two decades, and check usage has nose-dived. In 2021, only about 11 billion checks were written in the U.S., representing 5% of all non-cash payments by volume. Electronic payments (cards, ACH transfers, online transactions, etc.) have largely supplanted checks in everyday use.

This decline has been steady and striking. The total number of checks written has declined every year since 1992, the peak year for check volume. Over the past decade, check usage continued to erode at an average annual rate of over 6%. For example, the Federal Reserve Banks processed nearly 50% fewer checks in 2024 than in 2014 (about 3.0 billion commercial checks in 2024 versus 5.7 billion in 2014). By any measure, the paper check has been in a long-run secular decline.

It’s not that Americans are making fewer payments overall – in fact, electronic payments have exploded. We’ve simply shifted to other methods. Two decades ago, checks were still used for everything from grocery shopping to paying the electric bill. Today, few people pull out a checkbook at the supermarket or to pay routine bills. Debit cards, credit cards, and online bill-pay have taken over those functions.

The Federal Reserve cites the “increasing availability and use of payment alternatives” as the primary driver of the decline in checks. There are now countless ways to pay that didn’t exist or weren’t widespread a generation ago – from e-commerce payments, to mobile peer-to-peer apps, to electronic payroll deposits – and they’ve all chipped away at check usage.

The COVID-19 pandemic accelerated this trend even further. During the pandemic, both businesses and consumers sought contactless and remote payment options, accelerating the shift from paper to digital payments. Many who had been hesitant to bank or pay bills online were forced to do so in 2020–2021, and few are likely to revert to writing checks now that they’ve experienced the convenience of digital methods.

Despite the dramatic drop in check volumes, it’s important to note that checks haven’t disappeared entirely – and they still represent a sizable chunk of payment value. In 2021, those 11 billion checks totaled about $27.2 trillion, representing approximately 21% of the total value of all non-cash payments that year. In other words, while we no longer use checks for day-to-day transactions, the checks written tend to be for larger amounts (e.g., business-to-business payments and rental payments).

A single check can be for thousands or millions of dollars, which is why their share of the value of payments (21%) is much higher than their share of the number of payments (5%). This hints at where checks remain relevant: more on that next.

Why Checks Are (Almost) Going Extinct – And What’s Keeping Them Alive

Why Checks Are (Almost) Going Extinct

Why have paper checks been steadily declining? The short answer: better alternatives. For most purposes, using a check is less convenient and faster than electronic payment methods. Today, we have multiple types of digital payments that can do everything a check does, usually more efficiently. For example:

  • ACH Transfers:

The Automated Clearing House (ACH) system enables direct account-to-account payments. This powers features such as direct deposit of paychecks, automatic bill payments, and many online bill-pay services. Instead of mailing a check, consumers and companies can send money electronically via ACH for recurring payments, supplier payments, and more.

In fact, many “online bill pay” services offered by banks will attempt an electronic transfer via ACH first; only if the payee can’t accept ACH will the bank mail a paper check on the customer’s behalf.

  • Payment Cards:

Credit and debit cards have largely replaced checks for in-store purchases. It’s far quicker to swipe or tap a card (or phone) than to fill out a check at the register. Cards also work online and internationally, which checks do not.

The vast majority of U.S. households have debit cards linked to their bank accounts, providing a convenient payment option without carrying a checkbook.

  • Instant Payment Systems:

In the last decade, new real-time payment networks have launched. The private-sector RTP network (operated by The Clearing House) went live in 2017, and the Federal Reserve’s own FedNow instant payment system launched in 2023.

These allow money to move between banks within seconds, 24/7. For use cases like urgent bill payments or transferring money to a friend, instant payments offer speed that checks (which can take a day or more to clear) simply can’t match. FedNow is still in its infancy, but it represents the future of fast bank-to-bank transfers in the U.S.

  • Peer-to-Peer (P2P) Apps:

Services like Zelle, Venmo, PayPal, and CashApp have made it easy for individuals to pay each other without checks. Splitting a dinner bill, paying the babysitter, or sending money to a family member – all can be done digitally in seconds. This has largely supplanted the old practice of writing a personal check to reimburse someone.

Electronic payments grew as check usage shrank, because they offer greater convenience, speed, and often lower cost. Younger generations, in particular, have grown up with digital options and may never have learned how to write a check. Businesses have also been gradually adopting electronic invoicing and payment systems, eroding the dominance of checks in B2B transactions.

Despite their decline, checks aren’t dead yet. There are specific niches and preferences keeping them on life support:

  • Certain Demographics:

Check usage skews heavily toward older Americans and those in certain communities. For example, consumers age 65 and above are the highest users of checks, but even their reliance is waning – seniors made about 6% of their payments by check in 2024, down from 11% in 2015.

People in rural areas also tend to write checks more often than urban dwellers, and lower-income individuals sometimes rely on checks (or cash) if they haven’t adopted digital tools. For those uncomfortable with computers or mobile apps, a checkbook may still feel more familiar and secure.

Additionally, some folks simply prefer the tangible record-keeping that checks provide – the paper trail and the act of balancing a checkbook can give a sense of control over finances.

  • Business-to-Business (B2B) Payments:

Paradoxically, businesses – even some large ones – remain heavy check writers. Corporate payments between companies, as well as business-to-consumer payouts such as refunds and rebates, still frequently use checks. In fact, by some estimates, checks account for over half of the ~$25 trillion annual B2B payments market in the U.S.

Small and mid-sized businesses, in particular, often stick with checks because it’s the way they’ve always paid suppliers or because they lack the IT systems to easily shift to ACH or other electronic methods. There’s also an economic incentive where paying by check can be cheaper than credit card payments, which incur merchant fees.

A contractor or landlord might prefer receiving a check rather than having a percentage skimmed by card processors. Until electronic payment solutions are truly easy, universal, and fee-free for all parties, many businesses will continue to reach for the checkbook for certain transactions.

  • Peer and Informal Payments:

In some situations, writing a check remains practical. For example, when paying a casual laborer or splitting a large expense with a friend, if both parties don’t use the same digital app or if there’s no cash on hand, a check can serve as a neutral, low-tech solution. Unlike some P2P apps, checks don’t require both people to enroll in the same service.

For sending money as a gift (e.g., to a grandchild) or donating to a local charity or church, some individuals still prefer writing a check. Tradition dies hard in some of these cases.

  • Lack of Access or Trust in Digital:

A segment of the population remains unbanked or underbanked, without full access to digital payment systems. Others have bank accounts but mistrust online banking due to security fears. These individuals might find checks (and cash) to be the more accessible options for now.

Some low- and moderate-income households use money orders and checks to pay bills because they lack credit cards or want to avoid the overdraft risks associated with electronic payments.

A Growing Problem: Check Fraud and Security Risks

One unintended side effect of the decline in checks is that they’ve become an inviting target for fraudsters. Check fraud has surged in recent years, contributing to the Fed’s re-evaluation of its check services. Criminals know that a paper check carries a lot of sensitive information – the account holder’s name, address, bank account number, routing number, even a signature – all right there on the document.

If a thief intercepts a check, they can alter it (“wash”) or use the account details to attempt additional fraudulent payments. Unlike digital transactions, which use various encryption and authentication measures, a paper check sent by mail is relatively vulnerable.

The statistics are alarming. Between 2018 and 2021, the share of checks returned through the Federal Reserve system deemed potentially fraudulent increased from about 10% to 15%. In other words, by 2021, roughly 1 in 7 bounced checks handled by the Fed showed signs of fraud – a significant increase in a short time. Banks have reported significant increases in counterfeit and stolen checks, often linked to mail theft rings.

The Financial Crimes Enforcement Network (FinCEN) noted that in 2021, U.S. banks filed over 350,000 Suspicious Activity Reports related to check fraud – 23% more than the year prior – and in 2022 those reports exploded to over 680,000, nearly doubling the cases of suspected check fraud in one year. This makes check fraud one of the largest sources of illicit financial activity in the country.

Why the Spike?

Fraudsters may be exploiting the fact that, as check usage declines, banks and consumers may pay less attention to check security or assume checks are easier targets than heavily secured electronic systems. There’s also a simple reality that physically stealing a check (from a mailbox, for example) and altering it is a relatively low-tech crime – no hacking skills required.

Pandemic relief checks, for instance, became a lucrative target; thieves stole stimulus checks from mailboxes and even targeted government mailouts en masse, knowing many people weren’t expecting a check and might not notice its theft.

The rise in check fraud provides another incentive to move away from paper. It’s pushing banks to implement new anti-fraud measures (positive pay systems, watermarks, etc.), which add cost and complexity to check processing. From the Fed’s perspective, the uptick in fraud is yet another sign that the current check system is becoming less tenable. Fed officials have noted that check fraud is “rampant” and a critical issue that needs addressing – though, as dissenting Governor Bowman argued, the solution might lie in fighting fraud rather than abandoning checks.

Regardless, fewer checks written mean fewer opportunities for check thieves. Digital payments have their own fraud challenges (phishing, account takeovers, etc.), but they don’t present the same straightforward opportunity as stealing a piece of paper out of someone’s mailbox. The hope is that as we transition to more secure, encrypted payment methods, fraudsters will find it harder to operate, though it remains a constant cat-and-mouse game.

What Would Reduced Fed Check Services Mean for You?

Reduced Fed Check Services

If the Federal Reserve ultimately decides to scale back its check-processing services, what practical effects might consumers and businesses experience? While nothing is changing immediately, the scenarios being considered by the Fed give some hints of potential impacts:

  • Slower Clearing Times: Today, the Fed offers multiple clearing cycles per day for checks deposited at banks (generally up to four daily processing windows). If services are simplified, we might see fewer clearing cycles or shorter operating hours. This could mean that when you deposit a check, the funds may not be available immediately, especially if you miss a now-earlier cutoff. The era of near-instant money movement (with Zelle, cards, etc.) has already made the days-long float of checks feel antiquated; a scaled-back Fed service might exacerbate that for remaining check users.
  • Reduced Customer Convenience: The Fed also provides various support services to banks for exceptions and issues – for example, helping resolve discrepancies or errors in check processing (known as check adjustment services). If some of these services are eliminated or reduced, banks may have more difficulty quickly resolving issues such as encoding errors or disputes over altered checks. This could lead to more headaches for consumers or businesses trying to resolve a check issue, as their bank may face delays in resolving it.
  • Higher Costs (Fees): If the Fed continues operations but must invest heavily to upgrade systems, costs will be passed along. By law, the Fed must recoup its operating costs through fees it charges banks for check clearing. If the volume of checks continues to decline while expensive infrastructure must be maintained, the fee per check will likely increase to cover the shortfall. Banks, in turn, could start charging customers more for checking accounts or for processing checks.
  • Greater Reliance on Private Clearing Networks: If the Fed significantly pulls back, banks may route more checks through private-sector processors or correspondents. The check system might become more fragmented, with perhaps a couple of large banks or clearinghouses handling what the Fed used to handle. There could be less universality – for instance, some small banks might not have as efficient access and might need to partner with bigger banks to clear checks. Private providers may also charge higher fees due to low volumes and limited competition. The Federal Reserve has long provided a public service function to clear checks (ensuring that even the smallest community bank in a remote area can send a check into the Fed system and have it reach any other bank).
  • Pressure to Phase Out Checks Faster: If checks become slower and more costly to use, this can create a feedback loop: it discourages people from using them, which further reduces volume, reinforcing the rationale for cutting services. Banks might impose stricter policies on checks (e.g., longer deposit holds or fees for issuing cashier’s checks) to cover their risks and costs. We could also see more merchants refuse to accept checks at the point of sale – a trend already underway – especially if it becomes harder or pricier to process them.

The Fed has been careful to say it will not abruptly strand people. Any major changes would be telegraphed well in advance and likely phased in. There could be a period of many months or even years where the industry transitions.

If the Fed eliminated one of the daily check-clearing windows, banks would adjust their cutoff times and notify customers. Or if certain remote regions needed alternatives, the Fed might coordinate solutions. Nonetheless, the direction seems clear: writing checks will gradually become more inconvenient relative to other methods.

For the average consumer or small business, the key takeaway is that the payments landscape is evolving away from paper. If you’re someone who writes a handful of checks a month, you might not notice a difference yet, but behind the scenes, your bank and the Fed are thinking about how to get you onto other platforms. The smart move is to start familiarizing yourself with electronic payments now, rather than waiting until the last minute.

Embracing a Future with (Almost) No Checks

All signs point to a future where paper checks are a rarity. It’s quite possible that in a decade or two, the act of writing a check will feel as antiquated as using a typewriter or sending a fax. So how can consumers and businesses prepare for this transition?

1. Use Electronic Bill Payments:

If you’re still mailing checks to pay bills (utility bills, rent, etc.), consider switching to electronic bill pay through your bank or the billing company’s website. Most utilities, telecom providers, and lenders offer online payment options (ACH transfers or card payments).

Many banks’ online bill pay services will handle the delivery method for you – they’ll send an ACH if possible, or still mail a check if absolutely necessary – but from your perspective, it’s the same easy digital process. This not only saves you time and postage, but also ensures payments are tracked and can be automated. And you’ll avoid the risk of checks being lost or stolen in the mail.

2. Embrace Direct Deposit and Electronic Payroll:

Employers have largely moved to direct deposit of paychecks, but if you work for or run a small business that still issues paper payroll checks, it’s time to make the switch. Direct deposit via ACH is reliable and fast.

Similarly, if you receive government benefits or tax refunds by check, arrange for direct deposit to your bank account – the U.S. Treasury already prefers this method, and it’s safer (no risk of a check getting stolen) and quicker. In fact, many federal payments are now electronic by default as a result of past initiatives to reduce the issuance of government checks.

3. Try Out Person-to-Person (P2P) Payment Apps:

For those personal payments – paying the lawn care service, reimbursing a friend, giving money as a gift – consider using P2P apps or bank-based transfer services. Zelle, for example, is offered by most major banks and allows you to send money via email or phone number, with funds moving directly between bank accounts typically within minutes.

If privacy or security is a concern, remember that these services are generally as secure as your online banking, and you’re avoiding the very real security risks of paper checks. It might take a bit of setup for both parties, but once it’s done, it’s far more convenient than coordinating a time to hand over or mail a check.

4. Businesses:

Modernize Accounts Payable/Receivable: If your business still relies on printing and mailing checks to vendors or on receiving numerous checks from customers, explore modern B2B payment solutions. There are services that facilitate ACH payments, as well as newer options such as virtual cards and digital wallets, for B2B. These can often be integrated into accounting software, reducing manual work. Importantly, going electronic can reduce errors and fraud – no more check reconciliation issues or potential check forgeries.

Yes, there may be some setup costs or transaction fees, but weigh those against the labor of processing paper and the risk of lost checks. Moreover, younger clients and suppliers will expect digital options. Adopting e-payments can also speed up your cash flow (no waiting for checks in the mail).

5. Keep an Eye on Real-Time Payments:

The Fed’s FedNow service is new, but banks are gradually enrolling in it. In the coming years, more banks and credit unions will offer instant payment capabilities to their customers via FedNow or other networks. This could enable things like instant bill pay, faster payroll for gig workers, and quick settlement of invoices – all without checks.

Stay informed about what your bank offers. If your bank has a person-to-person payment feature or instant transfer option, give it a try. The more people use these services, the more ubiquitous they will become, creating a network effect that further diminishes the need for checks.

6. Plan for the Holdouts:

If you still need to issue a paper check (for example, if your landlord or a club you’re in only accepts checks), consider discussing alternatives with them. They might be unaware of how to use digital payments or have concerns. Sometimes, providing a little education or assistance (like showing a landlord how Zelle works, or helping a church set up an online donation portal) can break the inertia.

In cases where a check is unavoidable, you might opt for money orders or cashier’s checks from your bank – these are still paper, but come with added security and are tracked by the issuer. Just be prepared: as the ecosystem changes, those who insist on checks may face increasing friction.

It’s worth acknowledging that completely eliminating checks might not happen for a long time, if ever. As the saying goes, “old habits die hard.” Even the Federal Reserve’s request for input suggests that any wind-down will be gradual and considerate of remaining users. Other countries that have tried to mandate the end of checks have often faced public backlash and had to slow down (the U.K., for instance, floated a plan to phase out checks by 2018, then reversed course after an outcry).

In the U.S., there’s no mandate requiring you to stop using checks; market forces and practicality are driving the change. There may always be a small number of checks still in circulation for specific purposes. But they will increasingly be the exception, not the rule.

Conclusion

Paper checks have been declining for years, and recent signals from the Federal Reserve make that trend hard to ignore. Check usage has fallen sharply, and maintaining large-scale processing systems no longer makes financial sense given their infrequent use. While checks are not disappearing immediately, their role in everyday payments is clearly shrinking as digital options continue to take over.

For consumers and businesses, this shift is less a disruption than a practical adjustment. Most payments already occur electronically, and those tools will continue to improve in speed and ease of use. Checks will likely persist in limited situations for some time, but their footprint will continue to shrink. The direction is clear: the payment system is moving on, and preparing for that reality is the sensible next step.

Frequently Asked Questions

  1. Are paper checks being eliminated immediately?

    No. The Federal Reserve is only exploring changes to its check-processing services. Any reduction would be gradual, with advance notice and transition time.

  2. Why is the Federal Reserve scaling back check services?

    Check usage has dropped sharply while costs and fraud have increased. Maintaining aging check systems is becoming less efficient compared to digital alternatives.

  3. Will checks still be accepted in the future?

    Yes, for now. Checks are still used for large-value and certain business payments, but their role will continue to shrink over time.

  4. How could reduced Fed support affect consumers and businesses?

    It may lead to slower check clearing, fewer processing windows, and potentially higher fees, making checks less convenient than electronic payments.

  5. What are the best alternatives to using paper checks?

    Electronic options like ACH transfers, debit/credit cards, real-time payments, and peer-to-peer apps offer faster, more secure, and more convenient ways to pay.

Secure payment processing solutions for your business | Host Merchant Services.

City on Crypto: Inside Lugano’s Bold Bitcoin Adoption Experiment

A Swiss city is making crypto history. Lugano, a picturesque city in southern Switzerland, has transformed itself into a living laboratory for cryptocurrency adoption. As of late 2025, more than 350 shops and businesses in Lugano accept Bitcoin as payment. Even the city government takes Bitcoin (and the stablecoin Tether, USDT) for certain fees and taxes. Dubbed as “Plan ₿” – it aims to integrate digital currencies into everyday life.

The city partnered with Tether to advance crypto-friendly policies, rolled out Bitcoin payment terminals across the city, and aims to create a circular economy where users can earn and spend crypto locally. Below, we’ll discuss Lugano’s ambitious experiment in detail.

Lugano’s Plan ₿: A City’s Crypto Vision

Luganos Plan ₿ 1

In March 2022, Lugano’s city government launched Plan ₿ in collaboration with Tether, the issuer of the USDT stablecoin. The goal was clear: make Lugano a European blockchain hub and a pioneer in crypto-friendly living. City officials saw embracing cryptocurrency as an economic opportunity. By positioning Lugano as a “Crypto City,” they hoped to attract fintech innovation, blockchain startups, and tech tourism. This meant weaving crypto into daily transactions and public services, effectively putting Lugano on the map as a forward-thinking digital finance center.

From the outset, the Plan ₿ initiative announced that Bitcoin, Tether (USDT), and the city’s own LVGA token would be accepted for a range of municipal payments. Residents and companies could pay taxes, parking fines, public service fees, and even tuition in cryptocurrency if they choose. This move was not just symbolic – it aimed to demonstrate that Bitcoin and other digital currencies could coexist with the Swiss franc in a modern economy.

To support the plan, Tether and its partners also created a 100 million Swiss franc fund to invest in crypto startups in the region, and a 3 million CHF fund to help local businesses adopt crypto. The message was that Lugano is “open for crypto business,” providing both the regulatory framework and financial incentives to make blockchain technology part of the city’s fabric.

Building a Crypto-Friendly City: From Shops to City Hall

Crypto-Friendly City

Turning vision into reality required building an entire ecosystem. Over the next few years, Lugano’s administration worked closely with Tether and tech firms to implement crypto payments in practice. A crucial step was distributing free crypto point-of-sale terminals to local merchants. Hundreds of Lightning Network-enabled payment devices were distributed, enabling businesses to accept Bitcoin seamlessly.

By late 2025, more than 350 merchants – from family-run cafes and pizzerias to major retail chains like McDonald’s – had integrated these Bitcoin payment terminals. Shops display stickers or signs indicating they accept Bitcoin (alongside traditional methods), and staff are trained to handle crypto transactions.

Not just shops joined the experiment. Municipal offices also got on board. The city’s IT systems enabled Bitcoin and USDT payments for many services: you can scan a QR code on your tax bill or utility invoice and pay with crypto through your smartphone wallet. Essentially, Lugano began treating Bitcoin and Tether as de facto legal tender for city fees.

While not an official currency (the Swiss franc remains the sole legal tender), these cryptocurrencies are accepted in practice for public payments in Lugano, much like cash or cards. This was a bold policy choice – few places in the world allow taxes in crypto – and it signaled how serious Lugano was about mainstreaming digital currency.

How Does a Bitcoin Payment Work in Lugano?

Suppose you’re grabbing a coffee or paying for groceries at a participating store. At checkout, the merchant’s tablet or terminal will generate a QR code invoice for the amount (converted to BTC at the current rate). You open your Bitcoin wallet app on your phone, scan the code, and approve the payment. Within seconds (thanks to the Lightning Network, which enables fast and low-fee Bitcoin transactions), the payment is confirmed.

If you prefer using Tether (USDT) – a cryptocurrency pegged to the US dollar – many merchants accept that as well, which functions similarly via a QR code scan. For the user, it feels as easy as using any mobile payment app. For the merchant, the Bitcoin payment terminal handles the conversion and confirmation behind the scenes.

Everyday Life with Crypto: Can You Live on Bitcoin in Lugano?

By 2025, Lugano officials proudly claim that a resident can cover most daily needs with cryptocurrency. Walk through the city, and you’ll find coffee shops, restaurants, clothing boutiques, supermarkets, hotels, and even yoga studios that will cheerfully take your sats (the term for small fractions of Bitcoin) or USDT. Want to grab a pizza or pay for a haircut? In many cases, simply scan and pay with Bitcoin. Need to refill your parking card or pay a public school fee? The city’s online portal will accept your crypto payment. Even at the local McDonald’s, you can buy a Big Mac with Bitcoin via a phone tap – a novelty that attracts crypto enthusiasts from abroad.

However, reality is more nuanced than a total crypto utopia. Early real-world tests and experiences show there are still gaps. For instance, public transportation, fuel stations, and some utility providers were not yet accepting crypto as of 2025 – so you can’t completely ditch your francs for every expense.

So, while you can do a majority of your daily shopping in Bitcoin, you might still need traditional money for a few things. The city is working to close these gaps, aiming for an ideal “circular economy” where salaries, bills, and purchases could all occur in crypto if desired.

Public Response: Enthusiasm, Curiosity, and Caution

Public Response in Lugano

Lugano’s bold Plan ₿ has certainly put it in the spotlight. The city has hosted numerous blockchain events and conferences, including the annual Plan ₿ Forum, which in 2025 attracted around 4,000 attendees from 60+ countries. This has boosted tech tourism and attracted more than 110 crypto-related companies to establish operations in Lugano, ranging from startups to established blockchain firms. In terms of infrastructure and publicity, the project is a success – few other places can claim an entire city zone where digital currency is so widely accepted.

But what about the average Lugano resident or shopkeeper? Are they embracing Bitcoin in daily life? The response has been mixed and gradual. Many local businesses signed up to accept crypto, enticed by the city’s push and some clear perks. Merchants often cite lower transaction fees as a key advantage: processing a Bitcoin payment via Lightning can cost well under 1%, compared with 2–3% on credit card sales.

For a small café or retail shop, that means keeping more of their revenue. The city’s free provisioning of POS terminals also made it low-risk for businesses to join – they didn’t have to invest in expensive new equipment or software.

Despite the infrastructure, consumer adoption of crypto has been modest so far. Many residents continue using Swiss francs or credit cards out of habit or trust. For now, crypto transactions are sporadic – a novelty rather than a norm. However, merchants like him remain optimistic, viewing this as a long-term play: as more people hold crypto and comfort grows, today’s handful of transactions could grow into a significant share of sales in years to come.

Among the general public in Lugano, sentiments vary from enthusiasm to skepticism. There is a core community of crypto believers excited to be part of this pioneering project – they attend Bitcoin meetups, use the city’s MyLugano app to get cashback in LVGA tokens, and proudly demonstrate living on crypto. A larger portion of residents are neutral: they don’t mind that Bitcoin is accepted everywhere, but they personally haven’t felt the need to use it. There are also skeptics who voice concerns.

Some associate Bitcoin with speculation, volatility, or even crime (given media reports of scams or darknet usage). For example, a local university student interviewed by the media said she was wary of cryptocurrencies due to their volatile price swings and news of hacks – to her, they’re not something “real” to trust for daily spending.

Notably, Lugano has not experienced any major backlash or protests against the crypto initiative. Because Plan ₿ operates alongside (and not replacing) traditional money, most people tolerate it even if they’re indifferent – after all, no one is forced to use Bitcoin if they don’t want to. This coexistence of crypto and fiat in the city is a deliberate strategy to encourage gradual adoption rather than impose change.

Benefits and Early Outcomes

Even with cautious adoption, Lugano’s crypto experiment has yielded some tangible benefits:

  • Economic Development:

The city’s crypto-friendly reputation attracted more than 100 blockchain companies, creating jobs and investment. Lugano is now on the map as a go-to destination for crypto startups in Europe, exactly what city officials hoped for.

Conferences and events bring in visitors and business opportunities, diversifying the local economy beyond traditional finance and tourism.

  • Financial Innovation for Locals:

Through the MyLugano app, residents who choose to pay with crypto get rewarded. The city implemented a loyalty program where paying at local shops in BTC or USDT earns you cashback in LVGA tokens (Lugano’s own digital token pegged to the Swiss franc).

Users can receive up to 10% of their spending back in LVGA, which they can use for other purchases or to pay for city services. This incentive encourages people to try using crypto and helps keep value circulating locally (a step toward the circular economy vision).

  • Marketing and Modern Image:

Lugano has differentiated itself from other Swiss cities with this initiative. The “Crypto City” branding has drawn positive global media coverage and interest from technology circles.

At a time when many governments are cautious about crypto, Lugano’s proactive approach signals that it is an innovative, forward-looking city. This image can yield long-term benefits by attracting young talent, forward-thinking businesses, and tourism.

  • Merchant Savings:

As mentioned, lower transaction fees and the lack of chargebacks (crypto payments are irreversible) can help merchants save money compared to card payments. For small businesses, a few percentage points off fees is meaningful.

Some business owners also appreciate the option to accept crypto payments online without complex banking setups.

Of course, these benefits come with caveats – they are contingent on crypto being used and valued. This leads to the key challenges Lugano faces.

Challenges and Criticisms

No bold experiment is without hurdles, and Lugano’s crypto adoption drive has plenty:

1. Price Volatility:

Bitcoin’s value swings wildly at times. This is perhaps the biggest concern for anyone using it as a day-to-day currency. Neither shops nor the city government wants to expose themselves to the risk of holding volatile crypto for an extended period. Lugano’s solution is that most merchants (and the city itself) convert incoming Bitcoin to Swiss francs almost immediately.

Payment processors and services (e.g., a partnership with Bitcoin Suisse) facilitate instant conversion: when you pay 10 CHF worth of BTC for a coffee, the merchant can have it settled instantly as 10 CHF in their bank account or as a CHF-backed stablecoin. This shields them from losses if the BTC price drops later. It means, however, that in many cases, Bitcoin is more of a medium of exchange than a unit that local businesses actually keep.

Some crypto-enthusiast merchants do hold onto a portion of their Bitcoin sale,s hoping the price will rise, but it’s not the norm. The city has also officially adopted Tether (USDT) for payments, precisely because it is a stablecoin pegged to the dollar, reducing transactional volatility. Still, the reliance on instant conversion shows that Bitcoin-as-cash is a tough sell until its value stabilizes.

2. Technical and Custodial Risks:

Using crypto in daily life introduces technical considerations that most people aren’t used to. You must manage a digital wallet, secure your private keys, or trust a service to hold funds. If a user stores their Bitcoin in a mobile app or on an exchange, there’s a custodial risk – if that platform were to fail, get hacked, or go bankrupt, their money could vanish with no recourse (unlike a bank, where deposits are insured by the government up to a certain amount).

Swiss financial safeguards, such as deposit insurance, don’t cover crypto assets. Local experts have warned merchants and users about these risks; for instance, a finance professor at the University of Lugano advised anyone accepting Bitcoin to immediately convert it to fiat and not leave it in an online wallet to avoid being caught in an exchange failure.

Additionally, while the Lightning Network and payment apps are improving, there can be technical hitches – a user might fumble with an unfamiliar wallet app, or a payment might fail due to network issues, causing delays at checkout. These are new headaches that merchants have had to learn to troubleshoot on the fly.

3. Consumer Protection and Education:

Along with technical risks, there’s the matter of consumer rights and knowledge. Crypto transactions are largely irreversible – if you accidentally send Bitcoin to the wrong address or fall for a scammy QR code, you can’t call a bank to cancel the payment.

This means both shoppers and businesses must be extra vigilant, and it raises questions about refunds or disputes. How do you issue a refund for a returned item that was paid in Bitcoin? Likely through crypto as well, which not all customers might handle easily. The city and crypto advocates have been running education campaigns to teach people how to use wallets, how to transact safely, and the associated risks. But it’s a learning curve, and not everyone is comfortable with it yet.

4. Reputational Concerns (Crime and Illicit Use):

Cryptocurrencies have a lingering reputation in some circles as being associated with money laundering, tax evasion, or black-market dealings. By openly embracing crypto, Lugano has had to address these concerns. Critics worry that allowing anonymous digital cash-like payments could attract bad actors or at least raise regulatory concerns. Lugano officials, however, have been quick to point out that all crypto usage in the city follows Swiss regulations – for example, exchanges and crypto services must comply with anti-money laundering rules just like banks.

Furthermore, the mayor has publicly argued that cash is far more attractive to criminals than Bitcoin. Bitcoin transactions are recorded on a public ledger, making large illicit transfers easier to trace in many cases, whereas physical cash can circulate with total secrecy. The city insists that encouraging Bitcoin use does not mean tolerating illegal activity, and so far, there haven’t been any high-profile incidents to undercut their stance. Nonetheless, reputational risk remains if, for example, a major fraud or money-laundering case were ever linked to Lugano’s crypto scene.

5. Adoption Remains Uncertain:

Perhaps the simplest criticism is: Will enough people actually use Bitcoin for this to matter? Skeptics label Plan ₿ as a PR stunt – a clever way to draw attention, but something that might never graduate beyond a niche usage. If the vast majority of residents and businesses stick to familiar francs, then all the crypto infrastructure might end up underutilized. The next few years will be crucial to see if usage grows or plateaus.

To address this, Lugano may consider incentives (for instance, some cities have given small discounts or bonuses for paying in crypto) to nudge people towards trying it. The city is playing a long game, betting that younger generations and the ongoing global digital finance trends will gradually boost everyday crypto use. If that bet fails and crypto interest wanes, Lugano could be left with many terminals and hype, with little to show for in terms of active users.

Lugano vs. Other Crypto Experiments

Lugano’s approach stands out because it’s a municipal initiative without a national mandate. This contrasts with places like El Salvador, which in 2021 went so far as to declare Bitcoin legal tender nationwide. El Salvador’s top-down law generated buzz, but on the ground, adoption by ordinary citizens and retailers has been minimal – most still prefer the dollar for stability. By not forcing Bitcoin use and instead encouraging it alongside fiat, Lugano may achieve steadier, organic growth in usage. People and businesses here have the freedom to opt in or out, which arguably leads to more genuine adoption (or at least, less resentment) than legal mandates do.

Other cities have also tried to brand themselves as crypto-friendly. For example, Ljubljana, Slovenia, has many merchants that accept cryptocurrency, and Zurich, Switzerland, has a vibrant crypto startup scene with some crypto payment options. Lugano is different in that the city government itself is deeply involved – it’s not just startups or independent businesses pushing it, but the public sector leading the charge.

This public-private partnership via Plan ₿ is what enabled the scale (350+ merchants) in a short time, through subsidies and official support. This city-led model could serve as a blueprint for others, provided it manages the associated risks. If Lugano’s experiment shows positive outcomes with manageable downsides, it could inspire other cities or regions to dip their toes into crypto integration in a controlled manner.

Conclusion

As 2025 turns into 2026, Lugano finds itself at the forefront of a financial experiment that the world is watching. The city has successfully built the scaffolding for a crypto-based economy – the payments network, the legal framework, merchant buy-in, and public awareness are all in place. The coming years will test whether usage catches up with infrastructure. City officials remain optimistic that as Bitcoin and crypto become more mainstream globally (and as user-friendly tools improve), Lugano will be ready and ahead of the curve. They see their city as having a first-mover advantage if a blockchain-based economy truly takes off.

For now, Lugano offers a unique case study. It shows that with political will and strategic partnerships, it’s possible to bring crypto into daily commerce at a city scale. It also highlights the challenges of doing so: the work doesn’t end at installing payment terminals – you have to win hearts and minds, ensure security, and bridge traditional finance with the new world of crypto. Whether Lugano’s bold Plan ₿ will be remembered as a visionary success or an overhyped side note of the 2020s remains to be seen.

One thing is certain: this Swiss city has demonstrated that Bitcoin can find a home in everyday transactions, not just in online forums or investment portfolios. In Lugano, the cryptocurrency dream is walking the streets, buying coffee, and paying taxes – even if only a handful of citizens are doing it to start, the very fact they can is historic.

FAQs

Why did Lugano choose to support Bitcoin and crypto?

Lugano launched its “Plan ₿” initiative to position the city as a European blockchain hub. The goal is to attract fintech innovation, startups, and investment by integrating crypto into everyday commerce alongside traditional money.

How can people use Bitcoin in Lugano today?

Hundreds of local businesses accept Bitcoin for everyday purchases, and residents can also pay certain city fees using crypto. Payments are processed via simple QR code scans with a mobile wallet, similar to other digital payment methods.

How does Lugano handle Bitcoin’s price volatility?

Most merchants use payment processors that convert Bitcoin instantly into Swiss francs or stablecoins. This lets them accept crypto without taking on the risk of sudden price swings.

Has Lugano’s crypto adoption been successful so far?

Infrastructure adoption has been strong, with many businesses participating and international interest growing. Actual daily usage is still gradual, but the city views this as a long-term experiment rather than an overnight shift.

What risks or criticisms does Lugano face with this approach?

Concerns include price volatility, consumer protection, and reputational risk tied to crypto markets. The city addresses these by emphasizing regulation, stablecoins, and voluntary use alongside traditional payment options.

Crypto wallet app for easy cryptocurrency transactions and management on mobile devices.

Stripe Dives Deeper into Crypto: Acqui‑hires Valora Team to Boost Stablecoin Push

Stripe, the global payments giant, is doubling down on cryptocurrency – particularly on stablecoins – as it makes another strategic acquisition in the crypto space. In its latest move, Stripe has acquired the entire team behind Valora, a mobile crypto wallet startup. This quiet talent grab is designed to accelerate Stripe’s growing stablecoin initiatives and signals Stripe’s intent to make stablecoin payments a mainstream part of its platform.

The Valora team’s expertise in user-friendly crypto apps and emerging markets will now be applied at Stripe, strengthening the company’s push to integrate stablecoins into everyday payments. This development comes on the heels of Stripe’s other big crypto bets – including a $1+ billion acquisition of a stablecoin infrastructure startup in 2024, and even the launch of Stripe’s own blockchain project.

In this blog, we’ll break down what the Valora acqui-hire means, how Stripe might leverage Valora’s self-custody and global crypto know-how, and how it fits into Stripe’s broader crypto roadmap.

Valora: A Mobile Wallet Born in the Celo Ecosystem

Save in stables with easy access to USDT, USDC, and more stablecoins on Host Merchant Services platform.

Valora is a crypto payments app best known in the Celo blockchain community. Launched in 2021 as a spin-off from Celo’s development lab (cLabs), Valora set out with a clear mission to make it easy for anyone to access and use digital money on their smartphone. The Valora app became a simple way to send, save, and spend stablecoins and other crypto assets with a mobile-first experience. It was designed for users in emerging markets who often lack access to traditional banking, offering a friendly, low-barrier gateway to crypto finance.

Valora enabled peer-to-peer transfers of Celo Dollar stablecoins as easily as sending a text, even in regions such as Africa, where stablecoins can provide a safe dollar-based currency amid local inflation.

Valora is a self-custodial wallet; users hold their own crypto keys, but it abstracts away much of the complexity of blockchain. The app links to your phone number and provides an intuitive interface, so users may not even realize they’re interacting with multiple blockchains under the hood. (In fact, Valora expanded beyond Celo to support assets on Ethereum and layer-2 networks like Optimism, to give users more access.)

Through a “user-first” design, Valora demonstrated that even non-technical users can leverage cryptocurrencies and stablecoins for everyday needs. Over a few years, Valora has grown into a trusted tool for moving money globally, demonstrating that digital transactions can be more inclusive than the traditional banking system. The team also gained experience in training new users and developing secure, lightweight wallet technology for low-end mobile devices.

All of this made the Valora team an attractive target for a company like Stripe, which is now aiming to bring crypto to millions of mainstream users. Then, in December 2025, Valora CEO Jackie Bona announced that her entire team would be “joining Stripe” to “accelerate our mission” of expanding financial access globally.

Notably, Stripe is not buying the Valora app or brand outright – the Valora wallet app will actually remain with cLabs (its original home) to continue serving existing users independently. Instead, Stripe is effectively hiring the people behind Valora. This kind of deal underscores that Stripe values talent and expertise above the product itself. So what expertise does Valora’s team bring that Stripe is eager to leverage?

Why Stripe Acqui-Hired the Valora Team

Secure payment processing solutions for businesses at Host Merchant Services.

Stripe’s core business is payments infrastructure, serving millions of online businesses. Historically, Stripe has focused on traditional payment methods (cards, bank transfers) in developed markets.

So why bring in a crypto wallet team from the Celo ecosystem? To supercharge Stripe’s stablecoin and crypto payments strategy with battle-tested crypto UX talent. The Valora team offers several strategic advantages:

  • Mobile & Emerging Market Experience:

Valora’s team has deep experience building payment products for mobile-first users in developing countries. They understand how to design ultra-lightweight, intuitive apps that work even on basic smartphones and in spotty internet conditions common in regions where crypto is most useful.

This complements Stripe’s goal of reaching global users outside the formal financial system. Stripe’s CEO, Patrick Collison, has noted that stablecoins could dramatically widen global economic participation, and Valora lived that vision on the ground.

  • User-Centric Crypto Design:

The Valora engineers and designers solved tricky problems around self-custody and security while keeping the user experience simple. They made sending a stablecoin as easy as sending an email.

Stripe can leverage this expertise to ensure its upcoming crypto features are easy for everyday consumers and small businesses to use. In other words, if Stripe wants to hide the complexity of blockchain from its users, Valora’s team has done exactly that before.

  • Stablecoin Payments Know-how:

Valora was built around stablecoins. The team has seen how people actually use stablecoins for daily needs, from remittances to savings, and the challenges involved (like volatility of other cryptos, or cashing in and out to local currency).

This real-world insight is invaluable as Stripe integrates stablecoins into its products. It aligns with Stripe’s view that stablecoins will be a “core upgrade to global money movement.”

  • Web3 Development Talent:

Beyond the wallet app, Valora’s team also dabbled in new decentralized app features (even a mobile-friendly dApp marketplace).

Bringing in this Web3-savvy talent gives Stripe a stronger bench to develop crypto features at scale, without having to hire from scratch in a competitive market. This marks Stripe’s third crypto-focused acquisition in just over a year, underscoring its aggressive effort to recruit top crypto talent.

Jackie Bona herself highlighted the synergy, noting that Stripe shares Valora’s conviction in the power of stablecoins and that, by joining Stripe, they can “contribute our expertise in web3 and user-first experiences to a platform with unparalleled reach.”

In other words, Stripe’s massive merchant and user base provides the scale to truly mainstream the kind of inclusive crypto tools Valora was building. For Stripe, absorbing Valora’s team is a way to accelerate product development on several fronts – whether that’s creating a seamless crypto wallet for Stripe users, enabling stablecoin payouts in more countries, or something else entirely.

We don’t yet know which projects this team will tackle within Stripe. Still, given Stripe’s recent initiatives (more on those next), it’s likely to involve making stablecoin use ubiquitous and easy across Stripe’s ecosystem.

Stripe’s Expanding Stablecoin Strategy: From Bridge to Tempo

Stablecoin1

Stripe has spent the past two years pivoting hard into stablecoins as the future of payments. Let’s recap Stripe’s key moves:

  1. Bridge (Oct 2024) –

Stripe made headlines by acquiring Bridge, a little-known stablecoin infrastructure startup, for a whopping $1.1 billion. This was Stripe’s largest crypto acquisition to date. Bridge provides a suite of APIs that enable developers to integrate stablecoins into payments applications, handling complex components such as fiat on- and off-ramps and blockchain interactions.

Stripe’s CEO even described stablecoins as “room-temperature superconductors” for finance, implying they can transmit value with near-zero friction and revolutionize payments. Buying Bridge gave Stripe an engine to enable low-cost, instant cross-border transactions using stablecoins.

  1. Privy (June 2025) –

Next, Stripe acquired Privy, a crypto wallet infrastructure provider, for an undisclosed sum. Privy specializes in tools that let companies build user-friendly crypto wallets and identity management into their apps. By bringing Privy in-house, Stripe gained technology to support digital wallets and secure crypto storage for its customers.

In fact, Stripe’s Privy unit has already partnered with fintech giant Klarna to design a prototype crypto wallet for everyday shoppers. Klarna has launched its own stablecoin, indicating that prominent fintechs are also exploring this space. The Privy acquisition signaled that Stripe wants to make holding and using crypto seamless for mainstream users, not just back-end developers.

  1. Open Issuance (Oct 2025) –

About a year after buying Bridge, Stripe rolled out Open Issuance, a new platform that allows any business to launch and manage its own stablecoin with just a few lines of code. This Stablecoin-as-a-Service offering enables a company (e.g., a large e-commerce or fintech firm) to create a branded, fully reserved stablecoin and use it in its products.

Importantly, Stripe’s platform handles compliance, reserve management, and blockchain connectivity, making it easy for non-crypto companies to leverage this technology. Open Issuance even lets businesses capture interest on stablecoin reserves (typically held in safe assets such as U.S. Treasuries), creating a new revenue stream.

Early partners using Stripe’s Open Issuance include crypto-native firms (Phantom wallet launched a token, as have others). Still, Stripe predicts “dozens, if not hundreds,” of companies could issue stablecoins in the coming months. This move positions Stripe as a key enabler in the proliferation of stablecoins beyond just Circle’s USDC or Tether – potentially every major company could one day have its own stablecoin running on Stripe’s rails.

  1. Tempo (Dec 2025) –

Perhaps the boldest piece of Stripe’s plan: building its own blockchain. Stripe has unveiled Tempo, a new Layer-1 blockchain network optimized for stablecoin payments. Developed in collaboration with crypto VC firm Paradigm, Tempo is designed to be a high-performance, low-cost settlement network for digital money.

Its public testnet went live in December 2025, allowing developers to experiment. One notable demo feature: developers can spin up new stablecoins directly in their web browser with minimal code.

This suggests Tempo’s aim to significantly lower the barrier to entry for creating and transacting in stablecoins. Stripe has indicated that stablecoins issued through its Open Issuance will be interoperable across multiple chains, including Ethereum, Solana, and, eventually, Stripe’s own Tempo network.

That means if Tempo becomes fully operational, it could serve as a unifying backbone for stablecoin liquidity, connecting all these custom stablecoins and enabling them to move freely at scale. Essentially, Stripe is not just using existing blockchains; it’s building one tailored to global payments.

Stripe is assembling a full-stack stablecoin ecosystem: infrastructure (Bridge), wallets (Privy & Valora), issuance (Open Issuance), and a payment network (Tempo). The Valora team fits into this puzzle by strengthening the wallet/user-experience side and lending their perspective on how people actually use stablecoins day-to-day.

Their arrival at Stripe comes at an exciting juncture – right as Stripe’s stablecoin ambitions are shifting from development phase to real-world rollout.

Bringing Stablecoins to Mainstream Payments

Stripe’s recent crypto moves, capped by the Valora acqui-hire, reflect an apparent belief that stablecoins are becoming a practical layer of mainstream finance. Stablecoins enable fast, low-cost cross-border payments that traditional systems struggle to match, which explains the growing interest from companies like Visa, PayPal, and now Stripe. For Stripe, stablecoins fit naturally with its goal of supporting global commerce.

What sets Stripe apart is its focus on user experience. Instead of pushing crypto complexity onto consumers, Stripe is embedding stablecoins into familiar payment flows. With Valora’s expertise, Stripe can design products where users hold or send “digital dollars” through simple interfaces, without dealing with wallets, keys, or blockchains directly.

For businesses, this strategy could unlock faster settlements, global payouts, and new digital currencies issued through Stripe’s infrastructure. Regulatory and competitive pressures remain, but Stripe’s scale, compliance track record, and platform-first approach suggest stablecoins will increasingly feel like a regular part of online payments rather than a niche crypto feature.

Conclusion

Stripe’s acqui-hire of the Valora wallet team signals a deep commitment to crypto, especially stablecoins, as future payment rails. With talent spanning consumer wallets, infrastructure, and issuance, Stripe is positioned to launch fast, global, stablecoin payments. Regulatory response and user adoption remain open questions, but Stripe’s strategy shows long-term conviction rather than experimentation over the next several years worldwide.

Frequently Asked Questions

  1. Why did Stripe acquire the Valora wallet team?

    Stripe acqui-hired the Valora team to strengthen its crypto and stablecoin capabilities. The team brings experience in building user-friendly crypto wallets and mobile-first stablecoin payments.

  2. What is Stripe’s strategy around stablecoins and crypto?

    Stripe aims to make stablecoins a core part of global payments. It is building a full infrastructure for issuing, holding, and using stablecoins, with a focus on speed, access, and usability.

  3. Will the Valora app continue to operate?

    Yes. Stripe did not acquire the Valora app itself; it acquired only the team. The app will continue under its original organization, while the team now works on Stripe’s crypto products.

  4. How could Stripe’s stablecoin efforts benefit merchants and consumers?

    Stablecoins could enable faster, always-on payments with lower cross-border costs. Merchants may see quicker settlement, while consumers gain more flexible ways to pay globally.

  5. Is this part of a broader trend in the payments industry?

    Yes. Major payment companies are exploring stablecoins to enable faster, cheaper transactions. Stripe’s move reflects a broader shift toward crypto talent and blockchain-based payment infrastructure.

Contactless payment solutions for small businesses and retail stores.

Fintech Megadeal: Mollie to Acquire GoCardless and Build a Payments Powerhouse

Europe is set to witness a major fintech consolidation. Dutch payments firm Mollie has agreed to acquire UK-based GoCardless in a blockbuster deal reportedly valuing GoCardless at around $1.1 billion. This merger will combine two of Europe’s fastest-growing fintech companies into one of the most comprehensive payment platforms in the region.

After the Mollie-GoCardless deal, the combined entity will serve over 350,000 businesses across card payments, bank payments, and local “hyperlocal” payment methods, creating a single solution for merchants to handle a wide range of transactions. The deal, announced in December 2025, is subject to regulatory approval and expected to close by mid-2026. It marks one of the most significant European fintech acquisitions in recent years, underlining the trend of consolidation in the payments industry.

In this article, we’ll explore why this acquisition is happening now, including GoCardless’s path to profitability, its decision to pursue a buyer rather than an IPO, and the implications for merchants.

Mollie-GoCardless Deal: Combining Complementary Strengths

Mollie-GoCardless Acquisition

Mollie and GoCardless bring together highly complementary strengths to form a payments powerhouse. Mollie, founded in 2004 in the Netherlands, began as a payment service provider focused on online card payments and local payment methods for small- to medium-sized businesses.

Over two decades, Mollie has grown into a full-scale financial services platform, now offering not only card acquiring but also support for local payment options (such as iDEAL in the Netherlands), fraud prevention tools, financing (Mollie Capital), and robust APIs for integrations. Mollie serves over 250,000 merchants across more than 30 European markets, helping many of them accept payments online and in-store with ease. However, Mollie lacked its own debit payment network for account-to-account transactions.

GoCardless, on the other hand, was founded in London in 2011 with a very different focus: direct bank-to-bank payments. GoCardless built a global network for recurring payments using bank-to-bank debit systems (such as Bacs in the UK, SEPA Direct Debit in Europe, ACH in the US), enabling businesses to collect payments directly from customers’ bank accounts.

This approach offers lower failure rates and costs than card transactions, making it especially useful for subscription and invoicing scenarios. GoCardless today operates in 30+ countries and processes over $130 billion in payments annually, serving more than 100,000 businesses ranging from startups to large enterprises. It has become a go-to solution for companies with recurring revenue models, helping them reduce involuntary churn (from expired or declined cards) and streamline recurring billing.

By acquiring GoCardless, Mollie will integrate this global bank debit capability into its platform, combining cards and bank payments under one roof. Together, they can offer merchants a one-stop shop for payments. This merger creates a single provider serving over 350,000 businesses, integrating card payments, local methods, and bank payments into a single solution. Merchants of all sizes will be able to accept credit/debit cards, take direct bank payments (including recurring direct debits), and support local payment options, all through one unified platform.

GoCardless’ CEO Hiroki Takeuchi noted that by combining their expertise in card, bank, and hyperlocal payments into a single provider, they can better serve customers, accelerate growth, and raise the bar for the industry. Mollie’s CEO Koen Köppen echoed that sentiment, calling the deal a huge step toward fulfilling Mollie’s vision of “one complete platform for sustainable growth”.

Why This Mollie-GoCardless Acquisition, and Why Now?

Mollie-GoCardless Merger

Several factors explain why Mollie and GoCardless are merging now. One key reason is the changing market environment for fintech and payments companies. After years of rapid growth, fintech firms have faced pressure to achieve profitability and scale amid tougher economic conditions. GoCardless is a prime example: the company had reached unicorn status with a $2.1 billion valuation in early 2022, but the broader tech market downturn in 2022-2023 reset valuations across the industry.

Rather than chasing an IPO at a much lower valuation, GoCardless explored strategic options and began discussions with potential acquirers in 2025 (at one point even engaging with another fintech, Trustly). By late 2025, Mollie emerged as the frontrunner and ultimately the buyer. Market conditions – including lukewarm IPO markets and declining late-stage funding – made a sale to a well-capitalized partner an attractive path.

Just as important, GoCardless had been steering toward profitability, making itself a more appealing acquisition target. In recent years, GoCardless shifted from a “growth-at-all-costs” approach to a focus on sustainable finance. The company reportedly halved its pre-tax losses to ~£35 million for the year ending June 2024, and was on a clear trajectory toward profitability, aiming to post its first full-year profit by 2026.

In fact, CEO Hiroki Takeuchi told reporters in early 2025 that GoCardless was aiming to break even by the end of that year. This financial discipline proved crucial – acquirers value fintech businesses that have a credible path to profit, especially in a climate where investors are less willing to fund heavy losses. By late 2025, GoCardless’s fundamentals (growing revenues, up 38% year-on-year to £126.8M, and improving margins) made it an attractive target, even if its price tag was lower than during the 2021 funding boom. Takeuchi’s decision to sell to Mollie rather than pursue an IPO reflects a pragmatic assessment of these conditions and what would best support the company’s long-term mission.

Another factor is the broader trend of consolidation in the payments sector. Payment providers of all sizes are facing margin pressures, rising compliance costs, and a slowdown in venture capital funding, prompting many to consider mergers to achieve greater scale and efficiency. Combining forces can help them defend market share and offer a more complete suite of services to customers.

Mollie’s acquisition of GoCardless is a clear example of this consolidation trend – it’s one of the largest European fintech deals since the early open banking wave began. By merging, the companies aim to be stronger together in an increasingly competitive landscape.

Importantly, the deal also comes amid a shift in Europe’s payments landscape toward account-to-account (A2A) payments. Regulatory initiatives such as PSD3 and the upcoming Open Banking Regulation are pushing banks to open up account access and to adopt cheaper, faster payment methods beyond traditional card networks. At the same time, industry efforts such as the European Payments Initiative (EPI) are developing a pan-European instant payments network.

These developments signal that bank payments are gaining traction – especially for use cases like subscriptions, digital services, and marketplaces where merchants are looking to cut costs and reduce reliance on card networks.

GoCardless, being a leader in bank-to-bank payments, has benefited from this shift (signing up partners in SaaS and other sectors riding the open banking wave). Mollie, which excelled in card payments and local methods, likely saw the writing on the wall: to remain competitive in the coming years, a payments provider needs to offer multi-rail capabilities (i.e., both card and bank payment rails) on a unified platform. By acquiring GoCardless now, Mollie capitalizes on A2A momentum and ensures it can meet merchants’ growing demand for direct bank payments alongside cards.

Finally, there’s a straightforward synergy argument. Each company gains something it was looking for:

  • For Mollie: the addition of GoCardless instantly provides deep bank-payment coverage across Europe (and into North America/Australia, where GoCardless has a presence). It strengthens Mollie’s offering for recurring revenue businesses, a segment Mollie has been targeting, by solving the involuntary churn issue that pure card-based billing faces. It also enhances Mollie’s move upmarket – adding GoCardless’s enterprise clients and capabilities will bolster Mollie’s appeal to larger merchants beyond its SME core.
  • For GoCardless: partnering with Mollie provides access to a much larger distribution network of SMEs and mid-market merchants where Mollie is strong. Instead of going it alone or trying to IPO, GoCardless can leverage Mollie’s sales channels, integrations (e.g,. Mollie Connect for software platforms), and established brand among online businesses. It also means GoCardless’s technology can be embedded into many more checkout flows and merchant services via Mollie’s platform. This can accelerate GoCardless’s growth beyond what it might achieve as a standalone company.

GoCardless’s Path to Profitability and the Road to Exit

Mollie

It’s worth zooming in on GoCardless’s journey in the lead-up to this acquisition, as it illuminates why the company chose this path. Founded in 2011, GoCardless spent much of the 2010s in growth mode, raising over $600 million in venture capital and expanding its reach across the UK, Europe, North America, and the Asia-Pacific. By 2022, it had achieved unicorn status with a $2.1B valuation and processed tens of billions in annual payments. However, like many fintechs of that era, GoCardless was not profitable and instead prioritized growth and market expansion.

Around 2023-2024, the company and its investors recognized the need to shift gears toward profitability. This was partly driven by market conditions (as venture funding became harder to secure, and public markets punished unprofitable tech companies) and partly by the company’s maturation.

GoCardless began tightening its financials: as noted, it cut its losses by 50% (to ~£35M) in the year to mid-2024 and signaled a clear plan to reach profitability by 2026. The firm’s revenue was growing healthily – up 38% year-on-year in its last fiscal report – indicating that its core business (collecting fees on direct debit transactions) was scaling well. In an interview earlier this year, CEO Hiroki Takeuchi expressed confidence that GoCardless could reach breakeven in the near term.

By late 2024, GoCardless’s leadership had to evaluate the best way forward: continue as an independent company (perhaps aiming for an IPO down the line) or combine with a larger partner. The IPO route looked challenging – fintech IPOs had stalled mainly, and achieving a multi-billion valuation again in a public offering was uncertain.

Meanwhile, larger payment players were expanding their product lines, and GoCardless risked being outpaced if it remained a niche specialist. In this context, GoCardless entertained acquisition talks. The company engaged with multiple potential acquirers in 2025. Ultimately, Mollie was the best fit, both in terms of vision and the complementary nature of their products.

Takeuchi’s decision to sell to Mollie rather than pursue an IPO was calculated. In other words, joining forces with Mollie offered immediate scale and resources to GoCardless, plus the opportunity for GoCardless’s shareholders (and employees with equity) to potentially benefit from the combined company’s success (the deal is reportedly a mostly-stock transaction, meaning GoCardless stakeholders will receive shares in Mollie’s expanded business).

Importantly, choosing an acquisition doesn’t signal failure – it can simply be the smarter path in a given climate. Many fintechs that boomed in the 2010s are now finding strategic buyers rather than going public, especially when those buyers can accelerate their growth.

GoCardless’s solid fundamentals, strong product, global reach, and improving finances ensured that it was acquired from a position of strength, not distress. And by aligning with Mollie, GoCardless can aim for an even larger impact than it might have achieved solo, essentially betting that the combined entity will be greater than the sum of its parts.

Mollie-GoCardless Merger – An Integrated Payment Solution for Merchants

For merchants and businesses using these services, the Mollie-GoCardless merger promises a host of benefits. The most immediate impact is the availability of an integrated payment solution that covers virtually all the payment methods a merchant might need – cards, bank debits, and a variety of local payment options – all through one platform. This addresses a long-standing pain point for businesses, especially those that operate online or across borders: traditionally, a merchant might use one provider for card processing, another for direct debit or bank transfers, and yet others for country-specific methods (like iDEAL, Bancontact, Sofort, etc.).

That patchwork approach can be fragmented and complex, requiring multiple integrations and vendors. The combined Mollie-GoCardless platform aims to give SMBs and enterprises a single partner for all these needs, simplifying their payment stack. In practical terms, a merchant can log in to a single dashboard to manage credit card payments, set up recurring direct debit plans, and accept local e-wallets or bank apps, without juggling separate systems. This unified approach can save time, reduce technical headaches, and potentially lower costs through consolidated pricing.

Recurring revenue businesses (subscription-based companies) stand to gain significantly. The card-only approach has its limits for subscriptions. Many subscription businesses struggle with involuntary churn: customers unintentionally cancel when their card expires or their payment fails. GoCardless’s bank debit system offers a more reliable way to collect recurring payments (bank accounts don’t expire like cards, and direct debits have higher success rates), which can drastically reduce failed payments and customer churn.

By incorporating GoCardless, the new platform will enable merchants to easily offer customers a bank debit option at checkout or for subscription billing. Lower failed payment rates mean steadier cash flow for merchants and fewer subscription interruptions for customers.

Additionally, transaction fees for direct bank payments are often lower than card processing fees (since they bypass card networks), so merchants can reduce costs on a portion of their transactions by encouraging bank payments where suitable. All of this contributes to better subscription management and revenue optimization for businesses, a key selling point of the merger.

Merchants pursuing international expansion will also benefit from the powerhouse combination. Together, Mollie and GoCardless cover a broad geographic footprint and support a wide range of payment methods preferred in different regions. The merged platform will support local payment schemes across Europe and beyond, for example, iDEAL in the Netherlands, Satispay in Italy, Twint in Switzerland, and so on, alongside global card schemes and direct debit in major currencies.

This means a business using Mollie-GoCardless can easily accept payments from customers in multiple countries in their preferred local method, increasing conversion rates. The companies have emphasized “hyperlocal” capabilities: integrating with local banking systems and, in some cases, local business software or reporting formats to make operating in each country as smooth as possible.

For a merchant, expanding into a new European market could be as straightforward as enabling a new payment method on the platform, rather than signing a contract with a new local payment processor. In essence, the combined platform offers a frictionless global expansion path for merchants, handling the messy payment infrastructure behind the scenes.

Even smaller businesses (SMEs) stand to gain access to more advanced tools that were traditionally the domain of larger enterprises. Mollie has built features such as analytics, fraud prevention, financing options, and a marketplace for integrations. By folding GoCardless’s capabilities into the mix, those features now extend to bank payment flows as well. Mollie says the combined platform will let big companies unify their Europe-wide payments in one place, while giving smaller businesses advanced capabilities that are simple to use.

A small business using Mollie could tap into GoCardless’s Success+ tool (which intelligently retries failed direct debit payments at optimal times) or offer installment plans by combining card and bank debit options, sophisticated payment strategies that can improve cash flow and customer experience, now available to businesses of all sizes. Additionally, software platforms that use Mollie Connect (Mollie’s solution for SaaS companies and marketplaces to embed payments) will be able to integrate GoCardless’s bank debit network for their end-users with minimal effort.

This opens the door to a variety of apps and services (e.g., subscription management software and billing platforms) to easily offer both card and bank payment options natively to customers through a single integration.

Industry Impact and Future Outlook

The merger of Mollie and GoCardless affects not only their customers but also has broader implications for the payments industry, especially in Europe. For one, the combined company will become one of the largest independent payment platforms in Europe, which could ramp up competitive pressure on other providers. Global players like Stripe, Adyen, and Checkout.com have already been building out multi-rail payment capabilities (supporting both cards and bank payments).

With Mollie-GoCardless joining forces, merchants now have a strong European-based alternative offering similar breadth. This could prompt all players to further innovate and enhance their integrated offerings, ultimately benefiting merchants by providing more choice and better pricing over the long term. The race to build a single, multi-rail payments operating system for Europe is clearly accelerating, and Mollie’s megadeal is a bold move in that direction.

The acquisition also underscores the validity of Open Banking and bank payment solutions in the mainstream payments mix. Just a few years ago, direct debit and bank-to-bank payments were often seen as niche or supplementary methods (useful for utilities or payroll, but not front-and-center in e-commerce). Now, with one of the continent’s major payment firms betting big on bank payments by acquiring GoCardless, it’s a strong signal that account-to-account payments have arrived as a core offering.

As regulators continue to push for open banking adoption (making it easier for licensed fintechs to initiate payments directly from bank accounts), we can expect more merchants to adopt these methods, especially to avoid high card fees and to appeal to customers who prefer using their bank directly. The combined Mollie will be well-positioned to ride this wave, perhaps even influence standards, as it’ll handle a large volume of such transactions.

Of course, integration and execution will be critical in the coming months. Merging two sizeable fintech platforms is no small feat; technology systems need to be integrated, teams combined, and customers kept happy throughout. The companies have stated that the integration of GoCardless’s network into Mollie will be phased to avoid disruption and that they’ll continue to support all existing customers throughout the transition.

Regulators will also scrutinize the deal (particularly competition authorities in the EU and UK), given the substantial share of the direct debit market involved. However, there’s a chance of approval, as the European payments space remains fragmented and competitive, so a Mollie-GoCardless combination should not create a monopoly. If all goes as planned, the two companies will fully merge by mid-2026.

Looking further ahead, this deal could spur additional consolidation. As mentioned, many fintechs are facing similar pressures to expand their offerings and reach profitability. Europe in particular has a patchwork of payment startups specializing in various niches (from Buy-Now-Pay-Later to point-of-sale systems to crypto payments). We may see more mergers where complementary firms join to offer a broader suite, much like Mollie and GoCardless have done. This may be necessary to challenge the scale of US-based giants or to meet merchants’ demand for unified solutions.

Conclusion

Mollie’s acquisition of GoCardless is a major European fintech deal that combines card payments and merchant services with bank debit and recurring payments. Together, they can offer businesses a single platform for cards, bank debits, and local payment methods from day one.

The timing aligns with industry trends toward consolidation and shifting payment preferences. GoCardless gets a sensible exit after reaching profitability, avoiding a risky IPO, while Mollie gains scale and a broader product suite to compete globally.

If executed well, the merged company could reduce payment failures, simplify cross-border selling, and deliver more flexible, cost-effective payment options for merchants across Europe and beyond.

Frequently Asked Questions

Who are Mollie and GoCardless?Mollie is a European payment processor known for simple card and local payment integrations for online businesses. GoCardless focuses on bank-to-bank payments, helping companies collect recurring and invoice-based payments directly from customers’ bank accounts in many countries.

Why is Mollie acquiring GoCardless?The deal combines Mollie’s strength in card payments with GoCardless’s global bank debit network. Together, they can offer merchants one platform for one-time and recurring payments, while lowering costs and reducing failed subscription charges.

How large will the combined company be?The merged business will serve more than 350,000 merchants across Europe. It will support card payments, bank debits, and local payment methods at scale, positioning it as one of the most comprehensive payment platforms in the region.

What does this mean for existing customers?In the short term, services should continue as usual. Over time, Mollie users are expected to gain access to bank debit features, while GoCardless customers may be able to add card and alternative payment methods through a single platform.

Is this part of a broader trend in the payments industry?Yes. The acquisition reflects ongoing consolidation in fintech as companies seek scale, profitability, and broader product coverage. Combining card payments and bank debits under one provider is increasingly seen as a competitive advantage.

E-commerce transaction, online shopping, digital payment, mobile payment, merchant services, retail sales.

Social Commerce 2026: Integrating Payments with TikTok, Instagram, and More

Can a viral TikTok actually turn into instant sales? In 2026 and beyond, absolutely – social commerce has matured from a buzzword into a significant sales channel. A single trending video or Instagram post can now directly drive in-app purchases.

This means a frictionless shopping experience for consumers and a massive opportunity for businesses. Social commerce – selling products directly through social media platforms – has evolved into a full-fledged retail channel, especially among younger shoppers.

In this article, we’ll guide you through practical steps to ride this social commerce wave – from setting up shop on social platforms like Instagram and TikTok to optimizing the entire purchase experience. By the end, you’ll be ready to turn likes, shares, and follows into real revenue.

Why Social Commerce Is Now a Core U.S. Sales Channel?

Online retail growth with host merchant services and payment processing solutions.

To put the surge in perspective, here are a few eye-popping numbers illustrating social commerce’s rise:

  • Soaring Sales: U.S. social commerce sales are on track to reach around $90 billion in 2025, up from roughly $65 billion in 2023. By 2026, forecasts suggest this figure will exceed $100 billion, cementing social media as a multibillion-dollar retail channel.
  • Mainstream Adoption: Approximately one-third of young adults (ages 18–34) in the U.S. make purchases on social media each week. It’s not just occasional experimentation – for many, shopping on apps like TikTok or Instagram has become a weekly habit.
  • Wider Influence: Over 50% of all American consumers have made at least one purchase directly on a social platform. Even those who aren’t frequent social shoppers are being influenced by social content – around three-quarters of users say something they saw on social media influenced their buying decision in the past six months (including an astounding 90% of Gen Z consumers).
  • Growing Share of Ecommerce: Social commerce now accounts for roughly 7-8% of U.S. e-commerce sales, and that share is growing steadily. In specific product categories (beauty and fashion, for example), social-driven sales account for a significant share of total online sales.

Clearly, what was once “nice to have” is now a must-have channel. Social networks have invested heavily in shopping features, and consumers (especially Millennials, Gen Z, and even the upcoming Gen Alpha) are embracing the ability to buy seamlessly through the apps they already scroll every day.

Setting Up Shop on Social Platforms

Setting Up Shop on Social Platforms 1024x493 1

Selling directly on social media requires leveraging each platform’s built-in commerce tools. The good news is that the biggest apps have made it relatively straightforward for businesses to set up storefronts and integrate payments.

Below, we outline how to set up your social storefronts on four major platforms: Instagram (and Facebook), TikTok, and Pinterest. Each platform has its own quirks and opportunities, but the goal is the same: ensure that when followers see your content, they can buy in just a couple of taps.

Instagram & Facebook Shops

Instagram has long been a visual inspiration hub, and now it’s also a shopping destination. If you have an Instagram business account (and an associated Facebook Page), you can create a Shop that showcases your products directly on your profile. Here’s how to get started:

  • Catalog Integration:

First, connect a product catalog to your Facebook/Instagram account via Meta’s Commerce Manager. This catalog can be built by linking your e-commerce platform (e.g., syncing your Shopify or BigCommerce store) or by manually uploading product information.

The catalog includes images, descriptions, prices, and inventory for each product. Once approved, these items become your Instagram Shop listings.

  • Enabling the Shop:

Once your catalog is ready and your account meets eligibility requirements (e.g., adhering to commerce policies and having a U.S.-based business for now), you can enable the Shop tab on your Instagram profile.

This creates a storefront where users can browse your products without leaving the app. On Facebook, a Shop section will also appear on your page.

  • Product Tags:

With your shop in place, you can start tagging products in your posts, Stories, and Reels. When you create an Instagram post or reel featuring a product, tag the product from your catalog.

Viewers will see a small shopping bag icon or a product name; tapping it displays the item’s details and a “Buy” button. This way, a casual scroller who spots something they like in your photo or video can quickly tap and start the purchase.

  • Checkout Experience:

Until recently, Instagram offered in-app checkout for a truly seamless purchase (users could store their payment information with Instagram and complete the purchase right in the app). Update for 2026: Meta has phased out the native in-app checkout in Instagram and Facebook Shops for most merchants, shifting to an external checkout model.

What does this mean? Shoppers who tap “Buy” on an Instagram product are now usually redirected to the product page on your own website to complete payment, rather than paying inside Instagram.

While this adds one extra step (opening an in-app browser window for your site), it’s still a reasonably quick process. Tip: Make sure your website is mobile-optimized, and the product link leads directly to a ready-to-buy page (either the item already in the cart or an easy “Add to Cart” button). The smoother your site’s checkout, the more you’ll retain these social shoppers. Even without a fully native checkout, Instagram’s shopping features significantly reduce friction compared to manually finding your site.

  • Facebook Integration:

Because Instagram and Facebook are under the same Meta umbrella, your catalog and shop setup automatically extends to Facebook. Facebook Shops similarly allow you to showcase products on your page and in Facebook posts or ads.

A user browsing Facebook can click on a product and either purchase via your Facebook Shop (if eligible) or be taken to your website. Facebook also offers Marketplace and the option to use Messenger for inquiries. Still, for most retail brands, the unified Shop approach through Commerce Manager is the best way to manage everything in one place.

Why use Instagram/Facebook Shops?

You tap into the massive audience on these apps with visual storefronts, and you benefit from features such as saved payment information (Meta Pay) for some users, product discovery through the Explore tab and hashtags, and the ability for fans to share your shoppable posts. By 2026, more than one-third of U.S. Instagram users are expected to make purchases on the platform.

Even though the final checkout now redirects to websites, the key is that Instagram generates the intent and gets customers 90% of the way there. Don’t forget to promote your Instagram Shop: use Stories (“Swipe up to shop” or Link Stickers), make Reels that demo products with links, and consider Instagram ads that highlight your Shop’s products to targeted audiences.

TikTok Shop

TikTok is the new powerhouse in social commerce. With its entertaining short videos and algorithm-driven feed, TikTok excels at product discovery – users often stumble on things they didn’t even know they wanted. TikTok recognized this trend and launched TikTok Shop, a suite of features that enables businesses to sell directly on the platform. Between 2023 and 2025, TikTok Shop in the U.S. grew from a few thousand sellers to hundreds of thousands, as brands of all sizes joined.

To start selling on TikTok:

  • Sign Up as a TikTok Shop Seller:

TikTok Shop is available to business accounts that apply to join the program. You’ll need to provide your business information and, in some cases, documentation for verification.

Once approved, you gain access to the TikTok Shop Seller Center – a dashboard for managing your products, orders, and payments.

  • List Your Products:

Just like setting up an online store, you’ll add your product listings. You can manually input product details (photos, descriptions, price, stock) or integrate with e-commerce platforms.

TikTok has partnered with Shopify and others to enable direct product syncing, keeping your inventory up to date. As of 2026, TikTok Shop offers tens of millions of products across hundreds of categories – so ensure your product information and visuals stand out!

  • In-Feed Shopping Integration:

Once your products are in TikTok’s system, you can link them in your content. This is where TikTok truly shines. For example, you can tag products in your TikTok videos – a small pop-up or shopping cart icon will appear on the video, which viewers can tap to see the item details without leaving the video feed.

You can also showcase items in a dedicated Shop tab on your TikTok profile, which works like a storefront for browsing all your offerings. The goal is to make discovery-to-purchase as immediate as possible. If a viewer sees a “TikTok made me buy it” style video of your product and is intrigued, they can tap, learn more, and purchase it on the spot, all within the app.

  • Live Shopping:

TikTok is a pioneer in popularizing livestream shopping in Western markets. As a seller, you can host live streams where you demonstrate and discuss products, and viewers can purchase items in real time. During a TikTok Live session, you can pin product links on-screen; viewers can tap to buy without interrupting the stream.

This replicates the high-energy, instant gratification shopping experiences already wildly successful in Asian markets. (Fun fact: some brands have pulled in seven-figure sales in a single TikTok live session when a stream goes viral!). Even if you’re a smaller brand, live streams with a charismatic host and a time-limited offer can drive significant sales and engagement.

  • Checkout and Payment:

TikTok provides a native checkout experience. Users can pay within TikTok using stored payment methods (credit card, etc.), and TikTok processes the payment and order. From the customer perspective, it feels seamless – they never have to jump to a web browser or re-enter payment details if it’s saved.

For sellers, TikTok notifies you of the order in your Seller Center for fulfillment. TikTok Shop in the U.S. is still relatively new, but it’s growing incredibly fast (U.S. TikTok Shop sales more than doubled year-over-year in early 2025). Early adoption can give you an edge in reaching TikTok’s youthful, trend-setting user base.

TikTok’s algorithm can quickly amplify products. A single viral clip (e.g., a beauty tutorial or a kitchen-gadget demo) can generate thousands of orders if the product is available on TikTok Shop. Create engaging content that leverages trends, and pair it with Shop features to capture impulse buys. Also consider using TikTok’s Creator Marketplace or affiliate program to partner with influencers who can feature your products. TikTok allows approved creators to earn commissions on sales they drive through TikTok Shop, making it a win-win.

Pinterest Shopping

Pinterest might not dominate headlines like TikTok or Instagram. Still, it’s a dark horse in social commerce that deserves your attention – mainly if you sell products with strong visual appeal (home décor, fashion, DIY, food, etc.). Pinterest users primarily use the platform for planning and inspiration, curating their own shopping catalogs through Pins and boards.

In fact, more than half of Pinterest users say they consider it a shopping destination. Recognizing this, Pinterest has steadily rolled out features to make buying easier, blurring the line between discovering an idea and purchasing it.

To leverage Pinterest for social commerce:

  • Business Account & Catalog:

Switch to a Pinterest Business account if you haven’t already. Then set up your product catalog on Pinterest. Similar to Meta, you can connect your e-commerce inventory via a data feed or integrations (Pinterest offers plugins for Shopify, WooCommerce, etc., making it relatively simple to export all your product information to Pinterest as Product Pins).

Once your catalog is uploaded and approved, your product Pins will display up-to-date pricing, descriptions, and stock availability. They’ll also have a special tag (like a price tag icon) indicating they’re shoppable Pins.

  • Verified Merchant Program:

Apply to Pinterest’s Verified Merchant Program (VMP). Being a verified merchant gives your profile a badge (which boosts user trust) and access to enhanced shopping tools. It also potentially improves your distribution in Pinterest’s algorithms.

Pinterest wants to highlight credible sellers to its users, so earning verification can help your products appear more often, especially in the Shop tab of search results or on users’ home feeds.

  • Product Pins and Shopping Ads:

Once set up, your products can appear organically whenever Pinners search for related keywords or browse categories. For example, if you sell handmade ceramic mugs and someone searches for “kitchen coffee nook inspiration,” they might see one of your product Pins among the ideas. Users can click Pin to view a closer look, including your product details and the option to buy.

In most cases, clicking the Pin takes them directly to the checkout page for that specific product on your website. (Pinterest introduced direct checkout links that skip extra steps – so a user isn’t just taken to your homepage, but ideally straight to the item ready to purchase.) You can also promote your product Pins through Pinterest Ads to reach more of your target audience. Promoted Pins can include a call to action, such as “Add to Cart,” to nudge shoppers to complete their purchase.

  • Hosted Checkout (Limited but Growing):

Pinterest has been testing a Hosted Checkout feature that lets users complete the entire purchase without leaving Pinterest, similar to in-app checkout on other platforms. Currently, this is available for select U.S. merchants (primarily those using Shopify, as Pinterest’s pilot integration is with Shopify’s checkout system). If you’re eligible, a shopper who taps “Buy” on your Pin can enter their payment and shipping info in a Pinterest pop-up and place the order instantly. In contrast, the order details get passed to your Shopify for fulfillment.

This cuts out the extra step of opening a web browser, reducing drop-off. The program was initially limited, but Pinterest indicated plans to expand such features. By 2026, we can expect more merchants to have this capability as Pinterest refines the social shopping experience. Keep an eye on Pinterest’s updates – if hosted checkout becomes available to you, turning it on could boost your conversion rates on the platform.
  • Leverage Visual Search:

A unique aspect of Pinterest is its visual search tool (Pinterest Lens). Users can snap a photo of an item or upload an image to search for similar items. Ensure your product Pins include clear, high-quality pictures and relevant keywords so they can surface in those Lens results. Someone might take a picture of a jacket they saw in a store, search for it on Pinterest Lens, and find a similar-style Pin they can buy.

This is a more indirect form of social commerce, but it underscores the importance of being on Pinterest – the platform is often the bridge between inspiration and purchase.

Other Platforms and Emerging Channels

While Instagram, TikTok, Facebook, and Pinterest are the major players for social selling in 2025-2026, they aren’t the only ones exploring commerce:

  • YouTube: Primarily a video platform, YouTube has been experimenting with shopping features, especially given the rise of unboxing and review videos. Creators can now tag products in their videos or live streams (in partnership with merchants) so viewers can see and even purchase items shown, all while on YouTube. There’s also a “Merch Shelf” where creators can sell their merchandise directly under their videos. As YouTube continues to integrate with Shopify and other shopping tools, expect the line between watching a review and buying the product to blur.
  • Snapchat: Snapchat leverages augmented reality (AR) for commerce. Brands can create AR “try-on” filters (like seeing how a pair of sunglasses or a lipstick shade looks on your face) with a button to purchase the item. They’ve also introduced a feature called Snapchat Stores for select brands, and integration with Shopify for AR shopping ads. If your target demographic skews young and playful, Snapchat can be a niche but innovative commerce channel.
  • X (Twitter): Twitter (now X) has experimented with social commerce through features such as Product Drops and a Shop module on profiles, available to a limited set of businesses. Social shopping isn’t a primary focus of X yet, but the platform is being reinvented under new ownership, and there’s talk of it becoming an “everything app” including payments. Keep an eye out: by 2026, X may introduce new commerce features, such as in-tweet purchasing or expanded storefronts.
  • WhatsApp and Messaging Apps: In some countries, messaging apps have become hubs for commerce (for example, WeChat in China). In the U.S., Meta is integrating shopping into WhatsApp and Facebook Messenger, enabling users to browse a catalog and even place orders within a chat with a business. This could be powerful for small businesses that use messaging for customer interaction – imagine a customer inquiring about a product, and you can send them a direct “Buy now” link right in the chat. It streamlines the conversation-to-purchase flow.

Optimizing the Social Commerce Experience

Optimizing the Social Commerce Experience 1024x493 1

Setting up the ability to sell on social platforms is half the battle. To truly succeed and maximize revenue, you need to optimize the customer experience and build trust. Social media moves fast – if there’s friction in the buying process or doubt in customers’ minds, they’ll quickly abandon the purchase (or worse, lose trust in your brand).

Here are some strategies to optimize payments and the overall shopping experience on social media:

1. Leverage Influencer Partnerships for Trust and Reach

One way to accelerate your social commerce success is by partnering with influencers and content creators. Influencers can authentically showcase your products in a relatable way that resonates with their followers. This is powerful for two reasons: trust (people trust recommendations from their favorite creators) and reach (influencers can introduce your brand to thousands or millions of potential customers).

To use this in practice, consider setting up affiliate programs on social platforms. TikTok’s Creator Marketplace allows influencers to pick products to promote via TikTok Shop and earn commissions on each sale – if your products are listed on TikTok Shop, you can recruit creators to feature them. On Instagram, you might collaborate with influencers who can tag your products in their posts or use features like Instagram’s Branded Content (so that their post appears with a “paid partnership” and can include your shop link).

When followers see a real person vouching for your product and can buy it instantly, it dramatically shortens the customer journey from recommendation to sale. Tip: Choose influencers whose audience matches your target demographic, and give them creative freedom to present your product in an entertaining or informative way.

Authenticity is key – social media users can tell the difference between a stiff advertisement and a genuine endorsement. A well-done influencer partnership can create a ripple effect, where one viral post drives sales and also leads to many user-generated posts about your product (“I bought this from TikTok and it’s amazing!”), further amplifying your brand.

2. Host Live Shopping Events

As mentioned with TikTok Live, livestream shopping is an emerging trend that can create urgency and engagement. You can schedule a live shopping event on platforms that support it (TikTok is the leader here, but you could also do live product demos on Instagram Live or Facebook Live, even if you have to direct viewers to links since Instagram removed native Live shopping tags).

During a live event, interact with your audience – answer questions, show products up close, highlight how to use them, and offer a limited-time discount or bonus for viewers. The real-time interaction builds excitement and replicates the personal feel of an in-store experience. For example, a boutique clothing store might host a weekly “Live Try-On Session” in which a host models new arrivals, and viewers can purchase in real time.

Even without built-in checkout on a live (as is the case on Instagram now), you can verbally guide viewers: “See something you like? The link is in our bio to shop this item – grab it now, we have limited stock!” This multi-sensory experience (video, audio, chat) can significantly boost conversion rates compared to static images. Plus, live sessions often receive priority in algorithmic rankings and trigger notifications to followers, so they’re a great way to reach more eyes.

3. Ensure Payments Are Secure and Seamless

Security and ease of payment are critical. A significant number of users have expressed concerns about trust when making purchases on social media. Platforms are addressing this by building robust payment systems and buyer protections. As a seller, you should embrace the platform’s trusted payment options. For instance, TikTok and, formerly, Instagram Checkout handle sensitive payment information, so users feel secure (their credit card information is stored with a large platform, not a random website).

If your social shop redirects to your website, ensure your site is trustworthy: use HTTPS (secure socket layer encryption), display trust badges or accepted payment logos, and, if possible, offer quick payment methods like PayPal, Apple Pay, or Shop Pay that can fill in details quickly. The faster and more secure the checkout feels, the more likely a customer is to complete it. Also, highlight the platform’s buyer guarantees, if available. For example, some platforms have refund and customer support policies that can reassure buyers who are undecided. Tip: Keep the payment process as few steps as possible.

On any platform or your own site, avoid making a user click through too many pages or fill too many fields. Autofill, address lookup, and offering to save info for next time – these little conveniences prevent drop-offs at the final stage. Remember, social media shoppers often buy on impulse; if you make them stop and think (or worse, worry), you might lose the sale.

4. Streamline Fulfillment and Customer Support:

A sale isn’t complete until the product is in the customer’s hands and they’re happy with it. Social commerce can drive significant volume quickly, so be prepared on the fulfillment side. Ensure your inventory is accurately reflected across all platforms (overselling an out-of-stock item will lead to customer frustration). If you integrate your social shops with your central inventory system (many platforms support this), inventory will sync in real time, preventing that issue. Once orders come in, ship them promptly.

Today’s consumers, spoiled by Amazon Prime, expect fast shipping. Consider integrating with shipping apps or services that automatically update customers with tracking information. In fact, some social platforms provide integrated tracking updates – for example, TikTok Shop lets buyers see order status within the app, and sends notifications for shipping. Use those features to keep customers in the loop.

Additionally, be ready to handle inquiries that come via social channels: customers might comment on a post or DM you with questions about their order. Respond quickly and helpfully; a good customer service interaction on a social platform isn’t just about that one customer, but is often visible to others and can bolster (or harm) your reputation.

Tip: Make your return and refund policies transparent and fair. One barrier to social commerce adoption is fear of “What if it’s not what I expected? Can I return it?” If you clearly communicate (in your product descriptions or a link in your bio) that “Hassle-free returns within 30 days” or similar, customers will feel more at ease clicking that buy button in an app.

And if a return or issue does occur, handling it smoothly (perhaps through the platform’s resolution centers, when available) can turn what could be a negative experience into a positive word-of-mouth opportunity.

5. Use Analytics and Feedback

Lastly, continuously optimize by using the data and feedback these platforms provide. Most social commerce tools have some analytics – track which products get the most views or clicks on Instagram, which TikTok videos drove the most sales, or which Pins are saved frequently.

This can inform your content strategy (e.g., make more videos like the one that sold out your product) and inventory decisions (e.g., stock more of the items trending on social). Also, pay attention to comments and messages – they often contain valuable feedback about what customers want, any confusion they had in the buying process, or suggestions for new products.

The beauty of social media is that it’s a two-way street: you’re not just selling, you’re also listening and engaging. Use that to your advantage to refine your social commerce approach over time.

Conclusion

Social commerce in 2026 is shaping up to be the next big frontier in retail. What began as experimental “Buy” buttons has evolved into a whole ecosystem where shopping is seamlessly woven into social experiences. For younger, digitally savvy consumers, buying straight from an Instagram feed or during a TikTok binge isn’t a novelty anymore—it’s an expectation. Brands that adapt can turn everyday engagement into real revenue by meeting customers exactly where they already spend their time.

By integrating product listings and secure payments across platforms such as TikTok, Instagram, Facebook, and Pinterest, you remove friction between inspiration and purchase. A viral video or well-crafted post can drive not just followers, but sales, especially when the journey feels fun, simple, and trustworthy.

Lean into influencer partnerships, live demos, fast fulfillment, and smooth checkouts so customers feel confident swiping, tapping, and buying in the moment. As social and shopping continue to blur, every like, share, and comment becomes a potential storefront—so start building, testing creative content, and turning social buzz into bottom-line growth.

Frequently Asked Questions

How do I sell products directly on Instagram or Facebook?

You can sell directly by setting up a shop through Facebook Commerce Manager and connecting your product catalog. Once approved, you can tag products in posts and stories, and, in some regions, enable in-app checkout so customers can complete purchases without leaving the platform.

What is TikTok Shop, and who can use it?

TikTok Shop lets brands and creators sell products directly through videos and live streams. After registering as a seller and uploading your products, customers can purchase them directly within TikTok, with payments processed by the platform.

Are people actually buying products on social media?

Yes. Many shoppers, especially Gen Z and Millennials, now complete purchases directly on social platforms. In-app checkout and saved payment details make impulse buying fast and convenient.

How do payments work for social commerce orders?

When customers check out inside Instagram or TikTok, the platform processes the payment and later deposits your funds, minus fees, into your bank account. If you send shoppers to your own website, your usual payment processor handles the transaction

What are some best practices for selling successfully on social media?

Focus on engaging content that shows products in real use, not just ads. Keep your catalog updated, respond quickly to comments and questions, use live selling or Stories to create urgency, and ensure fast fulfillment and good customer service.