Contactless payment solutions from Host Merchant Services boosts business transactions.

Embedded Finance for SMBs: New Tools to Manage Cash Flow and Capital

Embedded finance is transforming how small- and mid-sized businesses manage finances. By weaving financial services into the software and platforms that companies already use, these solutions let owners pay bills, track income, and even borrow money without leaving their usual tools. Instead of logging into a separate bank or loan portal, entrepreneurs can manage invoices, expenses, payroll, and loans right from the apps they use to run their business.

This shift helps busy owners save time, reduce errors, and see their cash position in real time. In this blog, we’ll explain the advantages of embedded finance for SMBs and provide examples of the latest tools that are streamlining cash flow and funding. We focus primarily on new offerings in banking (like integrated bill pay dashboards), the platform economy (like Uber Eats lending), and business software (like payroll and accounting integrations) that are making it easier than ever for small businesses to get paid and secure capital through the platforms they already use.

Why Embedded Finance Matters for Small Businesses
Digital payment processing chip for Host Merchant Services logo, online payment solutions.

Small businesses often struggle with cash flow and juggling multiple financial tasks. Owners may have separate systems for banking, invoicing, payroll, accounting, and loans. This can mean logging into many websites, retyping data between programs, and hunting for financial information in spreadsheets. All these steps take up time and can delay getting paid or paying bills. For example, an owner might have to manually enter vendor bills into their accounting system and then pay them through a bank’s website on a different day. In the meantime, cash flow predictions are inaccurate, and deadlines may be missed.

Embedded finance tackles these pain points by integrating financial operations into business workflows. Instead of separate tools, imagine one dashboard that shows your bank balance, unpaid invoices, upcoming bills, and even loan offers, all in one place. When a platform embeds finance features, it can automatically sync data – such as linking accounting software to the business’s bank account – so information flows seamlessly.

As a result, SMBs gain a unified view of their finances and can perform tasks faster. For example, an invoice sent to a customer can trigger alerts for when it’s paid, or a recurring utility bill can be scheduled automatically without switching apps. This kind of automation reduces busywork and helps business owners focus on running and growing their company.

Several forces are driving this change. First, advances in technology (APIs, cloud computing, mobile apps) make it easier to embed payments and lending into different software. Second, SMB owners increasingly expect consumer-like convenience in their business tools – for instance, one-click payments and instant loan approvals.

Third, lenders and banks are more willing to partner with software companies to reach small businesses where they work. By leveraging data from sales, invoices or payroll, these solutions can underwrite loans based on actual cash flow rather than just credit scores. The combined effect is that finance is no longer an afterthought handled in spreadsheets and separate banking sites; it is becoming part of the everyday business platform.

Below, we look at concrete examples of how embedded finance is playing out in the market today, including banking innovations, marketplace partnerships, and integrations in payroll or accounting software.

Integrated Billing and Payments in Banking Platforms
Flexible payment processing solutions by Host Merchant Services for small businesses.

A new trend among banks and payment providers is to offer “all‑in‑one” cash management portals for business accounts. Instead of just a simple transaction list, these platforms bundle invoicing, bill payment, and expense tracking. One leading example is the recent Bill Pay for Business feature from a major bank. This tool is embedded into the bank’s online business banking platform, giving small business clients one central hub to manage payables and receivables.

With this type of platform, a business owner can create and send invoices to customers, and also pay vendors from the same interface. The system might automatically turn incoming vendor invoices (emailed or scanned) into bills that can be approved and paid later. It can sync with popular accounting software, so vendor and expense data flows into the general ledger without duplicate work. It also lets the user see pending and past payments in one place, providing a real-time view of cash flow.

An owner could schedule recurring bill payments (like monthly utilities or rent) on autopilot, set reminders for due dates, and even make partial payments when funds are low. Mobile-friendly dashboards allow managing finances on the go, with fraud alerts and secure login protecting transactions.

The benefits of such banking integrations are clear. SMBs save time by avoiding multiple logins or duplicate data entry. They reduce errors since the system keeps all records in sync. Automated reminders and notifications (for example, alerts if a payment is missed or a deposit hits the account) help prevent late fees or overdrafts. And having visibility into all accounts and bills lets owners plan better and avoid surprises.

Most small business owners consider cash flow and invoice management as major pain points. They want solutions that consolidate bills and payments. All-in-one cash flow tools built right into online banking answer that demand by giving them control and confidence to manage funds through a single secure platform.

Embedded Working Capital and Lending in Marketplace Apps

Beyond banks, digital marketplaces and gig economy platforms are now helping merchants access capital directly within their seller or manager apps. A notable example comes from the restaurant industry. Restaurants using a popular food-delivery and management app can now receive instant loan offers through the same interface they use to track orders and sales. This is done through a partnership with a fintech lender. The platform shows participating restaurants personalized financing offers that are tailored to each location’s actual revenue and cash flow patterns.

Here’s how it works for a typical restaurant owner. When they open the restaurant’s management dashboard on the app (used for tracking deliveries, sales trends, etc.), they see new financing offers labeled “capital for your business” or similar. These offers might specify an upfront cash amount and repayment terms that flex with the restaurant’s daily sales. The fintech partner, behind the scenes, underwrites each offer by analyzing the restaurant’s historical order data and financial performance, rather than relying on the business owner’s credit.

If the owner accepts an offer, the funds appear quickly (often in a day or two) and repayments are automatically deducted as a fixed percentage of future daily sales. This embedded approach is much faster and less paperwork than a traditional loan: the owner does not visit a bank or fill out complex forms. They literally get working capital at the push of a button in the Uber/Eats app.

This Uber Eats and Pipe partnership shows the power of embedded finance in marketplaces. Because the delivery platform already has rich data on each restaurant’s revenue and orders, it can use that information to extend credit smartly. Restaurants, which typically struggle to get bank loans or lines of credit on short notice, benefit from a source of funds that moves as quickly as their business.

Other marketplaces and point-of-sale providers are doing similar things. Some point‑of‑sale systems for retailers or restaurants now offer cash advances based on daily sales, directly through the POS software. E‑commerce platforms and payment processors also embed lending: online sellers can receive instant financing offers based on their sales history without leaving the seller dashboard. In all these cases, funding is integrated into the commerce experience.

The advantage of embedded loans and advances is efficiency. Business owners receive financing offers just by going about their day in the app. The approval process can be automated and frictionless, since the lender has continuous access to sales performance data. That means no waiting weeks for underwriting – often approval is instant or same-day. Tailored offers (amounts and terms) tend to fit the business better because they are based on real-time performance.

And since payments are often tied to a percentage of sales, repayment is more flexible: if business is slow one day, the deduction is small, easing cash flow pressure. For many small businesses, this immediate and data-driven access to working capital can be a game-changer, helping them cover payroll, stock up on supplies, or invest in marketing when needed.

Seamless Integration of Payroll and Payables
Affordable Host Merchant Services for seamless payment processing solutions.

Embedded finance is not limited to banks and market platforms. It also extends into business software, especially payroll and accounting systems. Managing payroll, employee benefits, and vendor bills often happens in separate silos. But new integrations are bringing these together in a single platform.

A leading payroll services provider now offers a built-in accounts payable solution powered by a well-known online bill-paying platform. Through this integration, a business can handle payroll and AP (accounts payable) workflows without switching systems.

When a company processes payroll through its HR software, it can also view outstanding vendor invoices, approve payments, and send payments (via check or electronic transfer) all within the same portal—vendor data, such as addresses and payment terms, syncs automatically. And just like with the banking example, the system provides dashboards for cash flow: showing how much is in the payroll account, how much is due for invoices, and how much is available overall.

Business owners can then make informed decisions about when to pay which expense. Because the payments software connects to a network of millions of businesses (vendors), it can simplify the process of sending funds to suppliers. For instance, if a supplier is already in the network, payment can be made electronically in seconds rather than mailing a check.

This kind of payroll-AP convergence saves significant administrative effort. SMBs no longer need to export payroll reports and then separately enter them into a bill payment system. Everything flows together – payroll deductions, tax payments, and bills – reducing the chance of missed entries or reconciliation issues.

The unified system can give real-time feedback: for example, if a payroll run or a major vendor payment would bring the account below a safe threshold, it might warn the user. By eliminating manual data entry, automating recurring fees, and centralizing vendor management, these platforms reduce paperwork and financial guesswork.

Other Emerging Embedded Finance Tools
Advanced payment technology integration for seamless merchant transaction solutions.

Several other innovative tools illustrate the reach of embedded finance in the SMB space:

Virtual Card Issuance and Smart Spend Management

Some payment providers now enable businesses to generate virtual credit cards directly within their management software. Instead of using corporate credit cards for every purchase, an owner can create single-use or one-time virtual card numbers for specific vendor payments.

These cards can be funded and tracked through the same software, giving more control over budgets and reducing fraud risk. The reconciliation is seamless because each virtual card’s transactions are automatically displayed in the business dashboard.

Cloud Accounting with Financing

Modern cloud accounting platforms often partner with fintech lenders to offer loans within the accounting app. If a small company uses online bookkeeping software to manage invoices and expenses, it might see offers for a cash advance or loan based on that data.

Since the accounting software already knows the customer’s sales history and outstanding invoices, it can propose funding packages that fit the business cycle. This saves the business owner from having to apply for financing with a bank separately.

E-commerce and Retail Finance

As mentioned, e-commerce sites, point-of-sale systems, and digital wallets for small businesses increasingly provide built-in financing. Sellers on an online marketplace might see a “quick cash advance” button on their seller account page. Or a retail shop using a modern POS system might receive push notifications about an offer for growth capital.

These embedded solutions often rely on the platform’s sales and payment data, making the lending process much more integrated and user-friendly than traditional loans.

Payroll Advances and Earned Wage Access

Some payroll platforms are embedding finance by letting employees access part of their earned wages before payday, directly through the employer’s payroll app.

While this primarily serves employees, it’s an example of how financial services are integrated into regular business tools (in this case HR software) to improve cash flow management on the employee side, which can in turn reduce turnover for SMBs.

In each of these cases, the common theme is that a business gets a financial service (payment, loan, card) without leaving the environment it already uses for operations. This “in-app” experience makes adoption easier and often more secure, since owners don’t have to trust unknown third-party sites with their data. It also lets providers offer more innovative, data-driven products.

If an accounting system knows a company’s invoice aging and cash on hand, it can automatically recommend an optimal payment schedule or highlight early payment discounts. Overall, these embedded tools create an interconnected financial ecosystem around the SMB, bringing the bank, the lenders, and the operational software closer together.

Benefits of Embedded Finance for SMBs

The rise of embedded finance offers several key advantages for SMBs:

  • Time Savings and Efficiency:

When invoice management, payments, and accounting records are all linked, business owners and their bookkeepers spend far less time on administrative tasks. Tasks such as data entry, transferring funds between accounts, or cross-checking records become largely automated.

Many embedded tools also automate routine workflows, such as automatically paying an approved bill on its due date, freeing owners from repetitive chores. This efficiency gain means SMB teams can focus more on strategy and sales rather than paperwork.

  • Better Cash Flow Visibility:

By unifying financial data, embedded finance platforms provide businesses with a real-time, 360° view of their cash flow. Owners can see on one screen what money is coming in (outstanding invoices, expected sales) and what is going out (bills, payroll, loan payments).

This holistic perspective makes it easier to forecast cash needs and avoid surprises. For example, seeing an upcoming cluster of large vendor payments might prompt a business to hold off on discretionary spending or to seek a short-term loan proactively.

  • Access to Faster Financing:

Traditional small business loans often require extensive paperwork and lengthy approval times. Embedded lending shortcuts this by using software to quickly analyze the company’s performance data.

As a result, businesses can access credit faster and with fewer requirements. Importantly, because the offers are based on the business’s actual revenue, lending terms can be more flexible and better aligned with the business’s cash cycles. For many small firms with volatile income, this means funding is truly an “on-demand” resource rather than a fixed bank line.

  • Reduced Error and Fraud Risk:

With payments and invoicing handled in an integrated system, the risk of manual errors (such as typos or duplicate payments) decreases significantly.

Many embedded tools also include alerts and multi-step verification for large payments. This added automation and security layer helps protect small businesses from fraud or costly mistakes, giving owners peace of mind.

  • Streamlined Workflows Across Departments:

Embedded finance often bridges departments that previously were separate – finance, operations, sales, etc. For example, if HR, payroll, and accounting are on the same platform, an employee’s tax withholdings flow directly into the company’s tax payments.

A sale captured in a point-of-sale system can automatically trigger updates to inventory and accounts receivable. These connected workflows break down silos within a small business, ensuring everyone from the owner to the accountant has up-to-date information.

  • Competitive Edge and Growth:

By using advanced financial tools, small businesses can operate more professionally like larger companies. Automation and data insights can allow an SMB to negotiate better with suppliers or manage inventory more tightly. Easy access to funding means they can scale up quickly when opportunities arise (for instance, stocking up on inventory ahead of a big sales season).

Embedded finance can help level the playing field, giving smaller players sophisticated financial capabilities without the need for large in-house finance teams.

Considerations and Looking Ahead

While embedded finance brings many benefits, there are important considerations for small business owners:

  • Data Security and Privacy:

Embedding financial services means sharing more data across platforms. SMBs should ensure that any software or app they use follows strong security and privacy practices.

Ideally, the integrations should use secure data connections (APIs) and the provider should comply with financial regulations (like data protection laws). Business owners must also manage user permissions carefully so that only trusted employees or advisors have access to financial tools.

  • Costs and Fees:

Some embedded services charge fees or take a cut of transactions. For example, invoice financing might come with a percentage fee. Business owners should understand these costs upfront.

Often, these fees are lower than alternative solutions (such as late payment penalties or high-interest small loans), but transparency is key. A good embedded platform will clearly disclose its pricing for bill payments, card issuance or loans.

  • Reliability of Technology:

Dependence on integrated software means SMBs need reliable internet and uptime. Owners should consider whether the platform has good customer support and backup systems. It helps if the chosen service has a track record of stability and is used by many other businesses.

  • Integration and Onboarding:

Connecting existing accounting, CRM or payroll software to new embedded finance tools can require setup work. Some platforms make this very easy with guided onboarding; others might need help from an IT or accounting professional.

Small businesses should plan for a learning curve as they transition to an integrated system, including any initial data imports.

  • Regulatory and Compliance Issues:

Depending on the financial features, there may be regulatory requirements. For example, offering lending or bill payment services requires compliance with financial rules.

Generally, the tech or banking providers handle this behind the scenes, but business owners should verify that any new finance tool is appropriately licensed or partnered with a regulated bank. This ensures the funds and transactions are protected under banking regulations.

Looking ahead, embedded finance for SMBs is expected to grow rapidly. New services continue to appear, often powered by API-first fintechs and open banking initiatives. We may see more analytics and forecasting tools built into these platforms (for example, innovative budgeting suggestions based on spending patterns).

On the funding side, expect more nuanced credit products – maybe revolving credit lines that automatically refresh when paid down, or peer-to-peer lending options inside business networks. Payment innovations, such as instant mobile wallets for businesses, could become the norm. Ultimately, small businesses stand to benefit as financial services become more tailored and accessible inside the software they already rely on.

Conclusion

Embedded finance is reshaping the small business financial landscape. By integrating billing, payments, expense management, and lending into core business apps, these tools remove friction from daily operations. Small business owners can handle bill payments, invoicing and payroll in one dashboard, and tap into working capital without jumping through hoops.

Examples such as a bank’s all-in-one bill payment platform, a food-delivery app’s built-in restaurant loans, and payroll software that automates vendor payments demonstrate how this trend is delivering value today. The result is simpler cash flow management, faster funding, and greater visibility for SMBs.

For business owners, the key takeaway is that more innovative financial management is becoming embedded and easier to access. Embracing these new tools can save time, improve decision-making, and unlock growth.

Frequently Asked Questions

  1. What is embedded finance for small businesses?

    Embedded finance integrates payments, lending, and financial tools directly into the software SMBs already use. This lets owners manage cash flow, pay bills, and access capital without switching platforms.

  2. How does embedded finance improve cash flow management?

    It unifies invoices, bills, banking data, and payments into one dashboard. This gives business owners real-time visibility into cash in and out, helping them plan and avoid surprises.

  3. What types of embedded finance tools are most common today?

    Standard tools include integrated bill pay, embedded lending in marketplace apps, payroll-AP integrations, virtual cards, and financing inside accounting or e-commerce platforms.

  4. Why is embedded lending beneficial for SMBs?

    Embedded lending uses real sales and performance data to offer instant, flexible financing. Approvals are faster, repayment adjusts with revenue, and owners skip lengthy traditional loan processes.

  5. What should SMBs consider before adopting embedded finance?

    Businesses should evaluate data security, fees, platform reliability, and ease of integration. Ensuring the provider is reputable and compliant helps protect financial data and transactions.
Online payment security illustration for Host Merchant Services.

Frictionless Online Checkout: Paze and the Race to Streamline Payments

Online shopping is booming, but so is cart abandonment – studies show roughly 7 in 10 consumers leave items in their cart, often due to complex checkout forms. Reducing this “checkout friction” is now a top priority for e-commerce businesses.

In response, banks and fintech firms are rolling out one-click checkout solutions. One high-profile example is Paze, a new bank-created digital wallet that lets customers pay with cards already on file at their bank, without typing card numbers at checkout. By tokenizing saved cards and integrating into payment platforms, Paze promises a faster, more secure way to pay.

This blog explains how Paze works, how partners like Nuvei and Fiserv are rolling it out, and how it stacks up against existing digital wallets like Apple Pay or PayPal.

The Checkout Friction Challenge

A smooth checkout experience is critical; even one extra field or page can push shoppers to abandon their purchase. Industry data suggest that nearly 71% of online shopping carts are abandoned in the U.S. Common checkout pain points include typing long card numbers on a tiny phone screen, registering a new account, or entering billing details – all of which add time and hassle.

These delays translate directly into lost sales for merchants. PayPal’s research found that speeding up guest checkout (through its Fastlane feature) cut the process from 2.5 minutes and 14 clicks to just 1 minute and four clicks, boosting conversion.

Cryptic address verification, CVV prompts, and complex forms are the opposite of the experience customers now expect. Many shoppers appreciate mobile wallets (Apple Pay, Google Pay, PayPal One Touch) that offer one-tap or one-click payment. But those solutions require customers to have set up that wallet (and often to have devices that support it). Paze aims to bring the convenience of one-click payment directly to consumers through the banks they already use – with no new app or account required.

Paze: A Bank-Powered Digital Wallet

Online checkout solutions by Host Merchant Services for businesses and shoppers.

Paze is essentially a “bank wallet” for online shopping. Participating banks and credit unions offer it, allowing customers to pay without revealing their actual card numbers to the merchant. Instead of entering card details or logging into a separate wallet account, a consumer can look for a “Pay with Paze” button at checkout and confirm the payment through their bank’s app or email link.

Paze collects all the consumer’s eligible debit and credit cards into a secure wallet within their bank’s app or website. At supported merchants, the buyer clicks the Paze button and authenticates (for example, by SMS code or mobile app login). The checkout then completes immediately using the customer’s card on file, without requiring any typing.

Paze’s bank wallet interface (example). Many major banks – including Capital One, Bank of America, PNC, Chase, U.S. Bank, Truist, and Wells Fargo – already support Paze. Their cardholders can tap the Paze icon at checkout to pay instantly with a saved card.

Because banks and credit unions provide Paze, customers do not need a new account or app. The payment option appears in the existing bank app, and all eligible cards from that bank are pre-loaded into the wallet. Paze’s official site lists seven central U.S. banks that support it, meaning millions of cards are already enrolled.

This seamless setup removes a significant hurdle where users don’t need to enter card numbers or create a new password for Paze.

Tokenization and Security in One Click

Tokenization

Paze uses tokenization, the same technology behind Apple Pay and Android Pay, to keep payments secure while speeding up checkout. When a customer pays with Paze, the bank generates a network token for the transaction instead of sending the actual 16-digit card number. Essentially, the merchant never sees or stores the real card number – they only get a single-use token.

The bank maps the token back to the customer’s actual card number after the sale. This both protects sensitive data and streamlines the flow. Because the card number is never typed in, there’s no chance of typos that could cause a failed payment or lost sale. Paze creates a short circuit in the payment flow: one tap authenticates the payment with the bank, which instantly authorizes the tokenized transaction.

Paze replaces each actual card number with a secure network token at checkout. The consumer’s card data is hidden and replaced with a masked token, preventing merchants from seeing the actual card details.

By design, Paze’s tokenization significantly reduces PCI scope for merchants and adds a layer of protection. Nuvei’s announcement explains that Paze “replaces sensitive card account numbers with single-use tokens and dynamic identifiers”, shielding the consumer’s real data. Industry analysts note that tokenization not only boosts security but also speeds up transactions by enabling fast routing through modern payment networks.

Paze’s wallet is “gateway-agnostic” and works with any processor that supports network tokens. This means merchants don’t pay any extra fee for Paze itself and may even benefit from lower interchange rates (since network-tokenized transactions can qualify for debit rates).

The overall user experience is essentially one-click checkout. As soon as you click “Pay with Paze” and confirm, the sale is authorized. There are no additional fields, no confirmation e-mail steps, and no new passwords – the whole process can take just a couple of seconds on a modern web browser.

Because everything is linked to the bank, customers see only a quick authentication (often via their mobile banking app) and then are back to the merchant’s order confirmation. This mirrors the speed of “account-on-file” checkouts used by major retailers, but Paze scales it across the open web.

Integration into Payments Platforms

Secure online payment processing with Host Merchant Services.

Paze’s value is realized when merchants make it available on their checkout pages. To achieve broad merchant coverage, Early Warning (Paze’s operator) has partnered with major payment platforms and processors.

In September 2025, Canadian payments company Nuvei announced it would integrate Paze into its U.S. e-commerce gateway. Nuvei processes transactions for tens of thousands of merchants, and adding Paze means any Nuvei merchant can offer Paze checkout with a single integration. According to Nuvei’s press release, merchants using Nuvei can now “access a fast, tokenized checkout” in which customers pay with cards already on file with their banks.

Phil Fayer, Nuvei’s CEO, explained that Paze’s familiar bank-based flow combined with Nuvei’s fraud tools will help “boost conversion” and “reduce abandonment.” The idea is that a merchant needs only one code update (through Nuvei) to turn on Paze, giving them a quick way to recover otherwise lost sales. Nuvei’s announcement emphasizes several advantages for merchants. By integrating Paze, merchants can lower cart abandonment rates by reducing checkout friction, while giving customers a seamless payment method linked directly to their bank. These benefits are powered by secure tokenization technology.

Around the same time, Fiserv (a large U.S. payments services firm) announced a collaboration to bring Paze to both banks and merchants. Fiserv will offer Paze to its bank clients and enable Fiserv merchants to accept Paze in checkout. The Fiserv press release emphasizes that Paze’s tokenized checkout provides “added security,” since card numbers are never shared with merchants.

Fiserv’s Deputy Head of Digital Payments, Matt Wilcox, said this gives clients “a future-forward approach to commerce” and a “convenient online checkout solution.” In effect, Fiserv is leveraging its network (which includes thousands of community banks and credit unions) to onboard Paze widely.

Smaller payment providers are also joining. For example, the fintech Payfinia announced in mid-2025 that it would help community banks and credit unions offer Paze. Star One Credit Union was named as the first Payfinia partner to launch Paze. Early Warning’s chief of partnerships noted that Payfinia’s framework gives smaller institutions “a more streamlined path” to offering Paze to their customers.

These distribution deals (Nuvei, Fiserv, Payfinia, and others) build a two-sided network: more banks add Paze, and more merchants accept it. Having big platforms on board is critical – industry experts say broad acceptance by both sides is needed to make any new wallet viable.

Competing with Other Wallets and Checkouts

Mobile payment with digital wallet and cash icons, e-commerce, online banking, financial transaction, Host Merchant Services.

How does Paze fit into the crowded “wallet” landscape? For consumers, the alternatives are familiar: PayPal (and Venmo), Apple Pay, Google Pay, Shop Pay, Amazon Pay, and other one-click solutions. Many consumers already use these options, and most large online stores already accept one or more of them.

In fact, Apple Pay dominates smartphone wallets – It controls about 92% of the U.S. mobile wallet market and processes roughly 14% of all online payments in 2024. Google Pay and Samsung Pay fill much of the remainder, and newer players like Shop Pay (by Shopify) have gained traction.

In that context, Paze is a late entrant. Early Warning is betting that a bank-backed wallet can gain trust and adoption by filling gaps. Paze’s significant advantage is that actual card numbers are never shared with merchants, addressing customer privacy concerns.

Many consumers worry about third-party apps and resale of their payment data, so the pitch is that a bank-branded wallet feels more secure. Indeed, a Paze survey found that 82% of Americans trust their bank’s security more than that of outside payment apps.

Banks created Paze to compete with PayPal, Apple Pay, and other payment services. The motivation is that when shoppers use PayPal or wallet apps, banks lose visibility and fee revenue. Paze keeps the payment flow within the bank’s ecosystem – the bank issues the token and still earns any interchange. It also means banks can capture data on the merchant and purchase category that they would otherwise forego.

However, skeptics warn that gaining real adoption will be an uphill battle. There are already many wallet options, and a consumer will only use Paze if they trust it will work everywhere they shop. One payments consultant points out that even if Paze catches on at specific merchants, those same merchants likely accept Apple Pay, Google Pay or Shop Pay already.

In other words, from the user’s perspective, most sites are not missing payment options – adding Paze may feel redundant unless it offers a compelling advantage. Apple Pay alone is supported by over 90% of U.S. retailers.

Paze can “overcome the lag” of late entry, though they acknowledge Zelle (Early Warning’s P2P app) did similarly come from behind to dominate bank-to-bank transfers.

Paze is playing in a “wallet war.” Its unique selling point is the bank relationship – customers are already logged in to their bank and authenticated with Face ID or a PIN so that payments can be instant. That trust could persuade some customers to pick Paze when it’s available. On the other hand, one-click convenience already exists in many forms. Whether Paze will win a meaningful share of wallet depends on how many major merchants adopt it and how quickly the banks market it.

Benefits for Merchants and Consumers

If Paze does gain traction, who stands to gain the most? Merchants benefit from higher conversion rates. Every extra step in a checkout is a drop-off point; eliminating fields and password prompts can win back sales. Because Paze reduces friction and errors (for instance, pre-filled address and card info), merchants should see fewer abandoned carts.

Merchants also save on fraud liability and compliance burden when tokens are used instead of raw card data. Smaller merchants (who often don’t have their own one-click system) get access to a bank-backed checkout with relatively little development effort.

For consumers, the main benefit is speed and convenience. For someone already banking with a participating bank, checkout is as simple as clicking a button and maybe approving it in the bank’s app. There is no need to fish out a wallet, dig up a card, or remember which provider to use. It also reduces typing mistakes as studies show a single address typo can scuttle a purchase, so pre-filled information means fewer errors.

And because the actual card number is never exposed, consumers get extra peace of mind – some surveys find many people worry about card skimmers or data breaches during checkout. With Paze, the bank itself handles the sensitive data.

Consumers also benefit from continuity. If they have multiple cards at one bank, they can load all of them into Paze and choose at checkout. If a card expires or is replaced, the bank can automatically update tokens (like existing account updater services), keeping the wallet current. Finally, Paze can work on any device via the web; it isn’t tied to mobile devices alone.

Challenges and Outlook

Despite the promise, Paze faces challenges. Getting merchant acceptance is critical as consumers won’t adopt Paze if it’s only accepted at a handful of niche stores. Early Warning’s strategy has been to rely on big processor partnerships (Nuvei, Fiserv, Worldpay, etc.) to reach merchants of all sizes.

The recent alliance with Worldpay (now part of FIS) is meant to open doors to Worldpay’s massive merchant base. Meanwhile, convincing all banks to join takes time. So far, all the founding bank owners of Early Warning support Paze, plus the new agreements via Fiserv and Payfinia are rapidly adding credit unions and community banks.

Some skeptics also point out that network effects are hard to reverse. Most consumers already have a default payment method – often a mobile wallet or a store’s one-click feature. Asking them to switch or add Paze requires marketing and incentives. To help, Early Warning is running merchant promotions (cashback deals and discounts) to encourage people to try Paze. Over time, they hope the convenience will speak for itself.

Another challenge is awareness. Consumers need to recognize the Paze logo at checkout and understand what it does.

Conclusion

Paze is a bank-centric answer to the one-click checkout puzzle. It’s a natural extension of banks’ existing digital offerings (like Zelle) into e-commerce. For companies looking to streamline payments, Paze offers an innovative option that leverages the card-on-file infrastructure already in place at banks.

If all parties – banks, processors, merchants, and shoppers – play along, it could indeed make online payments more frictionless. Time will tell whether Paze can capture users’ attention in a world already full of wallets.

Frequently Asked Questions

  1. What is Paze, and how does it work?

    Paze is a bank-powered digital wallet that uses the cards you already have with your bank. At checkout, shoppers click “Pay with Paze” and confirm through their bank, without typing card numbers or creating new accounts.

  2. Why is checkout friction such a problem for online stores?

    About 7 in 10 online carts are abandoned, often due to long forms, card entry, or extra steps. Faster, one-click options like Paze significantly reduce drop-offs and improve conversion rates.

  3. How does Paze keep payments secure?

    Paze uses tokenization, replacing your real card number with a secure, single-use token that merchants never see. This reduces fraud exposure while keeping checkout quick and seamless.

  4. How is Paze different from Apple Pay or PayPal?

    Unlike third-party wallets, Paze is offered directly by participating banks and requires no new app or setup. Consumers use the cards already stored with their bank for one-click checkout at any merchant that accepts Paze.

  5. Where can merchants and customers use Paze today?

    Paze is rolling out across major platforms like Nuvei, Fiserv, and others, enabling thousands of merchants to use it with minimal integration. Adoption is growing as more banks and payment processors support the wallet.

Contactless DEBIT CARD with Klarna logo, Euro symbol, and stars, promoting secure payment options.

Global Fintech Expansion: JPMorgan’s Digital Bank and Klarna’s EU Rollout

In recent years, global fintech competition has intensified as both traditional banks and upstart digital companies push into new markets. Central U.S. banking giant JPMorgan Chase is the latest example. It plans to launch its Chase-branded digital retail bank in Germany in the second quarter of 2026. This will be Chase’s second European retail market (after the U.K.) to push its digital-first model, which has already attracted millions of customers in London.

Meanwhile, Swedish fintech leader Klarna, known for buy now, pay later (BNPL), is rolling out a new Visa-powered debit-first payment card to consumers across over a dozen European countries. Klarna card, introduced in the U.S. in July 2025, lets shoppers pay upfront or switch to flexible BNPL installments at the tap of a card.

In both cases, local consumers will soon have new digital banking and payment options, and incumbent banks and fintech rivals must react as digital finance expands cross-border, giving consumers more choice – all while increasing competition for established providers.

JPMorgan’s Digital Bank Expansion in Europe

High-quality payment processing solutions for businesses by Host Merchant Services in Europe.

JPMorgan Chase has long been dominant in many financial segments, but retail banking in Europe is relatively new for the firm. In 2021, it launched Chase UK – a mobile banking app offering savings accounts, cash-back rewards, and budgeting tools – and won about 2.5 million UK customers within a couple of years. Building on that success, Chase is now setting its sights on Germany.

In November 2025, JPMorgan announced that it had moved roughly 120 employees into a new Berlin headquarters for its upcoming digital retail bank and plans to hire hundreds more. The bank will officially launch Chase in Germany in Q2 2026. Its first product will be a high-interest online savings account, reflecting the German preference for deposit products.

In interviews and filings, JPMorgan executives emphasize that Chase’s digital-only model – with no branch network to build – makes Europe’s largest economy an attractive “capital-light” expansion opportunity.

Germany presents both opportunities and challenges. On the one hand, it is the fourth-largest economy in the world and highly digitized. A survey found that around 71% of Germans had used a digital wallet in the past year, indicating a strong appetite for mobile banking and payments. U.S. banking executives note that German consumers are open to fintech solutions: domestic digital challengers such as N26, Revolut, and Trade Republic have already captured millions of users, suggesting ample room for competition.

On the other hand, Germany’s banking market is crowded. Incumbents like Deutsche Bank (around 19 million customers) and Commerzbank (over 10 million) still dominate through branches and longstanding customer relationships. In addition, Germany has hundreds of local savings and cooperative banks serving regional communities.

JPMorgan acknowledges that Chase will have to earn trust and differentiate itself: its CEO, Jamie Dimon, has publicly noted that Chase is “not yet so well known” in Germany. Local customers “expect” traditional attributes like reliability and security. The Chase management team says it will “enter the market with ambition, but also with deep respect for what German customers expect”.

JPMorgan’s existing footprint in Germany gives it some head start. The firm already employs nearly 1,000 people in the country across corporate banking, asset management, and private banking, and even after Brexit, it designated its Frankfurt unit as its European Union hub. It has built relationships with German firms and high-net-worth clients.

The new Berlin office, however, will focus on retail. Executives say it has room for about 400 employees once fully staffed. This expansion underscores CEO Dimon’s long-stated plan to “introduce Chase not only in the UK but also in Germany and other European countries.” The timing slipped (the launch was initially targeted for 2025), but the bank now seems committed to Q2 2026. JPMorgan aims to make Chase a top-five retail bank in Germany eventually—a bold goal, since even long-established local banks have struggled to reach that broad a consumer base.

Klarna’s Debit-First Card Rollout

Contactless payment credit cards for secure transactions at Host Merchant Services.

At the same time, Klarna Group, Sweden’s fintech pioneer, is deepening its European presence in payments. In July 2025, Klarna introduced its new Klarna Card in the United States – a Visa debit card with built-in BNPL (“pay later”) functionality. The U.S. launch was deemed a success, with roughly 685,000 customers signing up in the first few months. Building on this momentum, Klarna announced in September 2025 that it would roll out the card across the European Union. By November 2025, the expansion had grown to “15 new European markets”.

What Is the Klarna Card?

It is a debit-first payment card: by default, it uses the user’s own funds in a Klarna balance account (no overdraft or credit line) when paying. But the twist is that within Klarna’s app, a shopper can toggle the transaction to a BNPL option if desired – for example, “Pay in 3” installments or deferred pay-later plans. In other words, one plastic card (in digital or physical form) can act like a debit card or a credit card/BNPL card, depending on the customer’s choice. Visa’s new “Flexible Credential” technology powers this: it allows multiple payment credentials to be linked to one card.

In Europe today, Klarna’s card is already available in many countries. Specifically, it is rolling out in Austria, Belgium, Finland, France, Ireland, Italy, the Netherlands, Portugal, Spain, and Sweden. These were the initial launch markets as of late 2025. Within a few months, it has also expanded to the U.K., Denmark, Germany, Norway, and Poland. In total, Klarna now covers major markets across Western, Northern, and Southern Europe – essentially most countries where Visa operates and where Klarna has a significant user base. The company plans to add even more countries (including others in Scandinavia and Eastern Europe) in the near future.

For everyday European shoppers, Klarna’s new card promises several perks. It eliminates foreign transaction fees (so online or travel spending abroad is cheaper). It comes with a free “Klarna Balance” account to hold cash, budgets, and track spending. And critically, it gives consumers the freedom to split or delay payments – a key appeal of BNPL – but only if they want to. Many regulators had warned that easy credit could trap users. Still, Klarna’s card defaults to debit and only applies a credit check if a user expressly converts a purchase into longer-term credit.

In Europe – where debit cards have very high usage (often far above credit cards) – Klarna is effectively tapping into the existing habit of paying by debit. That means consumers can continue using their own money for most purchases but have BNPL as a built-in option for flexibility.

Strengthening Klarna’s Position

Low-cost payment solutions for small business credit card processing.

This card rollout is part of Klarna’s strategy to become a “one-stop” digital bank and payments network. Already Europe’s largest BNPL provider, Klarna is leveraging its 100+ million active users worldwide to extend into deposit accounts and everyday spending tools. Its card business (now powered by a deep partnership with Marqeta, a card-issuing platform) now accounts for roughly 10% of Klarna’s total payment volume.

In just a year, Klarna has partnered with major ecosystems. It has brought BNPL options into JPMorgan Chase’s merchant network, integrated with eBay and DoorDash, and even bundled mobile phone plans with its payment services. The European card expansion is another step toward this “super app” vision – combining loyalty, budgeting, and credit payments in one place. For fintech watchers, Klarna’s moves highlight how BNPL firms are encroaching on traditional banking turf.

BNPL companies like Klarna, Affirm, and Afterpay are increasingly offering services (debit cards, deposit accounts, debit networks) that blur the line with banks. By integrating credit and debit on a single card, Klarna challenges the orthodox distinction between “credit” and “debit” at the checkout.

Benefits for Consumers

What do these expansions mean for everyday consumers in Germany and Europe? In general, more choice and innovation tend to drive better deals and features. German savers, for example, may soon see a competitively high interest rate on Chase’s online savings accounts – competing with local offerings. JPMorgan has stated that it expects to lower consumer rates or enhance rewards to gain market share.

The arrival of Chase could force incumbent banks (like Deutsche Bank and Commerzbank) to accelerate their digital upgrades and improve pricing to keep customers. For tech-savvy users mainly, having a global player like Chase could introduce new features and robust mobile banking tools (for instance, Chase’s U.K. app already includes no-fee currency conversion and automatic round-ups). The competition could also nudge German banks to reduce branch fees or boost their own apps and online services.

Likewise, Klarna’s card gives shoppers another flexible payment method. Europeans already use cards heavily, and Klarna estimates its card will simplify how people pay for both daily essentials and larger purchases. Consumers who frequently shop online (or physically) can decide on the spot whether to deplete their account balance or break the bill into installments – all within a familiar app interface.

From a budgeting perspective, Klarna claims its customers can track spending, set budgets, and receive in-app reminders. The interest-free installment options mean buyers who would otherwise put items on a regular credit card (often with interest) can have more transparent, usually cheaper financing. Also, since Klarna’s card has no foreign exchange fees, it may be attractive for cross-border shopping or travel.

Of course, consumer advocates will watch for risks. BNPL critics point out that easy installment credit can tempt overspending, especially among younger shoppers. Regulators in Europe have been increasingly concerned about BNPL (some countries now require affordability checks). But Klarna emphasizes that the majority of users manage responsibly. Indeed, recent data shows BNPL delinquency rates remaining low, suggesting that most consumers don’t spiral into debt with these services.

Chase’s launch in Germany might raise data-privacy questions or cultural skepticism: German customers often prize privacy and may be wary of a big American bank’s reach. Nevertheless, Chase’s executives have been at pains to highlight the bank’s long track record and “trustworthiness”. Consumers can choose whichever service (or both) meets their needs: some will stick with local banks or cards, while others will test Chase or Klarna for convenience.

Implications for Competitors and the Market

Affordable merchant processing solutions for your business.

For incumbent banks and local fintechs, these expansions represent clear competition. In Germany, for example, consumers now see the entrance of a global retail bank brand—one that can cross-subsidize promotions from its large balance sheet. Deutsche Bank, Commerzbank, and Sparkassen/Volksbanken (savings banks) may face pressure on deposits and loan spreads. German banks will need to accelerate digital transformation and possibly cut costs to stay competitive.

Deutsche Bank has already been revamping its mobile app and exploring fintech partnerships, while international banks like Spain’s BBVA have also launched mobile banking in Germany this year. Smaller fintech startups in Europe could feel a “keep up or partner” effect: if consumer demand for integrated payment products rises, startups may need to join alliances (e.g., with Visa/Mastercard or open banking platforms) or risk losing ground. Some traditional institutions may respond by creating their own BNPL or app-based products; for instance, many card issuers now offer their own installment plans, and some banks have launched neo-banking arms.

Klarna’s card specifically intensifies rivalry in the payments space. It pits the fintech against not only other BNPL firms (like Afterpay and Affirm) but also directly against banks and credit card networks. When a shopper uses Klarna to pay, the transaction goes through Visa, but funds are settled by Klarna’s banking partner, not the local issuer. This means that banks lose out on interchange fees and interest, and card issuers lose time spent on usage.

Banks may counter by offering more compelling features (cashback, credit lines, instant loans) in their own cards. Some banks might even partner with BNPL players. In fact, JPMorgan announced last year a partnership with Klarna to offer BNPL to its business clients – illustrating that collaboration and competition can go hand in hand.

Regulators and industry groups are also paying attention. Banks everywhere have been lobbying to shape open banking and data-sharing rules (the JPMorgan “data access fees” saga in the U.S. is a prominent example). In Europe, regulators may scrutinize any wholesale dominance or consumer risk. But so far, the trend is towards enabling cross-border fintech under directives such as PSD2 and the Digital Finance Package, rather than blocking it.

From a macro perspective, the globalization of fintech means national players need to adopt more global standards (cloud infrastructure, cybersecurity, anti-money laundering) to keep pace. We’ve already seen that even a giant like JPMorgan faces regulatory hurdles: as it expanded digitally in Germany, its German unit was fined €45 million by BaFin for past compliance failures, reminding foreign entrants that local rules still apply.

The Global Fintech Landscape

The Global Fintech Landscape

These specific cases – Chase in Germany and Klarna in Europe – are part of a broader trend of globalization in financial services. Digital banking platforms and payment networks are inherently cross-border: a mobile app or cloud-based ledger can serve users anywhere at relatively low marginal cost. In the past, banks often stayed in domestic markets or entered markets with full branches.

Now they can expand digitally; the U.K. and Germany launches are milestones, but JPMorgan has signaled ambitions for even more European markets. Similarly, fintech startups that begin in one country quickly eye international growth. Klarna started in the Nordics, expanded across Europe, then to the U.S., and now is turning the card back to Europe, with thousands of merchants on board.

For global competition, this means national boundaries are less of a moat. German consumers might compare Chase to native banks, or a French Klarna user might use the same app as an Italian. Payment clearing is global (Visa/Mastercard, SWIFT, SEPA), and money moves quickly online. In practice, some localization still matters: language, local regulations (BaFin in Germany, ECB oversight), and consumer habits can influence uptake.

But leading fintech players are investing heavily to customize their offerings. JPMorgan’s German head, Daniel Llano, has talked up aggressive marketing and local partnerships to gain trust. Klarna’s materials note that its card will bring back the “choice” between debit and credit that checkout aisles once offered, tapping into universal consumer sentiments even as it tweaks features per country.

Competition is intensifying worldwide. A traditional ripple effect is at work: each expansion prompts responses across multiple regions. For example, when a central U.S. bank enters Europe, European banks may seek to improve their fintech capabilities to better compete at home and abroad. As fintechs like Klarna grow, global incumbents consider how to match their agility or acquire similar startups.

Even beyond Chase and Klarna, other global moves abound: U.S. neobank Chime signaled expansion to Mexico, Chinese digital banks are seeking licenses in Southeast Asia, and cross-border fintech partnerships (Visa, Mastercard, PayPal collaborations) are accelerating. In sum, the landscape is becoming more interconnected. For consumers, this is largely good news: more innovation, better pricing, and cutting-edge payment options. For competitors, it means a relentless need to innovate, partner, or pivot.

Conclusion

The coming year will likely see European financial markets change in notable ways. German consumers will soon be asked whether they want to open an account with Chase’s online bank—a significant shift from a market long dominated by local brands. At the same time, everyday shoppers across Europe will have a new card option that blurs the line between debit and buy now, pay later.

These developments illustrate how quickly the fintech sector is globalizing. Both big banks and fintech startups are following their customers – and leveraging technology to cross borders without heavy branch networks.

Local banks may need to offer higher savings rates or partner with fintechs to stay relevant; fintechs will need to navigate new regulatory regimes and fierce local loyalties. Regulators and policymakers will have to ensure these globalized fintech models do not undermine financial stability or consumer protection.

For investors and industry watchers, the message is clear: fintech expansion is a global arms race. Chase’s Berlin office and Klarna’s new card rollout are not isolated news, but signals of a broader transformation. The frontier of banking and payments is increasingly borderless, and competition is global, which ultimately means both more innovation and more complexity for all participants.

Frequently Asked Questions

  1. Why is JPMorgan Chase launching its digital bank in Germany?

    JPMorgan sees Germany as Europe’s largest economy and a promising digital banking market. Its branch-free, digital-only Chase model lets it expand cost-effectively while appealing to tech-savvy savers seeking high-interest online accounts.

  2. What makes Klarna’s new debit card different from regular cards?

    Klarna’s Visa-powered card combines debit and “buy-now-pay-later” (BNPL) options. Shoppers can pay directly from their balance or switch to installments within the Klarna app, giving flexible control over each purchase.

  3. How will these expansions affect European consumers?

    Consumers gain more choice, better rates, and innovative digital features. Chase could push German banks to offer higher savings yields, while Klarna’s card offers flexible payments and zero foreign transaction fees across Europe.

  4. What challenges do Chase and Klarna face in their new markets?

    Chase must win trust in a crowded, relationship-driven German market dominated by local banks. Klarna faces tighter BNPL regulation and must ensure users manage installment credit responsibly while maintaining profitability.

  5. What do these moves mean for the global fintech industry?

    They signal a new phase of cross-border competition, in which digital banks and fintechs expand internationally without branches. Global players like Chase and Klarna are redefining how consumers save, spend, and borrow, driving both innovation and disruption in finance.

Contactless payment solutions for small businesses by Host Merchant Services.

Lower Merchant Fees on the Way? Your Credit Card Rewards Might Pay the Price

Visa and Mastercard’s proposed $38 billion settlement with U.S. merchants could reshape how Americans pay, and how much they earn back when they do. The agreement aims to end a decades-long swipe-fee settlement battle over interchange, or “swipe,” fees, the small but powerful charges merchants pay each time a customer uses a credit card. If approved, it would slightly lower those fees and give businesses more flexibility to pass costs to consumers or reject high-fee premium cards.

Some see it as overdue relief for retailers burdened by card processing costs. While others argue that the change is primarily cosmetic, offering only marginal savings while preserving the networks’ control over the payment system. For consumers, the real impact may come elsewhere: in the gradual erosion of the rich rewards programs, points, miles, and cash-back offers that have long been funded by those same fees.

Key Takeaways
  • Visa and Mastercard have offered to lower merchant interchange fees by 0.1% over five years, aiming to settle a decades-long lawsuit over alleged price-fixing practices.
  • With lower interchange fees, credit card rewards programs may shrink, as these perks are primarily funded by the fees merchants pay to card networks.
  • The proposal would allow retailers to add surcharges for credit card payments or decline premium cards that carry higher fees, giving businesses more control over payment costs.
  • Retail groups argue the reduction is too small to make a real difference, calling the proposal inadequate and urging courts or, potentially, Congress to impose more substantial reforms.

The $38 Billion Swipe-Fee Settlement Deal That Could Reshape Credit Card Rewards

Credit card with a trophy symbolizing rewards for top payment processing solutions by Host Merchant Services.

Visa and Mastercard’s latest truce with U.S. merchants is being sold as a win for Main Street. The fine print suggests something more complicated: a slow, subtle squeeze on the rich credit card rewards that American consumers have come to treat as a birthright.

The card networks and a group of major banks have agreed to a revised settlement valued at roughly $38 billion to resolve a long-running antitrust battle over “swipe fees,” the charges merchants pay each time a customer uses a credit card. The deal, announced November 10, 2025, would trim some of those fees, cap others, and expand merchants’ ability to steer customers toward cheaper payment options and to add surcharges on card transactions. It is designed to replace an earlier, smaller settlement that a federal judge rejected as inadequate. It still requires court approval, and several merchant groups are already lining up against it.
At the heart of the dispute is interchange, the small percentage fee embedded in every card payment that has quietly become a major profit engine for banks and a major cost line for retailers. In the United States, those fees typically run around 2% to 2.5% on credit card transactions, higher than in most developed markets. For years, merchants have argued that Visa and Mastercard, working with large card-issuing banks, used their market power to keep those fees elevated, forcing businesses to subsidize the lucrative travel points, cash-back offers, and premium perks that cardholders enjoy.

The latest agreement nudges that system rather than upending it. Under its terms, average credit card interchange rates would fall modestly for several years, with a slight reduction — about one-tenth of a percentage point — locked in for five years. Fees on basic consumer credit cards would be capped at 1.25% for eight years. Merchants would gain more flexibility to choose which card categories they accept, softening long-standing rules that effectively compelled them to honor all cards bearing a network’s logo if they accepted any at all. They would also gain clearer rights to impose surcharges on credit transactions, within defined limits and subject to state law and disclosure requirements.

Neither Visa nor Mastercard admits wrongdoing under the deal. Both portray the settlement as a way to bring a decades-long legal saga to a close while preserving the essential structure of the U.S. payments system. Their argument is straightforward: a secure and convenient card network costs money to run, including interchange, fraud protection, credit risk, and customer rewards; any calibrated relief to merchants should not threaten those benefits.

Merchant advocates are unconvinced. For them, the headline numbers mask a familiar pattern: modest, temporary concessions that leave the fundamental economics largely intact.

The core of their criticism is that the fee relief is small relative to the total volume of card transactions. A reduction of 0.1 percentage point on a fee of more than 2% matters in aggregate dollar terms, but many individual businesses will experience it as little more than a rounding adjustment in their cost structure. The most significant caps and constraints also expire after several years, raising concerns that fees could drift higher once the settlement period ends.
There is also skepticism about how much practical freedom merchants will have to steer customers. While the agreement envisions the ability to differentiate among card types, such as standard consumer cards versus high-fee premium rewards products, merchants know the reality at the checkout. Telling a customer that their preferred travel card is not welcome or will cost extra is risky for anyone worried about losing a sale or damaging goodwill. For smaller businesses, already wrestling with tight margins and stiff competition, the theoretical right to refuse expensive cards may be difficult to exercise.

visa

What makes this settlement different from previous skirmishes is not the size of the fee cut but what it signals. It represents a formal acknowledgment, in a high-profile legal resolution, that the model that funds U.S. credit card rewards is under scrutiny. For nearly two decades, the engine has been simple: merchants pay relatively high swipe fees; those proceeds help support generous points, miles, and cash-back; card issuers compete to outbid each other on rewards; and consumers gravitate toward the flashiest offers, often unaware that the cost is baked into retail prices.

If that revenue engine is nudged even slightly, someone has to absorb the strain. In theory, the options are straightforward: card networks and issuing banks could accept lower margins; merchants could keep the savings; or rewards programs could quietly become less generous over time. In practice, the outcome is likely to be a blend, with the cost most visible at the edges of consumer benefits.

The U.S. has seen this pattern play out abroad. When regulators in Europe and Australia imposed tougher caps on interchange, the richest reward programs were scaled back, annual fees adjusted, and “free” perks became less plentiful. In the United States, post-crisis limits on debit card interchange coincided with the decline of many debit rewards programs. The current settlement is milder and market-driven rather than regulatory, but it points in the same general direction: pressure on the subsidy that makes 2%, 3%, 5x, and 10x rewards sustainable at scale.

Rather than an abrupt collapse of points and miles, industry analysts expect an incremental reshaping that is easy to miss in the headlines but noticeable over time. Issuers facing slightly thinner economics on each swipe may respond by trimming earn rates on new products, tightening caps on bonus categories, making redemption options less generous, or shifting more value behind annual-fee paywalls. Large sign-up bonuses, which have been an expensive marketing weapon in the battle for affluent customers, could become less extravagant. Perks such as lounge access, statement credits, and elite status tie-ins may be narrowed or more heavily restricted.

At the same time, the settlement’s provisions on surcharging and card acceptance could alter the checkout experience. More merchants, especially in sectors with slim margins, may experiment with explicit “credit card fees” or cash discounts, making the cost of card acceptance more visible to consumers. Some may highlight preferred payment methods, cheaper debit networks, bank transfers, or lower-fee card types, as they look to reclaim a slice of economics long ceded to the card industry. While large chains are likely to move cautiously to avoid customer backlash, they also have the leverage and data to test new structures at scale quietly.

mastercard

For cardholders, the prospect of paying more out of pocket at the register while earning slightly less in rewards is the uncomfortable flip side of what is being framed as a merchant victory. The settlement does not require merchants to pass any savings through to consumers via lower prices, and many are likely to view the relief as long-awaited compensation for years of elevated costs. In fiercely competitive categories, some of that benefit may filter into pricing or investment, but isolating its effect will be challenging.

Whether the deal ultimately takes effect in its current form is far from assured. It must clear judicial review from the same federal judge who previously threw out a smaller settlement for not going far enough. Early statements from merchant coalitions suggest they will argue that the revised package still falls short of addressing the dominant networks’ underlying market power. Parallel political efforts, including proposals to require more competition in routing credit transactions over different networks, remain in play and could impose more profound structural changes than any negotiated settlement.

What the agreement does, however, is move the debate into a new phase. The question is no longer whether swipe fees are legally and economically contested; they clearly are, but who will bear the cost of any adjustment? Networks and banks will fight to preserve profitability. Merchants will push for further concessions and more routing choices. In the middle sit consumers, who have grown used to being rewarded for every tap and swipe and may only gradually discover that those benefits are neither free nor guaranteed.

For now, the golden age of U.S. credit card rewards is not over. Issuers still rely on them to attract and retain customers; airlines and hotels still depend heavily on selling miles and points to banks; and consumers still respond to rich offers. But the settlement marks a warning shot: as legal and commercial pressure builds to ease the burden on merchants, the lavish incentives that helped fuel the shift to plastic and digital payments are increasingly part of the bargaining. Over the coming years, the price of lower merchant fees may be paid, quietly and incrementally, in devalued points, higher card fees, more surcharges, and fewer frictionless freebies at the top of the wallet.

Conclusion

The Visa-Mastercard settlement is framed as a win for merchants. In dollars, it offers measured relief. In design, it’s something more: a crack in the system that channels huge swipe-fee revenues into ever-richer rewards. If that crack widens, through more rigid rules, bolder merchants, or future court decisions, the golden age of effortlessly generous credit card rewards will feel the strain.

For now, your points aren’t disappearing. But for the first time in a long time, they’re no longer untouchable. They’re on the negotiating table, and everyone from big retailers to big banks is reaching for a piece.

Fast and reliable Host Merchant Services payment processing solutions for your business.

Stripe’s Tempo: The “Payments-First” Blockchain for Stablecoins

Stablecoins now handle trillions in annual transactions, but the blockchains they run on weren’t built for everyday payments. Most existing networks prioritize trading and general-purpose smart contracts, leaving a gap for systems that can manage fast, low-cost, and compliant money movement.

To address this, Tempo by Stripe-Paradigm is a new “payments-first” blockchain purpose-built for stablecoin transactions. Designed to match enterprise-grade scale, Tempo aims to bring the performance of Stripe’s global payment systems to the blockchain world.
Key Takeaways
  • Tempo is optimized for routine stablecoin transfers and business transactions, removing unnecessary complexity from trading-focused chains.
  • The network targets 100,000+ transactions per second with sub-second finality, supporting real-time global payments.
  • Users can pay transaction costs directly in stablecoins (such as USDC), providing transparent, stable pricing rather than volatile gas fees.
  • Features such as batch transfers, memo fields, and compliance tools (e.g., KYC and sanctions lists) cater to banks, fintechs, and large businesses.
  • Built on Paradigm’s Reth client, Tempo supports Ethereum tooling and smart contracts, making it easy for developers to adopt and integrate.

Tempo by Stripe-Paradigm: A Blockchain Purpose-Built for Stablecoin Payments

Secure blockchain payment solutions for businesses | Host Merchant Services.

Image source

The rise of stablecoins has created a strong demand for faster, more scalable payment rails. As of mid-2025, stablecoins already accounted for roughly 30% of all on-chain crypto transactions, which is over $4 trillion in annual volume (an 83% jump from the previous year). Yet most existing blockchains were built for trading and general-purpose use, not routine money transfers. Stripe (the payments giant) and crypto VC Paradigm jointly announced Tempo, a new layer-1 blockchain explicitly designed for high-volume stablecoin payments to address this gap.

This “payments-first” network will enable businesses to move money on-chain with enterprise-grade speed and cost. Stripe’s CEO, Patrick Collison, noted that conventional chains can’t easily support such use cases. For example, Bitcoin handles ~5 transactions per second (TPS) and Ethereum ~20 TPS, whereas Stripe’s own systems peak at over 10,000 TPS.

Stripe sees Tempo as the solution—a blockchain tailored to real-world financial flows rather than crypto trading.

Stripe has already been building out stablecoin infrastructure. In May 2025, it launched Stablecoin Financial Accounts in 101 countries, powered by Bridge (a stablecoin orchestration platform Stripe acquired earlier that year). This lets businesses hold USD-pegged stablecoins and transact in traditional fiat rails globally. Even so, Stripe executives found that certain fundamental features were missing from existing networks.

As Collison explained, fees must be meaningful to users, denominated in a familiar fiat currency, but most blockchains charge gas in their native token. He also pointed out that features like batch transfers are far more critical for payments than for trading.

These insights – and Stripe’s experience handling 10,000+ TPS in peak loads – motivated Stripe and Paradigm to incubate a dedicated new blockchain. Paradigm co-founder Matt Huang wrote that “much of the existing crypto infrastructure is focused on trading,” and Tempo will be optimized for payments.

Tempo is structured as an independent startup with its own engineering team. It is an Ethereum-compatible (EVM) layer-1 built on Paradigm’s high-performance Ethereum client (“Reth”), so developers can use familiar Ethereum tools (Solidity, wallets, etc.). Tempo’s architecture isolates routine money transfers from more complex smart-contract traffic. A “dedicated payments lane” ensures that simple transactions don’t get bogged down by general-purpose activity.

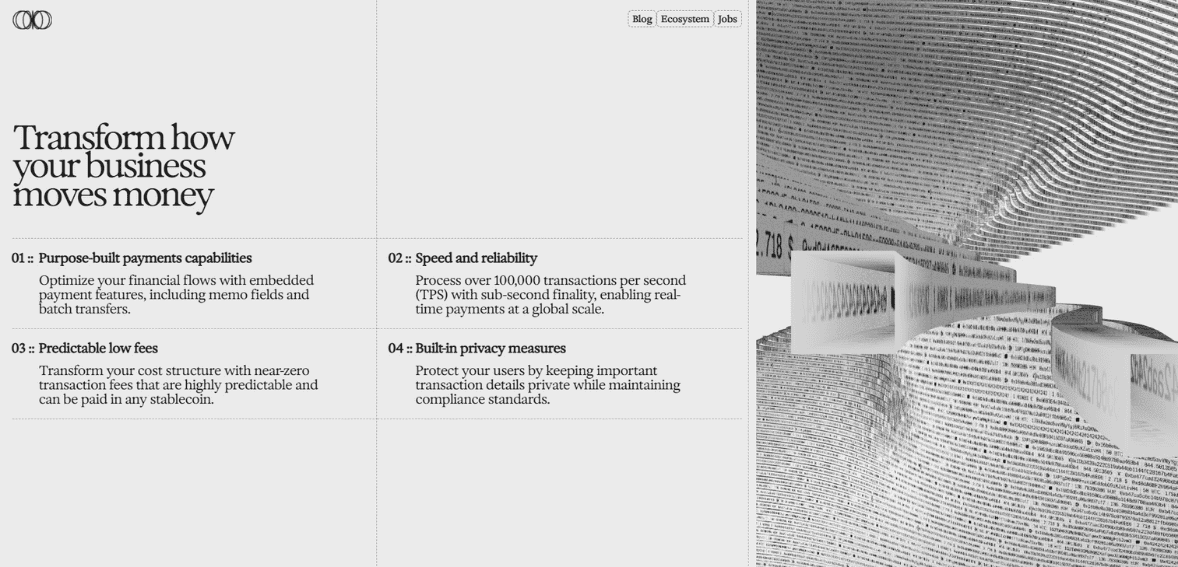
Stripe and Paradigm claim that Tempo can achieve well over 100,000 TPS with sub-second finality, an order of magnitude above what any current blockchain offers. Tempo aims to deliver the latency and throughput demanded by global commerce by focusing on just the operations needed for payments.

Tempo by Stripe-Paradigm Features

Seamless payment processing solutions for business transactions and merchant services.
  • High throughput:

Architected for >100,000 transactions per second with near-instant final settlement. This headroom is meant to accommodate demand peaks (remember Stripe’s ~10k TPS) and keep delays negligible.

  • Low, predictable fees:

Transaction fees are kept near-zero and can be paid in stablecoins rather than a volatile native token. Businesses could pay gas in USD-pegged coins (e.g. USDC) so their costs are transparent and stable, unlike on most blockchains.

  • Dedicated payments lane:

Tempo allocates a portion of each block just for routine transfers. By separating everyday payments from complex smart contracts, the chain avoids congestion and keeps payment processing smooth.

  • Stablecoin interoperability:

The network is stablecoin-neutral. It allows any issuer to use any stablecoin for transfers or fees. Tempo even includes a built-in automated market maker, enabling token swaps on-chain with very low friction.

  • Account abstraction (memos and batch):

Tempo supports features like native memo fields and native batch transfers. Businesses can add ISO 20022–style payment references (memos) for reconciliation and bundle multiple individual transfers into a single transaction, significantly improving efficiency for payroll or recurring payouts.

  • Privacy and compliance:

The chain offers optional private transactions and built-in compliance controls. User-level blocklists/allowlists let enterprises prevent sanctioned addresses or enforce KYC standards. These measures address privacy concerns while still obeying regulations – a key consideration for banks and large companies.

  • EVM compatibility:

Built on the Reth client, Tempo is fully compatible with Ethereum’s ecosystem. Developers can easily port smart contracts and wallets, lowering the barrier to adoption even though Tempo is a new network.

Taken together, these capabilities make Tempo unlike any mainstream chain today. By focusing exclusively on payments (stablecoin transfers, fiat on-ramps, payroll, etc.), it omits many elements needed for crypto trading that only add cost or latency. This streamlined design is why its creators call it “purpose-built” for real-world money movement.

More About Tempo

Secure blockchain payment solutions for businesses | Host Merchant Services.

Tempo is still in its infancy but already in trial use. A private testnet is running for select partners. These partners span fintech, commerce, and banking: design collaborators include Visa, OpenAI/Anthropic, Shopify, DoorDash, Nubank, Revolut, Standard Chartered, and others.

E-commerce and delivery companies can test cross-border payouts, while banks explore embedding blockchain payments or tokenized deposits. According to Stripe and Paradigm, use cases being tested include global payroll, intercompany remittances, embedded financial accounts, and even new AI-driven “agentic” payments.

The input from such diverse enterprises is meant to fine-tune Tempo’s features to actual business needs. (Eventually, Tempo plans to transition from its private network to a permissionless mainnet once the design is proven.)

Stripe’s rationale for all this can be summed up in two points: speed and user-friendly fees. In Collison’s words, Stripe’s payments traffic routinely outstrips what legacy blockchains can handle. And it’s not practical for a company to budget fees that fluctuate wildly with crypto markets. Tempo solves both: it delivers very high throughput and lets companies pre-purchase fee capacity in dollars (i.e., stablecoins).

Collison put it bluntly: existing blockchains “denominate their fees in blockchain-specific tokens,” whereas Stripe wanted fees “denominated in a fiat currency that makes sense to the user”. He added that features like native batch transfers (often unused in trading scenarios) are critical for payments. All these gaps led him to say, “We decided to incubate Tempo… We think of Tempo as the payments-oriented L1”.

Tempo reflects a broader shift in fintech infrastructure. It joins efforts like Circle’s new “Arc” network (announced Aug. 2025) – a multi-chain stablecoin platform for payments. These projects signal that big players see value in dedicated payment rails. If successful, Tempo could transform cross-border commerce, remittances, payroll, and more. Imagine instant, round-the-clock settlements between banks using on-chain tokenized deposits, or microtransactions for digital services priced in cents, all at minimal cost.

Companies could embed programmable payments directly into apps (for example, a ride-sharing platform issuing rides paid in stablecoins). These are the sorts of innovations Stripe cites when it talks about the next era of finance.

Of course, significant hurdles remain. Stablecoin-based systems still face uncertain regulation in many jurisdictions. Industry analysts caution that broad adoption will require clear rules and extensive testing beyond closed testnets.

Tempo’s architects are aware of this: they’ve included compliance hooks (like blocklists) and are collaborating with banks to ensure regulator comfort. In the words of crypto experts, specialized blockchains like Tempo “will likely play an even greater part in the crypto landscape” once governance catches up.

Conclusion

Stripe’s Tempo is a bold reimagining of what a blockchain can be. It’s a narrowly optimized, payments-oriented Layer-1 for the modern financial system. Stripe and Paradigm are both trying to build next-generation plumbing for cross-border transactions, embedded finance, and digital commerce by focusing exclusively on stablecoins, throughput, compliance, and UX.

If successful, Tempo could reshape how money moves globally, faster, cheaper, programmable, and finally built with business in mind.

Efficient payment processing solutions by Host Merchant Services for seamless business transactions.
Top Point of Sale Trends for 2026

Retailers, restaurateurs, and service businesses are rapidly modernizing their point-of-sale (POS) systems to meet changing consumer expectations. In 2025, POS technology is no longer limited to a cash register or card reader – it has become the nerve center of operations, tying together sales, inventory, customer data, and promotions across every channel.

Innovations in cloud computing, mobile devices, AI, and payments are reshaping the checkout experience both in-store and online. The result is smarter, faster, and more flexible POS systems that help businesses of all sizes improve efficiency and customer satisfaction. Below, we explore the top POS trends shaping technology in 2026, including cloud-based platforms and omnichannel integration, AI-driven analytics, mobile checkouts, and advanced payment methods.

Biggest POS Trends – The Top 9 That Shaped The Market in 2026

Cloud-Based and Hybrid POS Systems Are the Way Forward

Payment processing cloud technology illustration for Host Merchant Services.

By 2025, most businesses will have transitioned from traditional on-premises cash registers to cloud-based point-of-sale (POS) platforms. These modern systems are now widely used by retailers and restaurateurs of all sizes, offering greater flexibility, scalability, and cost efficiency. Unlike legacy terminals that require on-site servers and manual updates, cloud POS platforms store data and run software in the cloud, allowing managers and staff to access real-time sales and inventory information from anywhere. This anywhere-access capability keeps all locations in sync without manual data transfers.

Cloud-based POS systems also simplify maintenance through automatic software updates and feature deployments, ensuring merchants always run the latest version without downtime. Their affordability makes them especially attractive to small businesses, as most are offered through subscription-based, software-as-a-service (SaaS) models with low monthly fees rather than costly upfront purchases. Additionally, many cloud POS platforms adopt hybrid designs with local data caching, allowing operations to continue even during temporary internet outages. Once connectivity is restored, all transactions automatically sync back to the cloud.

The broader shift to cloud solutions has also introduced new subscription and as-a-service pricing models for POS systems. Instead of buying perpetual licenses, businesses now opt for monthly or annual plans that spread out costs, ensure continuous access to updates and support, and lower the barrier to entry for startups and pop-up shops. This ongoing subscription relationship also motivates POS providers to continually enhance their products, delivering consistent value to their customers.

Connected POS Platforms Are Transforming the Omnichannel Experience

POS terminal with wireless connectivity for secure card payment processing at Host Merchant Services.

Today’s customers expect a seamless shopping experience across every touchpoint, whether they browse products online, order through a mobile app, or pick up items in-store. This growing demand for omnichannel convenience requires POS systems to unify retail and e-commerce operations into a single, integrated platform. This means inventory, pricing, customer accounts, and loyalty programs must be synchronized across physical stores, websites, and mobile applications.

When a customer places an online order for in-store pickup (commonly known as “click-and-collect” or BOPIS), the POS system should automatically update stock levels both at the outlet and in the central inventory. Similarly, if a shopper views an item on their phone and completes the purchase in person, any applicable discounts or loyalty rewards should apply seamlessly across channels. Such cross-channel experiences are only possible when POS software maintains real-time synchronization between all sales points.

A unified POS environment provides several key advantages. It offers a single view of inventory, ensuring that stock counts update instantly with every sale, preventing overselling and allowing staff to locate items across all locations. It also maintains centralized customer profiles, storing contact details, order histories, and loyalty points in one place, enabling staff to deliver personalized service and targeted promotions. Flexible fulfillment options, such as returning online purchases in-store or shipping in-store orders to customers, are handled effortlessly by connected back-end systems. Moreover, consistent promotions across all channels ensure that discounts, gift cards, and loyalty points work the same way everywhere.

This shift toward unified commerce not only creates frictionless customer experiences but also strengthens brand loyalty and boosts sales. Research shows that retailers offering actual omnichannel experiences enjoy higher revenue and customer satisfaction. For business owners, this trend underscores the importance of choosing POS platforms that integrate seamlessly with e-commerce solutions such as Shopify, Magento, and WooCommerce, as well as social media marketplaces. Increasingly, companies are adopting “plug-and-play” POS systems that allow them to sell across multiple online and offline channels while managing everything from a single, centralized dashboard.

AI and Data-Driven Analytics at the POS

POS systems are now producing vast amounts of data, and businesses are increasingly using artificial intelligence (AI) and machine learning (ML) to unlock their value. No longer limited to simply recording transactions, modern POS platforms in 2025 serve as intelligent analytics and decision-support hubs. These systems leverage AI to forecast demand, optimize inventory, and deliver personalized marketing, all directly from the checkout counter.

An AI-powered POS can analyze historical sales data to predict which products are likely to sell out in the coming weeks, enabling timely reorders and minimizing lost sales. It can also identify emerging trends, such as a sudden spike in demand for specific items, and automatically alert managers to restock or promote those products. On the customer side, AI analytics can recognize purchasing patterns and preferences, allowing businesses to target specific offers or discounts to the right shoppers at the right time, boosting conversion and loyalty.

Through features like demand forecasting, the system learns from seasonal trends and events (such as holidays or weather changes) to suggest optimal reorder quantities, reducing both stockouts and overstock. Smart upselling uses customer insights to recommend complementary items at checkout. For instance, prompting employees to suggest a screen protector when a customer buys a phone case. Dynamic pricing, though more common online, is now being integrated into advanced POS systems, enabling businesses like restaurants to adjust prices automatically during peak hours. Customer insights tools would allow stores to identify VIPs and frequent shoppers and reward them with personalized loyalty benefits, such as automated birthday discounts or exclusive offers.

Overall, AI and analytics transform raw transaction data into actionable insights in real time. Both small retailers and large enterprises are rapidly adopting these capabilities, and many POS providers now include predictive analytics as a standard feature. For technology teams, this evolution calls for modular, API-driven architectures that enable machine learning models to connect to POS data streams seamlessly. Business owners get more accurate forecasting, more innovative marketing, and operational decisions that reflect actual customer behavior, making the modern POS a true intelligence engine for retail success.

Contactless and Flexible Payment Methods

Contactless payment processing by Host Merchant Services for seamless transactions.
Payment technology continues to evolve rapidly, and 2025 sees a greater variety and flexibility in how customers can pay. Contactless payment – whether by tapping a credit card, using Apple Pay or Google Pay on a phone, or scanning a QR code – has become the norm. Customers expect their POS to accept any modern payment type quickly and securely.

  • Mobile Wallets and NFC: Most POS terminals now have built-in NFC (near-field communication) readers. This allows customers to tap their smartphone or smartwatch to pay. It also enables tap-to-phone (“SoftPOS”) solutions, where a staff member’s smartphone can act as the payment terminal. SoftPOS technology is beneficial for pop-up shops and small vendors who want to accept contactless card payments without extra hardware.
  • QR Code Payments: Some systems display a QR code that customers scan with a mobile app (common in parts of Asia and gaining ground worldwide). The QR code can encode a payment link or be used with a digital wallet app. This method is convenient for quick checkouts or cases where physical terminals are scarce.
  • Buy Now, Pay Later (BNPL): “Buy now, pay later” services (such as Afterpay, Klarna, and Affirm) have become popular among consumers. In 2025, many POS systems will integrate BNPL options directly at checkout, both online and in-store. This gives customers more ways to pay in installments or with delayed payment, and can boost sales for merchants.
  • Cryptocurrency Acceptance: While still a niche, some retailers and hospitality businesses have started allowing crypto payments (e.g., Bitcoin or stablecoins). Specialized POS apps can instantly convert cryptocurrency transactions to local currency. This trend caters to tech-savvy customers, though it is not yet mainstream.
  • Flexible Wallets and Loyalty Payment: Some innovative POS platforms allow customers to pay with loyalty points, gift card balances, or mixed payment methods. For example, a shopper might split payment between a store gift card and a credit card. The POS handles all these seamlessly.

Because payment types evolve rapidly, security remains crucial. Modern POS systems use tokenization (replacing card numbers with random tokens), and end-to-end encryption so that sensitive payment details are never exposed in plain text on the system.

Two-factor authentication or biometric login (fingerprint or face scan) may be required for staff to access the payment functions. The upshot is that customers in 2025 enjoy many convenient payment options, and businesses must ensure their POS systems can handle all of them without compromising security or speed.

Mobile POS and Self-Service Kiosks

Traditional checkout counters are being rapidly replaced by more flexible, technology-driven models that enhance convenience and efficiency. One of the most significant shifts is the rise of mobile POS (mPOS), point-of-sale software that runs on smartphones, tablets, or dedicated handheld devices. Another major trend is the widespread adoption of self-service checkouts and kiosks, which empower both customers and employees while reducing wait times.

In modern retail environments, sales associates frequently carry tablets or handheld POS devices, allowing them to check prices, scan barcodes, and complete transactions anywhere on the sales floor. This approach, often called “line-busting,” ensures that staff can assist customers immediately without requiring them to queue at a fixed terminal. In hospitality settings such as restaurants and bars, servers use similar mobile systems to take orders and process payments directly at the table, saving time and improving service flow.

Mobile POS solutions are also transforming pop-up and outdoor sales. Small businesses and vendors at trade shows, farmers’ markets, or outdoor events can operate efficiently using just a tablet and a portable receipt printer, or even send digital receipts. Many mPOS applications function offline and automatically sync transactions once connectivity is restored, making them ideal for mobile operations.

At the same time, self-service kiosks have become standard in grocery stores, cafes, and quick-service restaurants. These kiosks allow customers to scan and pay for items independently, often incorporating AI tools such as cameras or scales to identify products like fruits and vegetables. By automating simple transactions, businesses can serve more customers with fewer staff and provide a faster, more autonomous experience for those who prefer self-checkout.

Another growing model is QR-based self-service, where customers use their own smartphones to scan product or menu QR codes. This enables them to browse options, place orders, and complete payments through a mobile web interface before showing a digital confirmation to collect their items. This “scan-and-go” approach is gaining momentum, especially in markets with high smartphone adoption.

The advantages of mobile and self-service POS models are clear: shorter lines, faster checkouts, and more personalized service. Businesses report higher average transaction values as customers enjoy browsing and buying at their own pace. For small merchants, affordable mobile POS systems make it easy to accept payments anywhere without the cost of a full register setup. For larger retailers, combining staffed checkouts, mobile associates, and self-service terminals creates a balanced and efficient customer experience that maximizes convenience and operational flexibility.

Integrated Systems: Loyalty, Inventory, and CRM

Integrated Systems

In 2025, a POS system is expected to be part of an integrated business ecosystem. It no longer operates in isolation; instead, it connects with CRM (customer relationship management), inventory management, e-commerce, accounting, and other software. The advantage is a unified, data-driven operation where all systems communicate in real time.

  • Real-Time Inventory Management: POS software is tightly linked to inventory systems. Each sale or return updates stock levels immediately. This lets businesses keep accurate stock across multiple warehouses and channels. Some stores even use Internet of Things (IoT) devices, such as smart shelves and electronic price tags, that automatically report inventory changes to the POS system.
  • Centralized Customer Data: Integrating with CRM systems allows a complete view of each customer. The POS can pull up past purchases, preferences, and contact information at checkout. This enables personalized service – for example, a cashier might see that a customer bought running shoes last month and now inform them of a sale on running socks. Data collected at the POS (such as email addresses or phone numbers for receipts) is returned to marketing databases for future outreach.
  • Loyalty and Rewards Integration: Most modern POS platforms include loyalty program management. Points or rewards earned online are tracked alongside in-store purchases. This means a customer can earn points by shopping on a website and redeem them at a brick-and-mortar checkout, or vice versa. Automatic tracking of loyalty transactions at the POS simplifies promotions and rewards.
  • Accounting and Reporting Sync: Sales data from the POS automatically syncs with back-office accounting and analytics tools. This reduces manual data entry and errors. Business owners can see financial reports up-to-date daily, rather than waiting for end-of-day spreadsheets.

This deep integration means that adding a new sales channel is easier than ever. For example, a retailer can expand into a new online marketplace or add a curbside pickup system, and the POS will handle it as another “store” in its network.

The unified data approach also empowers business owners: they can track top-selling items across channels, identify the most loyal customers, and make strategic decisions based on complete sales reports.

Enhanced Security, Compliance, and Privacy

As POS systems become increasingly interconnected, ensuring their security has become a top priority. In 2025, with cyber threats growing more sophisticated, businesses must implement robust protection measures at the checkout counter. At the same time, stricter government regulations and payment network compliance standards are driving retailers to adopt modern, security-focused POS solutions.

Modern POS terminals and card readers now rely on encryption and tokenization to protect payment data. End-to-end encryption ensures that a customer’s card information is encrypted the instant it is swiped or tapped, and only decrypted by the payment processor. This means that even if attackers intercept the data, it remains unusable without the decryption key. Additionally, sensitive card numbers are often replaced with unique tokens, preventing merchants from ever storing actual card data in their systems.

Compliance with the Payment Card Industry (PCI) standards has also become more rigorous. The latest guidelines require multi-factor authentication for administrators, regular vulnerability scans, and strict access controls. As a result, POS software now includes built-in compliance features such as requiring both passwords and one-time verification codes to access management functions.

At the same time, data privacy regulations like California’s CCPA and Canada’s PIPEDA have set clear rules on how customer data collected at checkout must be stored, used, and deleted. POS providers are incorporating “privacy by design,” ensuring customers can opt out of marketing, request data deletion, or export their personal information. This transparency not only builds trust but also positions compliance as a key selling point.

Another layer of protection comes from fraud detection and prevention tools. Many modern POS platforms include AI-powered analytics that flag suspicious activities in real time, such as unusually high-value transactions or repeated card use by a single customer, prompting staff to verify identities or seek manager approval. Biometric authentication is also becoming more common, allowing employees to log in using fingerprint or facial recognition instead of shared passwords, significantly reducing the risk of unauthorized access.

For business owners, a POS security breach can be devastating, leading to financial losses and long-term damage to reputation. That’s why modern POS platforms emphasize built-in, automated security, particularly cloud-based systems that deploy updates and patches across all locations simultaneously. Forward-thinking retailers now view compliance and data protection not merely as obligations but as competitive advantages, reassuring customers that their payment and personal data are safe and handled with the highest security standards.

Sustainability and Digital Efficiency

Sustainability and Digital Efficiency

Environmental sustainability and cost efficiency are increasingly shaping the evolution of POS systems. Businesses are adopting greener, smarter solutions that reduce waste, conserve energy, and streamline operations, all without compromising service quality.

One of the most visible shifts is the move toward digital receipts. Instead of printing paper copies, many businesses now offer e-receipts sent via email or text message. This not only reduces paper waste and printing costs but also helps retailers collect valuable digital contact information, with customer consent, for personalized marketing and loyalty programs. By 2025, most small and medium-sized businesses will default to offering e-receipts, and some will even incentivize customers to opt in with small discounts or loyalty points.

Another significant trend is the adoption of energy-efficient hardware. Modern POS terminals, scanners, and peripherals are designed to minimize power consumption through features such as automatic screen dimming, low-power chipsets, and sleep modes. Many businesses now use thermal printers, which require no ink or ribbons, further reducing waste and operational costs. Some retailers also choose devices built from recycled or sustainably sourced materials as part of their broader environmental commitments.

The shift toward compact, mobile POS setups also contributes to sustainability. Mobile POS devices reduce the need for bulky checkout counters, allowing for more flexible retail layouts and smaller energy footprints. Pop-up and tabletop systems consume less electricity than traditional full-sized registers and lighting setups, making them ideal for modern, minimalist retail spaces.

Beyond hardware, streamlined workflows driven by automation also help reduce environmental impact. By automating back-office functions such as inventory management and purchase ordering, businesses minimize paper use, manual data entry, and unnecessary travel or shipping associated with physical documents.

While sustainability might seem unrelated to the checkout process, it delivers tangible business and environmental benefits. Reducing paper usage lowers supply costs and declutters the workspace, while adopting eco-friendly practices resonates positively with environmentally conscious consumers. Ultimately, a green POS strategy not only supports corporate social responsibility goals but also enhances brand reputation, operational efficiency, and customer loyalty.

Emerging Technologies: IoT, AR/VR, and Beyond

Beyond the major trends shaping today’s POS systems, several emerging technologies are beginning to influence how retailers and restaurateurs envision the future of transactions. While many of these innovations are still in early stages, they hint at how the POS landscape may evolve in the coming years.
One of the most promising areas is the integration of the Internet of Things (IoT). Retailers are testing IoT-enabled devices that feed real-time data directly into POS platforms. For example, smart shelves equipped with weight sensors or RFID tags can automatically detect low stock levels and trigger replenishment in the POS system. Electronic shelf labels can instantly update prices and stay synchronized with digital pricing databases. In hospitality settings, IoT-enabled tables can alert servers when a guest finishes their meal or when a bill is ready to be settled. The overarching goal is to create a seamless, automated link between the physical retail environment and digital sales operations.

Augmented Reality (AR) and Virtual Reality (VR) are also merging with POS technology, enhancing customer engagement before checkout. Furniture stores, for instance, may allow customers to visualize products in their homes using AR apps that connect directly to the POS for instant purchase. Apparel retailers are experimenting with virtual try-on mirrors, where customers can preview outfits and then complete the transaction immediately within the same system. Although full VR shopping experiences remain niche, they are gradually gaining traction, offering immersive store environments that can integrate with POS platforms for payment and order fulfillment.

Voice commerce is another developing area. While currently more common in online retail and smart-home ecosystems, voice technology is also influencing POS systems. Some cafes and quick-service restaurants now let customers reorder their usual items through voice assistants, with the POS system automatically processing the order. Similarly, in-store staff may soon use voice commands to restock items or access reports hands-free, improving efficiency and convenience.

SoftPOS (Tap-to-Phone) technology is rapidly maturing and represents one of the most practical innovations. By turning a standard smartphone into a secure payment terminal, SoftPOS allows small merchants, pop-up vendors, and market sellers to accept contactless card payments without dedicated hardware. This lowers barriers to entry and extends digital payment acceptance to nearly any business setting.

Meanwhile, biometric payment methods are emerging as the next step in frictionless checkout. Some pilot programs enable enrolled customers to pay using a fingerprint or facial scan, linked to their digital wallets or accounts. While privacy and security concerns remain, these systems showcase the potential for faster, password-free transactions that blend convenience with personalization.

Though not yet essential for all businesses, these technologies highlight the POS system’s ongoing transformation from a static register into a dynamic commerce platform. As IoT, AR, voice, and biometric tools evolve, forward-looking POS vendors are focusing on open APIs, strong encryption, and modular architectures to stay compatible with innovations. For business owners, staying informed about these developments ensures that their POS investments remain adaptable and future-ready in an increasingly connected retail world.

Conclusion

The point-of-sale landscape in 2026 is defined by flexibility, intelligence, and integration. Businesses of all sizes are transforming their checkout systems into sophisticated platforms that handle everything from payments to personalized marketing.

For a broad US audience – from small business owners to large enterprise retailers and tech professionals – the message is clear: Invest in a POS strategy for 2025 that embraces these trends. Upgrading to cloud-based, integrated POS systems will improve operational efficiency, customer satisfaction, and adaptability. By staying ahead of these trends, businesses can ensure they meet consumer expectations, streamline their workflows, and maintain a competitive edge in the rapidly evolving retail and hospitality landscape.

Frequently Asked Questions

  1. What are the biggest POS trends to watch in 2026?

    The key POS trends include cloud-based systems, omnichannel integration, AI-powered analytics, mobile and self-service checkouts, and flexible payment options. Together, these innovations make transactions faster, smarter, and more customer-focused.

  2. Why are businesses shifting to cloud-based POS systems?

    Cloud POS platforms offer real-time access to sales and inventory data from anywhere, automatic updates, and lower upfront costs. They’re also scalable, allowing businesses to expand easily while maintaining consistent performance.

  3. How does AI improve POS systems?

    AI and machine learning analyze sales data to forecast demand, suggest reorders, and personalize promotions. This helps businesses make smarter inventory decisions and create more targeted, profitable customer experiences.

  4. What payment options do modern POS systems support?

    Today’s POS systems support a wide range of payment methods, including contactless cards, mobile wallets, QR codes, BNPL (Buy Now, Pay Later), and even crypto. Many also support mixed payments, loyalty points, and secure biometric verification.

  5. How are POS systems becoming more secure and sustainable?

    Modern POS platforms use encryption, tokenization, and multi-factor authentication to protect data. They also reduce paper waste by using digital receipts and energy-efficient, eco-friendly hardware to support greener operations.

Cryptocurrency payment integration on mobile device.

Crypto Payments Come of Age: Mainstream Tools for Merchants

Cryptocurrency payments have moved from a niche curiosity to a practical option in everyday commerce. Major payment providers and financial networks are rolling out services that make it easy for merchants to accept digital currencies.

These mainstream tools — from PayPal’s crypto checkout to Visa and Mastercard’s stablecoin integrations — are bridging the gap between crypto and traditional finance. As a result, businesses can tap into the growing crypto payment economy with less friction, lower fees, and mitigated risks. This blog explores the latest crypto payment solutions for merchants, their benefits, and key considerations as crypto enters the mainstream of payments.

PayPal’s “Pay with Crypto” Signals a Turning Point

Pocket PayPal logo with falling bitcoin coins, emphasizing online payment solutions.

One of the most evident signs of crypto payments going mainstream is PayPal’s new Pay with Crypto feature for U.S. merchants. Announced in mid-2025, this service allows businesses to accept customer payments in over 100 different cryptocurrencies – from Bitcoin and Ether to popular stablecoins – with instant conversion to fiat currency or stablecoin on the back end. Now, a shopper can pay using their crypto wallet (e.g., MetaMask or Coinbase Wallet) at checkout, while the merchant receives the funds in USD or in PayPal’s own USD-backed stablecoin (PYUSD) almost immediately.

This means merchants don’t have to handle or hold volatile crypto assets if they don’t want to. The crypto is automatically converted for them, eliminating exposure to price swings during the transaction.

Low fees are another selling point. PayPal is charging merchants a 0.99% transaction fee for crypto payments – roughly 90% lower than the fees on typical international credit card transactions. For businesses that sell internationally, those savings on payment processing can be significant.
PayPal’s CEO, Alex Chriss, noted that merchants can “pay lower transaction fees, get near-instant access to proceeds, and even earn interest on funds held in PYUSD” as benefits of the system. Indeed, funds kept as PayPal’s PYUSD stablecoin earn a yield (around 4% as of launch) within PayPal accounts, adding an extra incentive.

Importantly, Pay with Crypto taps into a large user base and crypto market. By supporting 100+ cryptocurrencies (covering an estimated 90% of the total crypto market capitalization) and major wallet apps, PayPal’s solution gives merchants access to a global pool of over 650 million crypto users.

In other words, customers around the world who hold crypto can spend it at checkout with PayPal merchants, expanding the merchant’s potential customer base. This opens doors to new sales, especially in cross-border scenarios where traditional payment methods can be costly or unavailable. “Imagine a shopper in Guatemala buying a special gift from a merchant in Oklahoma City,” Chriss said, explaining that PayPal’s crypto platform enables that purchase with lower fees and no complex forex or banking hoops. The vision is to make international e-commerce as seamless as a local sale, using crypto as the payment rail behind the scenes.

Payment Networks Embrace Stablecoins

Stablecoins

If PayPal’s move brings crypto payments to mainstream online checkout, the major payment networks are ensuring crypto fits into the global payments infrastructure. Both Visa and Mastercard have been actively integrating stablecoins – cryptocurrencies pegged to fiat currencies like the U.S. dollar – into their networks.

Stablecoins offer the benefits of crypto (speed, global reach, lower costs) without the volatility, making them attractive for payments. In fact, blockchain-based stablecoin transactions have exploded in volume in recent years, even surpassing the annual transaction volume of Visa and Mastercard combined in 2024, according to some metrics. Payment giants are responding by treating stablecoins as a serious complement to traditional currencies.

Visa, for example, has expanded its stablecoin settlement capabilities. In July 2025, Visa announced support for multiple USD-backed stablecoins and blockchains in its settlement platform. This includes adding support for Circle’s USDC (which Visa had piloted earlier), PayPal’s PYUSD, and a Paxos-issued stablecoin, USDG, across networks such as Ethereum, Solana, Stellar, and Avalanche. Visa even integrated a euro-pegged stablecoin (EURC) for Euro settlements.

The goal is to enable issuers and acquirers (the banks on each side of a card transaction) to settle payments with Visa using stablecoins in addition to traditional fiat. In essence, a merchant might one day receive a Visa payment from a customer and have the option to settle that transaction to their bank via a stablecoin rather than the slow bank wire process.

This can speed up cross-border payments and reduce costs by cutting out intermediary bank fees. Visa’s leadership stated that as trusted, regulated, stablecoins become interoperable at scale, they could “fundamentally transform how money moves around the world”—a strong endorsement of crypto’s role in future payments.

Mastercard is likewise bringing stablecoins into the fold. The company’s chief product officer wrote in 2025 that Mastercard already allows millions of people to spend their stablecoin balances at over 150 million merchants in its network by linking crypto wallet apps to Mastercard payment cards. Those are largely crypto debit cards (issued by companies like Crypto.com and Binance) that let users pay with crypto through the standard card system.

From the merchant’s perspective, they were still receiving fiat—but it showed the reach of stablecoins when bridged to traditional card rails. Now, Mastercard is going further by natively supporting a portfolio of stablecoins on its network for various uses. New partnerships will enable USD Coin (USDC), USDG, PYUSD, and even a bank-issued stablecoin (FIUSD by Fiserv) to be used for merchant settlement, money transfers, and stablecoin-native card issuance.

Mastercard is working with PayPal to explore settling transactions in PayPal’s PYUSD stablecoin in the future. It’s also integrating stablecoins into offerings like Mastercard Send/Move (for cross-border payments) and a forthcoming Mastercard One Credential that could let consumers spend both fiat and stablecoins from one account.

All of these efforts point to stablecoins becoming an accepted part of the payments ecosystem, backed by the security and compliance measures of established networks. The upshot for merchants is that over time, paying with a stablecoin could be as easy and trusted as any other payment – but faster and cheaper, especially for international transactions.
A cashier at a retail store accepts a digital payment from a customer. Payment giants like Mastercard are integrating crypto (particularly stablecoins) into their networks, so that in the near future, consumers could pay merchants with digital currencies as seamlessly as swiping a card.

Beyond Visa and Mastercard, other big financial players are embracing crypto in ways that directly or indirectly help merchants. Fiserv, one of the largest payment processors (behind popular POS systems like Clover), announced plans in 2025 to launch its own FIUSD stablecoin and partner with PayPal and Circle on stablecoin interoperability.

The idea is to use stablecoins to streamline merchant settlements and cross-border payments after hours. Meanwhile, leading fintech companies like Stripe are also exploring crypto rails. For instance, Stripe is helping develop a new blockchain network for stablecoin-based payments called “Tempo” to modernize payment infrastructure. Even point-of-sale hardware providers are on board: Verifone has partnered with BitPay to enable cryptocurrency acceptance on its card terminals in retail stores.

Benefits of Mainstream Crypto Payment Tools

Increased business growth with Host Merchant Services benefits.

For merchants, these mainstream crypto payment tools offer several compelling benefits:

  • Lower Transaction Fees:

Crypto payment services often charge lower fees than credit card processors. For example, PayPal’s 0.99% fee for crypto transactions undercuts typical card fees of 2–3% (even higher for cross-border sales).

Over time, lower payment processing costs can boost a merchant’s profit margins, especially on international orders, where currency conversion and intermediary bank fees are eliminated.

  • Global Customer Reach:

Accepting cryptocurrency opens the door to a worldwide customer base that prefers or only has access to crypto. There is an estimated multi-hundred-million-strong cohort of crypto holders globally, representing a $3+ trillion asset class.

By offering crypto as a payment option, merchants can attract new customers who want to spend their digital assets. In fact, surveys indicate 85% of merchants see crypto payments as a way to reach new customers and expand brand exposure.

Crypto is especially useful for serving international buyers in regions with limited banking or high payment barriers – they can transact directly, and the funds still arrive to the merchant in a usable currency.

  • Fast Settlement and Cash Flow:

Crypto transactions can settle in minutes (or even seconds on specific networks or with stablecoins), meaning merchants get their funds faster than waiting days for card payments to clear or bank transfers to arrive. PayPal’s system, for instance, provides near-instant access to the converted proceeds of a crypto sale.

Faster settlement improves cash flow for businesses. It also enables quicker order fulfillment or reinvestment of funds, as there’s no need to wait for lengthy clearinghouse processes.

  • Reduced Chargebacks and Fraud Risks:

Unlike credit card payments, cryptocurrency transactions are push payments that the customer explicitly authorizes on their device, and they are cryptographically secured. There are no card numbers that can be stolen and used fraudulently, and once a crypto payment is confirmed, it’s irreversible – meaning no chargeback threat to merchants.

This can significantly reduce losses from fraud and abuse. Studies show that many merchants adopt crypto precisely to minimize chargebacks and fraud-related costs. Plus, when mainstream providers like PayPal or Mastercard mediate crypto payments, they often add additional fraud screening and buyer protections, giving merchants confidence that these transactions are as safe as traditional methods.

  • Alternative for Customers and Marketing Boost:

Offering crypto gives customers more choice at checkout. Even if relatively few use it today, those who do are passionate about it. Merchants can gain positive marketing by positioning themselves as forward-thinking and accommodating of new technologies. During promotions or international sales, highlighting a crypto payment option can differentiate a merchant from competitors.

It also prepares the business for a future in which digital currency use may be far more widespread. In surveys, about 83% of merchants expect interest in digital currency payments to grow in the next 12 months. Getting on board early can be a strategic differentiator.

  • Stablecoin Advantages:

With stablecoins in particular, merchants get the best of both worlds – transactions in a cryptocurrency form that still hold a steady fiat value. This eliminates the worry that a coin’s price will swing wildly between the time a customer pays and the merchant settles. Stablecoins like USDC or PYUSD are designed for stability, making them ideal for commerce.

They can also earn interest or rewards when held (as with PayPal’s PYUSD program), potentially adding a bit of yield on top of payment convenience. And when merchants use stablecoins for cross-border payments or vendor payouts, they avoid the complexities and delays of currency conversion.

Addressing Volatility, Regulation, and Other Considerations

Volatility

While the new wave of crypto payment tools greatly simplifies things, merchants still need to be mindful of specific considerations when diving in:

  • Volatility and Conversion:

The most obvious concern with crypto is price volatility. The value of Bitcoin or Ethereum can fluctuate by the hour. The current mainstream solutions address this by instantly converting crypto to fiat or stablecoin – so the merchant is not left holding a volatile asset. If a merchant chooses to accept and hold an actual cryptocurrency (say, Bitcoin), they are exposed to market risk, which could result in a gain or a loss.

Most merchants avoid this by using payment providers (such as PayPal, BitPay, etc.) that lock in the fiat value at the time of sale. Stablecoins further mitigate volatility by design. A best practice is to convert crypto to fiat or a stablecoin immediately unless the business has a specific reason to hold crypto. This way, pricing remains effectively in dollars (or the merchant’s base currency) and accounting is simpler.

  • Regulatory Compliance:

When accepting crypto, merchants must follow applicable laws on money transmission, taxes, and reporting. In many countries, converting crypto into fiat requires records for tax purposes, just as with any other income (plus any capital gains if crypto was held). Reputable payment providers will usually help by providing transaction reports and even handling sales tax calculations in fiat.

Still, merchants should ensure their accounting systems can properly record crypto sales (which are usually recorded as sales at the fiat equivalent value at the time of the transaction). Know-Your-Customer (KYC) and anti-money-laundering rules may also apply if merchants deal directly with crypto; however, using established platforms (PayPal, Coinbase Commerce, etc.) outsources most of that compliance to those providers.

It’s also wise to double-check local regulations—for example, some jurisdictions may require special registration to accept crypto or prohibit specific tokens. The trend is toward more straightforward guidelines: the U.S. saw movement in 2025 with a proposed stablecoin regulatory framework that, if passed, would lend legitimacy and clear rules to the sector. Overall, working with mainstream, regulated companies for crypto payments helps ensure compliance is baked in.

  • Technical Integration:

Earlier generations of crypto payments required technical savvy—setting up wallets, managing private keys, and monitoring block confirmations. Now, mainstream crypto payment tools abstract away most of that complexity. Still, integration is a consideration: merchants will typically add a plugin or API from the provider to their website or point-of-sale system. An online shop using Shopify or WooCommerce can install extensions to accept crypto via partners like Coinbase Commerce or BitPay.

PayPal’s solution will likely be built into its standard checkout offerings, making it straightforward to use. In-store, a merchant might need to update their card terminal software if working with something like the Verifone crypto integration. These are usually one-time setup tasks, but merchants should allocate some time for testing.

It’s advisable to train staff (in physical retail) to handle crypto payments, even if the interface looks like a standard card transaction. Backup procedures (e.g., what to do if a blockchain transaction is pending too long) should be understood. However, providers often handle them automatically by confirming with the merchant only once the final amount is confirmed.

  • Customer Experience:

The success of crypto payments also depends on the customer side experience. If using a service like PayPal’s, the customer’s checkout flow needs to be smooth – e.g., scanning a QR code or connecting their wallet. Any hiccups (like long confirmation times or confusing wallet steps) can deter usage.

The good news is that with multiple fast blockchains and layer-2 networks supported, many crypto payments can be nearly instant and with negligible fees for the customer as well. Still, merchants may want to communicate at checkout that crypto payments are welcome clearly and, if possible, provide simple instructions. Over time, as these payments become as plug-and-play as Apple Pay or card tapping, the friction will be minimal.
  • Security:

Accepting crypto directly means securing wallet keys, but again, if using a payment provider, the merchant isn’t holding crypto directly. The security then is largely about ensuring the integration with the provider is secure (using HTTPS, API keys protected, etc.). Mainstream providers come with robust security measures.

Mastercard and others have introduced crypto fraud monitoring and identity verification tools similar to those in traditional payments. One specific point: merchants should beware of phishing or spoofing – e.g., an attacker tricking them into updating a receiving address. Sticking to well-known platforms and following their security guidelines is the best defense.

  • Adoption and Strategy:

Finally, merchants should set realistic expectations for crypto payment volumes. Even with all the buzz, only a single-digit percentage of merchants actively accept crypto today, and consumer usage is still emerging. This is poised to grow — more than 75% of U.S. merchants surveyed in 2023 planned to enable crypto payments within two years — but it will likely start as a small share of sales.

Thus, crypto should be seen as an additional option that could incrementally boost sales and reduce certain costs, rather than a replacement for existing payment methods overnight. It’s wise to monitor how many customers start using it and what kind of purchases they make. Some businesses may find it drives new high-value international orders, for example. Others may use it as a marketing angle (“10% off if you pay in crypto this week”) to spur initial usage. Being strategic and patient will help merchants get the most out of adding crypto payments.

The Road Ahead: From Niche to Norm

The trajectory of crypto payments in commerce is increasingly evident. What was once the domain of tech-savvy enthusiasts is now being transformed into polished, enterprise-grade payment solutions offered by the biggest names in finance and tech.

With PayPal enabling crypto at checkout for millions of merchants, and Visa and Mastercard weaving stablecoins into the fabric of global payments, the foundation is being laid for digital currencies to become a viable everyday payment option. Businesses that adopt these tools stand to gain access to new customers, reduce payment costs, and stay ahead of an innovation curve reshaping payments.

That said, the transition will be gradual and will vary by region and industry. Consumer trust and demand will grow as success stories spread and as using crypto becomes as easy as using any other mobile wallet. We may soon see a world where checking out with a crypto wallet is as unremarkable as tapping a phone for Apple Pay – the technology fades into the background, and people choose the payment method that offers them the best convenience and value.

For merchants, being ready for that world could pay dividends. The tools to accept crypto are no longer exotic or complex; they’re off-the-shelf offerings from payment providers you likely already use, designed to mitigate the old risks of crypto while amplifying its advantages.

Conclusion

Crypto payments are coming of age through mainstream channels. By leveraging features such as instant stablecoin conversion, low fees, and network-level integrations, these new tools make it practical for merchants to say “Yes, we accept crypto” without the headache or hassle. Early adopters are finding it can reduce costs and attract customers, all while offering a modern payment experience.

As the ecosystem continues to mature – with more stablecoin use, clearer regulations, and even central bank digital currencies on the horizon – the line between crypto and traditional money will further blur. Crypto as a payment option is here to stay, and it’s moving from a novelty to a competitive necessity in the toolkit of global commerce. Merchants who embrace these innovations can tap into a new era of borderless, frictionless transactions, positioning themselves at the forefront of payments.

Frequently Asked Questions

  1. What does it mean that crypto payments have gone mainstream?

    It means major players like PayPal, Visa, and Mastercard now support crypto and stablecoin payments. Merchants can accept crypto easily through familiar systems, with automatic conversion to fiat if desired.

  2. How does PayPal’s “Pay with Crypto” benefit merchants?

    Merchants can accept over 100 cryptocurrencies with instant conversion to USD or PayPal’s PYUSD stablecoin. They enjoy lower fees (0.99%), near-instant settlement, and the option to earn yield on PYUSD balances.

  3. Why are Visa and Mastercard integrating stablecoins?

    Stablecoins combine crypto’s speed and low cost with price stability. Visa and Mastercard now use them for faster, cheaper settlements and cross-border payments, making crypto fit smoothly into existing payment networks.

  4. What are the main advantages of accepting crypto payments?

    Merchants get lower transaction fees, faster payouts, reduced fraud risk, and access to a global crypto customer base. They can expand sales while keeping transactions secure and cost-efficient.

  5. Do merchants face risks when accepting crypto?

    Not if they use mainstream tools. Services like PayPal or Coinbase Commerce handle conversions and compliance, protecting merchants from volatility and regulatory complexity while simplifying integration.

NFT digital token representation on purple background.

Top NFT Trends to Watch

The world of non-fungible tokens (NFTs) is developing rapidly. After the initial frenzy of 2021 and 2022, the market cooled and shifted towards more practical uses of NFTs. In 2025, NFTs are moving beyond simple digital collectibles and hype, finding new roles in finance, art, gaming, and enterprise applications.
The global NFT market is still on a growth trajectory, expected to reach nearly $49 billion by the end of 2025, up from about $11 billion in 2022. Below are the top NFT trends to watch in 2025, reflecting how this maturing sector is innovating and expanding its reach.

Top NFT Trends: Best 8 to Watch

1. Real-World Asset Tokenization (RWA NFTs)

Secure payment processing icon for Host Merchant Services.

One of the most significant trends is the use of NFTs to represent real-world assets such as property, luxury goods, and other physical items. Real-World Asset (RWA) tokenization involves creating NFTs that confer ownership or fractional ownership of tangible assets—for example, real estate deeds, fine art, or collectibles. In fact, real estate NFTs alone saw over $1.4 billion in transaction volume, as fractional ownership models gained traction. By tokenizing high-value assets, NFTs allow investors to buy fractional shares of things that were once illiquid or accessible only to the wealthy.

This democratizes investment in assets like real estate and art, providing liquidity and broader access. Businesses are exploring RWA NFTs to open new revenue streams, turning traditionally illiquid assets into tradeable tokens on blockchain marketplaces. This trend is unlocking opportunities to invest in and trade real-world assets through NFTs, blurring the line between physical and digital asset markets.

2. NFTs with Utility and Community Value

Early NFTs were often just static images or collectibles, but utility NFTs are becoming far more critical. A utility NFT provides tangible benefits or functions beyond mere ownership of a digital image. For instance, NFTs can serve as tickets to exclusive events, membership passes to online communities, or governance tokens in decentralized organizations. Holders might get special access, voting rights in a DAO, or other perks tied to the NFT.
This trend means NFTs are increasingly used to build communities and loyalty programs—for example, an NFT could grant entry to a fan club, unlock bonus content, or offer discounts. In the business world, companies use utility NFTs to engage customers, such as loyalty rewards or VIP access for NFT holders.

Another innovation is dynamic, or “hybrid,” NFTs, which can change over time or respond to specific conditions. These are tokens programmed via smart contracts to evolve – imagine a game character NFT that levels up as you play, or digital art that morphs based on real-world data. Such hybrid NFTs add interactivity and keep collectors engaged by offering tokens that are not static but can update, upgrade, or personalize over time.
In 2025, these dynamic NFTs are gaining popularity, especially in gaming and digital art, where evolution and customization add a new layer of value. By moving beyond one-dimensional collectibles, NFTs with real utility and dynamic features are fostering stronger communities and long-term user engagement in the NFT ecosystem.

3. Gaming and Metaverse Integration

Seamless online payment processing by Host Merchant Services for small and large businesses.

The intersection of NFTs with gaming and virtual worlds (the metaverse) is a significant growth area. In 2025, gaming-related NFTs account for a substantial share of NFT activity – roughly 38% of global NFT transactions, making gaming the single largest NFT segment. The appeal is clear: NFTs can represent in-game items, characters, skins, virtual land, or other digital assets that players truly own and can trade. Early pioneers like CryptoKitties demonstrated the concept of NFTs in games back in 2017, and now countless games use NFTs for collectibles and play-to-earn models.

Gamers are embracing NFTs because they allow items to have real-world value and portability outside the game environment. A sword or avatar earned in one game could potentially be sold or even used in another game or platform.

NFTs are also foundational to the metaverse, where digital real estate and goods can be bought and sold as NFTs. Virtual land plots on metaverse platforms (like Decentraland or The Sandbox) are essentially NFTs that grant ownership of a virtual plot. By 2025, virtual real estate NFTs and metaverse assets will continue to rise in value as more users join these immersive platforms.

Brands and individuals are investing in virtual properties and NFT-based avatar wearables. This integration of NFTs in gaming and metaverse experiences means that digital items have persistent value beyond any single platform – they become part of a broader digital economy. Analysts project the market for gaming NFTs will keep expanding (with some estimates aiming for tens of billions in the coming decade).

4. Artificial Intelligence and NFTs (AI-Generated and Intelligent NFTs)

Another exciting trend is the convergence of artificial intelligence (AI) with NFTs. On the one hand, AI is used to generate art and collectibles, which are then minted as NFTs. Artists and platforms are leveraging AI algorithms (such as generative adversarial networks and other creative AI tools) to produce unique images, music, and other media that can be sold as “AI-generated” NFTs.

This has lowered barriers for content creation – even individuals with minimal artistic skill can use AI tools to create interesting NFTs. It’s estimated that AI-driven projects make up a growing share of new NFT launches; one analysis predicts roughly a 30% year-over-year increase in AI-generated NFTs around 2025–2026. The rise of AI art has also sparked debate about authorship and originality, but buyers are showing interest in these novel, algorithmically crafted collectibles.

Even more futuristic is the idea of “intelligent NFTs” (iNFTs)—NFTs embedded with AI agents or interactive machine learning models. In early 2025, an Ethereum development group (0G Labs) proposed ERC-7857, a new token standard for iNFTs that enables the secure on-chain transfer of AI models. This would allow an AI (like a trained chatbot or digital assistant) to be packaged as an NFT and bought or sold. The ERC-7857 standard addresses how to re-encrypt an AI’s data when ownership changes, ensuring the AI’s knowledge is transferred safely to the new owner.

If this concept takes off, we might see marketplaces for AI-driven digital characters or services, where owning the NFT means owning the AI agent. Additionally, mainstream interest in AI + NFT is evident – searches for terms like “AI NFT” spiked in 2025 as people anticipate new creative possibilities at the intersection of these technologies.

5. Brands, Phygital NFTs, and the Metaverse Economy

Brands Phygital NFTs and the Metaverse Economy

Big brands were early adopters of NFTs during the 2021 boom, often releasing limited-edition collectibles. In 2025, the approach has matured: many brands are focusing on “phygital” NFTs, which combine physical and digital experiences. For example, luxury fashion and lifestyle brands have used NFTs to authenticate physical products or as tickets to exclusive events.

A notable case is Adidas’s ALTS NFT collection, launched in 2025, which offers 20,000+ avatar NFTs that double as membership tokens – holders get access to special merchandise and invites to real-world events. Similarly, Gucci continued to issue NFT art pieces tied to its brand, blending digital art with the high-end fashion appeal of its products. These moves show how NFTs can act as digital keys for brand loyalty: owning a brand’s NFT might grant you VIP status, discounts, or unique experiences that non-holders can’t access.

This trend of linking NFTs to physical perks is driving what some call a “phygital token” market. In fact, luxury brands have pushed a 60% rise in phygital NFT transactions, using tokens to tie physical goods to digital records of ownership or exclusive content. NFTs provide provenance and authenticity for physical items (like a watch or a piece of art), and they create a community around the brand’s digital collectibles.

However, it’s worth noting that not all brand experiments have succeeded – by 2025, a few high-profile companies pulled back. For instance, Nike (which had acquired NFT studio RTFKT) decided to shut down its NFT platform and even closed its Nikeland metaverse project on Roblox. Starbucks launched an NFT-based rewards program (Odyssey) but later discontinued it. These retrenchments suggest that brands are learning and adjusting their Web3 strategies.

On the flip side, new entrants and institutional players are stepping in. E-commerce giant Amazon and software firm Salesforce have both begun integrating NFTs into their offerings, indicating ongoing confidence in NFT technology for customer engagement and e-commerce digital goods. Plus, analysts predict that by 2026, nearly half of Fortune 500 companies could be using NFTs in some form (for example, as part of loyalty programs or digital twins of products).

6. Cross-Chain and Interoperable NFTs

As the NFT ecosystem expands, it’s no longer confined to a single blockchain. In 2025, we see a clear trend toward cross-chain NFT platforms and interoperability. Ethereum dominated early NFT markets, but now alternative networks (like Solana, Polygon, Binance Smart Chain, and even Bitcoin via Ordinals) have thriving NFT communities.

Cross-chain marketplaces are emerging that let users trade NFTs across multiple blockchains, often through interoperable standards or bridges. Future-ready NFT platforms recognize that traders want a seamless experience no matter where an NFT was minted initially. You might hold NFTs on Ethereum but want to sell them on a marketplace that also supports Solana NFTs – new tools are making this possible without needing to convert or wrap assets in cumbersome ways.

There are also efforts to standardize NFT metadata and ownership so that NFTs can be transferred between virtual worlds and games. This is crucial for the metaverse vision: an avatar outfit NFT from one platform should ideally be usable in another match or social world. Projects in 2025 are increasingly designing NFTs with interoperability in mind, meaning the token’s data and attributes can be recognized across different ecosystems.

Additionally, with Ethereum’s upgrades and the rise of Layer-2 networks (such as Arbitrum, Polygon, and zkSync), NFT transactions are becoming faster and cheaper. This reduces the friction in moving assets across chains. In practice, the NFT marketplace landscape is moving toward a more agnostic model: users care less about which blockchain underpins their NFT, as long as ownership can be verified and transferred securely. This cross-chain trend will likely continue, making the NFT space more interconnected and accessible to a broader audience of creators and collectors.
7. Sustainable “Green” NFTs
Sustainable “Green” NFTs

The environmental impact of NFTs (and blockchain in general) has been a hot topic, mainly when Ethereum relied on energy-intensive proof-of-work mining. By 2025, we see a strong push towards sustainable NFTs and eco-friendly blockchain practices. Ethereum’s switch to proof-of-stake in 2022 drastically reduced its energy usage, addressing a significant concern.

Beyond that, many NFT creators and buyers now prefer energy-efficient blockchains (such as Tezos, Polygon, or Flow) that have lower carbon footprints for minting and transacting NFTs. This has led to the rise of terms like “green NFTs,” referring to NFTs minted on platforms that use minimal energy or even offset their emissions.

Plus, some NFT projects actively support environmental causes—for example, EcoNFTs that tie token ownership to funding carbon credits or conservation projects. These NFTs might represent a stake in a reforestation effort or a renewable energy project, blending collectibles with social impact. The growing awareness of sustainability in the crypto community is influencing marketplace behavior, too. In 2025, we see marketplaces advertising their carbon-neutral operations or facilitating carbon offsets when you mint an NFT.

According to industry observers, this trend of “greener” NFTs will only gain momentum. Artists and platforms adopting sustainable practices are likely to attract environmentally conscious users and avoid alienating audiences worried about climate impact. In sum, expect NFTs in 2025 to have a greener pedigree, whether through the blockchains they use or the real-world initiatives they support, aligning with broader global sustainability goals.

8. Regulation and Institutional Adoption

Finally, a crucial trend shaping NFTs in 2025 is the regulatory landscape and institutional involvement. After the wild west days of 2021, regulators around the world are increasingly scrutinizing NFTs to protect investors and ensure compliance (e.g., regarding fraud, securities laws, and taxation). The U.S. and EU have both signaled moves toward clearer legal frameworks for NFTs, which reduces uncertainty for businesses and investors. The U.S. SEC recently closed an investigation into a central NFT marketplace without pursuing enforcement, suggesting that regulators may opt to set guidelines rather than penalize the nascent industry.

In the EU, comprehensive crypto regulations (such as MiCA) are beginning to address NFTs, at least in terms of distinguishing them from cryptocurrencies and ensuring market integrity. Greater regulatory clarity in 2025 is a double-edged sword: it can increase trust and open the door for big players, but it also means NFT ventures must adhere to compliance requirements.

Speaking of big players, institutional adoption of NFTs is on the rise. Major corporations and brands (as mentioned earlier with Amazon and others) are exploring NFTs for their business models. We’re also seeing interest from financial institutions and venture capital in NFT infrastructure, investments in companies that build NFT platforms, custody solutions, or NFT-focused funds. The maturation of NFT technology (including better scalability through Layer-2 networks and improved security) makes it more viable for mainstream use.

However, the market is not without challenges: as of 2025, the total NFT market cap (around $6 billion) remains well below its late-2021 peak, and issues such as market volatility, scams, and intellectual property disputes persist. Regulators have noted problems such as NFT fraud, which totaled over $100 million in 2024, underscoring the need for stronger security and compliance tools in the space.

Despite these risks, the overall outlook is optimistic. Industry projections foresee the NFT market growing at a strong pace (over 30-40% CAGR) for the rest of the decade. Institutional capital tends to flow to markets with regulatory certainty and growth potential, so as rules solidify, we could see more traditional investors enter the NFT market. The combination of clearer regulations and widespread corporate adoption is poised to legitimize NFTs further and drive the next wave of expansion in 2025 and beyond.

Conclusion

NFTs in 2025 are far from a fad—they are evolving into a multifaceted ecosystem with use cases spanning numerous industries. From tokenized real-world assets and utility-driven tokens that offer real benefits, to the infusion of AI in digital collectibles, the NFT space is reinventing itself beyond the initial hype. Key sectors like gaming, metaverse platforms, and brand marketing are integrating NFTs to unlock new forms of engagement and revenue.

Meanwhile, technological strides in cross-chain interoperability and sustainability are addressing early criticisms and making NFTs more accessible and eco-friendly. Crucially, the support of major companies and the gradual maturation of regulations suggest that NFTs are moving into a more stable phase of development, attracting broader participation from both creators and investors.

For tech enthusiasts, developers, and artists, these trends mean more opportunities to innovate with NFTs – whether it’s building the next big game that leverages NFT economies or creating AI-driven art that finds a market on-chain. For investors and collectors, the trends highlight where value might accrue in the coming years: projects that offer tangible utility, strong communities, and interoperability are better positioned for long-term success.

Frequently Asked Questions

  1. What are Real-World Asset (RWA) NFTs?

    RWA NFTs are tokens that represent ownership of physical assets like real estate, art, or luxury goods. They make high-value assets easier to trade and allow fractional ownership, opening investment opportunities to more people.

  2. How are NFTs becoming more useful in 2025?

    NFTs now offer real utility, acting as access passes, loyalty rewards, or governance tokens. Many are also dynamic, meaning they can evolve or update over time based on user interaction or data.

  3. Why are gaming NFTs so popular?

    Gaming accounts for the largest share of NFT use, as players can own, trade, and sell in-game items as tangible assets. These NFTs also power virtual worlds, where land, avatars, and items hold real value in metaverse economies.

  4. How is AI changing NFTs?

    AI is being used to create generative NFT art and even “intelligent NFTs” that include interactive AI agents. New standards are emerging to enable AI-powered NFTs to be owned, transferred, and used securely on-chain.

  5. Are NFTs becoming more eco-friendly?

    Yes, with the shift to energy-efficient blockchains and carbon-neutral marketplaces, “green NFTs” are on the rise. Many projects now prioritize low-energy minting or linking NFTs to environmental causes, such as carbon offsets.

Flexible payment processing solutions from Host Merchant Services for seamless business transactions.

Open Banking Payments: Account-to-Account Checkout Revolution

Open banking payments is ushering in a new era of “pay-by-bank” or account-to-account (A2A) payments that let shoppers pay merchants directly from their bank accounts. Instead of entering a credit card number, customers log in to their banking app or website during checkout and authorize a transfer. This direct bank-to-bank flow bypasses the card networks entirely, resulting in faster payment confirmation and a more secure transaction.

In many markets (mainly Europe and the UK), regulators have mandated open banking APIs, enabling fintechs and payment platforms to access customers’ bank accounts (with permission) to initiate payments. The result is a checkout revolution: more merchants and payment providers are offering native bank transfer options at checkout.

This article explores those developments – from Revolut’s new payment gateway feature to Mastercard’s partnership with Paytently – and explains why open-banking payments can save merchants money and headaches by slashing fees and virtually eliminating chargebacks.

What Is Open Banking and “Pay by Bank”?

Pay by Bank

Open banking refers to the practice of banks exposing secure APIs so authorized third-party providers can access customer accounts (with consent). Under rules such as Europe’s PSD2 or the UK’s Open Banking framework, consumers can grant apps or fintechs read-only access to account balances or initiate payments directly.

When applied to e-commerce, this creates account-to-account checkout, where a customer chooses “pay with bank account” and selects their bank. The merchant’s system or payment gateway then redirects the shopper to the bank’s authentication page (or opens the bank’s app), the customer logs in and approves the payment, and funds are pulled immediately from the account. The customer pushes money to the merchant instead of the merchant pulling payment via a card.

Because these A2A payments use the bank’s own login and strong customer authentication (biometrics, one-time codes, etc.), they tend to be more secure than a simple card swipe. And because no card is involved, there are no interchange or scheme fees (or chargeback disputes) tied to a credit network.

Open banking payments are already common in parts of Europe and Asia and are gradually gaining ground worldwide. Payment analysts note that two factors drive this trend. The first is lower costs, and the second is better user experience. Banks can offer instant or real-time payments instead of multi-day ACH, and tech-savvy shoppers appreciate the convenience of paying directly from their phone banking app.

The Rise of Account-to-Account Checkout

Online payment processing with Host Merchant Services for secure transactions.

E-commerce is starting to see real momentum in pay-by-bank options. In Europe, for example, fintech firms and banks have been racing to add direct bank payments. One prominent example is the FinTech firm Revolut, which in late 2025 announced a new “Pay by Bank” feature for its merchant gateway. With this feature, Revolut’s business customers (online retailers) can display a bank transfer button at checkout. When shoppers click it, they are redirected to authenticate via their own bank app and confirm the payment. Revolut reports that merchants receive funds instantly, improving cash flow and the customer experience.

And because the bank authorizes every transaction, the risk of fraud or unauthorized chargebacks is “drastically” reduced. This feature launched initially in the U.K. and a dozen European countries (including France, Germany, Italy, Spain, and others), showing a strong demand. Revolut observed that U.K. pay-by-bank volumes nearly doubled in just one year.

Major payment networks and platforms are also backing open-banking checkout. For instance, Mastercard recently partnered with payments provider Paytently to roll out an optimized bank-payment solution for e-commerce. This new offering – powered by Mastercard’s “Open Finance” APIs – lets online shoppers pay via bank while merchants benefit from Mastercard-grade tokenization and routing.

Mastercard’s system issues a secure token instead of transmitting raw bank credentials, and Paytently’s orchestration engine routes each payment over the fastest rail (ACH or instant pay) to confirm it instantly. The goal is to cut fraud and improve checkout conversion by using the shopper’s bank login, fully authenticating transactions, and ensuring the merchant can be sure funds are on the way. Mastercard and Paytently’s collaboration will bring open-bank payments to more merchants globally, giving customers a “trusted, seamless” way to pay without cards.

Other industry players are moving similarly. Payment processors like Stripe now support a “Pay by Bank” option in Europe, letting U.K., German or French customers select their bank and approve a transfer instead of entering card details. Stripe notes that after the user authenticates the payment in their banking app, the transfer is settled with no card network involved – meaning no chargeback process is needed (once authorized, the funds cannot be clawed back as easily as a card payment).

In the U.S., the infrastructure is evolving, too. In 2023, the Federal Reserve launched its FedNow real-time payment network, which paves the way for instant bank transfers nationwide. Retail giants are experimenting as well. Walmart announced plans (with tech partner Fiserv) to offer instant bank transfer checkout by 2025, linking customers’ bank accounts to their Walmart Pay wallets. All these moves indicate that A2A payments are moving beyond theory into real-world use.

Open Banking Benefits for Merchants

Open Banking Benefits for Merchants

The big reason retailers care about open-banking checkout is cost and risk reduction. Traditional credit card transactions carry fees of 1 to 3% (plus flat fees) for every sale, and additional expenses or losses when a cardholder disputes a charge. By contrast, bank-to-bank payments typically cost much less. In many cases, a merchant might pay a fixed small fee per transaction (for example, a few cents) instead of a percentage of the sale.

Businesses could save 40-80% on processing costs by switching to pay-by-bank, depending on volumes and pricing models. (That said, merchants do incur some fees to the payment provider and possibly to their bank for each transfer. Even so, the overall rate is usually far below typical card interchange.)

There are other direct merchant advantages as well:

  • Faster, guaranteed settlement:

Account-to-account transfers can settle much more quickly than credit cards. Many A2A solutions offer instant or same-day funding, whereas card transactions may take 1-3 business days to decide. Real-time settlement means the merchant’s bank account is credited immediately upon customer payment. This improves cash flow and reduces waiting time.

And because the bank authorizes the payment, the funds are essentially guaranteed, avoiding the slow authorization hold that can happen with cards.

  • Virtually zero chargebacks:

One of the biggest headaches with credit cards is chargebacks: a buyer can dispute a card charge and force the merchant to refund it, often losing the merchandise and paying a chargeback fee. By contrast, pay-by-bank payments require the customer to log in and actively approve the transfer. As a result, once the payment goes through, it cannot be disputed by a simple card reversal.

Most open-banking payment flows explicitly have no chargeback process—if a consumer wants a refund, it must be handled through the merchant (as with a cash or check payment), not via a network dispute. This means merchants face far fewer fraud claims or reversals.

  • Lower fraud risk and higher security:

A2A payments leverage the bank’s security infrastructure. Customers typically must pass two-factor authentication (biometrics, one-time code, etc.) in the banking app before a payment is authorized. This multi-layered security is much harder for a fraudster to bypass than a stolen credit card number. And because the merchant never sees the customer’s full bank credentials, sensitive data is better protected.

In fact, many solutions tokenize the payment information: the bank issues a one-time token for the transaction rather than sharing the raw account details. This tokenization means even if data were intercepted, it couldn’t be reused. Combined with SSL encryption and other safeguards, open-banking payments often boast stronger fraud controls. These design features make account-to-account transfers inherently safer, cutting down chargeback rates and bogus disputes.

  • Improved customer experience and conversion:

Today’s consumers, especially mobile and younger shoppers, appreciate speed and simplicity. Pay-by-bank can be extremely fast: shoppers pick their bank, authenticate with perhaps a fingerprint or passcode, and return to the merchant, all within a few taps. This eliminates the need to type card details, CVV codes, or billing addresses. Fewer form fields and steps mean lower abandonment.

Industry reports suggest that offering bank payments at checkout can boost conversion rates by several points, particularly for customers whose cards might otherwise be declined or who prefer bank payments. It also opens up shopping to people without cards; for example, a growing segment of consumers now primarily use banking apps and might welcome a checkout option that fits their habits.

  • Greater trust and loyalty:

Some shoppers feel more confident when paying through their own bank, which they trust, rather than third parties. By partnering with banks or trusted fintechs, merchants can tap into that brand trust.

Plus, because open-banking payments rely on the customer’s existing bank account, merchants often get useful confirmation data (for instance, verified account numbers or proof of funds). This transparency can strengthen the merchant-consumer relationship and may even help with post-sale services (like refunds or memberships tied to the bank account).

Real-World Industry Moves

The trend isn’t limited to one or two companies. A few more examples illustrate the momentum:

  • Stripe and payment gateways:

Stripe, one of the world’s largest online payment processors, launched Pay by Bank in Europe. Merchants using Stripe can enable this in their dashboard so UK, German, or French customers can select their bank at checkout.

Once customers authenticate in their bank’s app, the merchant receives an immediate confirmation, and the funds are routed without going through card networks. Many other gateways and platform providers (Braintree, Adyen, etc.) are either already offering or exploring similar bank payment integrations, especially in markets with strong open banking adoption.

  • Card networks innovating:

Mastercard and Visa aren’t sitting out. In addition to the Paytently project mentioned above, these card networks also have open banking initiatives. For example, Mastercard launched a service called Mastercard Open Banking (formerly Mastercard Open Banking API) to let merchants connect to banks for A2A payments or data.

Visa has an “Open Banking Program” to build partnerships with fintechs for A2A and direct banking flows. Such moves show the incumbents see A2A not as a threat, but as a complementary rail that they can integrate. They often highlight features such as tokenization (familiar from cards) to secure new payment flows.

  • Retailers and apps

Beyond pure fintechs, some retailers and apps are enabling A2A. We already mentioned Walmart’s plan in the U.S. In Europe, many banks allow customers to pay merchants directly through their online banking or mobile app if the merchant supports it. Bill-splitting and invoicing apps also incorporate bank payments. Even non-financial platforms (ride-hailing, utilities, subscriptions) are experimenting with allowing users to pay from linked bank accounts.

All these developments signal that pay-by-bank is rapidly becoming table stakes for merchants. Industry surveys show that nearly 60% of banks and over 90% of payment service providers are now offering, or plan to offer, pay-by-bank solutions. These providers cite strong merchant interest: in one report, over 90% of PSPs said retailers were asking about bank-transfer checkout.

  • Market Trends and Adoption

The pace of adoption varies by region. Europe (especially the UK) leads thanks to open banking regulations. In the UK, for instance, data shows that roughly one-third of adults are now using some form of open banking service (such as budgeting apps or bank-initiated payments), with over 2 billion such payments in a recent month. Pay-by-bank options have seen explosive growth there. UK monthly pay-by-bank transactions jumped from about 15 million to 27 million in just one year.

This trend is similarly visible across Europe: countries that adopted PSD2 in 2018 have seen startups and banks launch pay-by-bank. In Scandinavia and the Netherlands, for example, A2A apps have long been popular; recently, more merchants in those countries have allowed customers to pay with banking app QR codes or bank transfers.

In the U.S., adoption has been slower but is picking up. Surveys find that only about 10-15% of U.S. consumers have ever used an account-to-account payment at checkout. Many Americans don’t know the option exists. Security concerns also play a role—more than half of non-users cite trust issues. However, attitudes are shifting: about 4 out of 5 consumers who have tried it report a positive experience.

The launch of FedNow in 2023 and fintech offerings (such as Plaid and Finicity, enabling account transfers) are accelerating the infrastructure. For example, direct debit via ACH has long been possible, but new, user-friendly flows (instant transfers via FedNow or tokenized account linking) are making A2A more practical for e-commerce. We should expect U.S. merchants to start rolling out these options more broadly in the next few years as the rails and consumer awareness improve.

Worldwide, forecasts anticipate that hundreds of millions of users will be using open-banking payments by the end of the decade. One study predicts a fourfold increase in active open-banking users over the next five years.

Governments and regulators in Asia and Latin America are also pushing real-time A2A systems, which should spur the adoption of bank-based checkout globally. India’s Unified Payments Interface (UPI) also saw rapid growth, and some Latin American countries have instant-transfer systems, albeit usually for person-to-person or bill payments for now. As these systems mature, merchants in those regions will likely follow suit with “pay-by-bank” at online checkout.

Technical and Security Considerations For Open Banking

Technical and Security Considerations For Open Banking

From a developer or fintech perspective, implementing open-banking payments involves new APIs and standards. Merchants or their payment providers must integrate with one or more open-banking gateways or directly with participating banks. The typical flow is: at checkout, the merchant calls an API to get a list of banks (or redirects to a single bank); the customer logs in to their bank’s interface; the bank returns an authorization token to the merchant; the merchant’s backend then triggers the actual transfer. Many third-party platforms handle all this complexity.

Key technical points include strong customer authentication and tokenization. Open-banking rules generally require multi-factor authentication, so the merchant never touches the customer’s credentials or one-time passcodes – they stay with the bank. The merchant only receives a token confirming the payment. The bank or network cryptographically signs this token (and other data), making it unforgeable.

Tokenization is also often used so that the account details themselves (like the account number) are never exposed outside the secure flow. From the merchant’s point of view, this means they don’t need to store sensitive card or bank data, reducing their compliance burden (for example, PCI scope).

On the user side, the process is usually made as seamless as possible: if on mobile, an app-to-app handoff occurs (the merchant’s app or browser opens the bank’s app); on desktop, a browser pop-up or redirect to a bank login page appears. Once the payment is confirmed, the merchant receives an immediate callback or webhook indicating success. Error handling is simpler than with cards: if the bank denies the payment (insufficient funds, incorrect credentials, etc.), the merchant is notified of a failed payment, and there is no lengthy chargeback dispute process.

The technology stacks behind open-banking payments are designed to reduce friction while maximizing trust. Banks invest heavily in secure APIs and fraud monitoring. Merchants work with PSPs that route payments to the “best rail” (e.g., fast rails if available, or regular ACH if not).

The result is an end-to-end system where the customer’s bank explicitly authorizes every transfer, and every step is logged and visible to both parties. For developers, this means using newer protocols (such as OpenID Connect and FAPI) and working with certified providers. But the payoff is a smooth, modern checkout flow that matches the security of banking apps.

Challenges and Considerations

Despite the benefits, open-banking payments are not a drop-in replacement for all card transactions—at least not yet. Some challenges include:

  • Consumer awareness and trust: Many shoppers still default to cards or digital wallets. Education is needed as payment flows must clearly explain how the process works and ensure customers feel safe entering their bank credentials (which are handled by the bank’s own interface, not the merchant). Until a wider audience learns about pay-by-bank, uptake may lag.
  • Bank coverage and fragmentation: Especially in the U.S. or other regions without strict open-banking mandates, not all banks support the needed APIs or real-time rails. Merchant platforms may need to support multiple bank connection services (some banks have their own portals, while others use aggregators). This can complicate technical integration. However, large banks and many small banks are beginning to connect to networks like FedNow or to fintech intermediaries, so this is improving.
  • Fee structures and contracts: While interchange fees go away, merchants should note that new fees or contracts may appear. For example, a pay-by-bank gateway might charge a per-transaction fee or a monthly service fee. In some markets, banks may start charging third parties for access to their APIs. Merchants should review pricing models – in many cases, the total cost is still lower than credit, but it’s not zero.
  • Global standardization: There is no single international standard for open banking payments. Each country or region has its own technical standards and legal framework. For a multinational merchant, this means enabling separate flows for each country. For example, an A2A checkout option in Europe won’t automatically work for a U.S. customer. This fragmentation can slow adoption globally, though large platforms increasingly offer region-specific versions of pay-by-bank.
  • Impact on rewards and customer habits: Some customers love credit card points or rewards and may hesitate to switch away from them. To encourage use, merchants and banks might consider incentives (e.g., discounts for using pay-by-bank). Over time, however, the convenience and security of bank-based checkout could outweigh rewards, especially if card benefits stay focused on credit purchases.

Most experts agree that these are surmountable. Many see parallels with how digital wallets took time to gain traction. As infrastructure (such as real-time rails and identity protocols) matures and more merchants begin offering pay-by-bank, it is likely to become a mainstream checkout option. Merchants should plan for the transition now, testing integrations in key markets and tracking adoption rates.

Conclusion

The migration from plastic cards to bank-based payments is well underway. Open banking has provided merchants with the foundation to accept account-to-account payments seamlessly and securely. The early results are precise: merchants who offer pay-by-bank at checkout are enjoying lower processing costs, faster cash flow, and far fewer fraud disputes. Even better, customers often appreciate the simplicity and trust of paying directly from their bank.

The industry is moving quickly. Platforms are building this capability into their core offerings, and surveys indicate broad demand from retailers for A2A checkout options. For e-commerce businesses, embracing open-banking payments could mean staying ahead of the curve. They stand to boost profit margins and improve the checkout experience simultaneously.

Frequently Asked Questions

  1. What is “Pay by Bank” and how does it work?

    It’s an account-to-account (A2A) checkout where shoppers choose their bank, authenticate in their banking app/website, and approve a transfer. Funds move directly from the customer’s account to the merchant, no card networks involved.

  2. Why is it cheaper than cards?

    There’s no interchange or scheme fee because cards are bypassed. Merchants typically pay a low, fixed, or reduced fee to the A2A provider, often cutting processing costs dramatically compared to the usual 1 to 3% on cards.

  3. What about chargebacks and fraud?

    Payments are strongly authenticated by the bank (biometrics/OTP), reducing fraud risk. Since the customer authorizes a bank transfer, classic card chargebacks don’t apply; refunds are handled directly with the merchant.

  4. How fast do I get paid?

    A2A can settle instantly or same-day, depending on the rail (e.g., instant payments vs ACH). That means quicker cash flow and fewer authorization holds compared to traditional card settlement timelines.

  5. Where is it available and who supports it?

    Adoption is strongest in the UK/EU under open-banking rules, with growing global momentum. PSPs and networks (e.g., Revolut’s gateway features, Stripe’s pay-by-bank in Europe, and network-led open-finance initiatives) are rolling it out, with real-time rails expanding in markets like the U.S.

Secure payment processing with Host Merchant Services.

AI-Powered Treasury and Payments: Smarter Cash Flow & Fraud Control

In today’s financial landscape, artificial intelligence is revolutionizing both treasury management and payment processing. Businesses are deploying AI and machine learning tools to automate routine tasks, forecast cash needs, manage liquidity in real time, and strengthen fraud defenses. Leading solutions illustrate this trend.

Fidelity National Information Services (FIS) recently unveiled Neural Treasury, an AI/ML-powered platform for corporate treasuries that promises proactive cash forecasting, automated operations, and continuous fraud monitoring. Likewise, card networks like Mastercard have introduced advanced decisioning engines – Mastercard’s new On-Demand Decisioning (ODD) allows issuers to embed custom, AI-influenced approval rules directly into the payment network, yielding faster and more personalized authorization outcomes.

This article explores how these AI-driven innovations optimize cash flow and fraud control, and what they mean for companies and finance teams.

AI-Driven Corporate Treasury Management

AI-driven payment processing technology at Host Merchant Services.

Corporate treasury teams traditionally juggle massive amounts of data and routine processes. They must monitor global bank balances, reconcile transactions, forecast inflows and outflows, and execute payments — all while managing foreign exchange, interest rates, and counterparty risks. Legacy systems and spreadsheets often leave treasurers reacting to events rather than planning.

AI remedies these challenges by linking disparate data sources and applying intelligent analytics. Modern platforms ingest ERP, accounting, payment, and market data to generate actionable insights, automate operations, and detect anomalies. The result is a treasury that moves from a retrospective observer to a strategic driver of cash optimization.

One prominent example is FIS’s Neural Treasury suite. Neural Treasury combines cloud software, machine learning, and even robotic process automation (RPA) to support the complete treasury workflow. It includes a specialized large language model (branded as Treasury GPT) trained on treasury data and best practices. Using these capabilities, Neural Treasury helps treasurers:

  • Analyze and Forecast Cash Flows: The system examines historical patterns and real-time data to predict future inflows and outflows. By spotting seasonal trends or payment cycle shifts, it produces more accurate forecasts than manual methods. Better forecasts let companies plan investments or debt paydowns and reduce excess cash held on the sidelines.
  • Optimize Liquidity Management: With a view of all accounts and currencies, the AI engine suggests when to concentrate funds or draw on credit lines. Automated routines can move idle cash to its most productive use (e.g., sweeping it into an interest-bearing pool or settling due payables). This proactive liquidity management prevents surprises during market swings.
  • Monitor for Fraud and Risk: The platform continuously learns transaction patterns across the company. Unusual payments or account changes trigger immediate alerts. For example, if an invoice payment is suddenly directed to a new bank account in a high-risk location, AI flags it for review. Over time, the fraud-detector “learns” from confirmed incidents and tightens its criteria, adapting to emerging scams.
  • Automate Reconciliation and Reporting: RPA bots and intelligent rules automate repetitive tasks, such as matching invoices to bank statements and summarizing treasury balances. Mundane chores once done in Excel – checking payment exceptions, updating cash position reports – are handled by software. This frees treasury staff to focus on analysis and strategy instead of data entry.
  • Enhance Visibility and Control: The system provides executives with real-time dashboards of payable and receivable activity. Treasury and finance leaders gain one view of cash exposure across business units and geographies. This holistic transparency supports informed decision-making during volatile conditions.

Other vendors are racing to offer similar treasury AI solutions. Banks and fintechs now sell specialized cash-forecasting tools that apply machine learning to historical transaction data.

These tools often supplement a company’s ERP or treasury management system, adding pattern recognition and statistical modeling capabilities. The industry consensus is clear: AI-driven forecasting and automation are becoming foundational features of modern treasury management.

Real-Time Forecasting and Liquidity Optimization

Real-Time Forecasting

At the core of AI-enabled treasury is better cash forecasting. Traditional forecasts – based on static models or simple trendlines – can fall short in a fast-changing economy. AI approaches improve on this by integrating internal data with external signals. An intelligent system might combine a company’s payment history with market indicators such as interest rates, foreign exchange volatility, and even commodity prices.

During an unexpected supply-chain disruption, the AI model can quickly re-run scenarios: Should upcoming payments be delayed? Is it better to hedge currency risk now? By simulating these scenarios in minutes, treasury leaders can act immediately.

These predictive capabilities translate to concrete benefits. Treasurers report that machine learning forecasts are not only faster but also more accurate, enabling companies to reduce idle cash buffers safely. Indeed, some firms find they can operate with significantly leaner cash reserves because they trust the AI’s precision. Instead of holding large safety cushions, they rely on dynamic forecasts to know precisely when cash will be needed or freed up. This boosts return on capital – companies put excess cash to work in investments rather than leaving it dormant in bank accounts.

In practice, many companies start small by applying AI to specific forecasting tasks. For instance, one common approach is to use AI for short-term prediction: analyzing the cash effects of incoming customer payments, payroll runs, or known debt obligations over the next few weeks. Others use it to forecast on a quarterly horizon, aggregating forecasted receivables, payables, and market factors. Each use of AI typically means retraining models regularly on new data, so forecasts adapt when business patterns shift (like after a price increase or the launch of a new product).

Besides forecasting, AI aids day-to-day liquidity decisions. For example, when initiating a payment, an AI assistant can recommend the best channel or currency. Suppose a supplier needs funds immediately, and the company has multiple payment options. In that case, the AI might suggest using an instant-pay network (like RTP or FedNow) instead of traditional ACH to ensure the recipient receives the funds on time. If payment is not urgent, the AI could recommend a lower-cost ACH or even splitting the payment to comply with thresholds and minimize fees. By automatically optimizing these choices, businesses save on transaction costs and avoid late-payment penalties.

Robotic Process Automation for Efficiency

Robotic Process Automation

Beyond forecasting, automation is another frontier where AI is making treasury smarter. Robotic Process Automation (RPA) combined with simple AI capabilities is already replacing many manual back-office tasks. Any repetitive, data-intensive task is a candidate: extracting invoice details from PDFs, matching payments to ledger entries, validating transaction metadata, or consolidating bank statements. AI-powered bots can do these faster and with fewer mistakes.

For instance, instead of a treasurer manually downloading bank statements each morning, an automated system can pull all account statements into one interface. Then an AI engine automatically aligns each line item with company records. Exceptions (unmatched items) are flagged, while the rest reconcile instantly. This not only speeds up month-end closing but also reduces human error from copying numbers or reconciling thousands of transactions by eye.

Another simple example is reducing reliance on legacy spreadsheet macros. Companies often have Excel templates with macros to import data and generate reports. New RPA tools can replace these with standardized data pipelines. Once the data connection is set, AI/automation handles the ingestion and formatting. The finance team can then focus on interpreting the results rather than tinkering with data plumbing.

AI in Payments and Authorization Decisioning

AI in Payments

While treasury teams are optimizing cash and operations, banks and payment networks are also applying AI to the flow of payments themselves. A key area is real-time transaction decisioning. Traditionally, when a customer swipes a card or initiates an online payment, the authorization request is subject to a series of checks. These checks used to rely on static rules (like “block purchases over $10,000”). Now, AI and machine learning are increasingly embedded into this process to make smarter, context-aware decisions instantly.

A prime example is Mastercard’s On-Demand Decisioning (ODD), launched in 2025. ODD lets card issuers insert their own logic – potentially AI-enhanced – into the authorization flow on Mastercard’s network. In practice, this means the bank that issued your card can define more nuanced rules, and Mastercard’s system applies them as the transaction is processed.

An issuer might prioritize approvals for its premium customers: if a high-value client attempts to pay the monthly mortgage, the issuer’s custom rule could ensure approval is granted immediately. If the card had been reissued recently (a common cause of declines), the issuer could also set a rule to reauthorize the transaction automatically rather than decline it.

Because On-Demand Decisioning runs within Mastercard’s own network, issuers gain instant control without having to re-route transactions through separate systems. In effect, it streamlines the authorization process by handling a greater portion of the decision at the network level. Early feedback indicates that banks using ODD see smoother service for essential customers and fewer unnecessary declines, all without extra operational overhead.

Mastercard’s move reflects a broader trend: card schemes and processors are tapping AI to balance security, user experience, and profitability. Visa offers analogous services (like Visa Advanced Authorization) that crunch hundreds of transaction attributes per purchase. These AI-driven engines might consider the cardholder’s past behavior, merchant risk profiles, device information, and more — all in milliseconds.

The goal is always the same: approve more legitimate transactions (boosting revenue and customer satisfaction) while cutting out fraud before it happens. In some cases, the networks’ risk models can prevent tens of billions of dollars in fraud each year by learning from global data patterns.

Beyond cards, instant payment networks (like real-time ACH or peer-to-peer rails) are also integrating AI. Any time a transaction moves between accounts, AI can analyze it on the fly. For instance, if a corporate customer initiates an instant wire transfer out of business hours to a new beneficiary, the system can trigger a risk check based on company history and global intelligence feeds. This “instant analytics” approach means fraud can be spotted even as payments clear within seconds.

AI-Powered Fraud Detection and Security

A recurring theme is that AI both drives efficiency and serves as a powerful fraud-prevention tool. Fraudsters are using increasingly sophisticated methods (even their own AI) to breach companies’ defenses. AI counter-measures are emerging everywhere in response.

In the payments realm, machine learning models continuously monitor transaction flows. They detect anomalies that would escape simple rules. A sudden change in the location of card purchases or the frequency of card purchases can trigger an alert. These models improve over time as they learn standard patterns for each customer or vendor. As a result, merchants and consumers face fewer false declines, but actual fraud attempts are halted more quickly.

Within corporate finance, AI also mitigates internal and B2B fraud. One primary target is business email compromise (BEC), in which attackers impersonate company executives or suppliers to trick payment staff into wiring funds to bogus accounts. Advanced systems now cross-check vendor details whenever an account change is requested. If an email or instruction looks suspicious (e.g., it comes from a slightly off-domain name or the bank account is offshore), the AI flags it. It might even simulate verification steps—for instance, automatically calling the original vendor’s known contact number—to confirm any change in payment instructions.

The impact can be huge. The U.S. Department of the Treasury and Federal agencies report that AI and machine learning have recently helped prevent and recover billions of dollars in fraudulent government payments. Although corporate treasuries are smaller than federal budgets, the lesson is the same: AI’s ability to process vast data quickly can drastically reduce losses. Companies implementing these tools often discover that the first or second week after deployment, they catch attempts they would have missed before.

Key fraud prevention techniques powered by AI include:

  • Anomaly Detection: Scanning all outgoing payments against learned patterns. Unusual recipient accounts, irregular payment timings or amounts, and rare combinations of transaction attributes get flagged instantly.
  • Network Analysis: Mapping relationships (for example, linking multiple vendor names to a single bank account). AI can reveal a fraudster controlling a web of seemingly unrelated entities.
  • Behavioral Biometrics: In card payments, analyzing typing patterns, device sensors, or location to verify the cardholder’s identity in real time. These subtle signals help distinguish a real user from a thief.
  • Adaptive Learning: Every confirmed fraud attempt retrains the model. If attackers invent a new scheme (say, a fake invoice format), the AI learns it quickly and looks for similar signs in the future.
  • Continuous Authentication: Beyond one-time checks, systems can continuously evaluate risk even after a payment is approved, raising alerts if subsequent actions (such as chargebacks or refunds) appear irregular.

All told, AI brings a proactive stance to fraud control. Instead of waiting for human investigation after a suspicious transaction, these tools work in parallel with operations teams, typically preventing fraud before any damage is done.

Business Impacts and Implementation Strategies

For businesses, the combined effect of AI in treasury and payments is profound. Organizations gain greater visibility and control over cash. They can optimize working capital by pinpointing exactly when and where money will be needed. Faster, AI-driven decisions also mean improved customer and partner experiences: suppliers get paid reliably, and customers enjoy smoother payment processing.

Meanwhile, the company’s risk exposure shrinks as fraud losses drop. In one industry report, banks and treasurers noted that AI-enabled risk tools significantly reduced false declines, preserving revenue that would have been lost under stricter manual rules.

These advantages translate into financial results. More accurate cash forecasts might allow a company to reduce lines of credit or negotiate better terms with lenders: automated processes and fewer fraud incidents lower operating expenses and insurance premiums. Perhaps most importantly, treasury staff can focus on strategic planning — analyzing capital structure, financing opportunities, and market risks — instead of mundane chores. This empowers the finance function to become a true business partner, rather than just a back-office function.

However, successful adoption requires planning. AI tools are only as good as the data they use. Businesses must invest in data integration and quality. This often means establishing real-time links between the ERP system, bank accounts, and market data feeds. It also means cleaning historical records so the AI models aren’t learning from flawed information. Companies may need to upgrade their treasury management systems (TMSs) or banking interfaces to leverage AI capabilities fully.

Change management is also crucial. Treasury teams should start with clear use cases: perhaps piloting AI-powered cash forecasting on one segment of the business, or deploying an AI fraud monitor for high-value transactions. Early quick wins build confidence. Leadership should ensure treasury and IT collaborate; many successful implementations assign “AI champions” to guide end users and refine models based on feedback. Staff training is essential too: as systems take over routine tasks, treasurers need to develop skills in data analysis and interpreting AI-driven insights.

Governance cannot be overlooked. Companies should set up oversight for these new systems, just as they would for any critical financial process. This means monitoring AI decisions, regularly testing models, and documenting how automated rules are set. It may involve risk teams reviewing AI models for biases (for example, ensuring credit decisions remain compliant with policy). Regulatory requirements are evolving to cover AI in finance, so organizations should stay abreast of guidelines from bodies such as banking regulators and international standards bodies (for example, the EU’s Digital Operational Resilience Act).

A practical way to move forward is often through partnership. Many businesses begin by working with their bank or a fintech vendor. For instance, banks now offer AI-enhanced treasury services (like cash forecasting tools on their platforms), so a corporate treasurer can experiment without building everything in-house. Similarly, card issuers using network tools such as Mastercard’s ODD or Visa’s risk services can tap into AI capabilities as part of their card programs, leveraging the expertise of those networks.

Conclusion

AI-powered treasury and payments systems are enabling more innovative cash management and stronger fraud control. Companies that adopt these technologies find their treasury departments acting more like nerve centers, guiding strategic financial moves. Automated forecasts help in planning investments; continuous monitoring keeps an eye on unauthorized activity; and customizable decision engines keep payments flowing smoothly.

While implementation takes effort — upgrading data infrastructure and guiding teams through change — the payoff is significant. Businesses that embrace AI in finance are better equipped to navigate uncertainty, respond quickly to opportunities or threats, and protect their bottom line.

The era of AI-enhanced finance is here. As machine learning and intelligent automation become standard tools, treasurers and finance leaders have the opportunity to transform their roles. By leveraging these innovations, companies can achieve quicker, data-driven decisions that optimize cash flow, minimize risk, and ultimately provide a competitive edge in a fast-paced economy.

Frequently Asked Questions

  1. What is AI-powered treasury management?

    AI-powered treasury management uses machine learning and automation to forecast cash flows, optimize liquidity, and detect fraud in real time. It replaces manual spreadsheets with intelligent, data-driven tools that improve decision-making and efficiency.

  2. How does AI improve cash forecasting?

    AI analyzes historical data, market signals, and real-time transactions to predict future cash needs than traditional methods more accurately. This helps companies reduce idle cash and plan investments or debt repayment proactively.

  3. Can AI help prevent payment fraud?

    Yes. AI models continuously monitor transactions, flag suspicious behavior, and adapt as fraud patterns evolve. Tools like FIS Neural Treasury and Mastercard’s decision engines catch anomalies before money leaves the account.

  4. What is Mastercard’s On-Demand Decisioning (ODD)?

    ODD allows card issuers to apply real-time, AI-based rules directly within the Mastercard network. It enables faster, more personalized approvals while reducing false declines and fraud.

  5. What benefits do businesses get from adopting AI in treasury and payments?

    Companies gain more accurate forecasts, lower operating costs, faster payments, reduced fraud losses, and better visibility of global cash. Treasury teams can shift from manual work to strategic financial planning.